
 Anti-Fungal Treatment Market | 2026-2036
Anti-Fungal Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fungal Treatment Market Outlook
Echinocandin-class compounds are consolidating market share among hospitalized patients with invasive candidiasis, displacing older azole therapies in high-acuity settings. Pfizer Inc. leverages its hospital distribution network to sustain formulary access across major health systems. Merck & Co., Inc. anchors its position through R&D investment in novel mechanism antifungals. Gilead Sciences, Inc. differentiates via its infectious disease franchise and clinical trial infrastructure.
Anti-fungal treatment encompasses pharmaceutical interventions targeting fungal cell wall synthesis, membrane integrity, or nucleic acid metabolism, with systemic agents typically administered intravenously for ICUs and immunocompromised hosts. These therapies serve to reduce mortality from invasive aspergillosis and cryptococcal meningitis in transplant and HIV populations. Oral antifungals occupy the largest volume share due to outpatient dermatophyte and candidiasis management, while injectable delivery modes capture the highest per-dose margins in hospital settings. Topical agents compete on price in retail pharmacy channels with limited clinical differentiation.
FDA breakthrough therapy designations and EMA accelerated assessment pathways shape development priorities for sponsors targeting resistant Candida auris strains. The WHO fungal priority pathogens list directs public funding and antimicrobial stewardship mandates across health systems. Stakeholders must monitor evolving resistance surveillance data and regulatory exclusivity frameworks to prioritize pipeline investments and geographic market entry sequencing.
Market Dynamics
Resistance surveillance networks and stewardship mandates are compressing prescribing autonomy for legacy azole therapies while accelerating formulary placement for novel mechanism agents in tertiary care centers.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Expedited review timelines for echinocandin derivatives targeting Candida auris are shortening commercialization cycles for hospital-focused sponsors.
- Oncology unit expansion:Transplant and hematology wards in the United States are expanding systemic antifungal procurement for neutropenic patients with invasive mold infections.
- WHO Fungal Priority Pathogens List:Public funding allocations and antimicrobial resistance surveillance mandates are directing hospital pharmacy budgets toward resistant strain coverage.
Market Restraints
- Polyene API concentration:Bulk manufacturing of amphotericin B active pharmaceutical ingredients concentrates in limited fermentation facilities, creating supply vulnerability.
- Echinocandin synthesis complexity:Semi-synthetic lipopeptide production requires specialized biocatalysis capabilities that constrain manufacturing scale-up.
- Azole cross-resistance:Widespread agricultural triazole use has generated clinical resistance reservoirs that compromise fluconazole efficacy in candidemia.
Strategic Opportunities
- Outpatient infusion centers:Shifting administration of long-course systemic therapy from inpatient wards to ambulatory settings creates channel expansion potential.
- Combination therapy protocols:Pairing novel glucan synthase inhibitors with existing azoles offers differentiation in salvage therapy positioning.
- Companion diagnostics:Fungal biomarker testing integration with therapeutic selection is opening precision medicine positioning in transplant units.
Industry Challenges
- Specialized mycology expertise:Clinical microbiology fellowship programs produce insufficient diagnostic capacity for early invasive fungal infection identification.
- Stewardship compliance costs:Mandatory antifungal utilization review programs require dedicated pharmacy resources that strain smaller hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fungal Treatment Market |
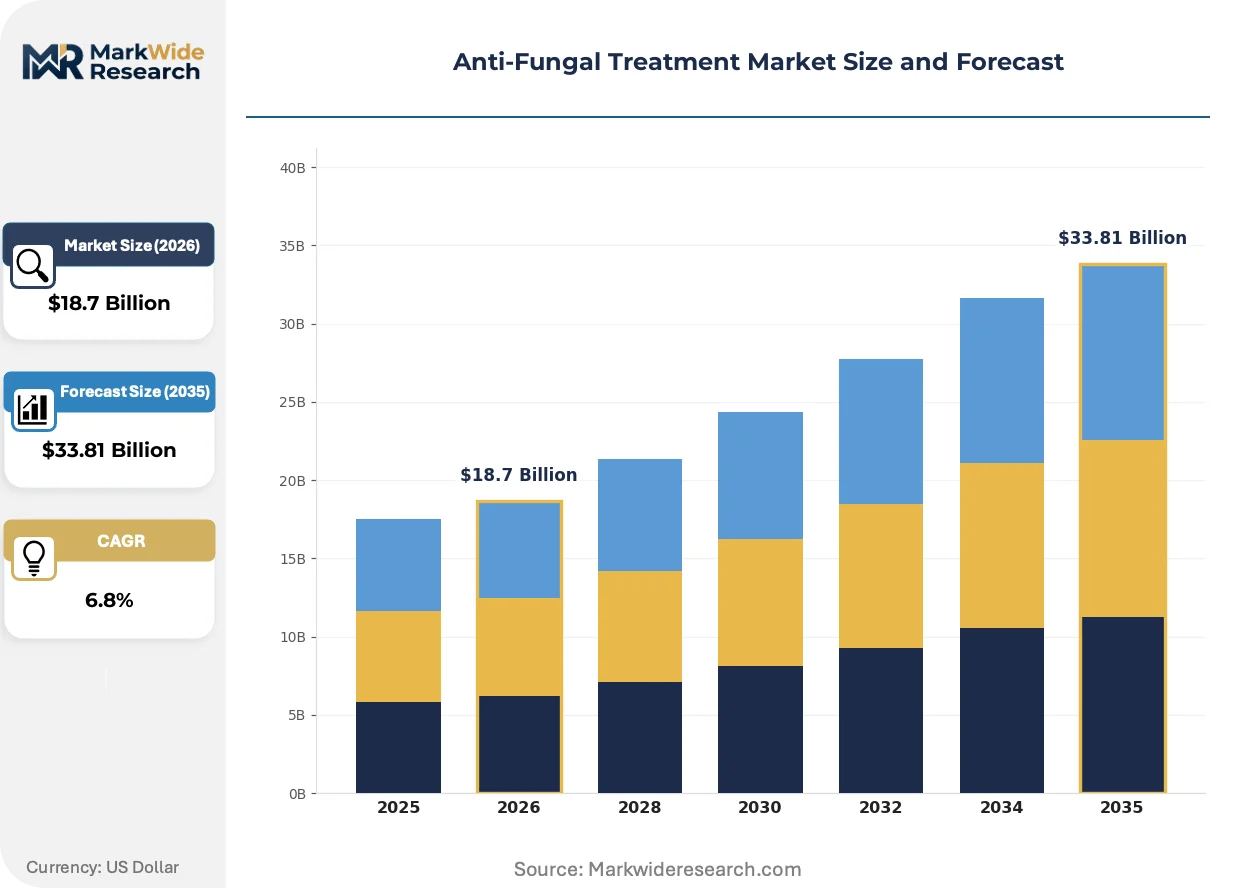
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Agents, Antifungal Creams, Oral Antifungals Delivery Mode: Injectable, Oral, Topical, Intranasal End User: Hospitals, Clinics, Home Care, Pharmacies Indication: Dermatophyte Infections, Candidiasis, Aspergillosis, Cryptococcosis |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Astellas Pharma Inc., Novartis AG, GlaxoSmithKline plc, Bayer AG, Sanofi, Johnson & Johnson, Gilead Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fungal Treatment Market Strategic Shifts
Novel delivery technologies and diagnostic integration are reshaping therapeutic positioning, with formulation science and biomarker-guided therapy emerging as primary vectors of competitive differentiation.
Liposomal encapsulation technology is absorbing the limitations of conventional amphotericin B nephrotoxicity, enabling extended dosing in renal-impaired ICU populations. Tertiary care centers in the United States are adopting these formulations as first-line empiric therapy for suspected invasive aspergillosis. The structural consequence is margin compression for generic conventional polyenes as payers mandate liposomal substitution in high-acuity settings.
EMA accelerated assessment pathways for antifungal agents addressing unmet medical needs are compressing regulatory timelines for sponsors with resistant Candida data packages. This framework rewards sponsors investing in geographically diverse clinical trial networks spanning multiple mycology reference centers. European hospital formularies are responding with faster access agreements for agents receiving conditional marketing authorization.
Hospital pharmacy committees are consolidating antifungal procurement through system-wide contracts that bundle systemic agents with diagnostic testing services. This behavioral shift concentrates purchasing power within integrated delivery networks and marginalizes standalone community hospital negotiations. The pattern is most pronounced in United States metropolitan markets where health system consolidation has advanced furthest.
Anti-Fungal Treatment Market Segmentation
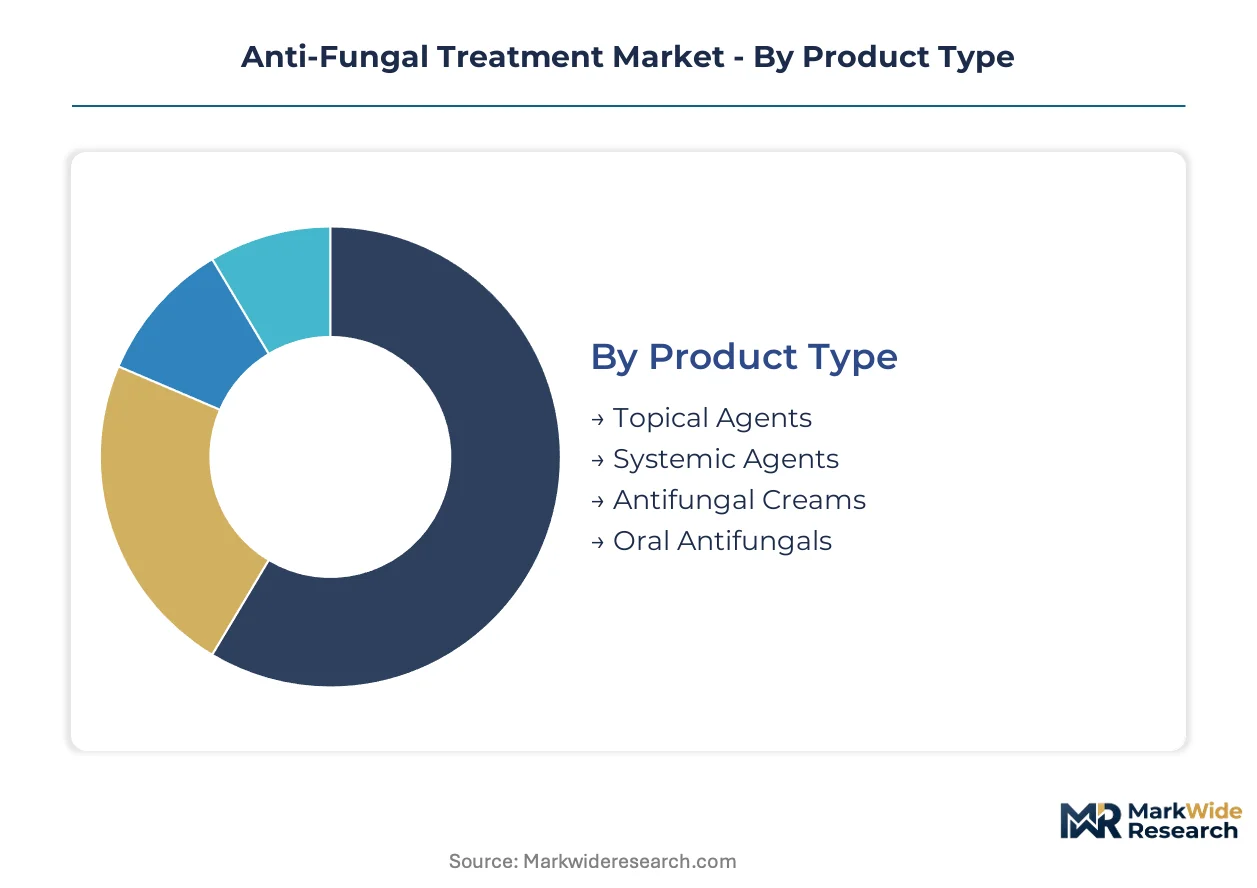
Anti-fungal treatment segmentation reflects divergent clinical economics across acute care and ambulatory settings. Procurement patterns vary sharply by delivery mode and end-user infrastructure, with hospital formularies prioritizing mortality reduction while retail channels compete on price accessibility.
Product Type:
Hospital procurement teams distinguish products by route of administration and therapeutic index, with systemic agents commanding premium formulary placement against topical alternatives.
- Systemic Agents:Intravenous echinocandins and polyenes penetrate deep tissue and CNS compartments for invasive mold infections. Demand concentrates in United States transplant centers where Candida auris outbreaks drive empirical coverage protocols.
- Oral Antifungals:Triazole tablets and flucytosine capsules enable outpatient step-down therapy after inpatient stabilization. Prescription volume tilts toward dermatology clinics managing recurrent vulvovaginal candidiasis and onychomycosis.
- Topical Agents:Allylamine and azole creams compete on retail shelf placement for tinea pedis and cutaneous candidiasis.
- Antifungal Creams:Emulsion-based formulations with clotrimazole or miconazole dominate over-the-counter pharmacy segments.
Volume sits with oral antifungals; growth tilts toward systemic agents.
Delivery Mode:
Margin structure separates hospital-administered injectables from self-administered oral and topical alternatives, with reimbursement coding driving channel selection.
- Injectable:Liposomal amphotericin B and micafungin sodium require infusion center infrastructure and therapeutic drug monitoring. United States oncology wards anchor demand for prolonged neutropenic coverage.
- Oral:Bioavailable triazoles and griseofulvin tablets support community-acquired infection management without hospital admission.
- Topical:Creams, solutions, and powders target superficial dermatophyte colonization with minimal systemic exposure.
- Intranasal:Amphotericin B suspensions deliver prophylactic coverage against sinonasal aspergillosis in high-risk hematology patients.
Injectable delivery captures highest per-dose margins; oral administration scales across outpatient volume.
End User:
Capital intensity and diagnostic capability determine which settings can manage invasive fungal disease versus superficial infections.
- Hospitals:Tertiary care centers with dedicated mycology laboratories handle disseminated candidiasis and breakthrough mold infections. Stewardship mandates from the Joint Commission shape empirical prescribing protocols.
- Clinics:Dermatology and infectious disease outpatient practices manage uncomplicated tinea and candidiasis with oral or topical regimens.
- Home Care:Infusion nursing services administer prolonged echinocandin courses for patients discharged from inpatient wards.
- Pharmacies:Retail and specialty pharmacy channels distribute oral agents and compounded topical preparations.
Hospitals anchor systemic therapy procurement; home care represents the steepest expansion trajectory as infusion services decentralize.
Indication:
Mortality risk and treatment duration separate opportunistic invasive infections from benign superficial colonization.
- Aspergillosis:Invasive pulmonary and disseminated disease in neutropenic hosts requires multimonth voriconazole or isavuconazole therapy. United States stem cell transplant programs drive prophylactic and empirical prescribing.
- Candidiasis:Spectrum spans mucocutaneous thrush to candidemia with end-organ seeding. Bloodstream infections concentrate in ICU settings with central line access.
- Dermatophyte Infections:Tinea corporis, cruris, and pedis respond to topical allylamines or oral terbinafine for nail involvement.
- Cryptococcosis:CNS meningitis in advanced HIV and solid organ transplant recipients requires induction with amphotericin B plus flucytosine.
Candidiasis generates highest case volume; aspergillosis commands premium therapeutic investment per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of systemic antifungals concentrates in the United States, where resistant Candida auris outbreaks and expanded oncology wards drive formulary investment. The FDA's breakthrough therapy pathways accelerate commercialization timelines for sponsors targeting immunocompromised populations. Secondary demand clusters in Western Europe and select Asia-Pacific markets with established transplant infrastructure.
United States
Tertiary care centers in Houston, Boston, and Seattle anchor systemic antifungal consumption through stem cell transplant and ICU expansion. The FDA's streamlined approval pathways for breakthrough antifungal agents shorten regulatory timelines for novel echinocandin derivatives. Philadelphia's hospital network consolidation creates system-wide procurement contracts that bundle systemic agents with diagnostic testing services.
Germany
EMA accelerated assessment pathways reward sponsors with resistant Candida data packages from geographically diverse trial networks. The country's antimicrobial stewardship mandates from the Paul-Ehrlich-Gesellschaft direct hospital pharmacy budgets toward novel mechanism agents. Berlin and Munich university hospitals serve as mycology reference centers coordinating multicenter clinical trials.
Japan
PMDA priority review vouchers for antifungal agents addressing unmet medical needs compress regulatory timelines for resistant strain coverage. The country's aging transplant population and hematology ward expansion drive empirical prescribing protocols. Osaka and Nagoya medical centers concentrate diagnostic capacity for early invasive fungal infection identification.
United Kingdom
NHS England's specialized commissioning frameworks concentrate antifungal procurement within designated tertiary centers for complex infections. The country's fungal priority pathogen surveillance networks direct public funding toward resistant strain coverage. London's hospital consolidation creates integrated delivery networks with consolidated purchasing power over standalone community facilities.
India
CDSCO accelerated approval pathways for critical antifungal therapies address candidemia and cryptococcal meningitis in HIV populations. The country's expanding oncology infrastructure and transplant program growth drive demand for systemic azole and polyene therapies. Mumbai and Hyderabad hospital clusters serve as regional hubs for mycology diagnostics and therapeutic drug monitoring.
Anti-Fungal Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hospital-focused innovators capturing premium formulary placement against generic azole suppliers. The market structure tilts toward consolidated procurement power within integrated delivery networks, compressing margins for standalone community hospital negotiations. Three archetypes dominate: multinational pharmaceutical conglomerates with infectious disease franchises, mid-cap biotechs with novel mechanism pipelines, and generic manufacturers competing on polyene API fermentation scale. Competitive moves concentrate on M&A for diagnostic-therapeutic bundling and capacity expansion for liposomal encapsulation manufacturing.
Within the multinational tier, Pfizer Inc., Merck & Co., Inc., and Gilead Sciences, Inc. occupy positions shaped by hospital distribution infrastructure and clinical trial investment. Pfizer exemplifies the hospital network archetype through formulary access across major health systems. Merck represents R&D-intensive positioning in novel mechanism antifungals. Gilead anchors the infectious disease franchise model with dedicated clinical trial infrastructure. These three entities collectively illustrate how commercial scale and therapeutic specialization determine competitive positioning in systemic antifungal procurement.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Astellas Pharma Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Bayer AG |
| Sanofi |
| Johnson & Johnson |
| Gilead Sciences, Inc. |
| Others |
Value Chain & Pricing Dynamics
Liposomal encapsulation technology adoption is simultaneously elevating manufacturing complexity and concentrating production among specialized fermentation facilities with the biocatalysis capabilities required for echinocandin-class synthesis. This production-method transition reshapes cost economics by embedding premium formulation science into hospital procurement contracts while constraining supply scale-up.
Pricing Analysis
Volume sits with oral azole tablets for outpatient dermatophyte management, while margins concentrate in liposomal amphotericin B and micafungin sodium vials for ICU settings. Price differentiation separates branded liposomal formulations from generic conventional polyenes based on nephrotoxicity profiles and therapeutic index. Cost compression in conventional polyenes is intensifying because payers mandate liposomal substitution in high-acuity settings. Retail pharmacy channels exhibit highest price sensitivity; tertiary care transplant centers demonstrate lowest sensitivity due to mortality-driven formulary decisions.
Supply Chain Analysis
Cold-chain logistics and specialized freight requirements for temperature-sensitive liposomal formulations elevate distribution costs from bulk fermentation sites to hospital pharmacies. Bulk amphotericin B API production concentrates in India, China, and Italy, drawing from fermentation-derived polyene feedstocks and semi-synthetic lipopeptide precursors. Single-source vulnerability in specialized biocatalysis capacity for echinocandin synthesis creates supply risk during demand surges. Distribution runs through integrated delivery network contracts that bundle systemic agents with diagnostic testing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation capacity for polyene and echinocandin API production operates at effective constraint, propping pricing power for manufacturers with captive supply or long-term offtake agreements.
For Market Incumbents: Hedge against azole cross-resistance erosion by accelerating novel mechanism glucan synthase inhibitor development and securing backward integration into liposomal encapsulation manufacturing. Threat from resistant Candida auris strains is displacing legacy azole protocols in oncology wards. Capacity addition in United States and German fermentation hubs anchors supply security. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for sponsors with resistant Candida data packages to secure premium formulary placement before established players consolidate. White-space targets include outpatient infusion center channels for prolonged echinocandin administration and companion diagnostics integration for biomarker-guided therapy in transplant units. Go-to-market angle should emphasize stewardship compliance bundling with pharmacy utilization review programs. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap biotech acquisition by multinational pharmaceutical conglomerates seeking infectious disease franchise expansion. Long-term viability hinges on pipeline depth against WHO fungal priority pathogens and regulatory exclusivity runway. Signal to watch is EMA accelerated assessment pathway grant velocity for novel mechanism agents, indicating sponsor quality and commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Geographically diverse trial networks spanning Houston, Berlin, and Osaka mycology centers satisfy FDA and EMA requirements for resistant strain data packages. |
| Regulatory Approval Pathway | Breakthrough therapy designation from FDA compresses review timelines for echinocandin derivatives targeting Candida auris in immunocompromised populations. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion addresses supply constraints for renal-impaired ICU populations requiring extended amphotericin B dosing. |
| Pipeline Diversification | Novel glucan synthase inhibitors with distinct resistance profiles differentiate positioning against azole cross-resistance in agricultural and clinical reservoirs. |
| Strategic Partnership | Diagnostic-therapeutic bundling with fungal biomarker testing companies opens precision medicine positioning in stem cell transplant units. |
Study Parameters
Multi-period observation of FDA approval timelines, EMA accelerated assessment grants, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-checked segment sizing across the analysis window.
The input-output matrix framed demand drivers including oncology ward expansion, resistant strain surveillance data, and stewardship mandate compliance against supply-side fermentation capacity and liposomal manufacturing scale. Segmentation dimensions modeled encompass product type, delivery mode, end-user infrastructure, and indication severity. CAGRs were derived from regression analysis of historical procurement volume against projected patient population growth and formulary access expansion. Industry-specific forecast inputs include WHO fungal priority pathogen surveillance trends and antimicrobial resistance stewardship penetration rates.
The model assumes a particular technology adoption path; alternative pathways for novel oral antifungal formulations with improved bioavailability would alter the outlook by shifting administration from inpatient to ambulatory settings. Forecasts reflect assumptions regarding regulatory exclusivity frameworks and resistance surveillance network expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market