
 Radioactive Iodine Ablation Therapy Market | 2026-2036
Radioactive Iodine Ablation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Radioactive Iodine Ablation Therapy Market Analytics
Multi-source procurement of iodine-131 isotopes is hardening as hospital networks reduce dependency on single suppliers. Curium sustains European production capacity through its vertically integrated radioisotope network. Johnson & Johnson anchors North American distribution through its specialty pharmacy infrastructure. Olympus Corporation differentiates in Asia-Pacific by controlling endoscopic delivery system integration for combined diagnostic-therapeutic protocols.
Radioactive iodine ablation therapy employs iodine-131, a beta-emitting radioisotope with a half-life of approximately eight days, to selectively destroy thyroid tissue through targeted radiation uptake. The treatment exploits the thyroid gland's unique iodine-avid physiology, delivering absorbed doses of 50–200 mGy to diseased tissue while sparing adjacent structures. Liquid iodine solution formulations lead in hospital inpatient settings due to standardized dosing protocols and established nuclear pharmacy workflows. Oral administration dominates delivery mode preference, though intravenous injection formats gain traction in European clinics seeking reduced contamination risk and faster bioavailability.
FDA regulations governing radioisotope handling and disposal, alongside NRC licensing requirements for nuclear medicine facilities, determine market access and operational compliance costs in the United States. Europe's EMA centralized procedure for radiopharmaceuticals, combined with REACH-mandated isotope transport protocols, creates divergent approval timelines across jurisdictions. Stakeholders must monitor evolving waste disposal regulations and reimbursement parity between inpatient and outpatient ablation settings as care migration accelerates.
Market Dynamics
Hospital networks are consolidating iodine-131 procurement to reduce supply vulnerability, forcing radioisotope distributors to restructure fulfillment models around multi-source redundancy rather than single-origin contracts.
Growth Catalysts
- FDA orphan drug incentives:Streamlined approval pathways for differentiated thyroid therapeutics accelerate clinical pipeline progression and expand addressable patient populations.
- Tertiary hospital endocrinology departments:Rising procedure volumes at specialized thyroid centers drive consistent demand for standardized ablation protocols.
- Intravenous iodine-131 formulations:European clinics adopting injection formats over oral administration reduce contamination exposure and improve dosing precision.
Market Restraints
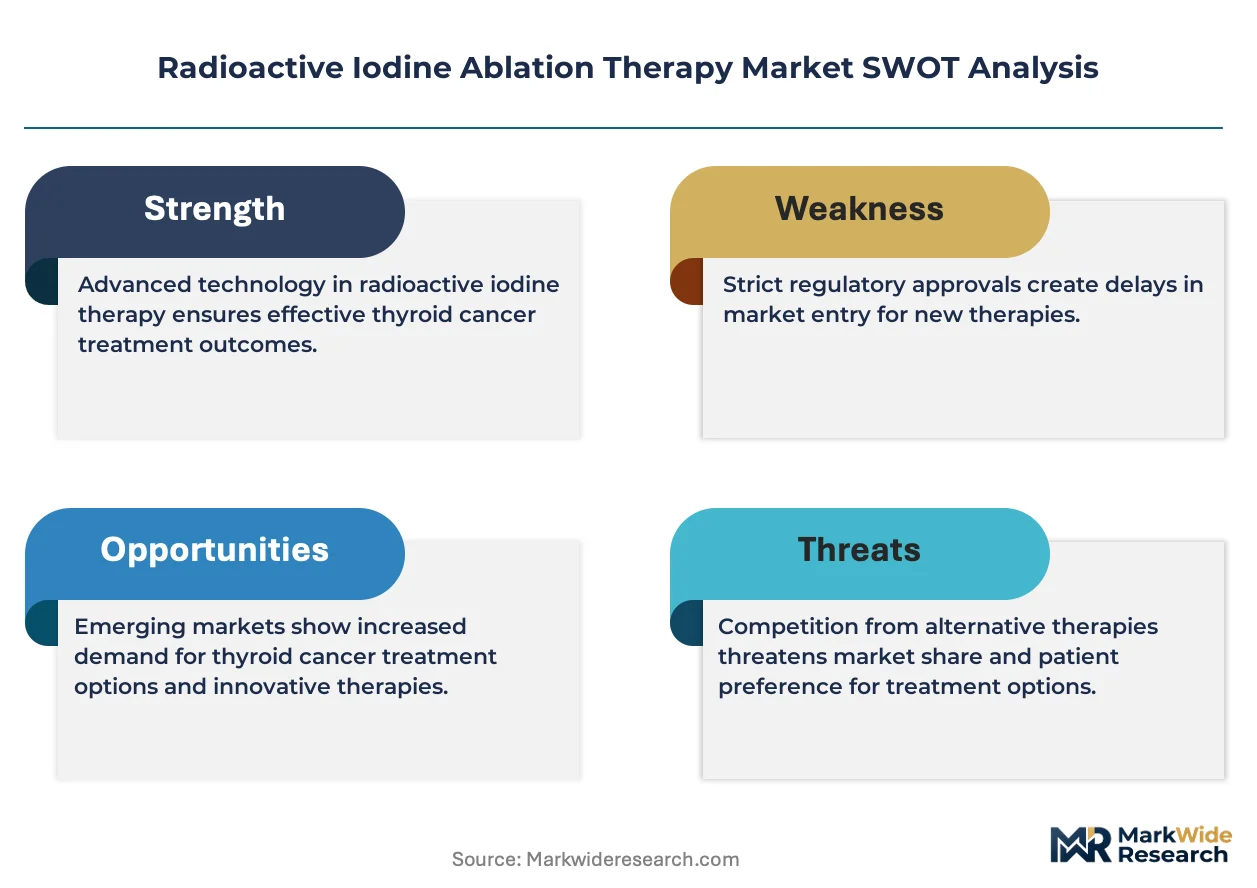
- Iodine-131 production concentration:Reactor-dependent isotope supply chains in limited geographic clusters create vulnerability to unplanned maintenance shutdowns.
- NRC licensing complexity:Nuclear medicine facility certification requirements in the United States extend operational startup timelines and elevate compliance overhead.
- External beam radiotherapy substitution:Precision-targeted radiation alternatives for select thyroid malignancies compete for physician preference in specific indications.
Strategic Opportunities
- Japan's aging thyroid patient base:Expanding geriatric demographics with differentiated cancer profiles create demand for personalized ablation dosing regimens.
- EMA centralized radiopharmaceutical procedure:Harmonized European approval standards reduce cross-border market entry friction for novel delivery formulations.
- Diagnostic-therapeutic protocol integration:Combined imaging-ablation workflows using hybrid tracer technologies compress patient pathway duration and improve care coordination.
Industry Challenges
- Nuclear pharmacy technician scarcity:Specialized compounding expertise for radioisotope handling limits facility expansion capacity and extends staffing cycles.
- Waste disposal compliance escalation:Evolving EPA and state-level radioactive material disposal mandates force ongoing infrastructure investment for treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radioactive Iodine Ablation Therapy Market |
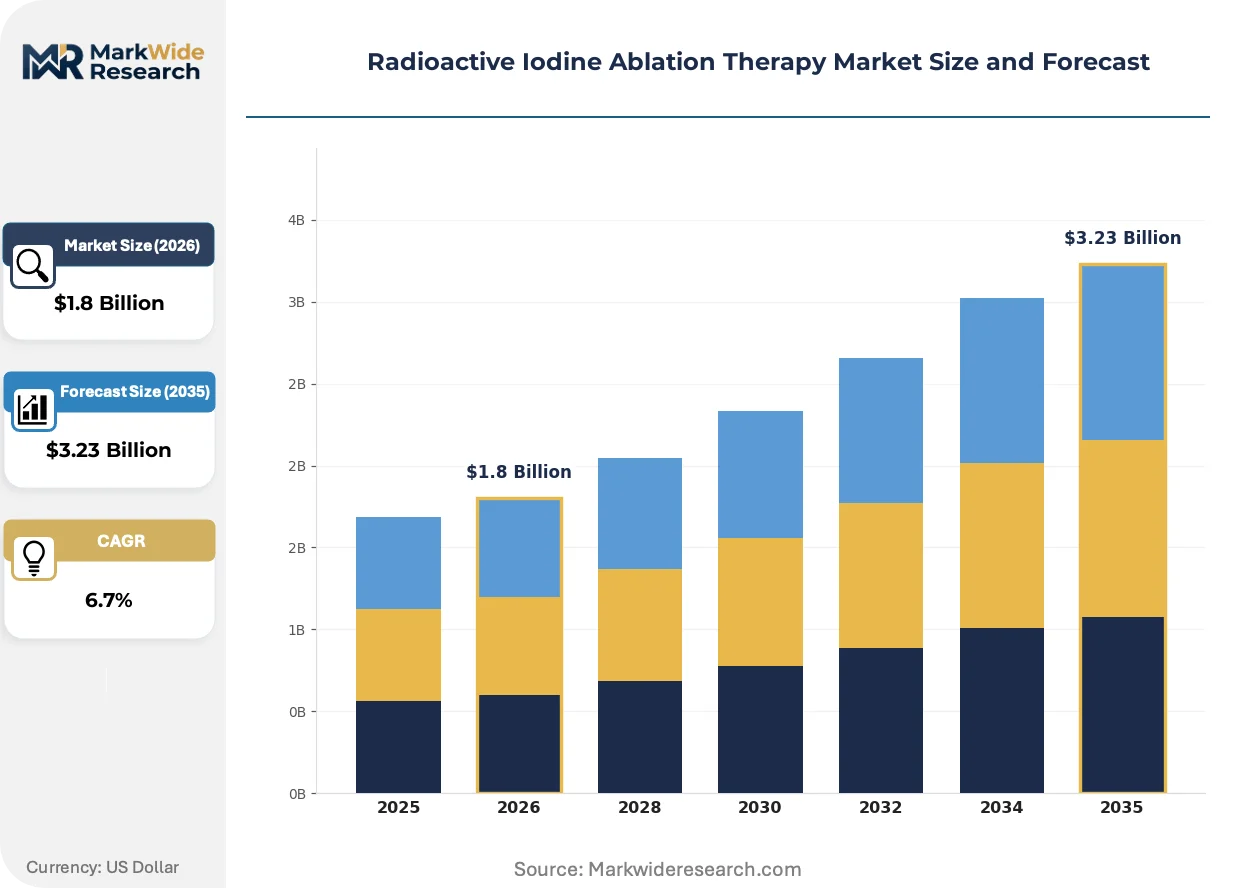
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radioactive Iodine Capsules, Liquid Iodine Solution, Injection Iodine, Diagnostic Iodine Application: Hyperthyroidism, Thyroid Cancer, Graves' Disease, Benign Thyroid Nodules End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Delivery Mode: Oral Administration, Intravenous Injection, Inhalation Therapy, Topical Application |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, Johnson & Johnson, Galil Medical Inc., AngioDynamics, Inc., Integra LifeSciences, Olympus Corporation, Terumo Corporation, Curium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radioactive Iodine Ablation Therapy Market Evolving Landscape
Radioactive iodine ablation therapy is experiencing fundamental workflow transformation as digital dosimetry, regulatory harmonization, and procurement rationalization reshape how treatment centers acquire and administer isotope-based care.
Personalized dosimetry software is converging with traditional uptake scanning to enable patient-specific absorbed dose calculations rather than fixed-activity protocols. Endocrinology departments at academic medical centers are piloting these platforms to reduce post-ablation hypothyroidism rates. The technology is converging with established nuclear medicine workflows to displace empirical dosing and compress adverse event incidence.
REACH-mandated isotope transport protocols are tightening documentation requirements for cross-border iodine-131 shipments within Europe. Pharmaceutical logistics providers must now maintain chain-of-custody records meeting ECHA substance tracking standards. German and French distribution networks are responding by regionalizing production buffers to minimize transit complexity.
Hospital pharmacy directors are consolidating radioisotope purchasing through group procurement organizations to extract volume-based pricing and supply security guarantees. This aggregation is displacing direct manufacturer relationships at individual treatment centers. The shift is most visible in United States health systems where centralized nuclear pharmacy operations now serve multiple hospital affiliates.
Radioactive Iodine Ablation Therapy Market Segmentation
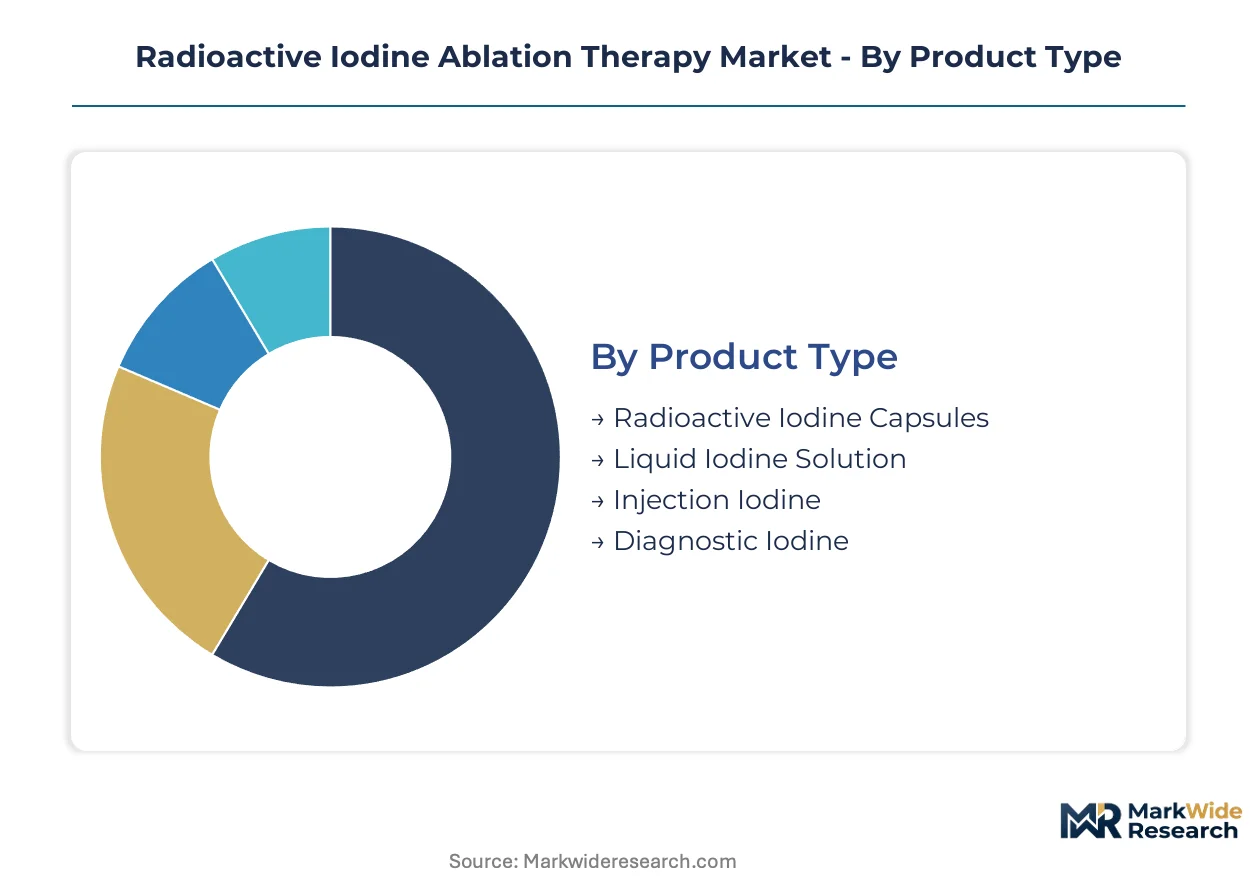
Segmentation in radioactive iodine ablation therapy reveals how formulation preferences, clinical settings, and administration protocols diverge across patient populations and regulatory environments. Understanding these partitions exposes where procurement investments concentrate and which delivery innovations command premium positioning.
Product Type:
Upgrade cycles in nuclear pharmacy infrastructure are pushing hospitals toward formulations that reduce contamination risk while preserving dosing precision.
- Radioactive Iodine Capsules:Gelatin-encapsulated iodine-131 with standardized activity levels enables outpatient administration and simplifies inventory tracking. Demand clusters in United States tertiary hospitals where NRC licensing favors sealed-source formats that minimize airborne release during handling.
- Liquid Iodine Solution:Aqueous sodium iodide formulations dissolved in water or juice permit flexible activity adjustment at the point of care. European clinics in Germany and France prefer this format for its compatibility with established nuclear pharmacy workflows and lower per-dose procurement cost.
- Injection Iodine:Sterile parenteral preparations for intravenous delivery.
- Diagnostic Iodine:Low-activity tracer formulations for pre-ablation uptake scanning and staging protocols.
Volume placements concentrate in Liquid Iodine Solution; the faster expansion belongs to Injection Iodine.
Application:
Cost tier stratification separates curative protocols from palliative or monitoring applications, with reimbursement intensity tracking disease severity and recurrence risk.
- Thyroid Cancer:Post-surgical ablation of residual tissue and metastatic lesions using calculated absorbed doses. United States academic medical centers drive protocol standardization through ATA guidelines implementation, while Japan's aging demographic expands the eligible patient pool for differentiated carcinomas.
- Hyperthyroidism:Definitive destruction of overactive thyroid tissue refractory to antithyroid drugs. German endocrinology departments favor this indication for its predictable single-dose efficacy and reduced long-term medication burden compared to chronic management.
- Graves' Disease:Autoimmune hyperthyroidism requiring tissue-specific intervention.
- Benign Thyroid Nodules:Non-malignant enlargements treated when compressive symptoms or cosmetic concerns warrant intervention.
Clinical volume clusters in Thyroid Cancer; Graves' Disease is gaining share fastest as first-line therapy displacement accelerates.
End User:
Customer type fragmentation reflects divergent capabilities in radioisotope handling, with licensing tiers determining which settings can sustain iodine-131 programs.
- Hospitals:Tertiary centers with dedicated nuclear medicine departments and licensed hot labs. United States health systems consolidate purchasing through centralized nuclear pharmacy operations serving multiple affiliates, while Japanese national university hospitals anchor regional referral networks for complex cases.
- Clinics:Outpatient endocrinology practices with limited radioisotope permits.
- Research Laboratories:Academic and commercial sites investigating dosimetry optimization and novel tracer combinations.
- Homecare Settings:Supervised self-administration protocols for select low-risk patients.
Procurement authority rests with Hospitals; Research Laboratories are climbing the fastest as personalized dosimetry trials multiply.
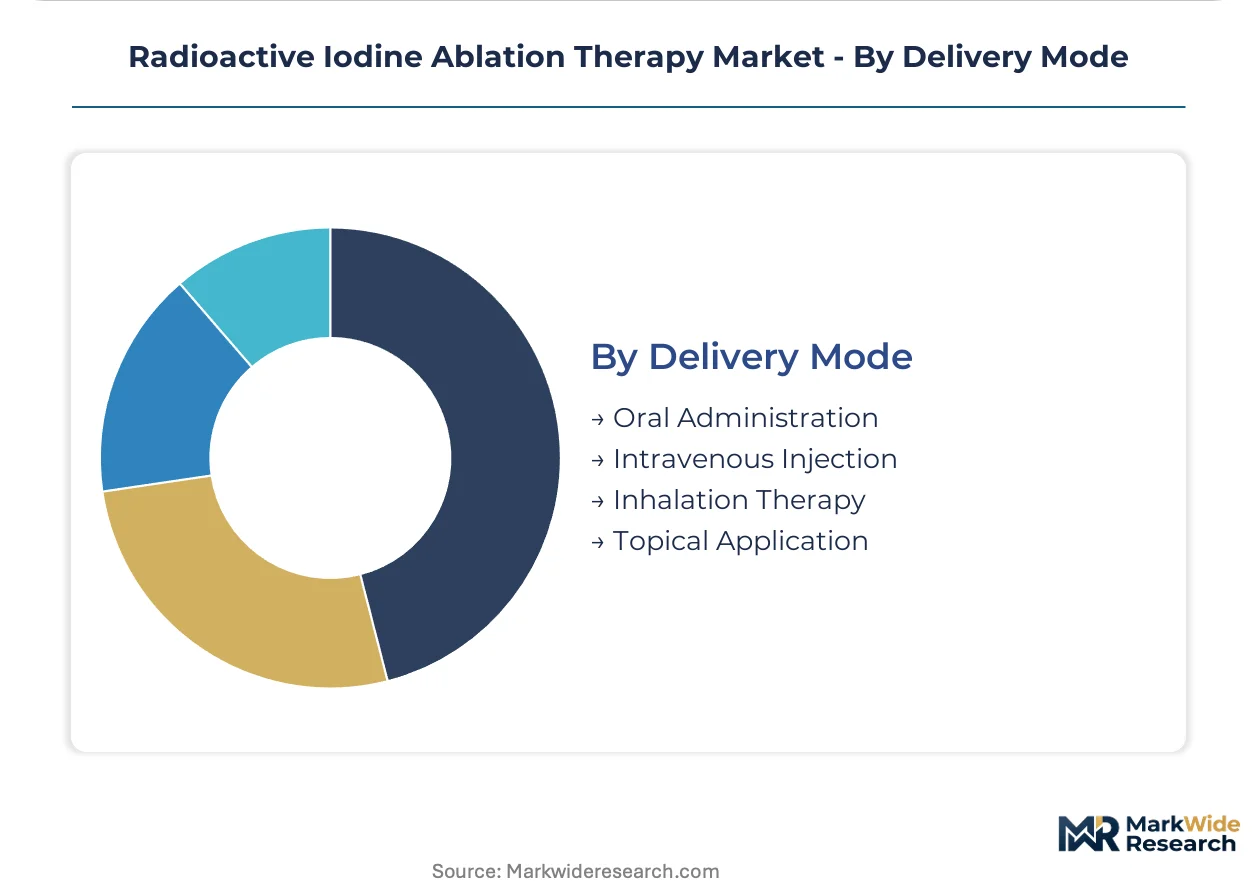
Delivery Mode:
Application context dictates format selection, with contamination control and bioavailability speed trading off against patient acceptability and infrastructure requirements.
- Oral Administration:Capsule or liquid ingestion remains the dominant delivery pathway. United States inpatient protocols favor this mode for its simplicity and reduced need for intravenous access, though European adoption of alternatives is accelerating.
- Intravenous Injection:Direct vascular delivery of sterile iodine-131 preparations. French and Belgian clinics lead adoption to eliminate saliva contamination and achieve faster plasma concentration peaks for time-critical protocols.
- Inhalation Therapy:Aerosolized radioiodine for specialized pulmonary metastasis targeting.
- Topical Application:Surface-directed delivery for cutaneous thyroid metastases.
Procedure counts favor Oral Administration; Intravenous Injection shows the steepest expansion trajectory as contamination regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reactor-based iodine-131 production in Canada, Belgium, and South Africa anchors supply security for treatment centers worldwide. Hospital networks in major economies calibrate procurement strategies against these isotope origination points.
United States
Tertiary endocrinology departments at academic medical centers in Houston and Boston drive procedure standardization through ATA guideline implementation. FDA orphan drug incentives and NRC licensing requirements shape facility expansion timelines. The Mayo Clinic anchors a regional referral network spanning the Upper Midwest for complex thyroid malignancy cases.
Germany
University hospitals in Munich and Heidelberg favor liquid iodine-131 formulations compatible with established nuclear pharmacy workflows. EMA centralized radiopharmaceutical procedures and REACH-mandated transport protocols govern cross-border isotope movement. The Rhine-Main cluster concentrates specialized thyroid centers with integrated diagnostic-therapeutic capabilities.
Japan
National university hospitals in Tokyo and Osaka manage expanding geriatric thyroid cancer populations through personalized ablation dosing regimens. METI oversight of radioisotope handling aligns with PMDA safety monitoring for nuclear medicine facilities. The Kanto region hosts the highest density of licensed hot labs for outpatient ablation protocols.
France
Clinics in Paris and Lyon lead European adoption of intravenous iodine-131 injection formats to reduce contamination exposure. ANSM radiopharmaceutical licensing and ECHA substance tracking standards tighten documentation requirements for isotope distribution. The Île-de-France region regionalizes production buffers to minimize transit complexity under REACH protocols.
United Kingdom
Thyroid centers in London and Manchester consolidate purchasing through NHS nuclear pharmacy networks serving multiple hospital trusts. MHRA guidance on radioisotope handling and disposal determines operational compliance costs for treatment facilities. The Oxford-Cambridge corridor anchors academic research into dosimetry optimization for pediatric applications.
Radioactive Iodine Ablation Therapy Market Competitive Landscape
Multi-source procurement restructuring dominates the current landscape as hospital networks reduce dependency on single suppliers. The vendor base fragments across three tiers: vertically integrated radioisotope producers controlling reactor-to-clinic supply chains; specialty pharmacy distributors managing last-mile nuclear logistics; and endoscopic equipment manufacturers integrating diagnostic-therapeutic delivery systems. Consolidation pressures favor players with captive isotope production or established nuclear pharmacy infrastructure. Geographic expansion and strategic partnerships represent the dominant competitive moves.
Among diversified medical technology conglomerates, Medtronic Plc and Boston Scientific Corporation exemplify scale-driven archetypes with broad portfolio coverage across interventional specialties. Johnson & Johnson occupies a position anchoring North American distribution through specialty pharmacy infrastructure. Curium represents the vertically integrated radioisotope producer archetype with European production capacity. Olympus Corporation and Terumo Corporation sit within the Asia-Pacific equipment integration tier, controlling endoscopic delivery system compatibility for combined protocols.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Galil Medical Inc. |
| AngioDynamics, Inc. |
| Integra LifeSciences |
| Olympus Corporation |
| Terumo Corporation |
| Curium |
| Others |
Value Network & Pricing Analysis
Reactor-to-clinic certification tiers split the iodine-131 market into NRC-licensed sealed-source premiums and liquid formulation commodities, with each tier demanding distinct supply chain investments in hot lab infrastructure and cross-border transport compliance. United States tertiary hospitals pay substantial premiums for capsule formats that minimize airborne release liability, while European clinics absorb REACH-mandated documentation costs to access lower-cost aqueous solutions from regional nuclear pharmacies.
Pricing Analysis
Warranty and handling-service bundling separates premium capsule suppliers from unbundled liquid formulation vendors, with the former embedding NRC compliance support and disposal guarantees into per-dose pricing. Three-tier pricing structure across premium sealed-source, standard liquid, and economy bulk isotope levels tracks certification grade and geographic delivery cost, with United States inpatient settings showing least price sensitivity due to reimbursement parity. Cost compression in European liquid formulations is intensifying because hospital pharmacy directors aggregate purchasing through group procurement organizations. Research laboratories exhibit highest price sensitivity as grant-funded operations optimize tracer procurement against fixed budgets.
Supply Chain Analysis
Regional distribution centers in Belgium, Canada, and South Africa anchor hub-and-spoke patterns that feed downstream nuclear pharmacy networks across North America and Europe. Iodine-131 production draws from uranium target irradiation at aging research reactors, with molybdenum-99 co-production dependencies and specialized lead-shielded transport casks as critical inputs. Single-source vulnerability concentrates at the reactor layer, where unplanned maintenance shutdowns cascade through six-month supply horizons. Distribution runs through vertically integrated radioisotope producers controlling captive production, specialty pharmacy distributors managing last-mile cold chain logistics, and hospital group purchasing organizations consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NRC licensing requirements and EPA radioactive waste disposal mandates erect substantial compliance moats, with facility certification timelines and infrastructure investments filtering out undercapitalized competitors and protecting incumbent returns.
For Market Incumbents: Cement market position by deepening backward integration into reactor partnerships or long-term offtake agreements that secure isotope supply against production concentration risks. Expand capacity in Japan's Kanto region to capture geriatric thyroid cancer volume growth. Curium's vertically integrated European network exemplifies the defensive architecture that limits entrant access to reliable iodine-131 supply. For New Entrants and Emerging Players: Capture share in personalized dosimetry software and hybrid tracer technologies where diagnostic-therapeutic protocol integration creates white-space opportunities outside established sealed-source distribution. Japan's aging patient base and Germany's liquid formulation preference represent most penetrable geographies for novel delivery innovations. Partner with academic medical centers to pilot patient-specific absorbed dose platforms that displace empirical protocols. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated radioisotope producers given EMA centralized radiopharmaceutical harmonization and multi-source procurement restructuring by hospital networks. Long-term viability hinges on captive production assets or established nuclear pharmacy infrastructure that transcends commodity pricing cycles. Watch FDA orphan drug incentive expansion for differentiated thyroid therapeutics as inflection signal for pipeline value creation.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Partnership or Long-term Isotope Offtake | Secures iodine-131 supply against unplanned maintenance shutdowns at limited production sites. |
| Personalized Dosimetry Software Development | Enables patient-specific dosing that reduces post-ablation hypothyroidism rates at academic centers. |
| EMA Centralized Procedure Submission | Accelerates cross-border market entry for novel intravenous formulations in European clinics. |
| Group Procurement Organization Consolidation | Extracts volume-based pricing and supply security guarantees from hospital network aggregation. |
| Hybrid Tracer Diagnostic-Therapeutic Integration | Compresses patient pathway duration through combined imaging-ablation workflow protocols. |
Research Methodology
Independent corroboration across nuclear medicine department heads, hospital pharmacy directors, radioisotope distribution executives, and regulatory affairs specialists underwrites the qualitative findings on procurement pattern shifts. Primary interviews with endocrinologists at tertiary centers in Houston, Boston, Munich, and Tokyo combined with secondary validation from FDA filings, EMA centralized procedure submissions, NRC licensing databases, and hospital GPO contract records. Bottom-up procedure volume estimates triangulate against top-down market sizing from reactor production capacity disclosures.
Comparable-period anchoring to historical ablation procedure registries and reimbursement claim patterns calibrates the projection framework across the analysis window. Segmentation dimensions span formulation type, delivery mode, application indication, and end-user facility tier, with regional regulatory clusters modeled separately for NRC, EMA, and PMDA jurisdictions. CAGRs derive from logistic adoption curves for intravenous injection formats and demographic elasticity for geriatric thyroid cancer incidence. Forecast inputs incorporate reactor maintenance schedules, orphan drug pipeline progression, and hospital network consolidation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reactor decommissioning decisions, personalized dosimetry regulatory acceptance, and external beam radiotherapy substitution rates. Outputs reflect documented assumptions on isotope supply continuity, reimbursement stability, and licensing requirement evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Non-Invasive Surgery Market