
 Brain Metastasis Therapeutics Market | 2026-2036
Brain Metastasis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Metastasis Therapeutics Market Analysis
Project finance for late-stage neuro-oncology pipelines is tilting competitive advantage toward firms with balance-sheet capacity to absorb Phase III risk. F. Hoffmann-La Roche Ltd leverages its diagnostic-therapeutic integration to control patient identification workflows. Merck & Co., Inc. sustains leadership through R&D intensity in checkpoint inhibitor combinations. Bristol-Myers Squibb anchors its position via geographic dominance in North American academic medical center networks.
Brain metastasis therapeutics comprise systemic and localized interventions designed to cross or bypass the blood-brain barrier, including small-molecule inhibitors, monoclonal antibodies, and stereotactic radiation platforms with sub-millimeter precision targeting. These modalities serve the primary purpose of extending survival and preserving neurological function in patients with secondary central nervous system malignancies. Targeted therapy commands margin pools where biomarker-driven patient selection justifies premium positioning, while immunotherapy represents the fastest-expanding category as checkpoint inhibitors demonstrate intracranial activity. Radiation therapy remains mature and volume-heavy, with delivery mode shifting toward implantable and intrathecal systems that reduce hospital dependency.
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathways shape demand by compressing development timelines and expanding early access programs. FDA oncology center review standards and EMA's MDR compliance requirements for companion diagnostics determine market access thresholds for combination regimens. Stakeholders must monitor evolving blood-brain barrier penetration benchmarks as regulatory agencies tighten efficacy expectations for CNS-active claims.
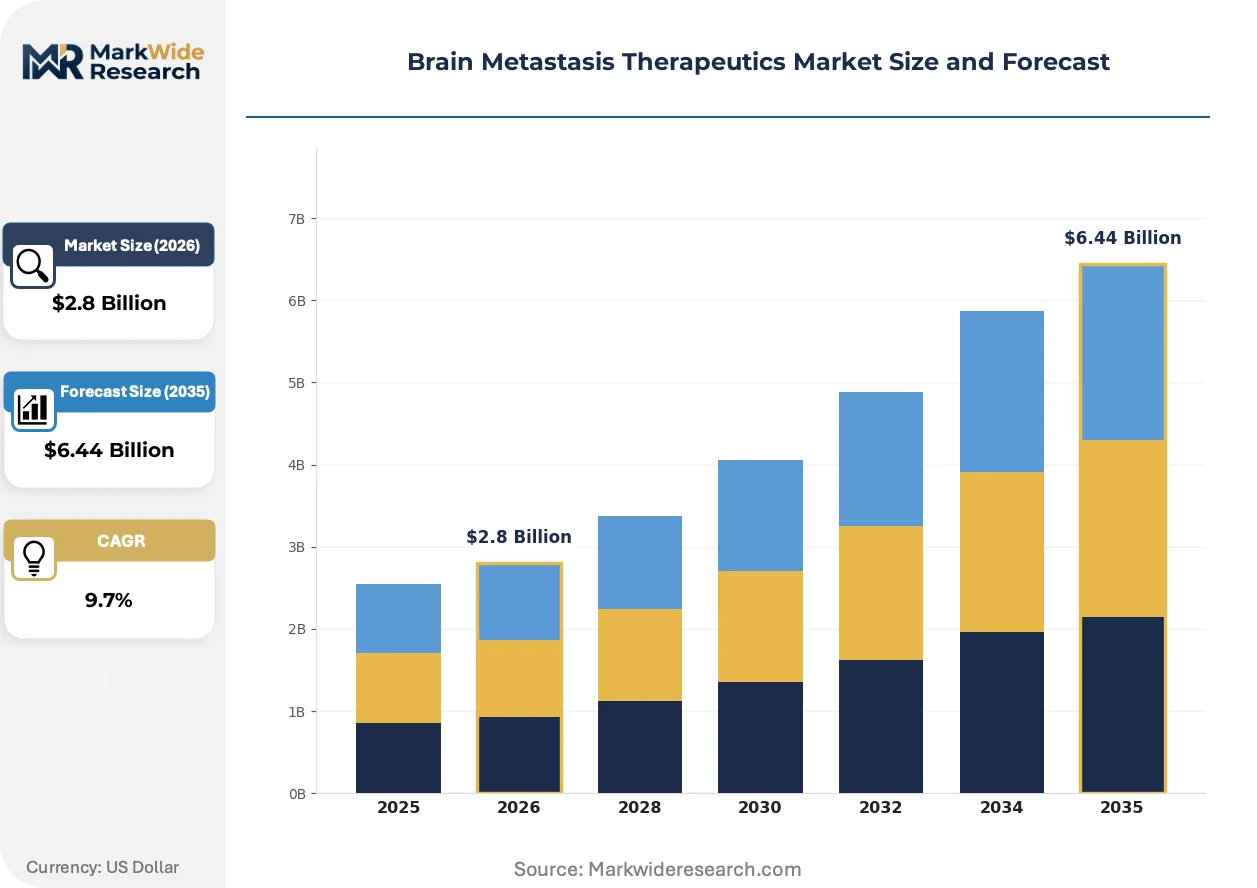
Market Dynamics
The blood-brain barrier penetration challenge is concentrating R&D investment toward molecular engineering platforms that enable systemic agents to achieve intracranial efficacy, fundamentally restructuring how therapeutic candidates advance through clinical pipelines.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for CNS-active candidates, enabling earlier commercial access for patients with limited treatment options.
- Biomarker-Driven Patient Stratification:Companion diagnostic integration allows oncology clinics to identify molecular subpopulations most responsive to targeted interventions, improving trial efficiency and real-world outcomes.
- Stereotactic Radiosurgery Platforms:Sub-millimeter precision delivery systems are expanding treatment eligibility to patients previously excluded from surgical intervention due to tumor location or comorbidity burden.
Market Restraints
- Plasma Protein Binding Limitations:High albumin affinity in many small-molecule candidates restricts free drug availability for blood-brain barrier transit, forcing reformulation investments.
- Specialized Neuro-Oncology Workforce Scarcity:Concentration of qualified investigators at academic medical centers in the United States, Germany, and Japan creates site activation bottlenecks for multinational trials.
- Reimbursement Uncertainty for Combination Regimens:Payer frameworks designed for single-agent oncology pricing struggle to assign value to checkpoint inhibitor plus targeted therapy protocols.
Strategic Opportunities
- Intrathecal Delivery Systems:Implantable pump technologies bypass systemic circulation entirely, opening addressable populations with leptomeningeal carcinomatosis previously considered untreatable.
- EMA PRIME Scheme Eligibility:Priority medicines designation offers enhanced regulatory support for therapies addressing the unmet need in CNS malignancies, accelerating European market entry.
- Real-World Evidence Infrastructure:Neuro-oncology registry networks in the United States and Germany enable post-approval efficacy confirmation without placebo-controlled trials.
Industry Challenges
- Pharmacokinetic-Pharmacodynamic Modeling Talent:Scarcity of specialists capable of predicting CNS penetration from preclinical data delays candidate selection and increases late-stage failure rates.
- Multi-Site Trial Coordination Complexity:Variability in neurocognitive assessment protocols across academic medical centers complicates endpoint standardization for registration studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Metastasis Therapeutics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Delivery Mode: Intravenous, Oral, Intrathecal, Implantable End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Settings Application: Treatment, Palliative Care, Clinical Trials, Supportive Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Bristol-Myers Squibb, Novartis AG, Pfizer Inc., Eli Lilly & Company, AstraZeneca, Bayer AG, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Metastasis Therapeutics Market Emerging Trajectories
Computational platforms are reshaping how therapeutic candidates are screened for blood-brain barrier permeability, compressing the traditional empirical optimization cycle and redirecting capital toward molecules with validated CNS exposure profiles.
Artificial intelligence-driven molecular dynamics simulation is digitizing the prediction of transporter-mediated brain penetration, replacing high-throughput screening cascades with in silico prioritization. Biotechnology firms and large pharmaceutical developers are integrating these platforms into early discovery workflows. The structural consequence is a narrowing pipeline funnel where only candidates with computationally validated CNS exposure advance to costly in vivo studies.
The FDA's Project Optimus initiative is revising dose-finding expectations for oncology therapeutics, requiring sponsors to demonstrate optimal biological dose rather than maximum tolerated dose. This regulatory shift extends Phase I timelines but improves probability of success in registration trials. Developers of brain metastasis agents are responding with adaptive trial designs incorporating neurocognitive endpoints at earlier stages.
Academic medical centers are consolidating purchasing authority for radiation therapy platforms through multi-hospital system contracts, displacing vendor-direct relationships that previously dominated capital equipment procurement. Equipment manufacturers are restructuring sales organizations around integrated service agreements spanning hardware, software, and clinical training. This concentration is most visible in the United States, where major neuro-oncology networks in Boston, Houston, and San Francisco anchor regional purchasing coalitions.
Brain Metastasis Therapeutics Market Segmentation
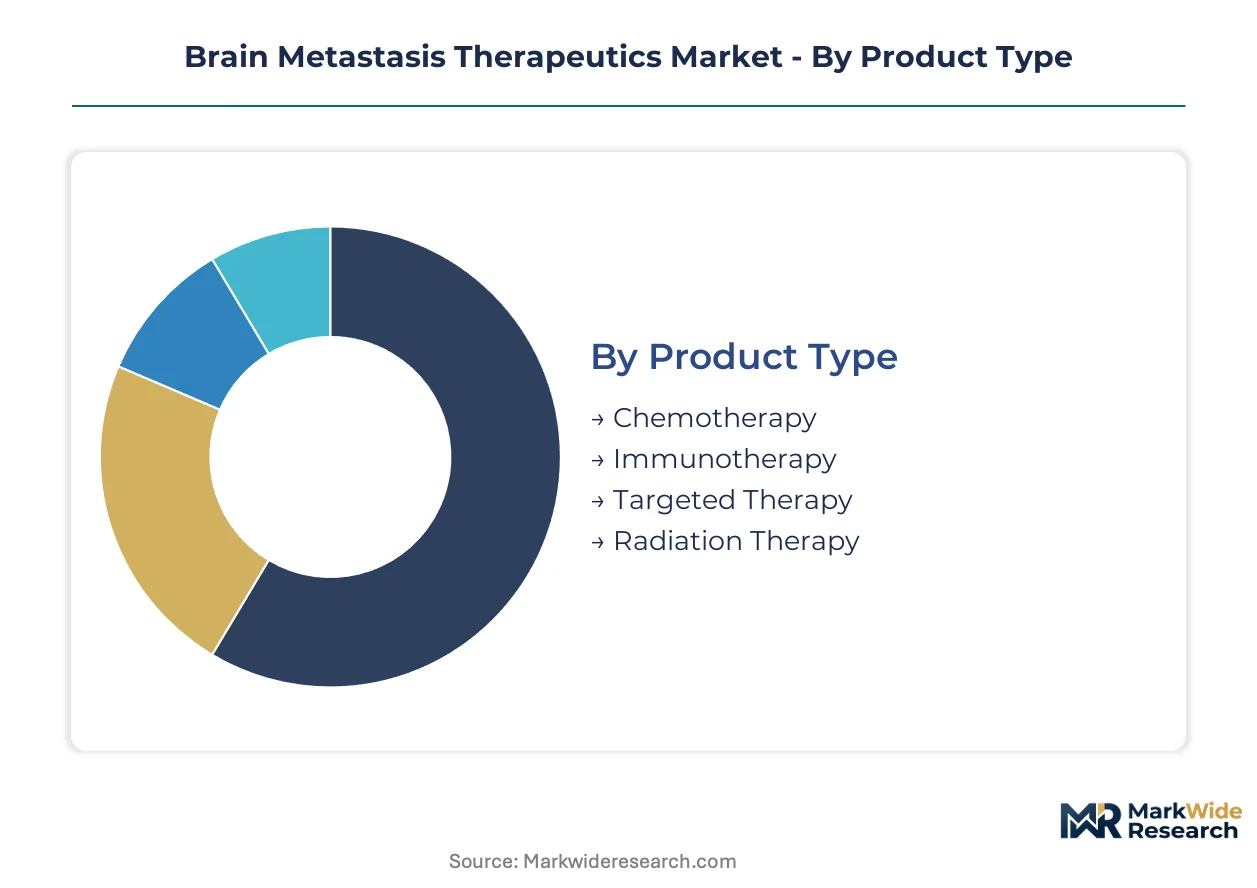
Segmentation in brain metastasis therapeutics reveals how treatment complexity fragments across delivery technologies, care settings, and clinical objectives. Each dimension carries distinct regulatory pathways, reimbursement structures, and technical capability requirements that shape vendor positioning and investment allocation.
Product Type:
After-sales service intensity varies sharply across therapeutic modalities, with radiation platforms demanding continuous hardware calibration and immunotherapy requiring cold-chain logistics support.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies engineered for blood-brain barrier penetration command premium positioning where companion diagnostics enable biomarker-driven patient selection. Demand concentrates in United States academic medical centers pursuing molecular stratification protocols, with FDA breakthrough designations accelerating commercial access timelines.
- Immunotherapy:Checkpoint inhibitors demonstrating intracranial activity are expanding addressable populations through combination regimens with radiation or targeted agents. Oncology clinics in Germany and Japan are adopting these protocols fastest, driven by EMA PRIME scheme eligibility and PMDA Sakigake designation pathways.
- Radiation Therapy:Stereotactic platforms with sub-millimeter precision require intensive field service contracts spanning hardware, software, and clinical training.
- Chemotherapy:Traditional cytotoxic agents retain volume in resource-constrained settings with established reimbursement frameworks.
Targeted therapy holds the largest share; momentum sits with immunotherapy.
Delivery Mode:
Cost tier stratification separates capital-intensive implantable systems from commodity oral formulations, with mid-tier intravenous infusion occupying hospital purchasing negotiations.
- Intravenous:Hospital-based infusion centers dominate administration, with oncology clinics in the United States consolidating purchasing through multi-hospital system contracts that displace vendor-direct relationships.
- Oral:Patient-administered small molecules reduce hospital dependency and enable homecare expansion, though bioavailability challenges persist for blood-brain barrier penetration.
- Intrathecal:Direct cerebrospinal fluid delivery via lumbar puncture or Ommaya reservoir addresses leptomeningeal carcinomatosis with specialized neurosurgical support requirements.
- Implantable:Programmable pump systems bypass systemic circulation entirely, opening populations previously considered untreatable but requiring surgical placement and refill logistics.
Intravenous administration retains volume leadership; implantable systems are climbing the fastest as technical barriers fall.
End User:
Customer type differentiation separates high-acuity academic centers with trial infrastructure from community oncology practices seeking standardized protocols.
- Hospitals:Comprehensive cancer centers anchor regional referral networks, with neuro-oncology departments in Boston, Houston, and San Francisco purchasing authority consolidating across multi-site systems.
- Oncology Clinics:Community-based practices in the United States and Germany are expanding targeted therapy adoption where companion diagnostic workflows integrate into routine care.
- Research Institutions:Phase I-II trial sites concentrate in Japan and Switzerland, with PMDA and Swissmedic frameworks enabling early access program expansion.
- Homecare Settings:Oral agent administration and portable pump management are shifting selected interventions outside traditional facilities, requiring nursing support infrastructure.
Hospitals command the dominant share; oncology clinics are gaining share fastest through community network expansion.
Application:
Maturity stage separates established treatment protocols from emerging palliative and supportive care categories with evolving evidence bases.
- Treatment:Curative-intent protocols combining surgery, radiation, and systemic therapy represent the core revenue base, with stereotactic radiosurgery eligibility expanding as precision improves.
- Clinical Trials:Academic medical centers in the United States, Germany, and Japan concentrate Phase II-III neuro-oncology studies, creating site activation bottlenecks due to qualified investigator scarcity.
- Palliative Care:Symptom-focused interventions for advanced disease are receiving expanded reimbursement attention as health technology assessments evolve.
- Supportive Care:Neurocognitive preservation and adverse effect management are integrating into protocol design under FDA Project Optimus dose-optimization expectations.
Treatment applications hold the largest share; clinical trials demonstrate the steepest expansion trajectory as pipeline activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized neuro-oncology networks concentrate purchasing authority in the United States, Germany, and Japan, where reimbursement frameworks for breakthrough therapies and conditional marketing authorizations accelerate adoption timelines.
United States
FDA breakthrough therapy designations compress development timelines for CNS-active candidates, while the agency's Project Optimus initiative revises dose-finding expectations for oncology protocols. Neuro-oncology networks in Boston, Houston, and San Francisco anchor regional purchasing coalitions that consolidate multi-hospital system contracts.
Germany
EMA PRIME scheme eligibility offers enhanced regulatory support for therapies addressing unmet CNS malignancy needs, accelerating European market entry for qualifying sponsors. Heidelberg and Munich host concentrated Phase I-II trial infrastructure where real-world evidence networks enable post-approval efficacy confirmation.
Japan
PMDA Sakigake designation pathways provide priority review for innovative neuro-oncology therapeutics, reducing time-to-market for intracranial-active agents. Tokyo and Osaka academic medical centers concentrate qualified investigator capacity, creating site activation advantages for multinational registration studies.
Switzerland
Swissmedic frameworks enable early access program expansion for experimental CNS therapeutics, attracting biotechnology firms seeking regulatory efficiency. Basel and Zurich research institutions anchor European clinical trial coordination for blood-brain barrier penetration studies.
United Kingdom
NICE technology appraisals determine reimbursement thresholds for combination regimens in secondary CNS malignancies, influencing payer adoption across NHS England. London and Cambridge neuro-oncology centers integrate companion diagnostic workflows into routine molecular stratification protocols.
Brain Metastasis Therapeutics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Large-cap pharmaceutical developers with diagnostic-therapeutic integration capabilities anchor the premium tier, while mid-scale biotechnology firms concentrate on molecular engineering platforms for blood-brain barrier penetration. The base tier includes regional generic manufacturers and radiation platform vendors with intensive after-sales service requirements. Consolidation pressure manifests through strategic partnerships combining checkpoint inhibitor portfolios with precision delivery technologies, alongside geographic expansion into Japanese and German early-access markets.
Within the integrated-diagnostics tier, F. Hoffmann-La Roche Ltd and Novartis AG exemplify channel-control strategies that span patient identification through treatment delivery. Bristol-Myers Squibb occupies a position emphasizing checkpoint inhibitor combinations with intracranial activity claims. These three anchors represent distinct competitive archetypes: diagnostic-therapeutic integration, precision oncology platform breadth, and immunotherapy-first combination development.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| Novartis AG |
| Pfizer Inc. |
| Eli Lilly & Company |
| AstraZeneca |
| Bayer AG |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific cold-chain logistics corridors connecting Osaka to Los Angeles and Rotterdam to Singapore dictate cost dynamics for temperature-sensitive biologics, concentrating pricing power with carriers holding validated container fleets while forcing downstream tiering between academic medical centers absorbing premium freight rates and community oncology practices selecting standard distribution tiers.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to commodity chemical benchmarks and energy input baskets, creating transparency that compresses margin capture for generic small-molecule manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates branded blood-brain barrier engineered agents with companion diagnostic bundling from unbranded cytotoxic formulations and commodity radiation fractions. Pricing pressure stems from Medicare reimbursement compression for intrathecal delivery procedures. Community oncology practices exhibit highest price sensitivity due to thin capitation margins, while comprehensive cancer centers absorb premium positioning for trial access.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza, Catalent, and Samsung Biologics holding mammalian cell culture capacity for monoclonal antibody production, while specialized radiopharmaceutical synthesis concentrates at Mallinckrodt and Lantheus facilities. Active pharmaceutical ingredient sourcing draws from Switzerland, Ireland, and Singapore for high-potency oncology compounds. Cold-chain distribution feeds from central depots in Indianapolis, Basel, and Tokyo through validated last-mile partnerships with specialty pharmacy networks. Single-source vulnerability sits with Ommaya reservoir and programmable pump manufacturers where FDA 510(k) clearance timelines deter dual-sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brain metastasis therapeutics occupy an early-cycle expansion position as intracranial-active checkpoint inhibitors penetrate first-line protocols previously reserved for radiation monotherapy, with FDA breakthrough designations compressing adoption timelines for combination regimens.
For Market Incumbents: Harden diagnostic-therapeutic integration by acquiring companion diagnostic developers with validated CNS biomarker assays, insulating against margin erosion from biosimilar small-molecule entrants. Expand Phase III trial infrastructure in Heidelberg and Tokyo to preempt site activation bottlenecks that delay registration for intrathecal delivery candidates.
For New Entrants and Emerging Players: Pursue leptomeningeal carcinomatosis as the most penetrable indication, where implantable pump technologies bypass entrenched radiation protocols and reimbursement frameworks remain unsettled. Establish partnerships with neurosurgical device distributors rather than building oncology sales forces directly.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates spinning off neuro-oncology assets lacking diagnostic integration scale. Blood-brain barrier engineering platforms with validated preclinical CNS exposure profiles represent the highest-conviction acquisition archetype. Watch FDA Project Optimus dose-optimization guidance revisions as the signal indicating whether adaptive trial designs accelerate or delay registration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Roche and Novartis anchor patient identification workflows through FDA-approved CNS biomarker assays. |
| Intrathecal Delivery Platform Licensing | Implantable pump technologies open leptomeningeal populations previously excluded from systemic therapy protocols. |
| EMA PRIME Scheme Application | Priority medicines designation accelerates European market entry for blood-brain barrier penetrating candidates. |
| Real-World Evidence Registry Participation | German and US neuro-oncology networks enable post-approval efficacy confirmation without placebo-controlled trials. |
| Adaptive Trial Design Implementation | FDA Project Optimus compliance requires neurocognitive endpoint integration at Phase I stages. |
Methodological Framework
The analysis maps targeted therapy, immunotherapy, radiation platforms, and intrathecal delivery systems, each validated through neuro-oncology department heads, hospital procurement managers, regulatory affairs leads at biotechnology firms, and payer access specialists. Primary interview data triangulates against FDA 510(k) and BLA filings, ClinicalTrials.gov protocol registrations, EMA assessment reports, and hospital GPO contract databases. Bottom-up patient-flow modeling reconciles with top-down pharmaceutical revenue disclosures across the analysis window.
Assumptions held fixed include current FDA breakthrough therapy designation approval rates and EMA conditional marketing authorization timelines, while variables include PMDA Sakigake uptake velocity and Medicare reimbursement rate adjustments for combination regimens. Segmentation dimensions span product type, delivery mode, end-user facility tier, and regional regulatory cluster. CAGRs derive from log-linear regression of historical adoption curves adjusted for pipeline phase transitions and blood-brain barrier penetration benchmark evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-scale biotechnology firms with computational CNS penetration platforms would shift outcomes through accelerated trial enrollment. Regulatory restriction tightening on leptomeningeal carcinomatosis endpoints or reimbursement exclusion for unproven combination protocols represent primary revision risks. Quarterly review of FDA oncology center guidance documents and CMS national coverage determination filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuroscience Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Triple X Syndrome Management Market