
 Herpes Simplex Keratitis Treatment Market | 2026-2036
Herpes Simplex Keratitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Simplex Keratitis Treatment Market Foresight
A capital-intensity divergence between large-scale API manufacturers and specialty ophthalmic formulators is unwinding competitive stability in herpes simplex keratitis therapeutics. GlaxoSmithKline plc leverages its antiviral heritage to sustain dominance in oral acyclovir formulations. Bausch Health Companies Inc. anchors its position through specialized eye drop portfolios targeting corneal specialists.
Herpes simplex keratitis treatment encompasses pharmaceutical interventions designed to suppress viral replication, mitigate stromal inflammation, and prevent corneal scarring in HSV-1 ocular infections, typically administered via topical ganciclovir gel or oral valacyclovir with dosing protocols calibrated to epithelial versus stromal disease presentation. The primary purpose is preservation of visual acuity through early viral load reduction and long-term latency management. Antiviral medication dominates current prescription volumes due to established efficacy protocols, while intravitreal delivery mode represents the fastest-expanding structural segment as clinicians seek targeted posterior segment drug deposition. Ophthalmology clinics capture concentrated margin pools through procedure-linked reimbursement for advanced delivery interventions.
FDA ophthalmic guidance documents, EMA's MDR framework for invasive delivery devices, and WHO essential medicines listings collectively shape product registration requirements, manufacturing standards, and market access pathways across major jurisdictions. These frameworks elevate clinical evidence thresholds for novel formulations while accelerating generic substitution in mature oral drug categories. Stakeholders must monitor evolving reimbursement policies for office-based intravitreal administration versus hospital-based alternatives.
Market Dynamics
Intravitreal delivery systems are compressing treatment paradigms for recurrent HSV-1 ocular infections, forcing API manufacturers and specialty formulators into direct competition for corneal specialist access.
Growth Catalysts
- EMA MDR framework:Streamlined device-approval pathways for ophthalmic delivery systems accelerate European clinic adoption of advanced intravitreal interventions.
- Ophthalmology clinic consolidation:Large specialty chains in the United States centralize purchasing power for procedure-linked antiviral therapies.
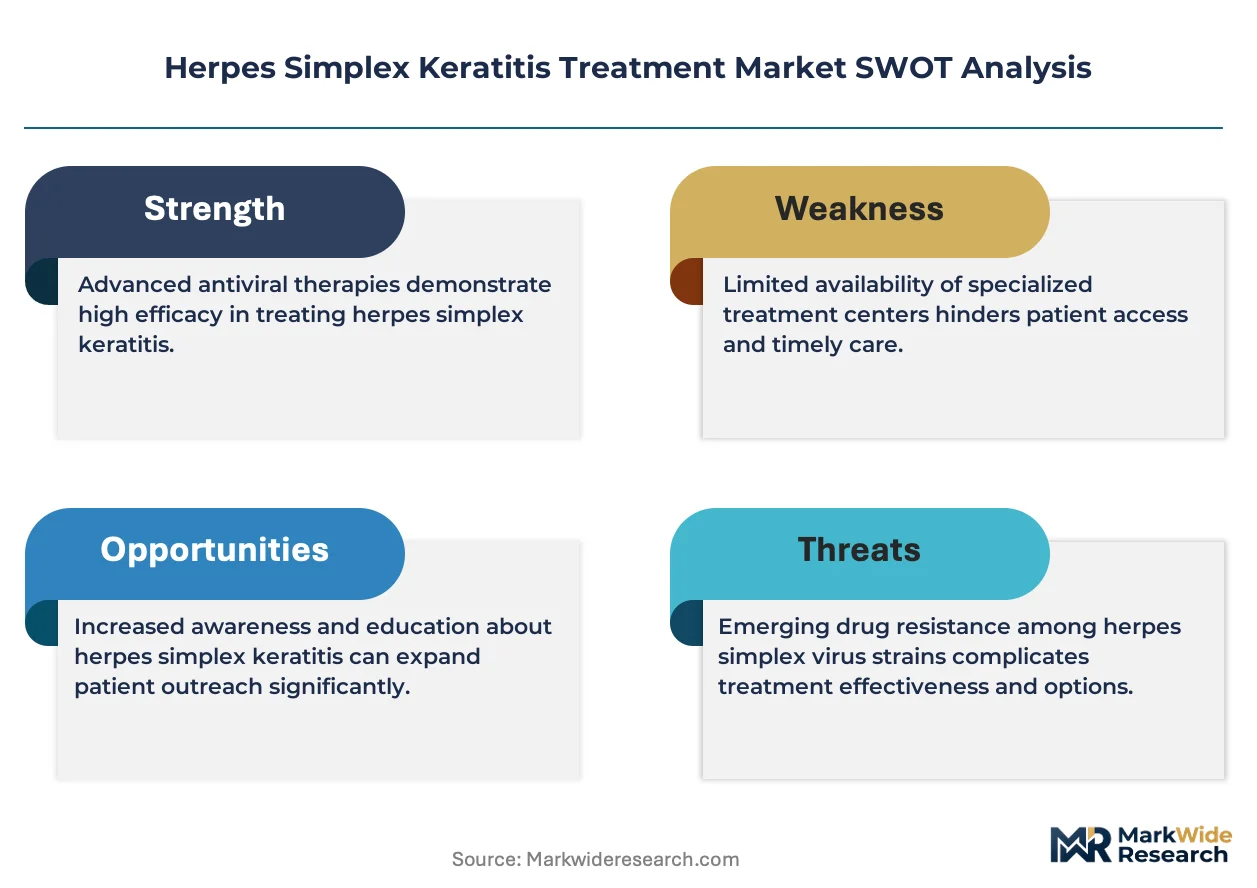
- Long-acting depot formulations:Extended-release ganciclovir implants reduce dosing frequency and improve patient compliance in stromal keratitis management.
Market Restraints
- API supply concentration:Bulk acyclovir and valacyclovir production clusters in Indian and Chinese chemical hubs, exposing formulators to export-license volatility.
- FDA ophthalmic guidance thresholds:Stringent bioequivalence requirements for topical generics extend development timelines and elevate clinical trial costs.
- Oral antiviral substitution:Generic valacyclovir commoditization compresses margins for branded topical alternatives in uncomplicated epithelial disease.
Strategic Opportunities
- Japan's aging corneal patient base:METI reimbursement incentives for minimally invasive delivery modes create entry pathways for depot-technology specialists.
- Combination antiviral-anti-inflammatory platforms:Converging steroid-sparing protocols address unmet need in necrotizing stromal presentations without triggering viral reactivation.
- Office-based intravitreal administration:Ambulatory surgical center certification expansions in Texas and Florida unlock procedure-volume growth outside hospital settings.
Industry Challenges
- Ocular pharmacokinetic modeling expertise:Scarcity of specialists bridging formulation science and corneal penetration dynamics delays novel delivery-system development.
- ISO 14155 clinical investigation standards:Multi-site ophthalmic trial coordination across divergent national ethics frameworks extends study startup intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Simplex Keratitis Treatment Market |
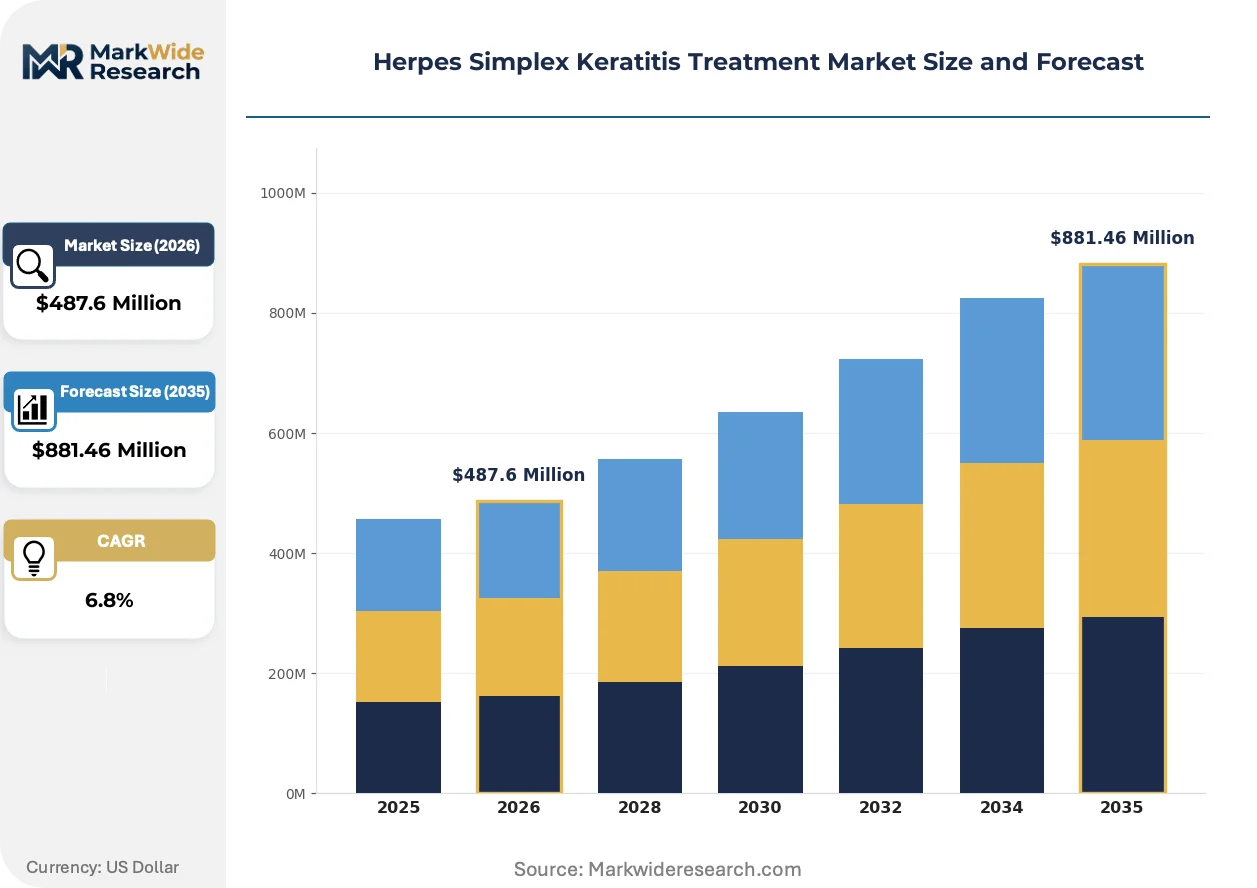
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Medication, Topical Ointments, Oral Drugs, Eye Drops End User: Hospitals, Ophthalmology Clinics, Home Care, Ambulatory Surgical Centers Delivery Mode: Topical, Oral, Injection, Intravitreal Indication: Primary Infection, Recurrent Infection, Prophylaxis, Complications |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Bausch Health Companies Inc., Pfizer Inc., Merck & Co. Inc., Aurobindo Pharma Limited, Dr. Reddy's Laboratories Limited, Cipla Limited, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Simplex Keratitis Treatment Market Shifts & Advancements
Sustained-release ocular drug delivery is reshaping competitive boundaries between systemic and local antiviral approaches, compressing the historical dominance of oral prophylaxis.
Nanoparticle-encapsulated ganciclovir formulations are fragmenting the topical antiviral segment by enabling transscleral drug reservoirs that bypass corneal epithelial barriers. Corneal specialists in academic medical centers are piloting these platforms for recurrent stromal disease. The technology is fragmenting procurement patterns as hospitals negotiate device-drug bundles rather than discrete pharmaceutical purchases.
REACH authorization requirements for novel excipients in ocular formulations are elevating toxicology documentation burdens for European market entrants. Manufacturers must now submit extended dermal and ocular irritation datasets prior to clinical trial authorization. Small-cap formulators lacking in-house regulatory toxicology capabilities are outsourcing to contract research organizations in Switzerland and the Netherlands.
Corneal specialists are unbundling diagnostic and therapeutic reimbursement, driving demand for point-of-care HSV PCR testing integrated with same-day treatment decisions. Independent ophthalmology clinics in the United States are acquiring rapid molecular diagnostic platforms to capture procedure-linked revenue streams. California and New York regulatory frameworks for office-based laboratory testing are accelerating this operational model shift.
Herpes Simplex Keratitis Treatment Market Segmentation
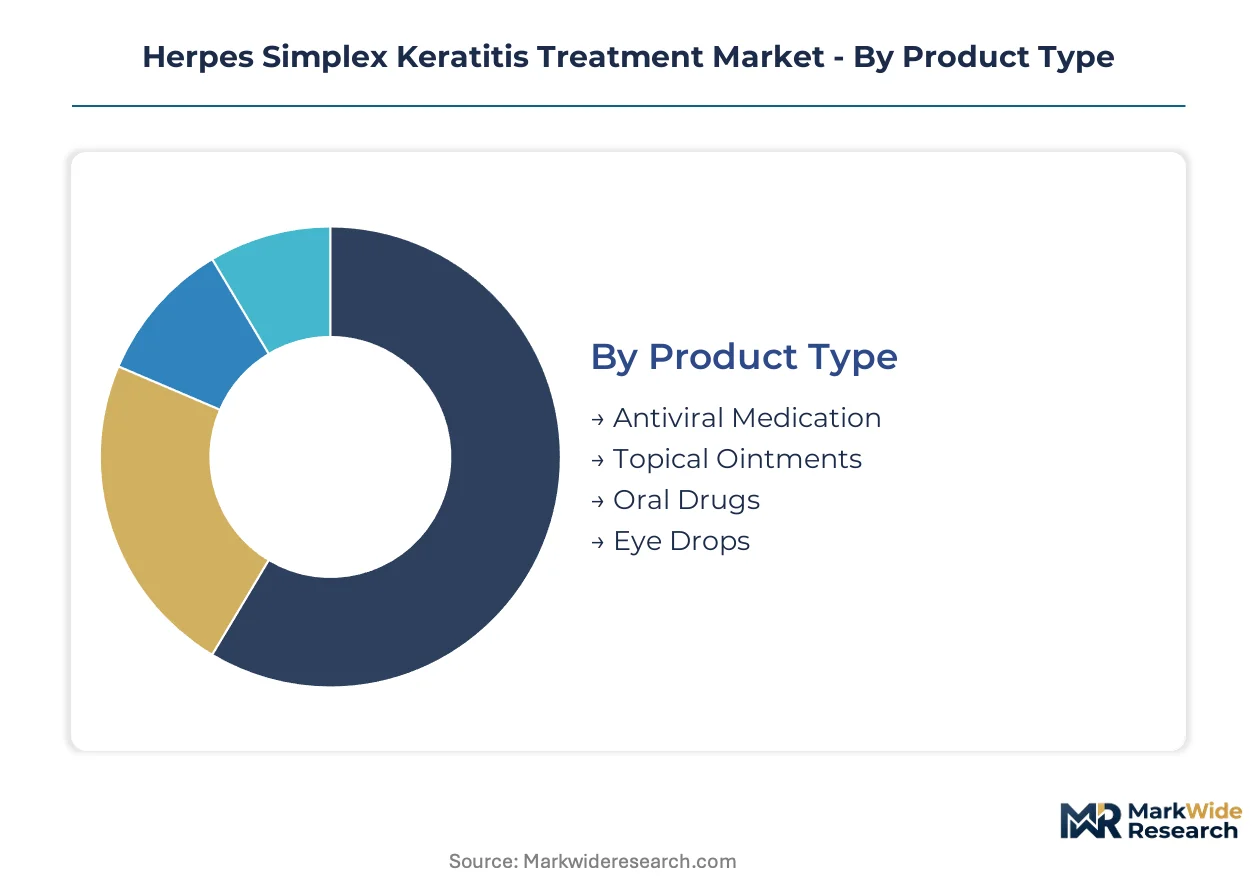
Segmentation in herpes simplex keratitis therapeutics reveals divergent margin architectures across delivery modes and care settings. Product type and delivery mode categories concentrate value capture, while end-user fragmentation shapes procurement dynamics.
Product Type:
Margin pools concentrate in formulations requiring specialized manufacturing capabilities and regulatory navigation for ocular bioavailability.
- Antiviral Medication:Systemic nucleoside analogs including acyclovir and valacyclovir suppress viral DNA polymerase activity. Demand clusters in the United States where oral prophylaxis protocols dominate uncomplicated epithelial disease management, though generic substitution compresses branded pricing power.
- Eye Drops:Topical formulations enable direct corneal surface drug deposition with minimized systemic exposure. Ophthalmology clinics in California and New York are expanding same-day dispensing for procedure-linked revenue capture, driving volume concentration in ambulatory settings.
- Topical Ointments:Semisolid preparations for overnight retention on periocular tissue.
- Oral Drugs:Tablet and capsule formulations for systemic viral suppression in stromal presentations.
The dominant share belongs to antiviral medication, while eye drops are gaining share fastest through clinic-based dispensing models.
End User:
Procurement authority fragments across integrated health systems and independent specialty practices with divergent reimbursement structures.
- Ophthalmology Clinics:Specialty practices concentrate advanced diagnostic and therapeutic decision-making for corneal disease. Large chain consolidations in Texas and Florida centralize purchasing power for intravitreal delivery systems, while independent California clinics invest in point-of-care PCR platforms.
- Hospitals:Academic medical centers manage complex necrotizing stromal cases requiring multidisciplinary coordination. Demand concentrates in tertiary referral networks where FDA-regulated trial access and specialized pharmacy compounding support novel formulation evaluation.
- Ambulatory Surgical Centers:Office-based surgical facilities certified for intravitreal administration.
- Home Care:Self-administered oral antiviral regimens for prophylaxis and maintenance therapy.
Ophthalmology clinics command the highest procedure-linked margins, though ambulatory surgical centers are expanding volume fastest through certification pathway streamlining.
Delivery Mode:
Technology differentiation in drug deposition depth creates tiered pricing structures across surface, systemic, and posterior segment targeting.
- Intravitreal:Direct vitreous cavity injection enables targeted drug reservoirs for recurrent posterior segment HSV-1 involvement. Japanese METI reimbursement incentives for minimally invasive delivery modes are accelerating adoption among corneal specialists seeking alternatives to systemic toxicity.
- Topical:Corneal surface application via drops, gels, or ointments for epithelial disease. Demand concentrates in European ophthalmology clinics where EMA MDR framework streamlines device-drug combination approvals, though REACH authorization requirements for novel excipients elevate toxicology documentation burdens.
- Oral:Systemic absorption for bilateral disease or stromal involvement beyond topical penetration.
- Injection:Subconjunctival or periocular depot administration for intermediate drug release kinetics.
Topical delivery retains the dominant prescription volume, while intravitreal administration shows the steepest expansion trajectory through specialty clinic procedure growth.
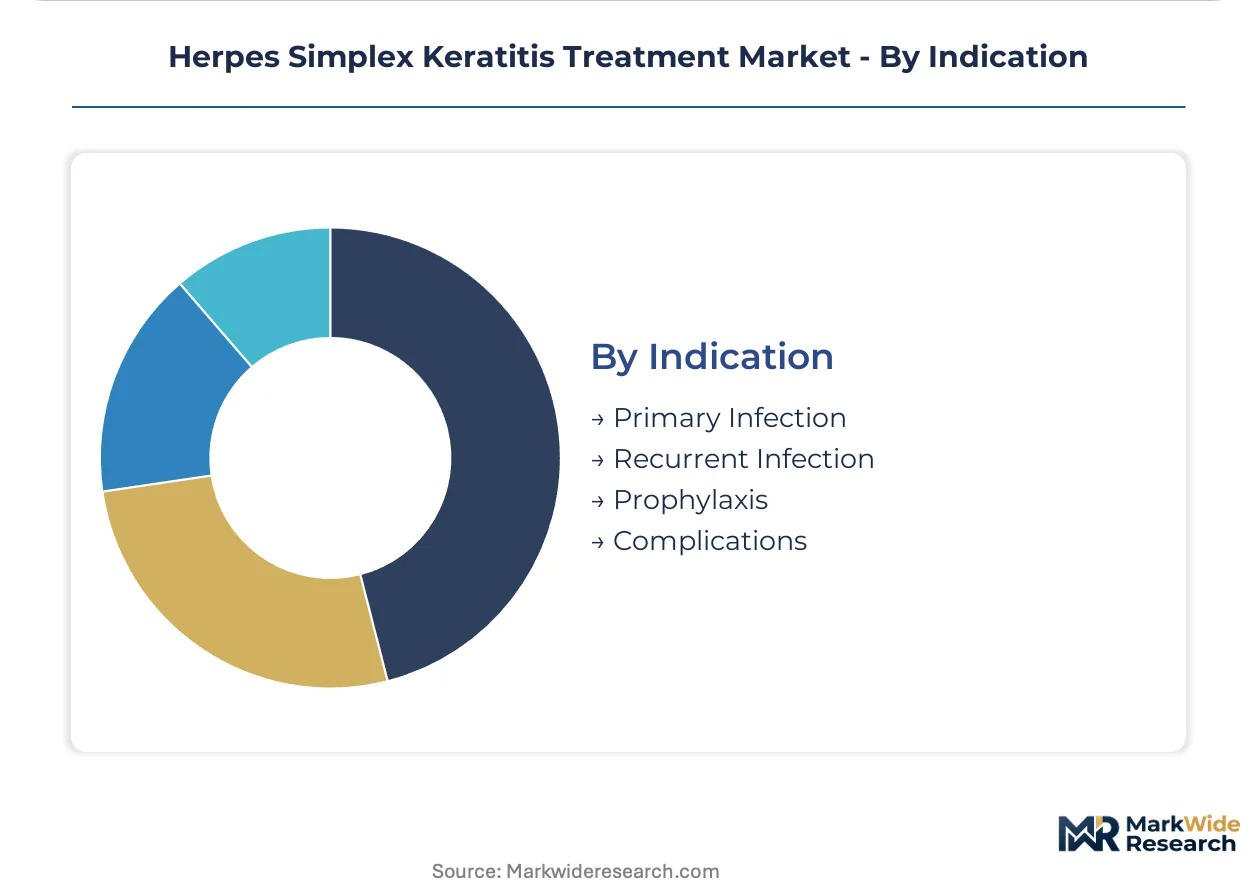
Indication:
Disease severity and recurrence history determine treatment intensity and duration, creating distinct value pools across the clinical spectrum.
- Recurrent Infection:Reactivation of latent HSV-1 in trigeminal ganglia requiring long-term prophylaxis or targeted intervention. Corneal specialists in academic medical centers are piloting sustained-release depot formulations to reduce dosing frequency and improve compliance in stromal keratitis management.
- Primary Infection:Initial ocular HSV-1 presentation typically managed with topical antiviral monotherapy. Demand concentrates in the United States where specialized corneal care infrastructure supports early viral load reduction protocols.
- Prophylaxis:Chronic suppressive therapy to prevent recurrence in high-risk patients.
- Complications:Advanced disease manifestations including corneal scarring, neovascularization, or secondary bacterial infection.
Recurrent infection captures the dominant therapeutic investment, while prophylaxis is climbing the fastest as long-term latency management protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-sensitive procurement dominates in India, creating a structural asymmetry that shapes formulation strategies across geographies.
United States
Specialized corneal care infrastructure and ophthalmology clinic consolidation drive premium uptake of intravitreal delivery systems. FDA ophthalmic guidance documents elevate clinical evidence thresholds for novel formulations. Large specialty chains in Texas and Florida centralize purchasing power for procedure-linked antiviral therapies.
Germany
Academic medical centers manage complex necrotizing stromal cases requiring multidisciplinary coordination. EMA MDR framework streamlines device-approval pathways for ophthalmic delivery systems. Industrial clusters in Baden-Württemberg host contract research organizations supporting toxicology documentation for REACH compliance.
Japan
An aging corneal patient base and METI reimbursement incentives for minimally invasive delivery modes accelerate depot-technology adoption. PMDA regulatory pathways prioritize locally conducted clinical trials for novel sustained-release formulations. Kanto region specialists pilot extended-release ganciclovir implants for recurrent stromal disease management.
India
API supply concentration in chemical hubs supports bulk acyclovir and valacyclovir production for global formulators. CDSCO regulatory frameworks align with WHO essential medicines listings for market access. Maharashtra and Gujarat manufacturing clusters face export-license volatility that exposes international formulators to supply disruptions.
Switzerland
Precision formulation capabilities and regulatory toxicology expertise attract small-cap developers lacking in-house capabilities. Swissmedic oversight of clinical trial authorization maintains rigorous multi-site coordination standards. Basel and Zurich host contract research organizations supporting European market entrants navigating REACH authorization requirements.
Herpes Simplex Keratitis Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with large-scale API manufacturers competing against specialty ophthalmic formulators for corneal specialist access. The market exhibits tiered consolidation where heritage antiviral developers face pressure from generic substitution and sustained-release innovators. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, regional generic manufacturers, and niche ocular delivery specialists. Competitive moves center on portfolio diversification into combination antiviral-anti-inflammatory platforms and geographic expansion through clinic chain partnerships.
Within the heritage antiviral tier, GlaxoSmithKline plc and Novartis AG occupy positions shaped by decades of nucleoside analog development. Bausch Health Companies Inc. represents the specialty ophthalmic formulator archetype, anchoring competitive dynamics around eye drop portfolios and corneal specialist relationships. Among India-based API-to-formulation players, Aurobindo Pharma Limited and Dr. Reddy's Laboratories Limited exemplify cost-leadership strategies targeting commoditized oral antiviral segments.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Bausch Health Companies Inc. |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Aurobindo Pharma Limited |
| Dr. Reddy's Laboratories Limited |
| Cipla Limited |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Generic valacyclovir commoditization is displacing branded topical alternatives across uncomplicated epithelial disease, simultaneously compressing margin pools in United States outpatient settings and redirecting API demand toward Indian bulk manufacturers. This substitution dynamic fragments pricing power between commoditized oral segments and protected intravitreal delivery tiers.
Pricing Analysis
The customization-premium spread separates procedure-linked intravitreal bundles from standard topical antiviral prescriptions. Three-tier pricing structure across premium, standard, and economy levels captures this divergence: premium tiers attach to FDA-regulated sustained-release implants with bundled diagnostic services; standard tiers cover branded topical ganciclovir gel; economy tiers absorb generic oral nucleoside analogs. Price differentiation stems from certification level—FDA ophthalmic guidance compliance elevates clinical trial costs—and volume scale, where large ophthalmology clinic chains extract procurement discounts. Cost compression in oral antiviral tiers is intensifying because Indian API manufacturers compete on valacyclovir bulk supply. Home care patients exhibit highest price sensitivity, while academic medical centers managing necrotizing stromal cases demonstrate lowest sensitivity due to outcome-focused procurement.
Supply Chain Analysis
Inventory lead-times for ganciclovir API stretch across 12-16 week cycles, exposing formulators to demand-planning volatility in recurrent infection seasons. Supply concentrates in Maharashtra and Gujarat chemical hubs for acyclovir and valacyclovir bulk production, with Swiss precision formulation capabilities anchoring European depot-technology finishing. Raw material dependencies center on nucleoside analog precursors, borosilicate glass vials for intravitreal packaging, and novel excipients requiring REACH authorization documentation. Single-source vulnerability characterizes extended-release implant polymer suppliers, where Japanese and German specialty chemical producers dominate. Distribution runs through ophthalmology clinic direct purchasing for procedure-linked therapies, while hospital-based procurement channels handle complex necrotizing cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as corneal specialists unbundle diagnostic and therapeutic reimbursement, creating niche entry points for point-of-care PCR platform providers and sustained-release formulation specialists.
For Market Incumbents: Shield oral antiviral franchises from generic substitution pressure by backward integration into Indian API supply partnerships that secure cost-competitive valacyclovir feedstock. Simultaneously deepen captive production of sustained-release ganciclovir implants to capture procedure-linked margin pools in consolidating ophthalmology clinic chains. FDA ophthalmic guidance thresholds for bioequivalence represent the primary regulatory threat extending competitor development timelines. For New Entrants and Emerging Players: Office-based laboratory testing infrastructure gaps in independent California and New York ophthalmology clinics present immediate white-space targets where incumbents under-serve with legacy referral models. Japan's aging corneal patient base and METI reimbursement incentives for minimally invasive delivery modes offer the most penetrable geography for depot-technology specialists. A go-to-market angle anchored in same-day PCR-to-treatment workflow integration unlocks clinic procurement decisions. For Investors and Strategic Acquirers: EMA MDR framework implementation reshapes the acquisition landscape by elevating device-approval documentation burdens that favor targets with existing ophthalmic delivery system regulatory dossiers. Long-term viability over the next decade hinges on portfolio diversification into combination antiviral-anti-inflammatory platforms addressing necrotizing stromal presentations. The signal to monitor is Japanese PMDA approval velocity for novel sustained-release formulations, indicating whether Kanto region pilot programs will scale to national reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Platform Development | Converging steroid-sparing protocols address unmet need in necrotizing stromal presentations without triggering viral reactivation. |
| Office-Based Intravitreal Certification | Ambulatory surgical center expansions in Texas and Florida unlock procedure-volume growth outside hospital settings. |
| Point-of-Care PCR Integration | California and New York regulatory frameworks for office-based laboratory testing accelerate operational model shifts. |
| REACH Compliance Outsourcing | Swiss and Dutch contract research organizations support small-cap formulators lacking in-house toxicology capabilities. |
| Japanese METI Reimbursement Alignment | Minimally invasive delivery mode incentives create entry pathways for depot-technology specialists in Kanto region. |
Research Methodology
Operator-level perspectives from corneal specialists, ophthalmology clinic procurement directors, hospital pharmacy compounding managers, and regulatory affairs leads anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA ophthalmic guidance documents, EMA MDR framework implementation records, ClinicalTrials.gov entries, and WHO essential medicines listings. Bottom-up prescription volume modeling and top-down therapeutic category sizing enabled cross-verification of segment-level estimates.
Sensitivity analysis tested forecast robustness across alternative scenarios for intravitreal adoption velocity and generic substitution rates. The analytical framework disaggregated volume and value outputs across product type, delivery mode, end user, and indication dimensions throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to historical prescription trends and forward-looking reimbursement policy assumptions. Industry-specific inputs included PMDA trial completion timelines and METI reimbursement incentive phase-in schedules.
Forecasts assume regulatory continuity in FDA ophthalmic guidance, EMA MDR device-approval pathways, and Japanese METI reimbursement frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Lazy Eye Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Macular Edema Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Artificial Iris Market