
 Galvanized Steel Coil Market | 2026-2036
Galvanized Steel Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanized Steel Coil Market Intelligence
High-strength automotive-grade coil is rotating toward center stage as OEMs chase lighter chassis materials. ArcelorMittal leverages its European R&D network to sustain premium-grade output. POSCO anchors Northeast Asian supply through integrated blast furnace operations. Tata Steel competes on construction-specialized widths across South Asian project pipelines.
Galvanized steel coil is zinc-coated flat-rolled carbon steel produced via hot-dip immersion or electro-deposition, typically carrying 30–600 grams of zinc per square meter to resist atmospheric corrosion in structural and fabricated applications. Hot-dip coil dominates volume flows into construction framing and roofing, while pre-painted variants command margin pools in appliance housings and architectural cladding. Electro-galvanized coil specializes in automotive body panels where surface finish precision outweighs coating thickness.
China's MEE enforces tightening emission caps on zinc smelting and steel galvanizing lines, reshaping plant upgrade cycles. India's BIS mandates revised coating weight standards for infrastructure-grade material, filtering import eligibility. The EU's CSRD extends disclosure requirements to steel supply chains, affecting market access for non-compliant exporters. Stakeholders must track how carbon border adjustments and coating specification divergence alter sourcing economics across major demand corridors.
Market Dynamics
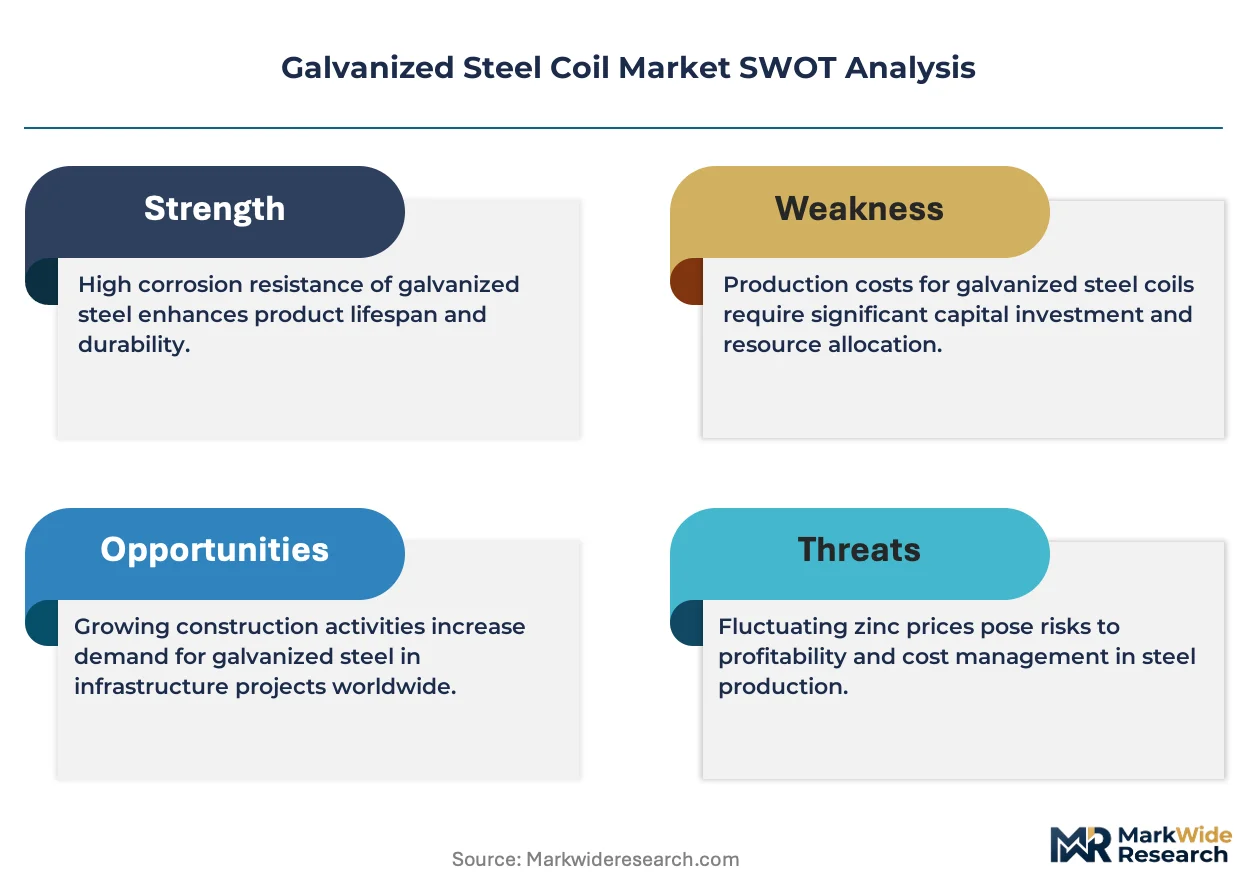
China's MEE emission caps on zinc smelting and steel galvanizing lines are forcing plant upgrade cycles across the galvanized steel coil supply base. This regulatory pressure compounds with India's BIS coating weight mandates and the EU's CSRD supply chain disclosure rules to reshape competitive economics.
Growth Catalysts
- Automotive lightweighting mandates:OEM chassis engineers specify high-strength galvanized grades to meet NHTSA CAFE standards and EU fleet emission targets. Coil producers with automotive-certified lines capture premium positioning.
- India's infrastructure build-out:National highway corridors and urban metro expansion under the PLI scheme for specialty steel generate concentrated demand for infrastructure-grade coated flat steel with specified zinc coating weights.
- Dual carbon goals in China:MEE enforcement tightens emissions standards for steel production, accelerating consolidation toward larger, cleaner galvanizing operations with captive zinc refining.
Market Restraints
- Zing price volatility:London Metal Exchange zinc futures swing with energy cost fluctuations and concentrate supply disruptions from Peruvian and Australian mining operations, compressing galvanizing margin predictability.
- Blast furnace concentration in Northeast Asia:Integrated steelmaking capacity clusters in specific coastal Chinese provinces and South Korean industrial zones, creating geographic supply vulnerability to weather events or power rationing.
- Aluminum-zinc alloy substitution:Building envelope architects in temperate climates specify Galvalume and aluminum-zinc-silicon coatings for extended corrosion resistance, eroding pure zinc-galvanized share in commercial roofing applications.
Strategic Opportunities
- Pre-painted coil penetration in Southeast Asian construction:Vietnam, Indonesia, and Philippines commercial builders adopt factory-applied color coatings to reduce on-site labor costs and accelerate project completion timelines.
- EU Green Deal carbon border adjustments:CBAM implementation creates competitive opening for low-carbon galvanized coil producers with verified Scope 1-3 emissions data and renewable-energy-powered galvanizing lines.
- Electro-galvanized precision for EV battery enclosures:Electric vehicle battery pack housings require thin, uniform zinc coatings with exact surface finish specifications that electro-galvanizing lines deliver versus hot-dip alternatives.
Industry Challenges
- Skilled galvanizing line operator scarcity:Experienced technicians who can manage bath chemistry, line speed, and coating weight consistency across varying substrate gauges command wage premiums and retention difficulty.
- CSRD compliance data infrastructure:EU-destined exporters must deploy supply chain carbon accounting systems and third-party verification protocols to meet disclosure timelines, requiring IT capex and auditor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanized Steel Coil Market |
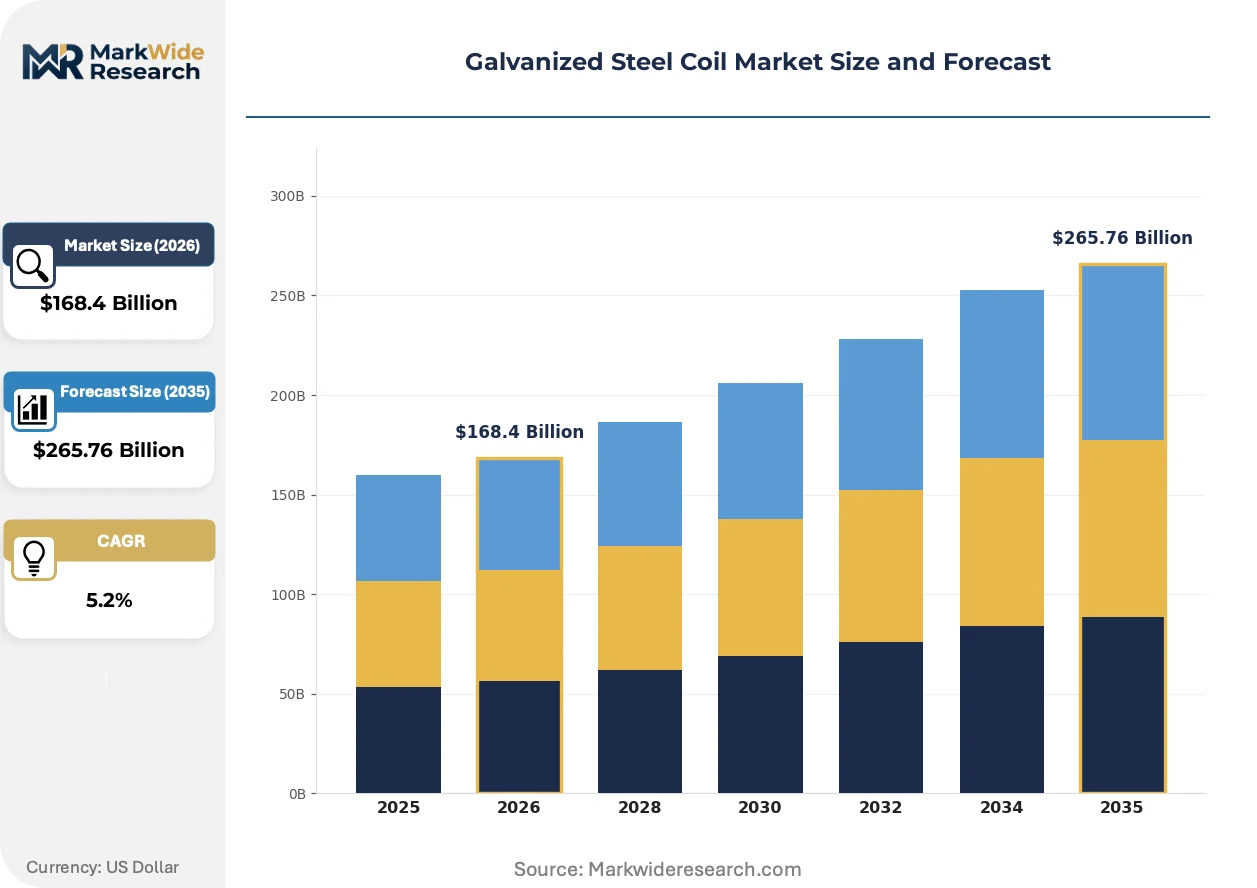
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $265.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot-Dip, Electro-Galvanized, Galvannealed, Pre-Painted End User: Construction, Automotive, Appliances, Infrastructure Coating Thickness: Less than 30 Microns, 30-60 Microns, 60-90 Microns, Above 90 Microns Distribution Channel: Direct Sales, Online, Wholesalers, Retailers |
| Companies Covered | Nippon Steel Corporation, Zibo Camel Material Co., Ltd., ArcelorMittal, Tianjin Runfei Trade Co., Ltd., Win Road International Trading Co. Ltd, China Baowu Steel Group, Tata Steel, Metal Zenith, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanized Steel Coil Market Strategic Shifts & Innovations
Active coating formulation advances and digital process control systems are compressing quality variance and enabling just-in-time production models across galvanized steel coil supply chains.
Zn-Mg-Al alloy coatings with enhanced cut-edge corrosion resistance are supplanting conventional pure zinc galvanizing in automotive underbody and chassis applications. European OEMs specify these magnesium-aluminum-zinc systems for salt-spray performance requirements. The technology is compressing market share for legacy hot-dip grades in corrosion-critical segments.
The EU's CSRD extends mandatory sustainability disclosure to steel supply chains, forcing non-EU exporters to deploy carbon accounting infrastructure. Industrial consequence includes procurement preference shifts toward suppliers with verified low-carbon production. Asian exporters to EU automotive and appliance manufacturers face the steepest compliance ramps.
Direct mill-to-fabricator digital platforms are consolidating fragmented construction steel procurement. Contractors in India and Southeast Asia bypass traditional distributor tiers through B2B marketplaces with real-time inventory visibility and cut-to-length specification. This channel compression is most visible in South Asian commercial building projects with predictable volume schedules.
Galvanized Steel Coil Market Segmentation
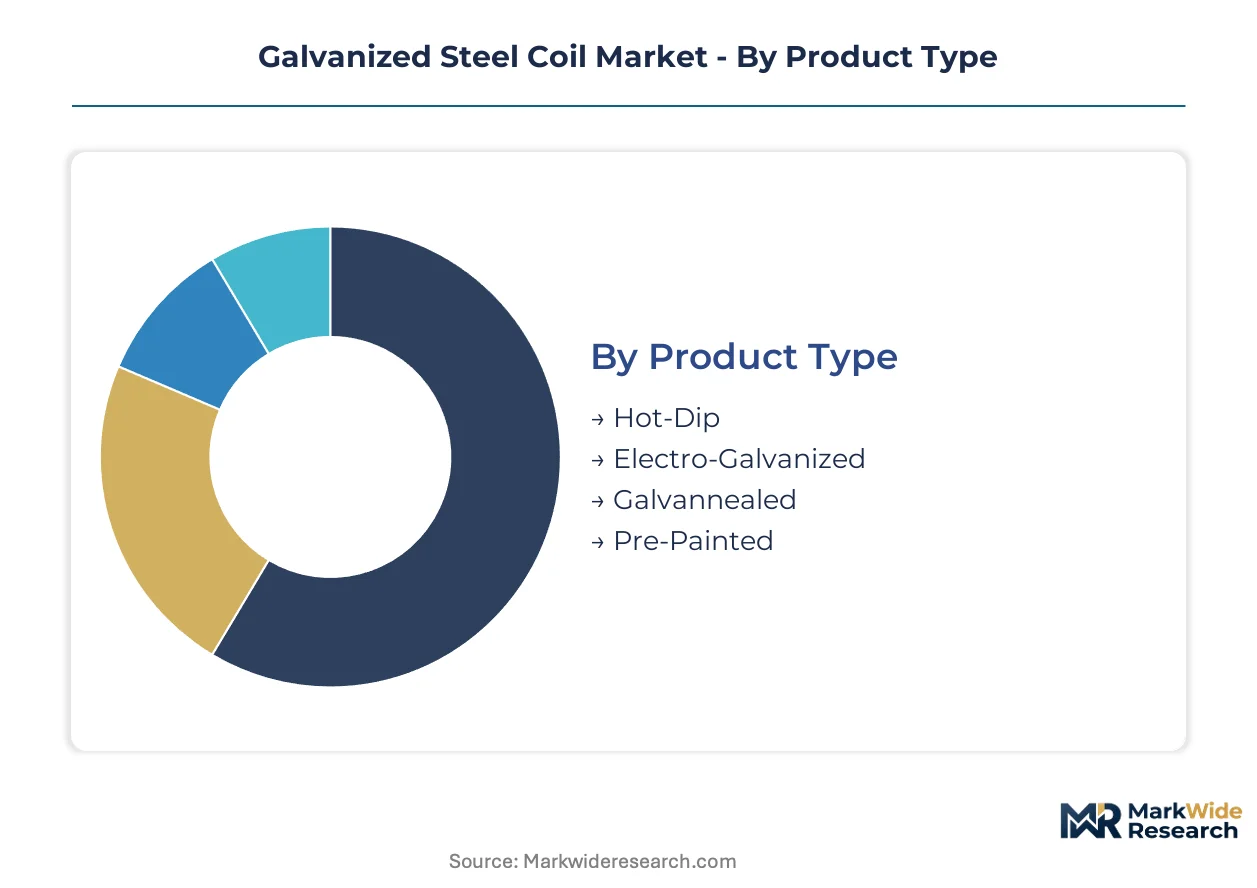
Segmentation in the galvanized steel coil market reveals how coating chemistry, end-use specifications, and procurement pathways create distinct margin pools. Channel dynamics and technical requirements fragment competitive positioning across product grades and customer workflows.
Product Type:
Channel flows diverge sharply between commodity-grade hot-dip coils routed through wholesalers and precision electro-galvanized material sold direct to automotive Tier-1 suppliers.
- Hot-Dip:Zinc immersion coating applied to steel strip at temperatures exceeding 450°C produces 30–600 g/m² protective layers. Construction framing and roofing contractors in Vietnam and Indonesia pull volume through distributor networks for standardized coil widths. India's National Highway Development Authority specifies hot-dip grades for bridge decking and guardrail posts.
- Electro-Galvanized:Electrolytic deposition achieves thinner, more uniform zinc coatings with superior surface finish control. Battery enclosure fabricators for electric vehicle platforms in South Korea and Germany specify electro-galvanized coil for precise weldability and corrosion resistance in thin-gauge applications.
- Galvannealed:Post-galvanizing heat treatment creates zinc-iron alloy layers optimized for paint adhesion. Automotive body panel stampers favor this grade for exterior skin applications requiring Class A surface quality.
- Pre-Painted:Factory-applied organic coatings eliminate field painting labor for commercial building envelopes. Southeast Asian project developers specify color-coated coil to compress construction schedules and reduce site workforce requirements.
Hot-Dip dominates installed base. Electro-Galvanized is where expansion concentrates.
End User:
Cost-tier stratification separates specification-grade automotive and appliance material from price-sensitive construction commodity flows.
- Construction:Structural framing, roofing systems, and cladding applications consume high-tonnage coil with standardized coating weights. Philippine commercial builders and Indian metro rail contractors drive concentrated demand for 275 g/m² zinc coating specifications through project-tender procurement channels.
- Automotive:OEM chassis engineers specify high-strength galvanized grades to meet NHTSA CAFE standards and EU fleet emission targets. Coil producers with automotive-certified lines capture premium positioning through direct mill-to-press-shop relationships.
- Appliances:Refrigerator and washing machine housings require pre-painted coil with specific color matching and formability characteristics. White goods manufacturers in China and Mexico source through contracted volume agreements with coating line operators.
- Infrastructure:Transmission towers, railway electrification structures, and port facilities demand heavy coating weights for extended service life. India's Dedicated Freight Corridor and Saudi giga-projects specify above-90-micron coating specifications for corrosion-critical installations.
Construction commands volume leadership. Automotive delivers margin premium.
Coating Thickness:
Application severity and environmental exposure dictate coating weight selection across end-use specifications.
- Less than 30 Microns:Thin electro-galvanized coatings serve interior automotive panels and appliance components where atmospheric exposure is minimal. Precision stampers in Germany and Japan specify this grade for cost-sensitive visible surfaces.
- 30-60 Microns:Standard hot-dip coating weights balance corrosion protection with formability for general construction applications. Residential roofing and light commercial framing in temperate climates specify this middle tier.
- 60-90 Microns:Enhanced protection for industrial and coastal environments where salt spray accelerates degradation. Australian mining infrastructure and UAE coastal developments specify this range for extended maintenance intervals.
- Above 90 Microns:Heavy zinc coatings for extreme exposure conditions including chemical processing facilities and marine structures. Offshore platform fabricators and desalination plant constructors require this specification tier.
30-60 Microns captures mainstream volume. Above 90 Microns is climbing the fastest.
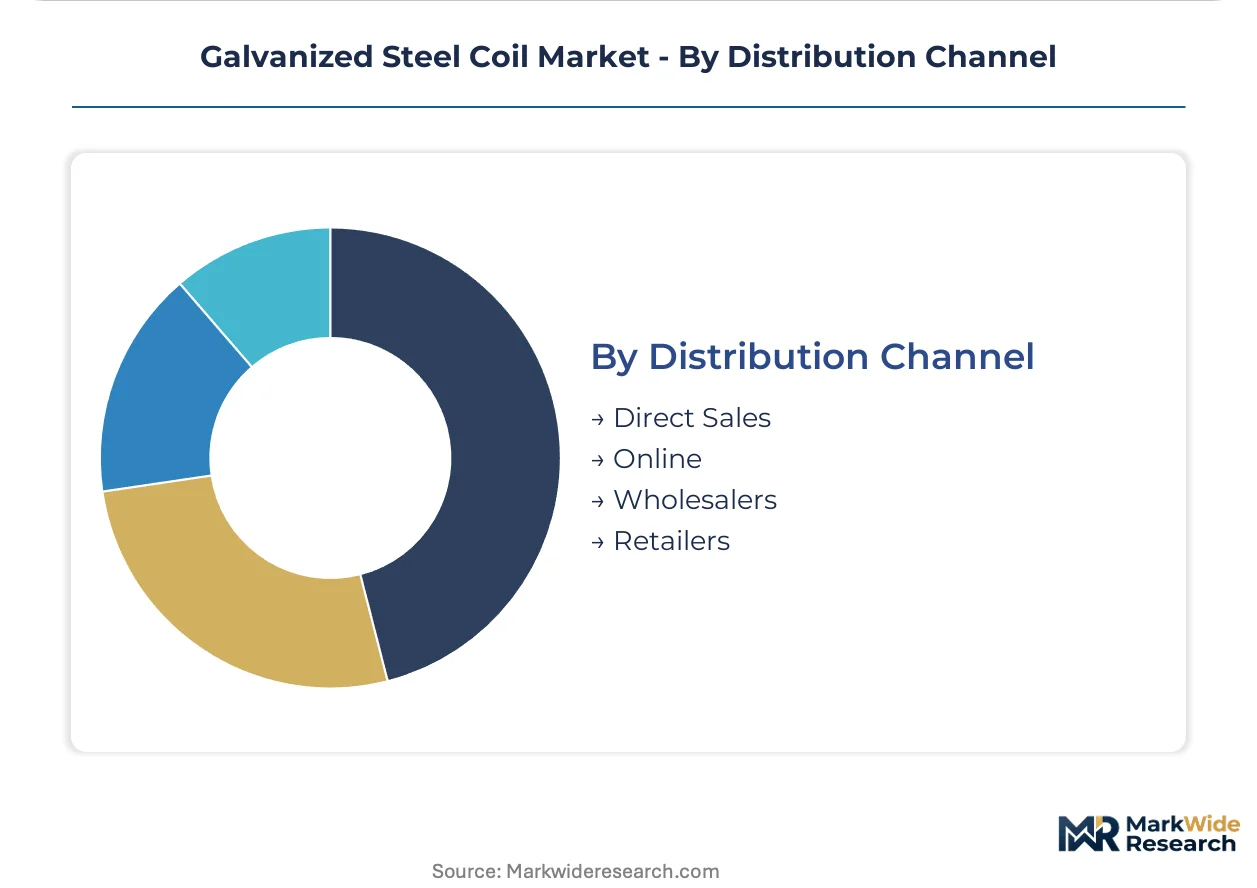
Distribution Channel:
Customer scale and specification complexity determine whether procurement flows through intermediaries or direct mill relationships.
- Direct Sales:Large-volume automotive OEMs and appliance manufacturers negotiate annual contracts with mill-direct pricing and technical service support. ArcelorMittal and POSCO maintain dedicated account teams for strategic direct customers.
- Online:B2B platforms with real-time inventory visibility and cut-to-length specification are compressing traditional distributor tiers. Indian and Southeast Asian contractors bypass stockists through digital procurement channels for predictable project schedules.
- Wholesalers:Regional steel distributors maintain coil inventory for construction contractors with intermittent, specification-variable demand. Wholesaler networks dominate fragmented building markets across secondary Chinese cities and South Asian urban peripheries.
- Retailers:Small-format hardware and building material outlets serve repair, maintenance, and light fabrication demand. This channel handles narrow-width slit coil and specialty sizes for job-shop metal fabricators.
Wholesalers anchor installed base throughput. Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated blast furnace capacity clusters along specific coastal Chinese provinces and South Korean industrial zones, creating geographic supply vulnerability to weather events or power rationing. Smelter-grade zinc refining and hot-dip galvanizing lines concentrate where coking coal meets ocean freight terminals.
China
National highway corridors and urban metro expansion generate concentrated demand for infrastructure-grade coated flat steel with specified zinc coating weights. The MEE enforces tightening emission caps on zinc smelting and steel galvanizing lines, reshaping plant upgrade cycles. Shandong and Jiangsu provinces host the densest concentrations of galvanizing capacity undergoing environmental compliance retrofits.
India
The National Highway Development Authority and Dedicated Freight Corridor project specify hot-dip grades for bridge decking, guardrail posts, and railway electrification structures. BIS mandates revised coating weight standards for infrastructure-grade material, filtering import eligibility. Maharashtra and Gujarat industrial corridors concentrate demand centers for coated flat steel under the PLI scheme for specialty steel.
South Korea
Electric vehicle battery pack housings require thin, uniform zinc coatings with exact surface finish specifications that electro-galvanizing lines deliver versus hot-dip alternatives. POSCO anchors Northeast Asian supply through integrated blast furnace operations. The Busan-Ulsan industrial zone maintains dedicated electro-galvanizing capacity serving automotive Tier-1 suppliers.
Vietnam
Commercial builders adopt factory-applied color coatings to reduce on-site labor costs and accelerate project completion timelines. Construction activity across Southeast Asian markets pulls demand upward for pre-painted coil. Ho Chi Minh City and Hanoi metro areas concentrate commercial building projects with predictable volume schedules bypassing traditional distributor tiers.
Germany
OEM chassis engineers specify high-strength galvanized grades to meet EU fleet emission targets and NHTSA CAFE standards for export platforms. The EU's CSRD extends disclosure requirements to steel supply chains, affecting market access for non-compliant exporters. The Ruhr industrial region and Bavarian automotive clusters maintain demand for automotive-certified galvanizing lines with premium positioning.
Galvanized Steel Coil Market Key Industry Players
Concentration sits with integrated steel producers operating captive galvanizing lines and regional specialists serving construction distributor networks. The vendor base spans multinational blast furnace operators, Chinese state-owned steel groups, and Southeast Asian trading houses with cut-to-length processing capabilities. Three archetypes dominate: scale-driven integrated producers with automotive certification, construction-commodity specialists competing on width availability and logistics, and trading intermediaries consolidating fragmented procurement across secondary markets. Competitive moves center on capacity expansion in low-carbon galvanizing and strategic partnerships with pre-painted coating line operators.
Among Asia-Pacific integrated producers, Nippon Steel Corporation and China Baowu Steel Group occupy positions within the scale-driven archetype serving automotive and infrastructure demand corridors. POSCO represents the Northeast Asian supply anchor with blast furnace-integrated operations. ArcelorMittal and Tata Steel exemplify the construction-specialized and automotive-certified tier competing across European and South Asian project pipelines respectively.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Zibo Camel Material Co., Ltd. |
| ArcelorMittal |
| Tianjin Runfei Trade Co., Ltd. |
| Win Road International Trading Co. Ltd |
| China Baowu Steel Group |
| Tata Steel |
| Metal Zenith |
| POSCO |
| Others |
Cost & Logistics Intelligence
CSRD disclosure mandates gate both supply qualification and price differentiation simultaneously for galvanized steel coil exporters to EU automotive and appliance manufacturers. Producers lacking verified Scope 1-3 emissions data and third-party verification protocols face procurement exclusion regardless of coating weight precision or surface finish quality.
Pricing Analysis
EU CSRD dictates the pricing tier structure across the galvanized steel coil market, separating premium-positioned automotive-certified lines from construction commodity grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with automotive OEM direct contracts commanding the top tier and distributor-sourced construction material occupying the bottom. Cost compression in standard-grade hot-dip coil is intensifying because aluminum-zinc alloy substitution erodes pure zinc-galvanized share in commercial roofing. Construction contractors sourcing through wholesaler networks exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize coating consistency over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites zinc concentrate flows from Australian and Peruvian mining operations to Northeast Asian smelting and galvanizing complexes. Geographic supply concentration centers on China, South Korea, and Japan, where integrated blast furnace operations cluster in coastal industrial zones. Raw material dependencies draw from coking coal, zinc concentrate, and hot-rolled substrate feeds. Single-source vulnerability concentrates in Shandong and Jiangsu provinces where environmental compliance retrofits are forcing capacity consolidation. Distribution runs through direct mill relationships for automotive OEMs, B2B platforms for Southeast Asian construction procurement, and regional wholesalers for fragmented building markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and national infrastructure authorities with specification-setting authority, fragmenting traditional distributor influence. Large-scale project tendering in India and Southeast Asia concentrates procurement decisions among fewer actors with volume commitment leverage.
For Market Incumbents: Compound defensive positioning by securing automotive certification renewals ahead of EU CSRD enforcement timelines and deepening backward integration into captive zinc refining to buffer London Metal Exchange volatility. Aluminum-zinc alloy substitution in commercial roofing and skilled operator scarcity across galvanizing lines represent parallel threats requiring R&D investment in Zn-Mg-Al coating formulations and technical training pipeline development. For New Entrants and Emerging Players: Anchor in pre-painted coil penetration across Vietnam, Indonesia, and Philippines commercial construction, where factory-applied color coatings compress project schedules and distributor bypass through B2B platforms is most advanced. The most penetrable white-space sits in electro-galvanized precision supply for South Korean and German EV battery enclosure fabricators, with go-to-market execution through direct technical sales to Tier-1 automotive suppliers. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape toward low-carbon galvanized coil producers with renewable-energy-powered galvanizing lines and verified emissions data infrastructure. Long-term viability favors integrated producers with automotive certification and construction-specialized width capabilities across both premium and commodity tiers. The signal to watch is CBAM implementation pace and procurement preference shifts among EU-destined exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Galvanizing Line Investment | CBAM compliance secures EU automotive and appliance market access against carbon-intensive competitors. |
| Pre-Painted Coil Capacity Expansion | Southeast Asian construction demand for factory-applied coatings accelerates project completion timelines. |
| Automotive Certification Renewal | OEM chassis specifications for high-strength grades sustain premium positioning through direct mill relationships. |
| Zn-Mg-Al Coating R&D Partnership | European OEM salt-spray requirements displace legacy hot-dip grades in corrosion-critical underbody applications. |
| B2B Platform Channel Development | Digital procurement penetration in India and Vietnam compresses traditional distributor tiers for predictable volume schedules. |
Research Approach
A spread of perspectives from galvanizing line operators, automotive Tier-1 procurement managers, construction project contractors, and zinc smelting technical directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings of listed steel producers, BIS coating weight standard documentation, and EU CSRD regulatory texts. Bottom-up volume estimates from coating line capacity and top-down demand triangulation from construction project pipelines and automotive production schedules were cross-referenced for consistency.
Segmentation dimensions modeled include coating chemistry type, end-use specification tier, coating thickness category, and distribution channel pathway across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules throughout the forecast period. Industry-specific forecast inputs incorporated MEE emission cap enforcement trajectories, PLI scheme disbursement timelines for Indian specialty steel, and EV battery enclosure specification evolution from automotive platform engineers.
Material uncertainties — zinc price volatility from energy cost fluctuations, MEE enforcement intensity variations, and aluminum-zinc substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pace and infrastructure project execution rates. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and coating specification divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper Azoles Market
Metals
Aluminum Extrusion Market
Metals
Scandium Market
Metals
Ferrochrome Market
Metals
Qatar Metalworking Market
Metals
Global Titanium Metal Market
Metals
Global Brass Rods Market
Metals
Anodized Titanium Market
Metals
Global Tantalum Market
Metals
Platinum Compounds Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
US and Mexico Stainless Steel Market
Metals
Refined Nickel Market
Metals
Silico Manganese Market
Metals
Hafnium Foil Market
Metals
North America Metal Casting Market