
 Anodized Titanium Market | 2026-2036
Anodized Titanium Market Size, Share, and Industry Trends Forecast 2026-2036
Anodized Titanium Market Analysis
Skilled anodizing technicians with vacuum-chamber and color-specification expertise is bifurcating the competitive landscape into premium-certified shops and commodity finishers. AOTCO Metal Finishing leverages its AS9100 and ISO 13485 credentials to anchor aerospace and medical contracts. TIODIZE sustains proprietary Tiodizing processes that differentiate its corrosion-resistant coatings for defense and industrial clients. Techmetals competes on geographic reach, operating multiple facilities that control regional turnaround times for Midwest manufacturers.
Anodized titanium refers to electrolytically oxidized titanium substrates where controlled oxide layer thickness—typically 5–25 micrometers—generates interference colors, dielectric properties, and enhanced wear resistance without altering base-metal biocompatibility. The process serves industries requiring durable, non-toxic, electrically insulated surfaces that withstand saline or bodily-fluid exposure. Sheets and tubes dominate product-type revenue, with tubes commanding margin premiums in vascular-stent and hydraulic-line applications where internal-bore uniformity matters. Medical-grade titanium alloys represent the fastest-growing grade category, as FDA and EMA biocompatibility filings increasingly specify anodized surfaces for permanent implant contact exceeding thirty days.
EPA hazardous-air-pollutant rules for chromium and cadmium alternatives are redirecting automotive and aerospace finishing toward anodized titanium chemistries. REACH Annex XVII restrictions on hexavalent chromium, plus EU Medical Device Regulation surface-characterization requirements, are elevating documentation burdens for European suppliers. ISO 10993 biocompatibility testing and ASTM F67/F136 material standards govern medical-device market access across multiple jurisdictions. Stakeholders must monitor regulatory divergence between EPA-permitted electrolyte formulations and ECHA-substance-restriction trajectories when siting new capacity or qualifying dual-source suppliers.
Market Dynamics
REACH Annex XVII restrictions on hexavalent chromium and EPA hazardous-air-pollutant rules are redirecting automotive and aerospace finishing contracts toward anodized titanium suppliers with certified electrolyte formulations. This regulatory compression is bifurcating the competitive landscape into premium-certified shops and commodity finishers.
Growth Catalysts
- EU Medical Device Regulation surface-characterization requirements:EMA biocompatibility filings increasingly specify anodized titanium surfaces for permanent implants exceeding thirty days, expanding medical-grade alloy demand.
- Saline-exposure durability specifications:Vascular-stent and hydraulic-line applications require internal-bore uniformity that anodized titanium tubes deliver, commanding margin premiums over sheet alternatives.
- German precision engineering clusters:Aerospace supply chains in Bavaria and Baden-Württemberg anchor premium-grade consumption, concentrating procurement among AS9100-certified finishers.
Market Restraints
- Electrolyte chemistry volatility:Sulfuric acid and phosphoric acid input costs fluctuate with industrial chemical supply chains, compressing batch-processing margins for small-batch medical finishers.
- Vacuum-chamber technician scarcity:Skilled operators capable of color-specification control number fewer than five hundred across North America and Europe, capping certified-shop expansion.
- Plasma electrolytic oxidation substitution:PEO coatings achieve thicker oxide layers on magnesium alloys for automotive lightweighting, threatening titanium's position in non-implant structural applications.
Strategic Opportunities
- Indian orthopedic implant manufacturing:CDSCO regulatory harmonization with ISO 10993 standards is opening contract-finishing opportunities for European-certified suppliers establishing technical partnerships with Mumbai and Hyderabad device makers.
- Additive manufacturing convergence:Electron-beam-melted titanium lattice structures require post-build anodizing for osseointegration surfaces, creating integrated workflow demand from medical 3D-printing service bureaus.
- US Inflation Reduction Act domestic content incentives:Aerospace and defense procurement preferences for domestically processed critical materials favor new anodizing capacity in Ohio and Texas industrial corridors.
Industry Challenges
- Dual-source qualification timelines:FDA and EMA biocompatibility dossiers require eighteen-to-twenty-four-month validation cycles for secondary anodizing suppliers, delaying supply chain diversification.
- Legacy ERP integration with process-control systems:Small-batch finishers struggle to connect vacuum-chamber data logging to customer quality-management platforms, blocking aerospace tier-one supplier status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anodized Titanium Market |
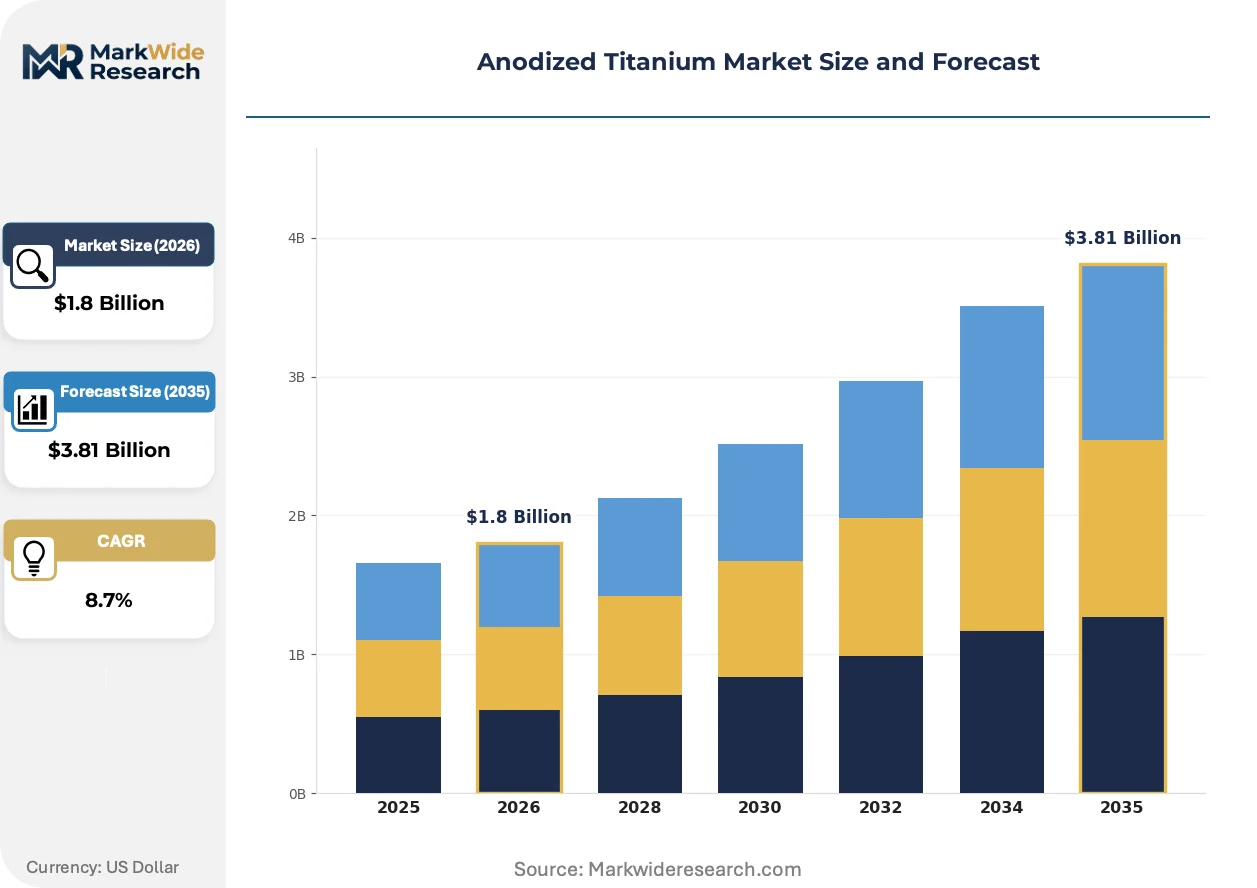
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Bars, Tubes, Foils End User: Aerospace, Medical Devices, Automotive Components, Consumer Electronics Grade: Commercially Pure, Titanium Alloys, Aerospace Quality, Medical Grade Application: Surface Treatment, Structural Components, Corrosion Resistance, Biocompatibility |
| Companies Covered | AOTCO Metal Finishing, HPL Stampings Inc., Techmetals, Leatherwood Manufacturing, Light Metals Coloring, TIODIZE, G & J Steel & Tubing, SIFCO ASC, Aalberts Surface Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anodized Titanium Market Emerging Trajectories
Pulse-anodizing algorithms and real-time spectroscopic color monitoring are compressing specification variance and enabling lot-size-one medical device production. These precision advances are reshaping competitive differentiation away from volume scale toward process-control sophistication.
Nanosecond-pulse anodizing with closed-loop thickness interferometry is supplanting conventional DC anodizing in orthopedic implant finishing. Stryker and Zimmer Biomet procurement teams now mandate pulse-process certification for new vendor qualification. This technology compression is collapsing acceptable color-variation tolerances from ±5 nanometers to ±1.5 nanometers, disqualifying legacy DC-line operators from premium medical contracts.
REACH authorization timelines for chromic acid alternatives are accelerating electrolyte-reformulation investments among European finishers. The ECHA sunset date for hexavalent chromium in aerospace conversion coatings forces qualified-supplier-list updates across Airbus and Safran supply chains. German anodizing shops with pre-approved sulfuric-boric acid blends capture redirected qualification resources while competitors await substance-evaluation outcomes.
Certificate-of-analysis bundling with dimensional inspection data is replacing traditional lot-acceptance sampling for vascular-stent tubing orders. Boston Scientific and Medtronic procurement teams now require anodizing suppliers to deliver statistical-process-control charts with each shipment, shifting quality-assurance liability upstream. This documentation compression is most visible in Minnesota and Massachusetts medical-device manufacturing corridors where FDA inspection intensity concentrates.
Anodized Titanium Market Segmentation
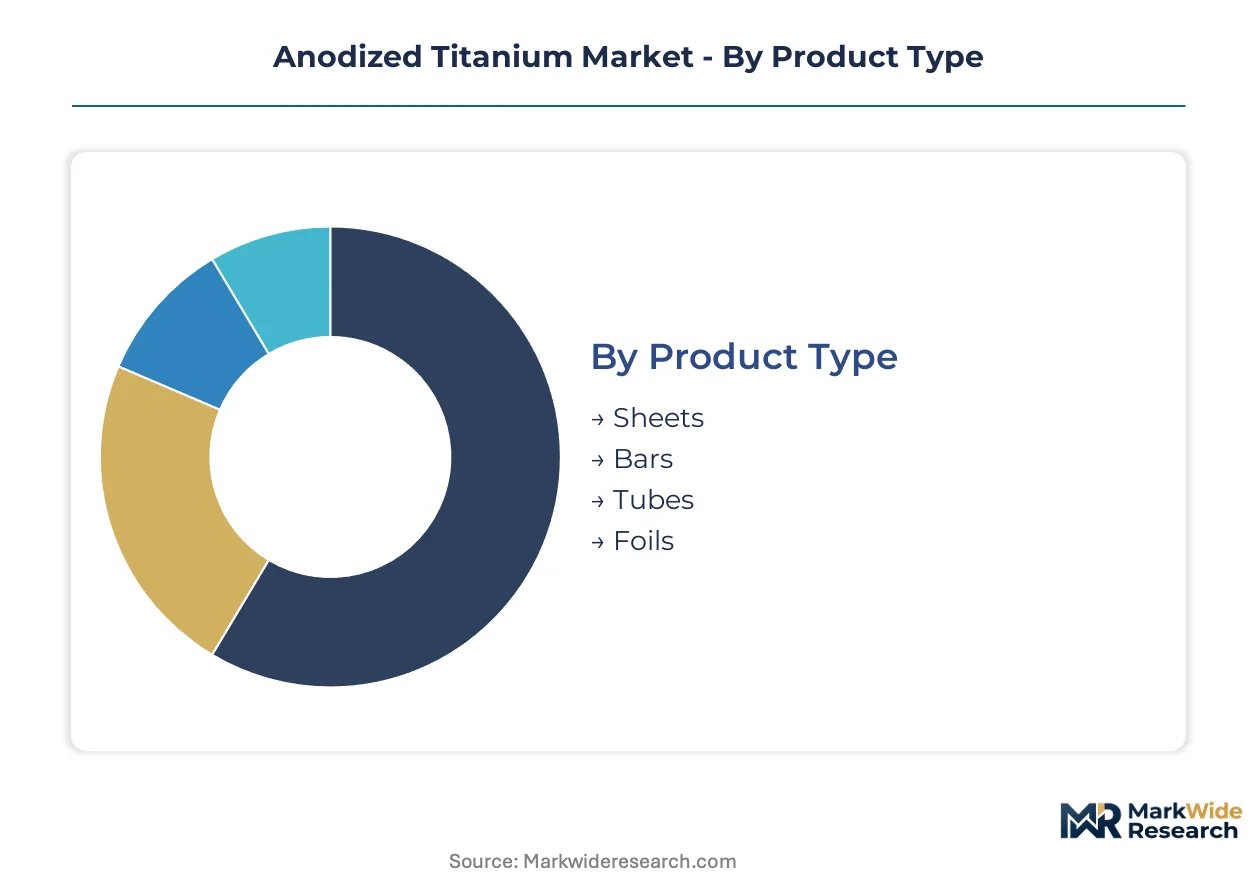
Anodized titanium procurement patterns diverge sharply across product geometries and end-use specifications. Medical device OEMs prioritize biocompatibility-certified grades with nanometer-level oxide uniformity, while aerospace buyers weight lot-traceability and AS9100 documentation above per-unit cost.
Product Type:
Margin pools concentrate in tubular geometries where internal-bore anodizing demands vacuum-chamber expertise and real-time thickness monitoring.
- Tubes:Vascular-stent and hydraulic-line applications require interference-color uniformity across internal diameters. Bavarian aerospace supply chains and Minnesota medical-device corridors command premium pricing for bore-concentricity certification.
- Sheets:Large-format architectural and consumer-electronics substrates generate volume throughput at compressed margins. German precision-engineering clusters anchor premium-sheet consumption for aircraft interior panels.
- Bars:Orthopedic implant blanks and aerospace fasteners dominate bar-stock anodizing, with Stryker and Zimmer Biomet procurement teams mandating pulse-process certification.
- Foils:Micro-thin substrates for neural electrodes and battery current collectors require specialized handling equipment; CDSCO-harmonized Indian manufacturers represent expanding demand.
Tubes hold installed capacity. Sheets are rotating up the share rankings.
End User:
Application complexity and regulatory burden determine customer-tier profitability across verticals.
- Medical Devices:Permanent implants exceeding thirty days of bodily contact drive ISO 10993 biocompatibility testing and FDA/EMA dual-dossier preparation. Pulse-anodizing certification now gates vendor qualification for Stryker and Zimmer Biomet supply chains.
- Aerospace:REACH Annex XVII hexavalent-chromium restrictions redirect Airbus and Safran conversion-coating contracts toward sulfuric-boric acid anodizing formulations. AS9100-certified German finishers capture redirected qualification resources.
- Automotive Components:EPA hazardous-air-pollutant rules for chromium alternatives favor anodized titanium in lightweighting applications; plasma electrolytic oxidation on magnesium alloys threatens structural non-implant demand.
- Consumer Electronics:Color-specification control for premium device housings requires skilled vacuum-chamber technicians; fewer than five hundred qualified operators exist across North America and Europe.
Medical Devices holds installed capacity. Aerospace is rotating up the share rankings.
Grade:
Certification depth and lot-traceability documentation separate pricing tiers within grade categories.
- Medical Grade:ASTM F67/F136 material standards govern permanent implant access; EMA filings increasingly specify anodized surfaces for osseointegration interfaces. Boston Scientific and Medtronic procurement teams now require statistical-process-control charts with each shipment.
- Aerospace Quality:Lot-acceptance sampling replacement with certificate-of-analysis bundling shifts quality-assurance liability upstream to anodizing suppliers. German shops with pre-approved electrolyte blends capture Airbus supply-chain updates.
- Titanium Alloys:Ti-6Al-4V and Ti-6Al-7Nb substrates dominate orthopedic and aerospace structural applications; additive-manufacturing convergence creates post-build anodizing demand from electron-beam-melted lattice structures.
- Commercially Pure:Grade 1 and Grade 2 titanium serve cost-sensitive industrial and architectural finishes; sulfuric acid input-cost volatility compresses batch-processing margins.
Medical Grade holds installed capacity. Aerospace Quality is rotating up the share rankings.
Application:
Functional performance requirements dictate process-control investment levels and customer stickiness.
- Biocompatibility:Surface characterization for permanent implants requires nanometer-level oxide-thickness control; nanosecond-pulse anodizing with closed-loop interferometry supplants conventional DC processing.
- Corrosion Resistance:Saline-exposure durability specifications for marine and chemical-processing equipment favor proprietary Tiodizing processes; defense and industrial clients pay formulation premiums.
- Surface Treatment:Decorative and functional finishing for consumer goods and architectural elements competes on regional turnaround times; Techmetals' multi-facility geographic reach serves Midwest manufacturers.
- Structural Components:Load-bearing aerospace and automotive applications balance weight reduction against fatigue-performance retention; US Inflation Reduction Act domestic-content incentives favor Ohio and Texas processing capacity.
Biocompatibility holds installed capacity. Corrosion Resistance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA biocompatibility filings increasingly specify anodized titanium surfaces for permanent implants exceeding thirty days. REACH Annex XVII restrictions on hexavalent chromium redirect aerospace finishing contracts toward certified suppliers. EPA hazardous-air-pollutant rules for chromium alternatives favor anodized titanium chemistries in automotive and defense applications.
United States
Stryker and Zimmer Biomet procurement teams mandate pulse-process certification for new vendor qualification. FDA biocompatibility dossiers require eighteen-to-twenty-four-month validation cycles for secondary anodizing suppliers. Minnesota and Massachusetts medical-device manufacturing corridors concentrate FDA inspection intensity and Boston Scientific procurement requirements.
Germany
Airbus and Safran supply chains redirect conversion-coating contracts toward sulfuric-boric acid anodizing formulations. ECHA sunset dates for hexavalent chromium in aerospace conversion coatings force qualified-supplier-list updates. Bavarian and Baden-Württemberg precision-engineering clusters anchor premium-grade consumption among AS9100-certified finishers.
India
CDSCO regulatory harmonization with ISO 10993 standards opens contract-finishing opportunities for European-certified suppliers. Mumbai and Hyderabad device makers expand orthopedic implant manufacturing capacity. Domestic technical partnerships with certified European finishers accelerate biocompatibility dossier preparation for export markets.
United Kingdom
EMA filings increasingly specify anodized surfaces for osseointegration interfaces in permanent implants. REACH compliance documentation burdens elevate certification requirements for surface-treatment suppliers. Aerospace supply chains in Midlands and Southeast England concentrate defense and commercial aviation finishing demand.
Japan
METI industrial standards govern precision finishing requirements for medical-device exports. PMDA biocompatibility testing protocols align with FDA and EMA dossier structures for dual-market access. Kansai and Chubu industrial corridors concentrate titanium processing expertise for orthopedic and dental implant applications.
Anodized Titanium Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the anodized titanium market. Premium-certified shops with AS9100 and ISO 13485 credentials capture aerospace and medical contracts, while commodity finishers compete on regional turnaround times. The competitive landscape stratifies into certification-driven premium operators, proprietary-process defenders, and geographic-reach players. Dominant competitive moves include electrolyte-reformulation investments ahead of REACH authorization timelines and pulse-anodizing technology licensing for medical-grade qualification.
Among US-based finishers, AOTCO Metal Finishing and TIODIZE occupy positions on the premium-certification vector. AOTCO leverages AS9100 and ISO 13485 credentials to anchor aerospace and medical contracts. TIODIZE exemplifies the proprietary-process archetype through differentiated corrosion-resistant coating formulations. Techmetals represents the geographic-reach strategy, with multi-facility operations controlling regional turnaround times for Midwest manufacturers. These three players illustrate how certification depth, process exclusivity, and logistics density serve as alternative bases for competitive position.
| Leading Market Players |
|---|
| AOTCO Metal Finishing |
| HPL Stampings Inc. |
| Techmetals |
| Leatherwood Manufacturing |
| Light Metals Coloring |
| TIODIZE |
| G & J Steel & Tubing |
| SIFCO ASC |
| Aalberts Surface Technologies |
| Others |
Supply Flow & Price Mechanics
AS9100 and ISO 13485 certification regimes simultaneously gate supply qualification and enable price differentiation across medical and aerospace tiers, compressing uncertified finishers into commodity margins while premium shops capture documentation premiums.
Pricing Analysis
Bavarian finishers command 40-60% premiums over Midwest US counterparts for identical tube geometries, reflecting AS9100 audit density and ECHA pre-approved electrolyte status. Three-tier pricing structure across premium-certified, standard-industrial, and economy-architectural levels separates pulse-anodizing medical grades from DC-line commodity output. Pricing pressure stems from sulfuric acid input-cost volatility squeezing small-batch medical finishers with limited forward-contract coverage. Automotive and industrial buyers exhibit highest price sensitivity, while Stryker and Zimmer Biomet procurement teams accept premium pricing for nanometer-level oxide uniformity.
Supply Chain Analysis
Strait of Malacca titanium sponge transit underwrites German and US anodizing feedstock security, with disruption risk elevating spot premiums for non-contracted mills. Supply concentrates in China, Japan, and Russia for titanium sponge reduction, while Germany, the United States, and India host downstream anodizing capacity. Batch-processing draws from sulfuric acid, phosphoric acid, and boric acid chemistries tethered to industrial chemical supply chains. Single-source vulnerability concentrates in vacuum-chamber equipment manufacturers, with fewer than three qualified suppliers globally. Distribution runs through direct OEM contracts for medical and aerospace tiers, with regional job-shop networks serving industrial and architectural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anodized titanium sits in early-cycle expansion as REACH Annex XVII enforcement redirects hexavalent-chromium aerospace contracts toward certified sulfuric-boric acid formulations, accelerating premium-grade penetration.
For Market Incumbents: Compound certification depth by adding ISO 10993 testing capabilities in-house, reducing eighteen-to-twenty-four-month dual-dossier preparation cycles that currently cede share to integrated competitors. Defend against plasma electrolytic oxidation substitution in automotive structural applications by anchoring titanium's fatigue-performance advantage through joint R&D with electron-beam-melting service bureaus. Vertical integration into electrolyte formulation—specifically pre-approved sulfuric-boric acid blends—captures ECHA redirect opportunities before competitors complete substance-evaluation outcomes. For New Entrants and Emerging Players: Additive-manufacturing post-processing services represent an under-served layer where incumbent anodizing shops lack electron-beam-melted lattice-structure workflow integration. Target Mumbai and Hyderabad orthopedic implant manufacturers seeking CDSCO-harmonized European technical partnerships for biocompatibility dossier acceleration. Lead with pulse-anodizing certification as the go-to-market wedge, disqualifying legacy DC-line competitors from Stryker and Zimmer Biomet vendor lists. For Investors and Strategic Acquirers: ECHA's hexavalent-chromium sunset timeline reshapes the acquisition landscape toward German and US shops with pre-approved electrolyte blends and existing Airbus or Safran qualified-supplier-list placement. Long-term viability over a five-to-ten-year window favors vertically integrated mid-cap specialists with captive titanium sponge sourcing and in-house vacuum-chamber fabrication capabilities. Watch for nanosecond-pulse anodizing equipment manufacturers as the inflection signal—their order backlogs indicate medical-grade capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pulse-Anodizing Certification Investment | Stryker and Zimmer Biomet procurement teams now mandate this process for vendor qualification. |
| Electrolyte-Reformulation Partnership | ECHA pre-approved sulfuric-boric acid blends capture redirected Airbus and Safran qualification resources. |
| Additive Manufacturing Integration | Electron-beam-melted titanium lattice structures require post-build anodizing for osseointegration surfaces. |
| Indian Technical Partnership | CDSCO-harmonized Mumbai and Hyderabad device makers accelerate biocompatibility dossier preparation for export markets. |
| Vacuum-Chamber Technician Pipeline | AS9100-certified shops face expansion caps with fewer than five hundred qualified operators across North America and Europe. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with biomedical engineers at Stryker and Zimmer Biomet, procurement managers at Boston Scientific and Medtronic, anodizing shop floor supervisors, and regulatory affairs leads navigating FDA and EMA dossier preparation. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, ISO 10993 biocompatibility testing protocols, and ASTM F67/F136 material standards. Bottom-up capacity assessments triangulated against top-down aerospace and medical device production forecasts.
Across the analysis window, the forecasting framework modeled product-type segmentation across tubes, sheets, bars, and foils; end-user verticals spanning medical devices, aerospace, automotive, and consumer electronics; and grade-tier differentiation between medical-grade, aerospace-quality, titanium alloys, and commercially pure substrates. CAGRs were derived from electrolyte chemistry adoption curves, regulatory enforcement timelines, and OEM procurement pattern shifts. Industry-specific inputs included REACH authorization trajectory for chromic acid alternatives and US Inflation Reduction Act domestic-content incentive uptake.
Underlying assumptions cover sustained REACH Annex XVII enforcement, EPA hazardous-air-pollutant rule continuity, and vacuum-chamber technician training pipeline expansion, with deviation risk concentrated in electrolyte input-cost volatility and plasma electrolytic oxidation technology advancement. Practitioners should keep alternative scenarios live as ECHA substance-evaluation outcomes and CDSCO regulatory harmonization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Russia Metal Fabrication Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
High Purity Tungsten Market
Metals
Copper Azoles Market
Metals
Expanded Metal Foils Market
Metals
Cold Drawn Wire Market
Metals
Beryllium Copper Plate Market
Metals
Electrolytic Manganese Metal Market
Metals
Lithium Foil Market
Metals
High Purity Aluminium Market
Metals
Bearing Steel Market
Metals
India Steel Market
Metals
Base Metals Market
Metals
Beryllium Market
Metals
High Purity Pig Iron Market
Metals
Recycled Metal Market