
 Silico Manganese Market | 2026-2036
Silico Manganese Market Size, Share, and Industry Trends Forecast 2026-2036
Silico Manganese Market Intelligence
Smelter capacity expansion in key producing nations like South Africa and India is broadening the supply base beyond traditional centers. This shift challenges the long-standing dominance of Chinese producers. Ferroglobe PLC leverages its global manufacturing footprint to serve diverse regional steel markets. Tata Steel Limited sustains a competitive edge through its significant backward integration into raw material sourcing.
Silico manganese is a ferroalloy composed primarily of manganese, silicon, and iron, with manganese content typically ranging from 60% to 70%. Its principal function in steel manufacturing is to act as a deoxidizer and an alloying agent, improving the steel's strength and toughness. High-carbon silico manganese represents the largest product type, valued for its cost-efficiency in bulk steel production. Consequently, the construction end-user segment, a major consumer of this steel, dictates a significant portion of market demand.
Environmental regulations, including China's MEE emissions targets and the EU's REACH framework, impose stringent controls on ferroalloy production. Concurrently, quality mandates from bodies like the Bureau of Indian Standards (BIS) define specifications for material used in critical infrastructure. Navigating the trade-off between energy-intensive traditional smelting and the capital costs of greener production technologies remains the central strategic challenge for producers.
Market Dynamics
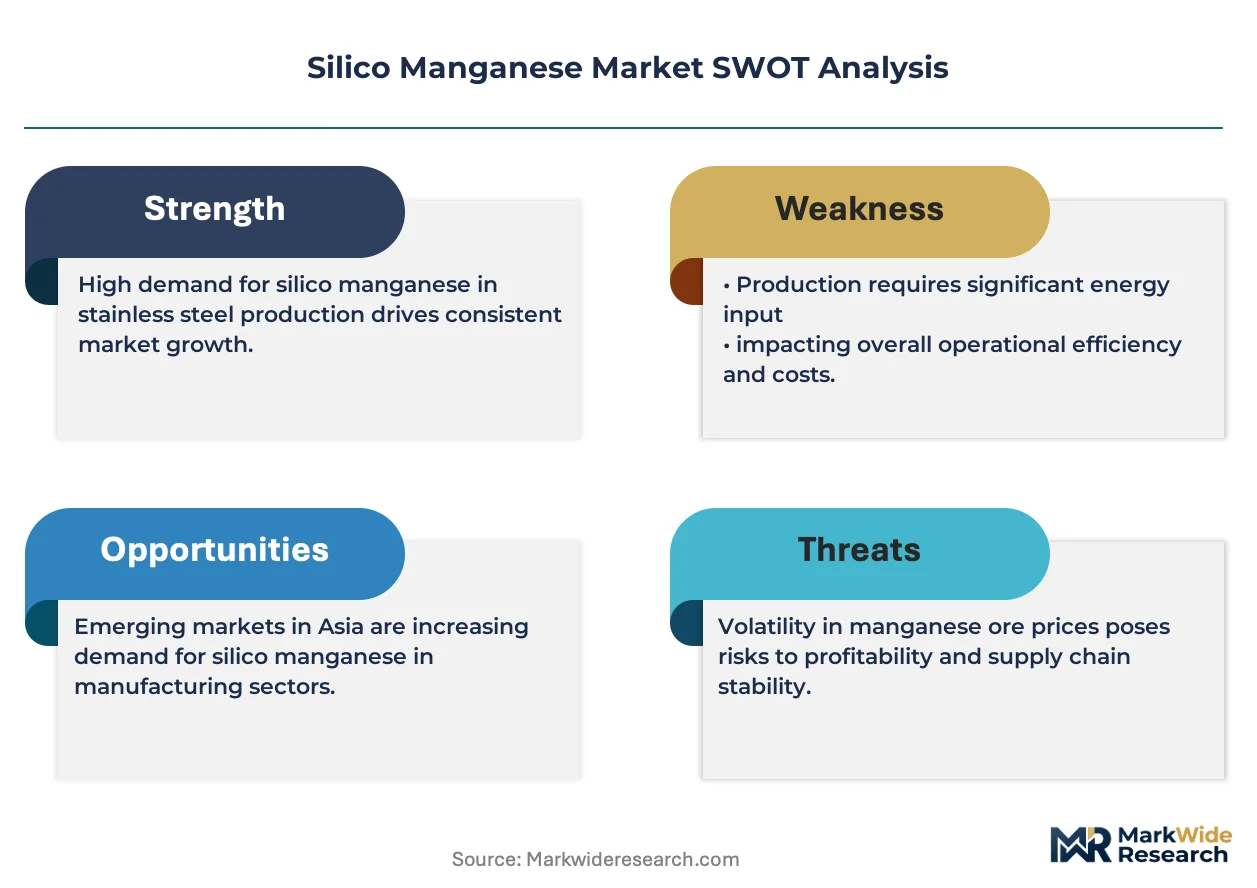
The central tension shaping the silico manganese market is the global steel industry's demand for cost-effective alloys clashing with stringent environmental mandates on energy-intensive smelting. This dynamic is reconfiguring supply chains away from producers unable to meet new emissions and efficiency benchmarks.
Growth Catalysts
- Automotive Steel Demand:The use of high-strength, low-alloy steels in automotive manufacturing to reduce vehicle weight and improve safety drives consistent demand for silico manganese as a critical alloying agent.
- Indian Infrastructure Projects:Government-led initiatives in India, such as large-scale construction of bridges and public transportation, are creating substantial, concentrated demand for construction-grade steel and its constituent ferroalloys.
- Energy Recovery Technologies:The adoption of systems that capture waste heat from smelter off-gas for power generation is enabling producers to lower operational costs and comply with emissions regulations.
Market Restraints
- Input Cost Volatility:Producer profitability is highly sensitive to fluctuations in the price of key inputs, particularly high-grade manganese ore and metallurgical coke, which are subject to global supply and demand imbalances.
- Energy Intensity:The reliance on electricity-intensive submerged arc furnaces makes the industry vulnerable to rising power tariffs and grid instability, posing a significant operational risk in many producing nations.
- Substitution Risk:In the production of certain low-specification steel grades, ferrosilicon or other manganese alloys can be substituted for silico manganese, capping price premiums in cost-sensitive segments.
Strategic Opportunities
- Southeast Asian Market Entry:Developing steel industries in nations like Vietnam and Indonesia present an opportunity for silico manganese exports as their domestic ferroalloy production capacity lags behind steel output growth.
- Specialty Grade Development:There is a growing niche for high-purity, low-carbon silico manganese grades tailored for advanced applications, including stainless steel and high-performance engineering steels.
- Green Steel Alignment:Producers can leverage investments in low-emission smelting technologies to market their product as a component for "green steel," attracting customers with corporate sustainability goals.
Industry Challenges
- Capital-Intensive Upgrades:The significant capital expenditure required to retrofit existing smelters or construct new facilities that meet modern environmental standards, such as China's MEE targets, is a major barrier.
- Divergent Quality Standards:Manufacturers must navigate a complex web of national and international standards, such as the Bureau of Indian Standards (BIS) in India and ASTM standards in the US, which can vary significantly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silico Manganese Market |
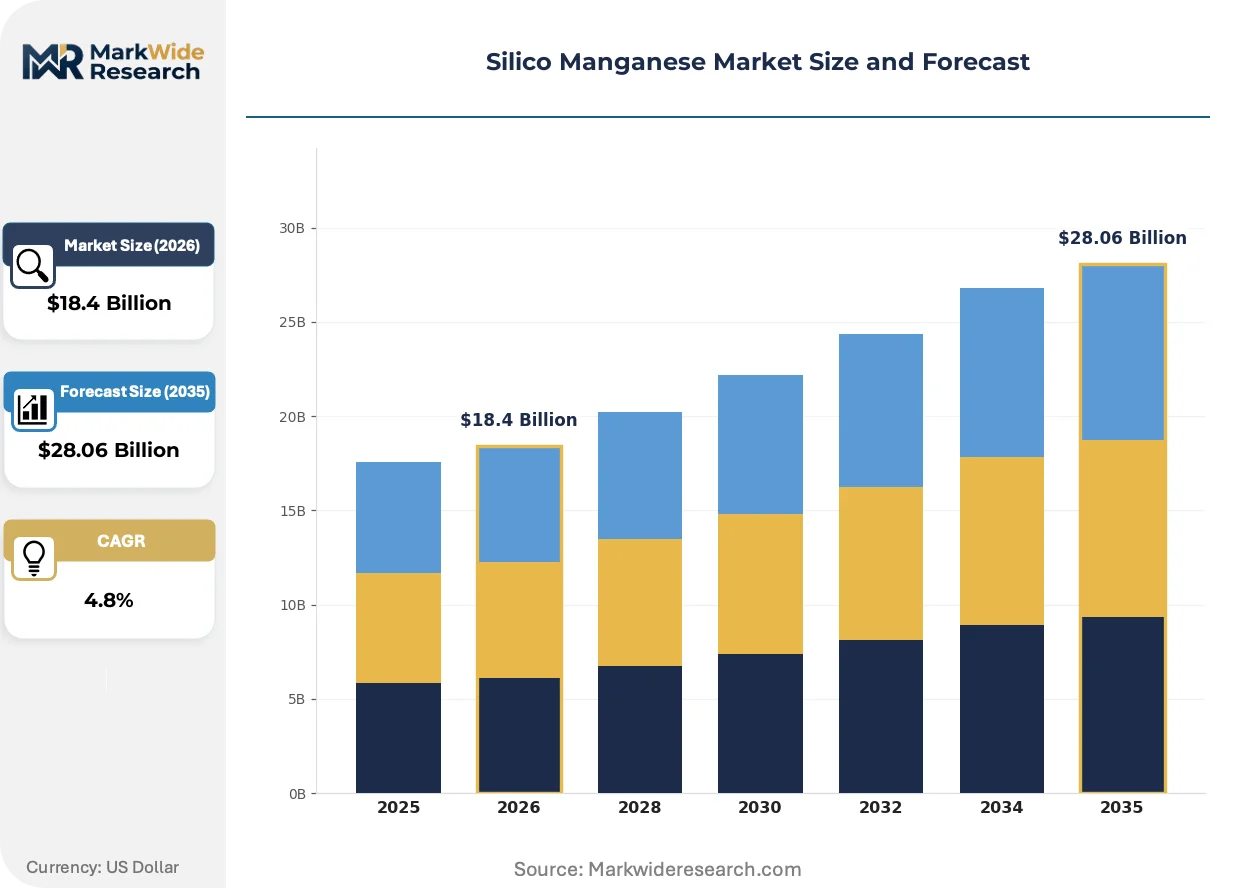
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Carbon Silico Manganese, Low-Carbon Silico Manganese, Medium-Carbon Silico Manganese, Ferroalloys Application: Steel Manufacturing, Foundry, Ferroalloy Production, Alloy Steel End User: Construction, Automotive, Machinery, Electronics Form: Granular, Powder, Lump, Pellets |
| Companies Covered | Tata Steel Limited, Glencore, Ferroglobe PLC, Sakura Ferroalloys, CITIC Dameng Mining Industries Limited, Eramet SA, Exxaro, Assmang Proprietary Limited, OM Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silico Manganese Market Strategic Shifts & Innovations
Technological advancements and regulatory pressures are compelling a fundamental re-evaluation of production economics and supply chain resilience. Efficiency in energy consumption and verifiable environmental performance are becoming key differentiators, moving beyond simple price and chemistry considerations.
Advanced Process Control
Advanced process control systems use real-time sensor data to continuously monitor and adjust furnace parameters, optimizing energy use and alloy composition. Major producers are gradually adopting these systems to improve operational efficiency and output consistency. This technology is integrating furnace-level operational data with plant-wide energy management, enabling more sophisticated cost control and predictive maintenance.
China's Dual Carbon Policy
China's "dual carbon" policy framework imposes strict quotas on energy consumption for heavy industries, including ferroalloy production. This directive actively pressures operators of older, less efficient smelters to either invest in significant technological upgrades or face production curtailments. The silico manganese sector is particularly affected, leading to a consolidation of production towards more technologically advanced and energy-efficient facilities.
Certification-Driven Sourcing
A preference for suppliers with transparent environmental credentials and third-party certifications is emerging among major steelmakers, particularly those supplying to European markets. This trend disrupts traditional procurement models that focused almost exclusively on price and chemical specifications. The shift is most pronounced in supply chains feeding automotive and construction sectors that must comply with evolving regulations like the EU's Carbon Border Adjustment Mechanism.
Silico Manganese Market Segmentation
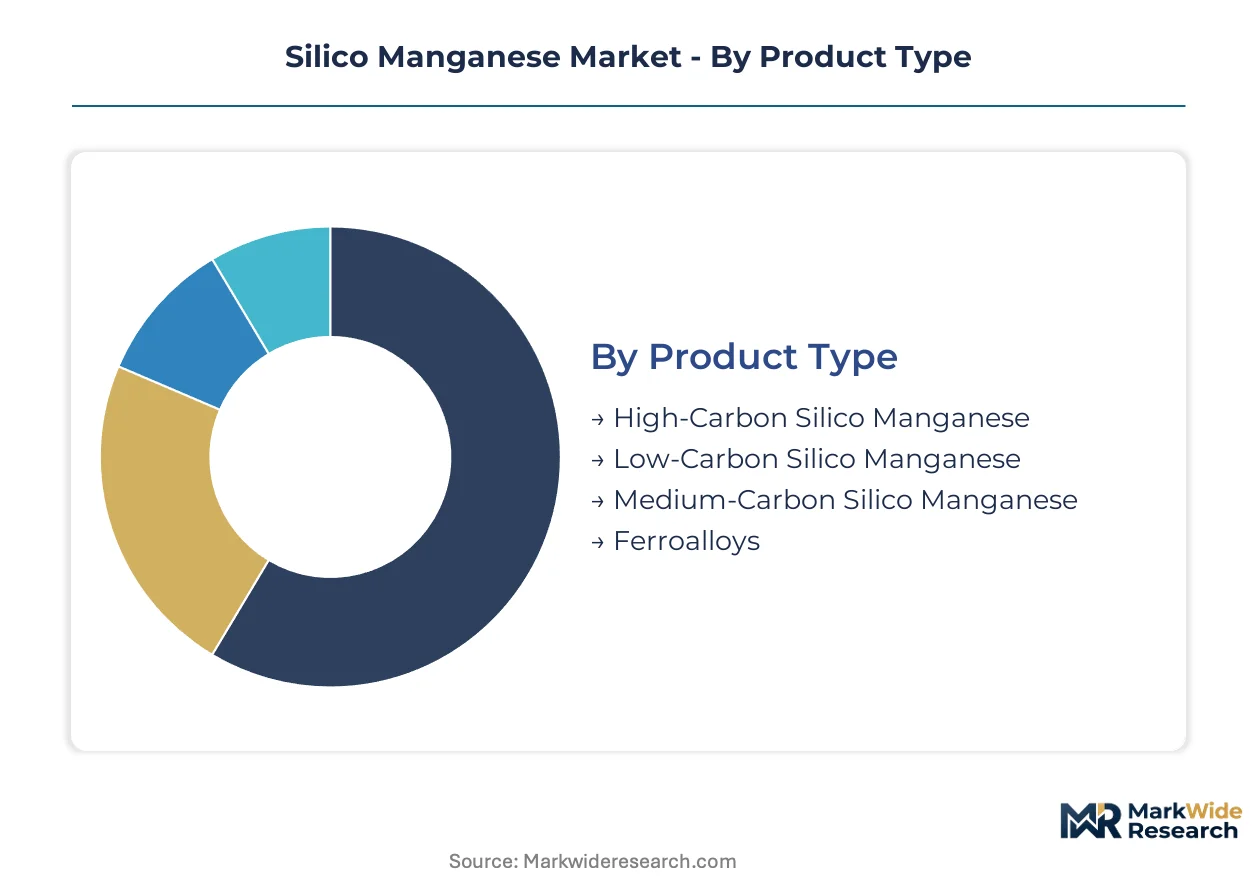
The Silico Manganese market segmentation highlights the diverse product forms and applications critical for steel production. Understanding these categories reveals how different end-user demands shape manufacturing processes and material specifications. This granular view assists stakeholders in identifying specific market opportunities and challenges.
Product Type:
The product type segmentation illustrates the spectrum from highly standardized bulk materials to specialized, customized alloys for specific steel grades.
- High-Carbon Silico Manganese:This product type, typically containing 60-70% manganese and 15-20% silicon, offers cost-efficiency for bulk steel production. Demand concentrates heavily in the construction sector, where its deoxidizing and alloying properties improve the strength of structural steels.
- Low-Carbon Silico Manganese:Characterized by lower carbon content, this grade is essential for advanced applications requiring precise metallurgical control. Specialty steel producers in automotive manufacturing seek this variant for high-strength, low-alloy steels that reduce vehicle weight.
- Medium-Carbon Silico Manganese:This intermediate grade balances cost and performance, finding application in various general engineering steels.
- Ferroalloys:This broad category encompasses various iron alloys, with silico manganese being a prominent member, used to introduce specific elements into steel.
Most installed capacity flows through High-Carbon Silico Manganese. Expansion is steepest in Low-Carbon Silico Manganese.
Application:
Application segments highlight the varying volume requirements and technical specifications demanded by diverse industrial processes.
- Steel Manufacturing:This application represents the primary consumption channel for silico manganese, where it functions as a crucial deoxidizer and alloying agent. Global steel production, particularly for automotive and infrastructure projects, drives consistent demand for this essential ferroalloy.
- Alloy Steel:Silico manganese is integral to producing alloy steels, which require enhanced mechanical properties like strength and corrosion resistance. Specialized automotive components and high-performance engineering steels rely on its precise alloying capabilities.
- Foundry:Foundries utilize silico manganese to improve the casting properties and mechanical strength of cast iron and other ferrous alloys.
- Ferroalloy Production:Some silico manganese is consumed internally or traded within the broader ferroalloy industry for further processing or blending.
Steel Manufacturing commands the largest share of silico manganese consumption. The Alloy Steel segment is expanding most quickly.
End User:
End-user segments define the ultimate consumers of silico manganese-containing products, each with distinct quality and volume requirements.
- Construction:This sector is a major consumer, driving demand for bulk steel used in infrastructure projects like bridges and public transportation. India's large-scale infrastructure initiatives significantly concentrate demand for construction-grade steel and its constituent ferroalloys.
- Automotive:The automotive industry requires high-strength, low-alloy steels to reduce vehicle weight and enhance safety, directly impacting silico manganese demand. Manufacturers prioritize consistent quality for critical components like chassis and body structures.
- Machinery:The machinery sector utilizes silico manganese-alloyed steels for components requiring durability, wear resistance, and structural integrity in industrial equipment.
- Electronics:While a smaller consumer, the electronics industry uses specialized steel grades in various components, where specific magnetic or thermal properties are critical.
The Construction sector represents the largest end-user segment for silico manganese. Automotive demand is gaining share fastest.
Form:
The form segmentation indicates how silico manganese is supplied, reflecting various processing requirements and ease of handling for different industrial applications.
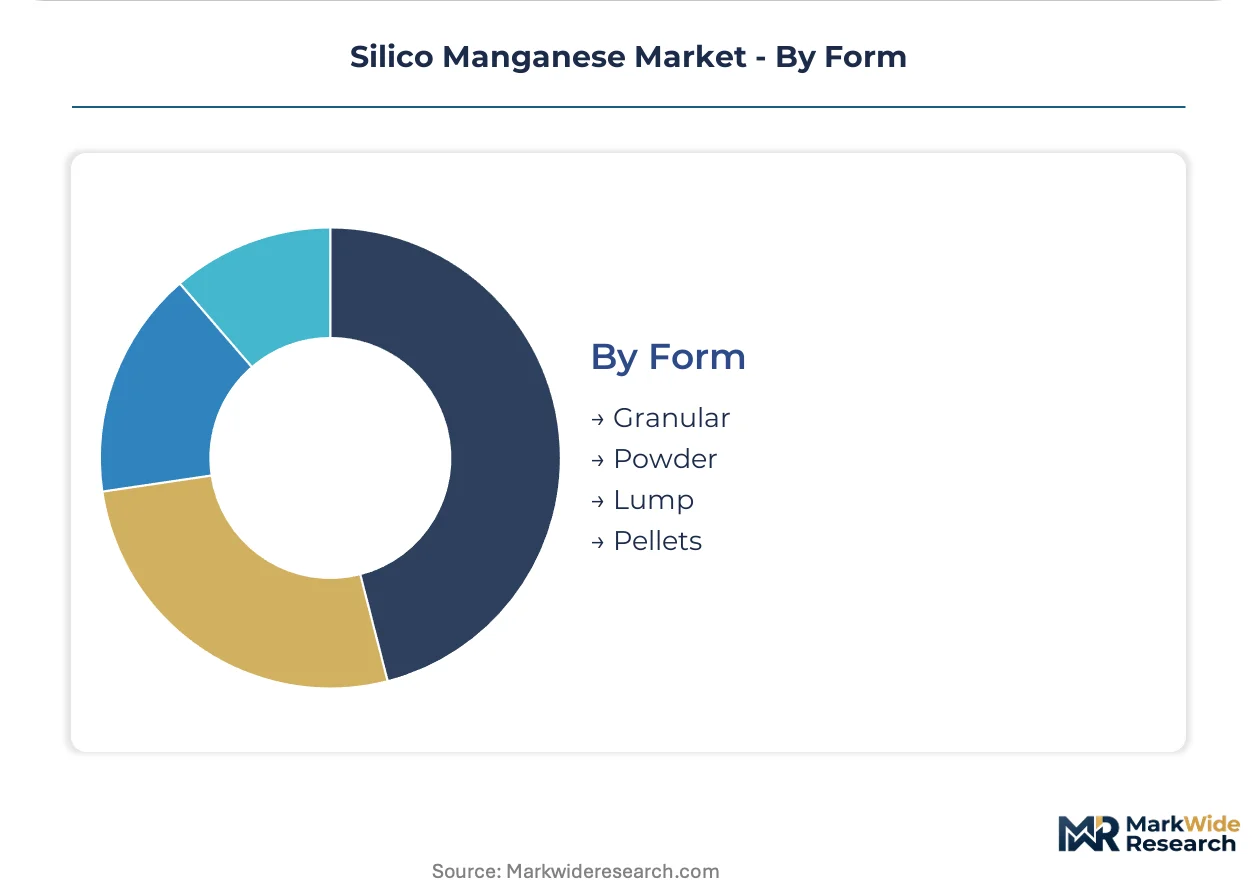
- Lump:Lump form silico manganese is the most common and cost-effective presentation, preferred for bulk additions in large-scale steelmaking operations. Its robust nature makes it suitable for direct furnace charging in electric arc and induction furnaces.
- Powder:Powdered silico manganese offers precise dosing and faster dissolution rates, making it valuable for ladle metallurgy and specialized alloying. This form is often used in high-purity steel production where tight compositional control is essential.
- Granular:Granular silico manganese provides a good balance between handling ease and dissolution speed, suitable for various steel and foundry applications.
- Pellets:Pellets offer consistent sizing and reduced dust, improving material handling and furnace recovery rates in specific steelmaking processes.
Lump form dominates the physical distribution of silico manganese. The Powder segment exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The silico manganese market experiences significant shifts due to regulatory arbitrage, where stringent environmental mandates in established producing nations lead to production migration. This dynamic influences investment patterns and reshapes global supply chains, favoring regions with lower compliance costs or robust green technology adoption.
China
China's steel manufacturing and burgeoning automotive sector create substantial internal demand for silico manganese. The nation's dual carbon goals and MEE emissions targets compel older, less efficient smelters to upgrade or face curtailments. This drives consolidation among producers, particularly in industrial clusters like the Yangtze River Delta.
India
India's large-scale infrastructure projects and construction boom generate concentrated demand for construction-grade steel, directly impacting silico manganese consumption. The Bureau of Indian Standards (BIS) mandates quality specifications for materials used in critical infrastructure. Major steel and ferroalloy production hubs in states like Odisha are expanding capacity to meet this domestic need.
South Africa
South Africa remains a significant producer, leveraging its rich manganese ore reserves to supply global steel markets. Environmental compliance for mining and smelting operations is a constant focus for producers. The Mpumalanga province, known for its ferroalloy production, continues to attract investment in processing facilities.
Vietnam
Developing steel industries in Vietnam present a growing opportunity for silico manganese exports as domestic ferroalloy production lags behind steel output. The government's industrial development policies encourage foreign investment in manufacturing. Integrated steel complexes in regions like Ha Tinh province are expanding their production capabilities.
Brazil
Brazil's robust domestic steel production and automotive sector sustain consistent demand for silico manganese. Environmental licensing for mining operations and energy efficiency mandates shape production practices. The metallurgical industries concentrated in Minas Gerais state contribute significantly to the national supply.
Silico Manganese Market Key Industry Players
Chinese producers anchor one tier of the silico manganese market, primarily serving domestic demand, while globally integrated specialists hold significant share in international trade. The market exhibits a tiered structure, with large-scale commodity producers coexisting with niche players focusing on specialty grades. Strategic archetypes include raw material integrated giants, global trading houses, and regional specialists. Capacity expansion and backward integration into raw material sourcing are dominant competitive moves.
Scale-driven players like Tata Steel Limited and Glencore exemplify the trend towards vertical integration and global distribution. Tata Steel Limited sustains a competitive edge through its significant backward integration into raw material sourcing. Glencore operates a vast global network, connecting raw material supply with diverse steel markets. Ferroglobe PLC, with its global manufacturing footprint, occupies a position as a key supplier to diverse regional steel markets.
| Leading Market Players |
|---|
| Tata Steel Limited |
| Glencore |
| Ferroglobe PLC |
| Sakura Ferroalloys |
| CITIC Dameng Mining Industries Limited |
| Eramet SA |
| Exxaro |
| Assmang Proprietary Limited |
| OM Holdings Limited |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals, along with the EU's REACH framework, gate access to qualified supply and dictate premium-tier pricing for environmentally compliant silico manganese products. This dynamic reconfigures supply chains away from producers unable to meet new emissions and efficiency benchmarks, influencing investment patterns significantly.
Pricing Analysis
Distributor margin structures reflect the commodity nature of high-carbon silico manganese, where pricing operates largely on a contract-based long-term offtake model. Price differentiation stems from quality grade, adherence to specific certification levels like BIS standards, and the volume scale of the order. Pricing pressure stems from input cost volatility, particularly for manganese ore and metallurgical coke. The construction sector represents the most price-sensitive buyer segment, while automotive manufacturers prioritize consistent quality and certified supply over absolute lowest cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns manage the movement of silico manganese from production sites to steel mills. Geographic supply concentration centers on China, India, and South Africa, which leverage their raw material access and production infrastructure. The supply chain draws from key inputs such as high-grade manganese ore and metallurgical coke. Commodity price volatility for these inputs represents a significant supply chain risk. Downstream distribution runs predominantly through direct sales to large steel manufacturers and through specialized trading houses for smaller volume requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Silico Manganese market is a stable compounder, driven by the consistent global demand for steel in infrastructure and manufacturing. This fundamental requirement underpins steady growth across the analysis window.
For Market Incumbents: Cement market leadership through strategic backward integration into raw material sourcing, securing long-term supply stability. Invest in advanced process control systems to mitigate the threat of rising energy costs and stringent environmental regulations like China's MEE emissions targets. Expand capacity in growing demand centers such as India, leveraging established relationships with major steel producers.
For New Entrants and Emerging Players: Begin with developing specialty grade silico manganese tailored for advanced applications like stainless steel, where demand for precise metallurgical control is higher. Target the rapidly developing steel industries in Southeast Asian nations, where domestic ferroalloy production lags behind steel output. A go-to-market angle focused on verifiable environmental performance and third-party certifications can attract customers with corporate sustainability goals.
For Investors and Strategic Acquirers: Roll-up economics work for consolidating fragmented regional producers because environmental compliance costs and capital-intensive upgrades favor larger, more efficient operations. The long-term viability of this market over a 5-10 year window remains strong due to steel's foundational role in global development. Watch for the consolidation of Chinese production capacity as a signal of market rebalancing and potential acquisition targets in other regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Addresses concentrated demand from large-scale infrastructure projects and enhances regional supply stability. |
| Backward Integration into Manganese Ore | Secures critical raw material supply and mitigates input cost volatility for ferroalloy producers. |
| Green Manufacturing Transition | Aligns production with global environmental mandates and attracts customers seeking "green steel" components. |
| Long-term Supply Agreements with Automotive OEMs | Ensures consistent demand for low-carbon silico manganese in high-strength, low-alloy steels. |
| Investment in Advanced Process Control | Optimizes energy consumption and alloy composition, improving operational efficiency and product consistency. |
Research Approach
Bottom-up construction end-user modeling reconciled against top-down silico manganese supply-side tracking forms the analytical core of this study. The methodology combines extensive primary interviews with steel mill procurement managers, ferroalloy producers, automotive component manufacturers, and construction contractors. Secondary validation draws from government industrial statistics, trade association reports, company financial filings, and regulatory body publications from BIS and China's MEE.
The input-output matrix framing underpins the quantitative analytical framework used to project market dynamics across the analysis window. Segmentation dimensions modeled include product type, application, end user, form, and regional regulatory environment. Compound annual growth rates were derived through a proprietary algorithm that accounts for historical trends and projected future demand drivers. Global steel production forecasts and manganese ore price trends serve as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruptions and unforeseen technological breakthroughs in steelmaking processes. Forecasts reflect assumptions regarding economic stability and regulatory enforcement over the projection horizon. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Stainless Steel Lashing Wire Market
Metals
Osmium Market
Metals
Aluminum Tubes Market
Metals
High Purity Base Metals Market
Metals
Lightweight Aluminium Pistons Market
Metals
Battery Metals Market
Metals
Bearing Steel Market
Metals
Saudi Arabia Aluminum Market
Metals
Carbotanium Market
Metals
Stainless Steel Panels Market
Metals
Europe Metal Casting Market
Metals
Global Electrolytic Copper Foil Market
Metals
Aluminum Sheet Market
Metals
Anodized Titanium Market
Metals
Nickel Foam Market
Metals
Platinum Compounds Market