
 Iraq Paints and Coatings Market | 2026-2036
Iraq Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Paints and Coatings Market Foresight
Aftermarket color-matching and touch-up services is reshaping margin distribution across the Iraq Paints and Coatings Market, pulling value away from bulk product sales toward technical support and custom formulation. Akzo Nobel NV leverages its global color database infrastructure to serve premium architectural clients in Baghdad's commercial districts. Jazeera Paints anchors its position through deep distribution into Iraq's southern governorates and proximity to Basra's industrial corridor. Hempel AS specializes in protective coatings for oilfield infrastructure, navigating the technical specifications of Iraq's energy sector procurement.
Paints and coatings encompass liquid or powder formulations comprising binders, pigments, solvents, and additives that cure to form adherent, protective, or decorative films on substrates; viscosity typically ranges from 70 to 120 Krebs units for architectural applications, with film thickness requirements of 25 to 150 microns depending on exposure class. Industrial coatings command premium pricing due to corrosion-resistance specifications for petrochemical equipment, while water-based architectural paints capture volume leadership in residential construction across central Iraq. Powder coatings represent the fastest-growing technology segment as Iraqi manufacturers adopt electrostatic spray lines to eliminate solvent emissions and reduce waste disposal burdens.
Iraq's Central Organization for Standardization and Quality Control enforces product labeling and VOC limits that determine market access for imported coatings, while the Ministry of Oil's procurement standards mandate specific corrosion-protection certifications for upstream applications. The country's national planning framework ties infrastructure spending to local supplier qualification, creating regulatory pathways for domestic blending operations. Stakeholders must monitor how Baghdad's evolving building codes and environmental enforcement capacity reshape product formulation requirements and import licensing procedures.
Market Dynamics
Iraq's reconstruction pipeline is redirecting procurement toward domestic blending capacity as Baghdad enforces local content thresholds on state infrastructure contracts. This structural shift compresses import-dependent distribution models while elevating technical service capabilities as a competitive differentiator.
Growth Catalysts
- Housing Reconstruction:Public works spending in Baghdad and Basra provinces accelerates architectural coatings consumption as civic infrastructure and residential stock expand simultaneously.
- Central Organization for Standardization and Quality Control VOC Limits:Stringent labeling and emissions standards create compliance barriers that favor established domestic blenders with certification infrastructure.
- Oilfield Protective Coatings:Upstream energy procurement mandates specific corrosion-protection certifications, anchoring demand for high-performance industrial formulations.
Market Restraints
- Solvent Price Volatility:Petrochemical feedstock fluctuations compress margins for solvent-borne coating producers serving Basra's industrial corridor.
- Import Concentration Risk:Specialty resin and pigment supply chains remain concentrated through Gulf transshipment hubs, exposing formulators to transit disruptions.
- Technical Labor Scarcity:Qualified coating applicators and quality control technicians are concentrated in Baghdad, constraining project execution in outlying governorates.
Strategic Opportunities
- Southern Governorate Penetration:Distribution infrastructure gaps in Maysan and Dhi Qar provinces create first-mover advantages for localized blending operations.
- Powder Coating Conversion:Electrostatic spray technology adoption among Iraqi metal fabricators opens solvent-free formulation segments with reduced waste disposal burdens.
- Ministry of Oil Certification Pathways:Specialized corrosion-protection approvals for upstream applications command premium positioning in energy sector procurement.
Industry Challenges
- Formulation Registration Timelines:Central Organization for Standardization and Quality Control product approval cycles delay market entry for imported specialty coatings.
- Color-Matching Technical Capability:Spectrophotometer-equipped service centers are concentrated in Baghdad, limiting aftermarket touch-up response times in peripheral markets.
- Legacy Distribution Integration:Traditional merchant networks resist transition to technical service models that bundle formulation expertise with product supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Paints and Coatings Market |
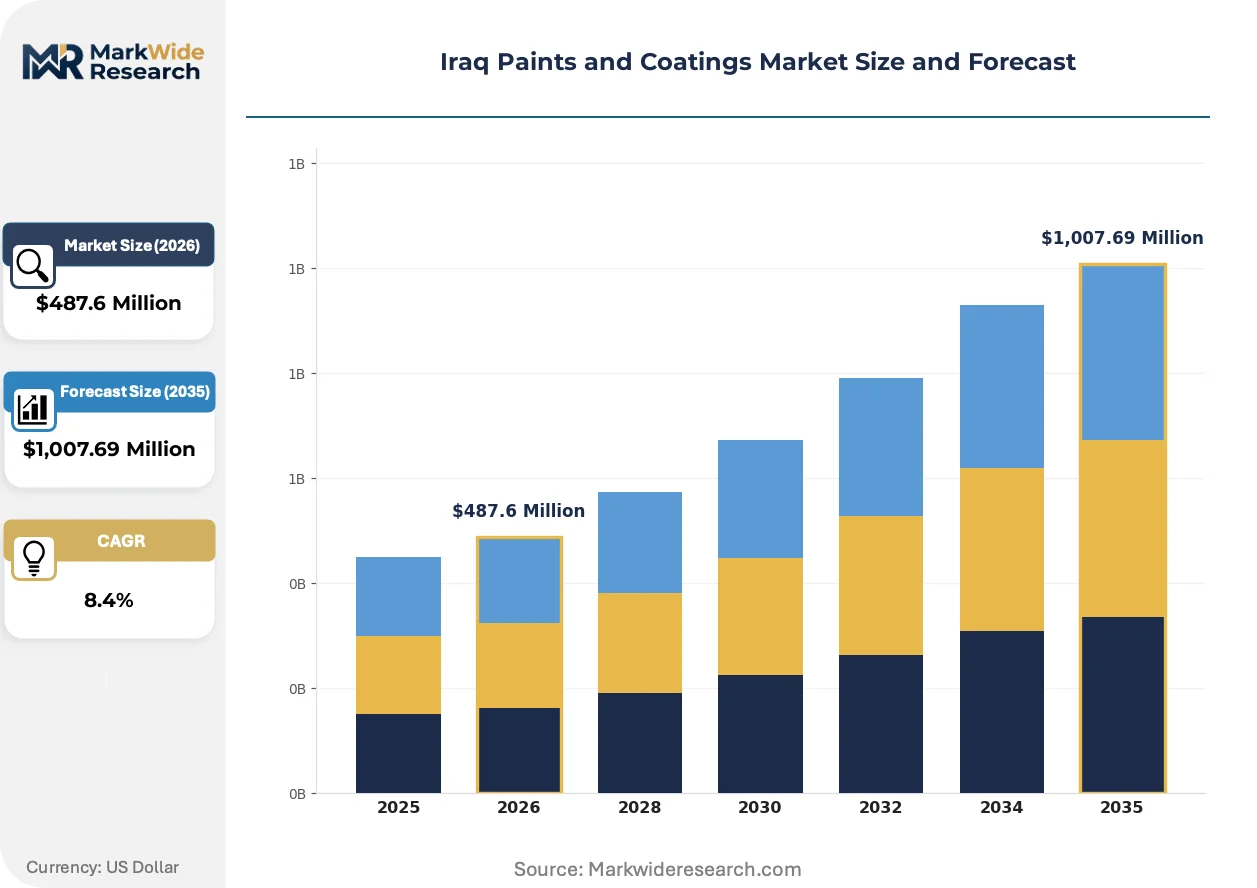
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Paints, Industrial Coatings, Protective Coatings, Specialty Coatings End User: Construction, Automotive, Marine, Aerospace Application: Residential, Commercial, Infrastructure, Industrial Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Curable |
| Companies Covered | Akzo Nobel NV, Jazeera Paints, Modern Paint Industries Company, National Paints Factories Limited, Hempel AS, Al-Tabieaa Company, Caparol, Asia Paints Company, Jotun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Paints and Coatings Market Shifts & Advancements
Formulation chemistry and application technology are converging to reshape competitive positioning across Iraq's coatings value chain. Technical service capabilities increasingly separate premium positioning from commodity supply.
Water-borne acrylic-alkyd hybrid technology is hybridizing performance attributes of conventional solvent systems with reduced VOC profiles. Residential contractors in Baghdad's commercial districts are specifying these formulations for interior applications where ventilation constraints limit solvent-borne deployment. The technology is compressing the premium gap between imported European architectural coatings and upgraded domestic production.
Iraq's Central Organization for Standardization and Quality Control is tightening enforcement of product labeling requirements and VOC maximums that determine import licensing eligibility. Domestic blending facilities with established quality management systems are capturing volume previously served by direct import channels. Industrial coatings for oilfield applications face parallel technical specification mandates from the Ministry of Oil that favor certified local producers.
Color-matching and touch-up services are unbundling from bulk product transactions across Baghdad's premium architectural segment. Specifiers in commercial real estate development now contract separately for formulation databases, on-site tinting equipment, and technical support rather than accepting standard distributor offerings. This service-layer separation is most pronounced in high-visibility commercial facades where aesthetic consistency requirements override pure product cost considerations.
Iraq Paints and Coatings Market Segmentation
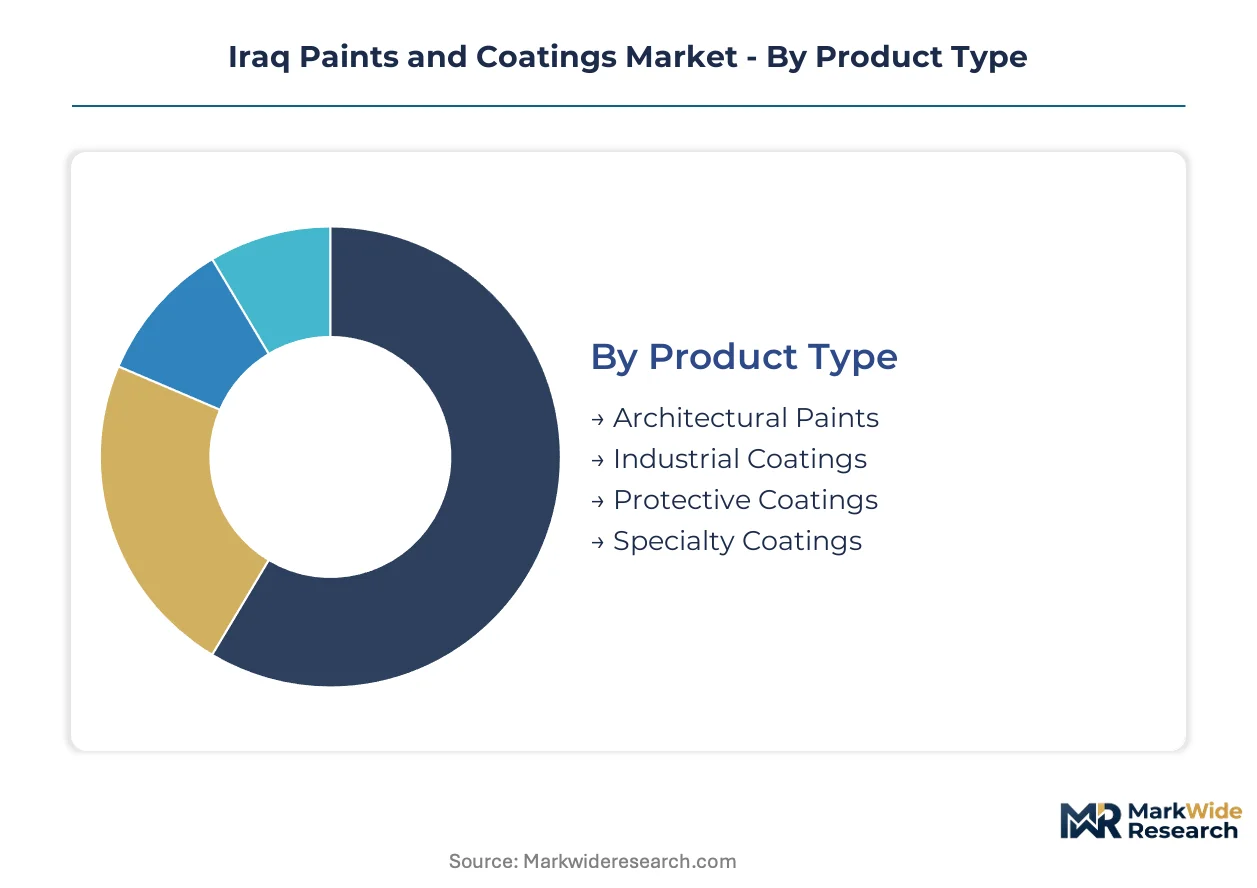
Segmentation in Iraq's paints and coatings market reveals how formulation chemistry, end-use requirements, and regulatory constraints fragment procurement patterns. Technical specifications diverge sharply between Baghdad's residential construction and Basra's oilfield infrastructure.
Product Type:
The use-case spectrum spans decorative interior finishes through corrosion-resistant industrial systems, with procurement concentration shifting toward certified domestic blending capacity.
- Architectural Paints:Water-borne and solvent-borne formulations for interior and exterior building surfaces, typically 25-75 microns dry film thickness. Baghdad and Basra provinces concentrate demand as public housing reconstruction and private commercial development accelerate simultaneously.
- Industrial Coatings:High-performance systems for manufacturing equipment and metal fabrication, emphasizing chemical resistance and durability. Basra's petrochemical corridor anchors procurement, with Ministry of Oil certification requirements filtering supplier participation.
- Protective Coatings:Heavy-duty barrier systems for aggressive environments including immersion and atmospheric exposure. Pipeline and storage tank applications in southern governorates drive specification complexity.
- Specialty Coatings:Niche formulations including intumescent fireproofing and anti-graffiti systems. Baghdad's high-visibility commercial facades generate concentrated demand for aesthetic performance guarantees.
Established volume favors architectural paints; emerging adoption favors protective coatings.
End User:
Customer archetypes range from state procurement entities with local content mandates to private operators prioritizing technical service responsiveness.
- Construction:Residential, commercial, and infrastructure contractors specifying coatings for new build and refurbishment. Central Iraq's housing reconstruction pipeline dominates volume, with Baghdad governorate absorbing the largest share of architectural procurement.
- Automotive:OEM and aftermarket refinish applications requiring color-matching precision and durability. Repair shop networks in urban centers concentrate demand, constrained by spectrophotometer equipment availability.
- Marine:Shipyard maintenance and offshore platform protection in Basra's port facilities. Immersion-grade specifications and anti-fouling requirements limit qualified supplier pools.
- Aerospace:Military and limited civil aviation maintenance applications. Specialized substrate preparation and cure schedules restrict this segment to technical service-capable distributors.
Construction commands absolute volume; marine coatings climb the fastest on oilfield infrastructure expansion.
Application:
Surface exposure classes and performance warranties segment the market by project scale and specification authority.
- Residential:Interior and exterior decorative finishes for single-family and multi-unit housing. Baghdad's informal settlement upgrading programs and new development zones concentrate demand for economical water-based systems.
- Commercial:High-visibility retail, office, and hospitality interiors requiring color consistency and durability guarantees. Premium architectural specifiers in Baghdad's commercial districts unbundle technical services from bulk supply.
- Infrastructure:Bridges, utilities, and civic buildings with extended durability specifications. Ministry of Construction procurement channels favor certified domestic blenders meeting local content thresholds.
- Industrial:Manufacturing facilities, warehouses, and process equipment with chemical and abrasion resistance requirements. Basra's industrial corridor generates concentrated demand for epoxy and polyurethane systems.
Residential absorbs maximum tonnage; infrastructure applications gain share fastest on state spending acceleration.
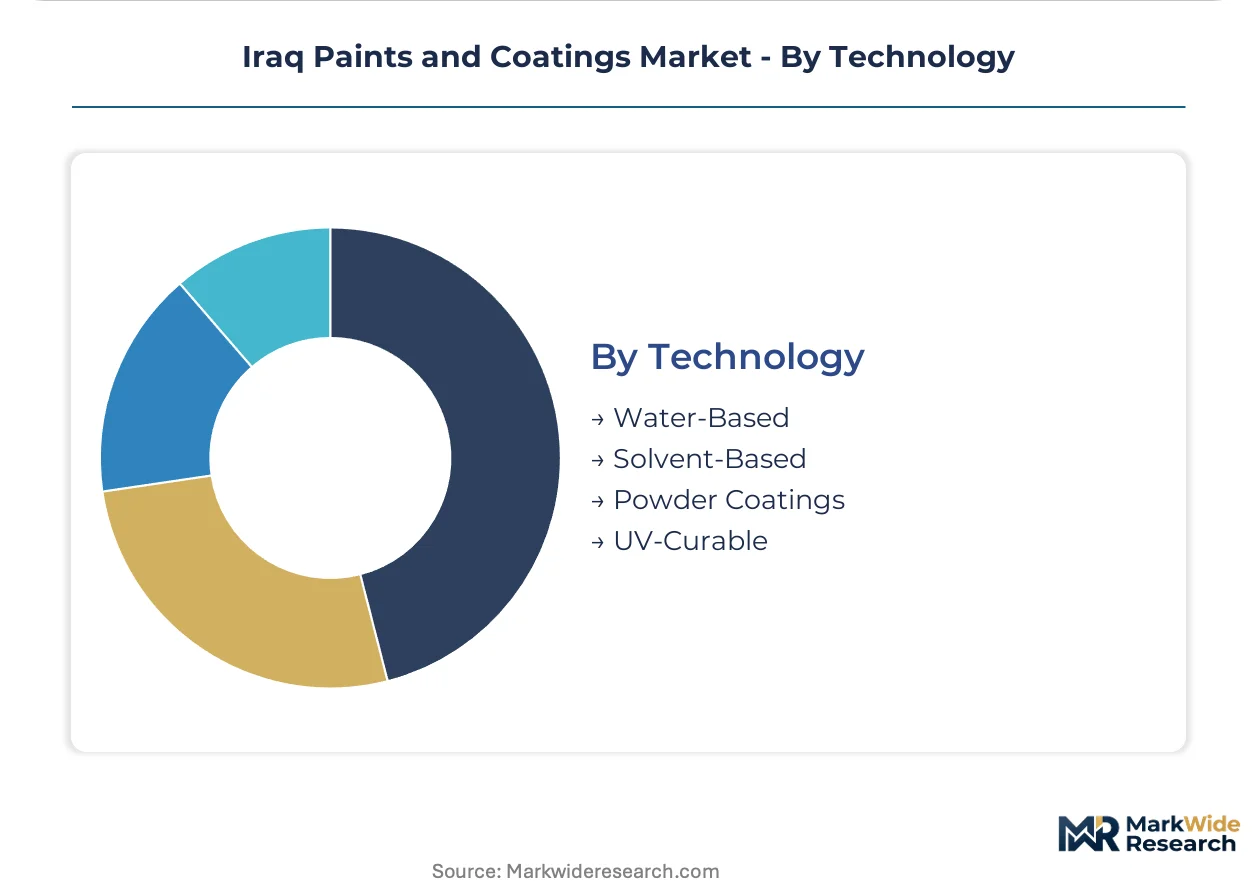
Technology:
Formulation platforms differentiate by VOC compliance, application efficiency, and capital equipment requirements for end-users.
- Water-Based:Acrylic and acrylic-alkyd hybrid dispersions with reduced solvent content. Baghdad residential contractors specify these for interior applications where ventilation constraints limit solvent-borne deployment.
- Solvent-Based:Conventional alkyd and polyurethane systems with superior flow and durability in harsh climates. Petrochemical feedstock price volatility compresses margins for producers serving Basra's industrial base.
- Powder Coatings:Thermosetting resins applied via electrostatic spray with zero VOC emissions and near-complete material utilization. Iraqi metal fabricators are converting spray lines to capture waste reduction benefits.
- UV-Curable:Rapid-cure formulations for high-throughput manufacturing lines. Limited adoption in Iraq constrained by capital equipment requirements and technical labor scarcity outside Baghdad.
Solvent-based systems retain volume leadership; powder coatings expand most quickly on environmental compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baghdad governorate buyers exhibit the highest price elasticity, squeezing margins on standard architectural grades, while Basra's oilfield procurement shows inelastic demand for certified protective systems. This divergence is reshaping where domestic blenders invest technical service capacity versus bulk production.
Baghdad Governorate
Housing reconstruction and commercial real estate development concentrate architectural coatings demand across Baghdad's central districts. The Central Organization for Standardization and Quality Control enforces VOC maximums and product labeling standards that filter import eligibility. Sadr City upgrading programs and new development zones in Karrada absorb volume for economical water-based interior systems.
Basra Governorate
Oilfield infrastructure expansion and port facility maintenance anchor protective coatings procurement in southern Iraq. Ministry of Oil corrosion-protection certifications mandate specific technical qualifications for upstream suppliers. The petrochemical corridor around Um Qasr and West Qurna fields generates concentrated demand for immersion-grade epoxy and polyurethane systems.
Maysan Governorate
Distribution infrastructure gaps create first-mover opportunities for localized blending operations serving residential and light industrial applications. Central Organization for Standardization and Quality Control registration timelines delay imported specialty coatings, favoring established domestic formulators. Amara city and surrounding districts lack spectrophotometer-equipped service centers, constraining color-matching response times.
Dhi Qar Governorate
Public works spending on civic infrastructure accelerates architectural coatings consumption in southern Iraq's underserved markets. Local content thresholds on state contracts redirect procurement toward qualified domestic blenders with Baghdad certification relationships. Nasiriyah's industrial zones and residential expansion areas present penetration targets for technical service-capable distributors.
Iraq Paints and Coatings Market Competitive Landscape
Multinational specialists and regional domestic blenders split the market along certification and service capability lines. Baghdad-based operations with Central Organization for Standardization and Quality Control approval infrastructure capture volume from direct import channels. Three archetypes dominate: global coating majors leveraging color databases and technical service networks; regional Arab Gulf producers with southern Iraq distribution depth; and domestic Iraqi blenders qualifying for local content procurement. Competitive moves concentrate on Ministry of Oil certification acquisition and southern governorate distribution expansion.
Within the multinational tier, Akzo Nobel NV anchors premium architectural positioning through global color infrastructure deployed in Baghdad commercial districts. Jazeera Paints exemplifies regional Gulf-based penetration, with distribution density into Basra's industrial corridor and southern governorates. Hempel AS occupies the protective coatings specialist position, navigating Ministry of Oil technical specifications for oilfield infrastructure. These three represent distinct competitive vectors—technical service premium, geographic proximity advantage, and sector-specific certification—rather than overlapping head-to-head contest.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| Jazeera Paints |
| Modern Paint Industries Company |
| National Paints Factories Limited |
| Hempel AS |
| Al-Tabieaa Company |
| Caparol |
| Asia Paints Company |
| Jotun |
| Others |
Supply & Pricing Matrix
Specialty resin and pigment imports concentrated through Gulf transshipment hubs feed directly into margin compression for domestic Iraqi blenders, forcing downstream value capture toward technical service bundling rather than bulk product markup. Baghdad's enforcement of local content thresholds on state contracts redirects procurement toward certified domestic facilities, elevating formulation expertise as the primary pricing differentiator.
Pricing Analysis
Aftermarket color-matching and touch-up services drive lifetime value across Baghdad's premium architectural segment. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and technical service intensity. Pricing pressure stems from petrochemical feedstock volatility squeezing solvent-borne coating margins in Basra's industrial corridor. Residential contractors in Baghdad's informal settlement upgrading programs exhibit highest price sensitivity, while Ministry of Oil procurement for upstream corrosion-protection systems shows minimal elasticity.
Supply Chain Analysis
Tariff exposure between UAE transshipment hubs and Iraqi border crossings dominates supply chain risk calculations for imported specialty inputs. Raw material sourcing draws from Saudi Arabia for petrochemical feedstocks, China for titanium dioxide pigments, and Germany for epoxy resin systems. Single-source vulnerability concentrates in spectrophotometer equipment and advanced tinting machinery, constraining color-matching service expansion beyond Baghdad. Distribution runs through traditional merchant networks transitioning toward technical service models that bundle formulation expertise with product supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's paints and coatings sector represents an early-cycle expansion story, with housing reconstruction and oilfield infrastructure renewal creating simultaneous demand tailwinds across architectural and protective coating segments.
For Market Incumbents: Build certification moats through Central Organization for Standardization and Quality Control registration infrastructure, accelerating product approval timelines that delay import competitors. Deepen backward integration into petrochemical feedstock supply to defend against solvent price volatility threatening Basra industrial margins. Prioritize Ministry of Oil corrosion-protection certification acquisition as a barrier against regional Gulf producers seeking upstream energy positioning. For New Entrants and Emerging Players: Pursue distribution infrastructure gaps in Maysan and Dhi Qar governorates where spectrophotometer-equipped service centers remain absent and color-matching response times lag Baghdad standards. Target powder coating conversion opportunities among Iraqi metal fabricators adopting electrostatic spray lines for environmental compliance. Anchor go-to-market strategy through localized blending partnerships that satisfy state contract local content thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional Arab Gulf producers holding southern Iraq distribution depth but lacking Baghdad certification relationships. Five-to-ten year viability hinges on domestic blending capacity expansion aligned with state procurement localization mandates. Monitor Ministry of Oil tender award patterns as the inflection signal for protective coatings demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive supply of solvents and resins insulates margins from Gulf pricing volatility. |
| Ministry of Oil Certification Acquisition | Specialized corrosion-protection approvals unlock premium positioning in upstream energy procurement. |
| Powder Coating Line Conversion Partnerships | Electrostatic spray technology adoption among metal fabricators opens solvent-free formulation segments. |
| Southern Governorate Distribution Expansion | Localized blending operations in Maysan and Dhi Qar capture first-mover advantage in underserved markets. |
| Spectrophotometer Service Center Deployment | Color-matching technical capability outside Baghdad accelerates aftermarket touch-up revenue capture. |
Research Methodology
Operator-level perspectives from plant managers at domestic blending facilities, procurement leads at Baghdad construction contractors, Ministry of Oil technical specification officers, and distribution channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, Central Organization for Standardization and Quality Control registration filings, and Ministry of Construction procurement disclosures. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Scenario-bracketing framed the analytical approach, modeling demand trajectories across housing reconstruction intensity and oilfield capital expenditure cycles. Segmentation dimensions spanned formulation chemistry, end-use application, performance certification tier, and regional procurement cluster. CAGRs derived from trend extrapolation adjusted for regulatory enforcement capacity and local content policy implementation pace.
Macroeconomic conditions sit as an overlay; deviation in dinar exchange rate stability, oil revenue allocation to infrastructure budgets, or regional trade route security would shift the trajectory. Forecasts reflect assumptions about regulatory continuity and state procurement localization commitment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Water Color Market