
 Pre-Painted Galvanised Iron (PPGI) Market | 2026-2036
Pre-Painted Galvanised Iron (PPGI) Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Painted Galvanised Iron (PPGI) Market Analytics
Multi-source procurement among large fabricators is expanding as buyers diversify beyond captive mills to mitigate alloy-zinc supply volatility. Tata Steel leverages its Jamshedpur and Kalinganagar integrated complexes to sustain captive hot-dip galvanizing lines feeding downstream color-coating units. ArcelorMittal competes through European R&D centers that specialize in high-durability PVDF formulations for coastal construction markets. POSCO anchors Northeast Asian supply through its Gwangyang works, where in-house production of substrate and coating resin tightens quality loops for appliance-grade sheet.
Pre-painted galvanised iron consists of hot-dip zinc-coated steel substrate passivated with chromate or chrome-free treatments, then roller-coated with organic films cured at 200–250°C to achieve 15–35 µm dry-film thickness, serving primarily as a corrosion-resistant, aesthetic cladding and enclosure material. Coil dominates volume flows because continuous processing lines at mills minimize edge-defect rates and enable just-in-time slitting to fabricator widths, whereas sheet commands premium positioning where contractors demand cut-to-length panels for rapid site assembly. Polyvinylidene fluoride coatings lead margin pools in Middle Eastern and Southeast Asian export markets due to chalk-resistance warranties exceeding twenty years, while polyester retains volume leadership in standard residential roofing across India and Latin America.
REACH restrictions on hexavalent chromium passivation and China's GB standards for heavy-metal content in architectural coatings are forcing reformulation investments across Asian and European supply chains. The US EPA and OSHA jointly influence domestic coil-coating operations through VOC emission limits and workplace exposure thresholds that shape plant location decisions near fabrication clusters. India's BIS certification for color-coated steel sheets creates non-tariff barriers that favor domestic mills over unqualified imports in government infrastructure tenders. Stakeholders must monitor how diverging national eco-label criteria fragment product specifications and force parallel inventory strategies across export portfolios.
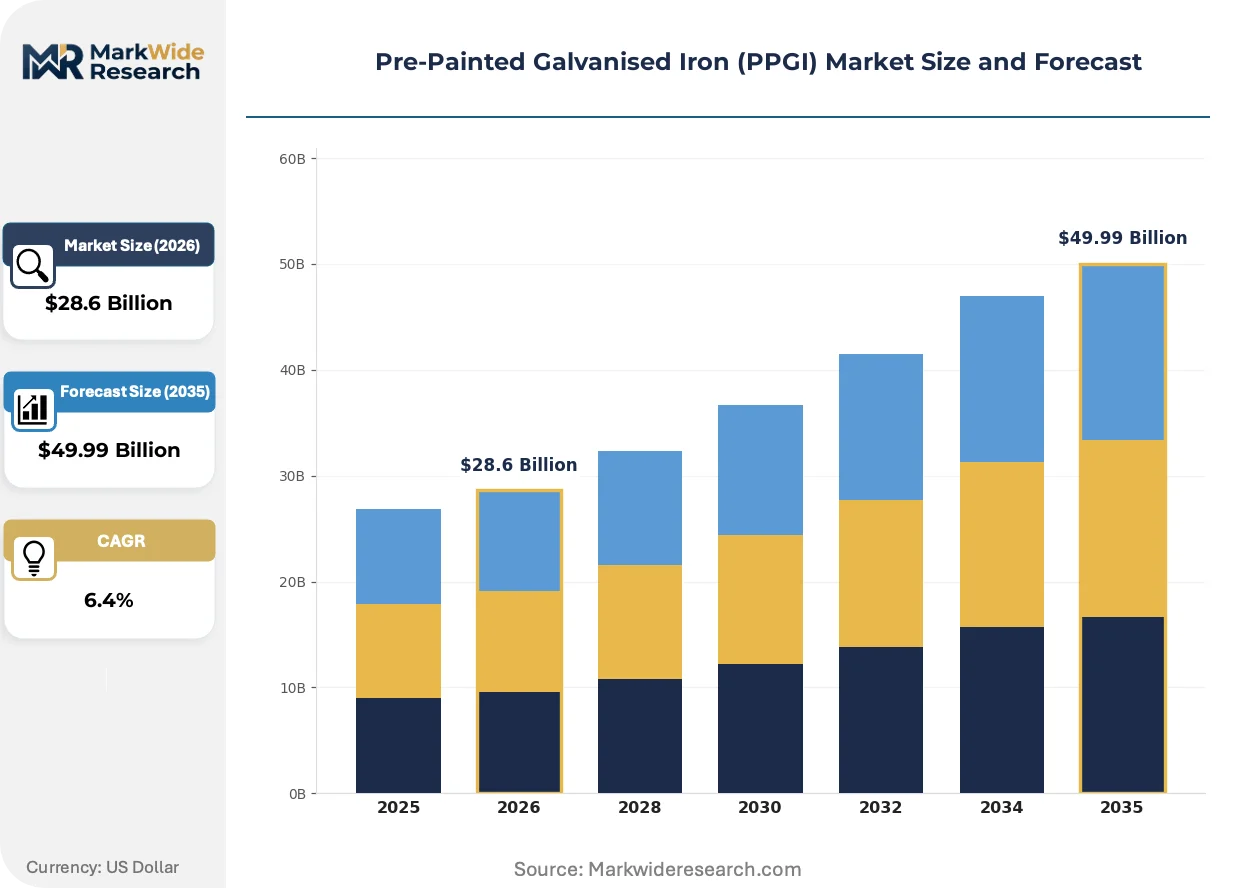
Market Dynamics
China's dual carbon goals and stricter MEE emissions standards are compressing the supply base toward low-VOC coating systems, while construction contractors across Southeast Asia expand procurement of coil-form material for commercial roofing.
Growth Catalysts
- India BIS Certification:The country's mandatory quality mark for color-coated steel sheets creates preferential access in government infrastructure tenders, favoring qualified domestic mills over unqualified imports.
- PVDF Formulation Advances:High-durability coatings with chalk-resistance warranties exceeding twenty years command premium positioning in Middle Eastern and Southeast Asian coastal construction markets.
- Continuous Coil Processing:Mill-based roller-coating lines minimize edge-defect rates and enable just-in-time slitting to fabricator widths, reducing downstream processing costs.
Market Restraints
- Alloy-Zinc Input Volatility:Fluctuations in zinc pricing and availability create margin compression for mills without captive hot-dip galvanizing capacity.
- REACH Hexavalent Chromium Restrictions:European reformulation mandates for chrome-free passivation treatments increase R&D expenditure and qualification timelines.
- Galvanized Steel Substitution:Unpainted hot-dip galvanized sheet retains cost advantage in price-sensitive residential applications where aesthetic requirements are minimal.
Strategic Opportunities
- Appliance-Grade Sheet Expansion:Northeast Asian demand for premium surface-quality PPGI in refrigerator and washing machine panels offers margin expansion beyond construction.
- India Industrial Corridor Proximity:Color-coating capacity additions near Mumbai and Pune capture logistics advantages for western India manufacturing clusters.
- Chrome-Free Treatment Convergence:Silane-based and zirconium-based passivation technologies align with tightening GB standards in China and REACH compliance in Europe.
Industry Challenges
- Coating Formulation Expertise Gap:Shortage of chemists experienced in low-VOC resin systems compatible with high-line-speed curing constraints.
- Parallel Inventory Complexity:Diverging national eco-label criteria force mills to maintain multiple product specifications across export portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Painted Galvanised Iron (PPGI) Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coil, Sheet, Strip, Plate Paint Coating: Polyester, Silicon Modified Polyester, Polyvinylidene Fluoride, Epoxy, Acrylic Application: Construction, Appliances, Packaging, Transportation, Agriculture End User: Manufacturers, Fabricators, Distributors, Contractors |
| Companies Covered | Tata Steel Limited, JFE Steel Corporation, ArcelorMittal, NIPPON STEEL CORPORATION, JSW Steel Limited, Baosteel Group, Hyundai Steel, United States Steel Corporation, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Painted Galvanised Iron (PPGI) Market Evolving Landscape
Coating chemistry and procurement patterns are reshaping competitive positioning. Formulation investments, regulatory compliance architectures, and buyer concentration are the three forces compressing traditional supply arrangements.
Chrome-free passivation chemistry is consolidating as the substrate treatment standard across export-oriented mills. European REACH restrictions and China's GB standards for heavy-metal content are forcing simultaneous reformulation. The technology is consolidating quality loops at integrated complexes with in-house resin production.
REACH restrictions on hexavalent chromium passivation are tightening supply chain entry criteria. Mills without qualified chrome-free treatments face exclusion from European architectural tenders. Indian exporters to the EU are accelerating silane-based qualification programs to maintain market access.
Multi-source procurement among large fabricators is fragmenting traditional mill-buyer relationships. Contractors in Southeast Asia now split orders across three to four qualified suppliers to mitigate alloy-zinc volatility. This pattern is most visible in Thailand and Vietnam commercial roofing markets where project scale justifies supplier diversification.
Pre-Painted Galvanised Iron (PPGI) Market Segmentation
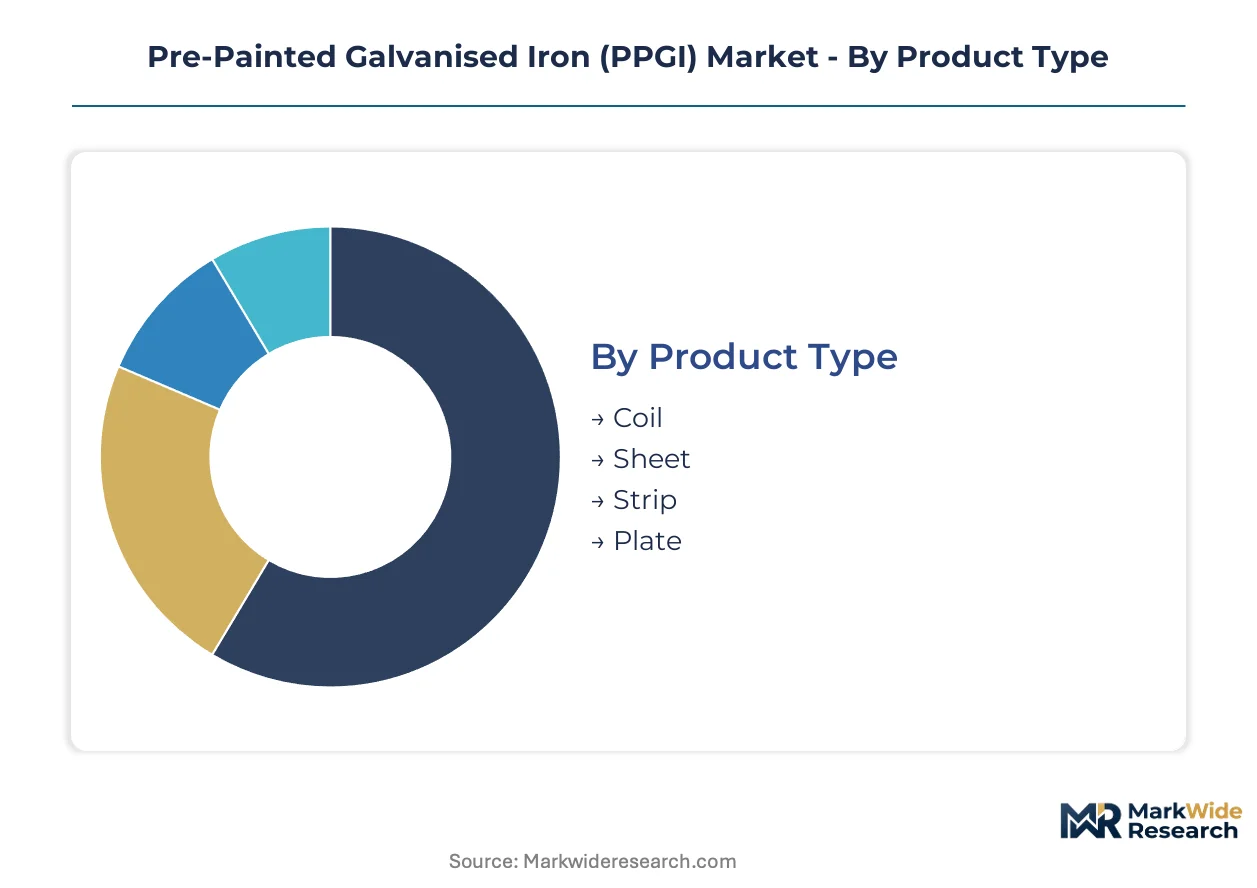
PPGI segmentation reflects divergent buyer priorities across construction, manufacturing, and distribution channels. Coil-form material serves continuous processing needs of large fabricators, while sheet commands premium positioning where contractors demand rapid site assembly. Coating chemistry and substrate format together determine logistics economics, warranty terms, and end-use qualification requirements.
Product Type:
Buyers differentiate by processing infrastructure and inventory velocity requirements.
- Coil:Continuous mill processing minimizes edge-defect rates and enables just-in-time slitting to fabricator widths. Construction contractors across Southeast Asia expand procurement of coil-form material for commercial roofing systems requiring scale and dimensional flexibility.
- Sheet:Cut-to-length panels serve contractors demanding rapid site assembly without downstream slitting capability. Premium positioning concentrates in Middle Eastern and Southeast Asian coastal markets where logistics costs favor pre-processed formats.
- Strip:Narrow-width coils target specialized fabricators producing flashing, trim, and accessory components for building envelopes.
- Plate:Thicker-gauge formats address structural applications and heavy-guard enclosures in industrial machinery.
Volume sits with Coil; growth tilts toward Sheet as contractor procurement patterns fragment.
Paint Coating:
Coating selection tracks durability requirements, warranty expectations, and regional regulatory constraints on VOC content.
- Polyvinylidene Fluoride:PVDF formulations deliver chalk-resistance warranties exceeding twenty years through fluoropolymer chemistry. Demand concentrates in Middle Eastern and Southeast Asian coastal construction markets where salt-laden atmospheres accelerate coating degradation.
- Polyester:Standard polyester coatings retain volume leadership in residential roofing across India and Latin America through cost-efficient formulation. India's BIS certification for color-coated steel sheets creates preferential access for qualified domestic mills deploying polyester systems.
- Silicon Modified Polyester:Hybrid chemistry bridges durability and cost for industrial building applications in moderate climates.
- Epoxy:Chemical-resistant films serve appliance interiors and food-processing equipment requiring hygienic surface properties.
- Acrylic:Waterborne and low-VOC acrylic systems align with China's GB standards for heavy-metal content and MEE emissions compliance.
Polyester dominates shipment tonnage; PVDF captures expanding share in coastal premium segments.
Application:
End-use sectors impose distinct surface-quality, forming, and corrosion-resistance specifications.
- Construction:Architectural cladding and roofing systems consume the majority of PPGI volume, with demand bifurcating between standard residential and premium commercial specifications.
- Appliances:Refrigerator and washing machine panels require premium surface-quality PPGI with zero-defect cosmetic standards, offering margin expansion beyond commodity construction grades.
- Packaging:Container and drum applications prioritize chemical resistance and forming characteristics over aesthetic properties.
- Transportation:Trailer bodies and vehicle components demand high-strength substrates with specialized coating adhesion for severe forming operations.
- Agriculture:Grain silos and livestock housing utilize standard-grade material where cost efficiency outweighs extended warranty requirements.
Construction absorbs the heaviest volume; appliance-grade sheet climbs fastest on premium positioning.
End User:
Channel structure determines order patterns, technical service requirements, and inventory risk allocation.
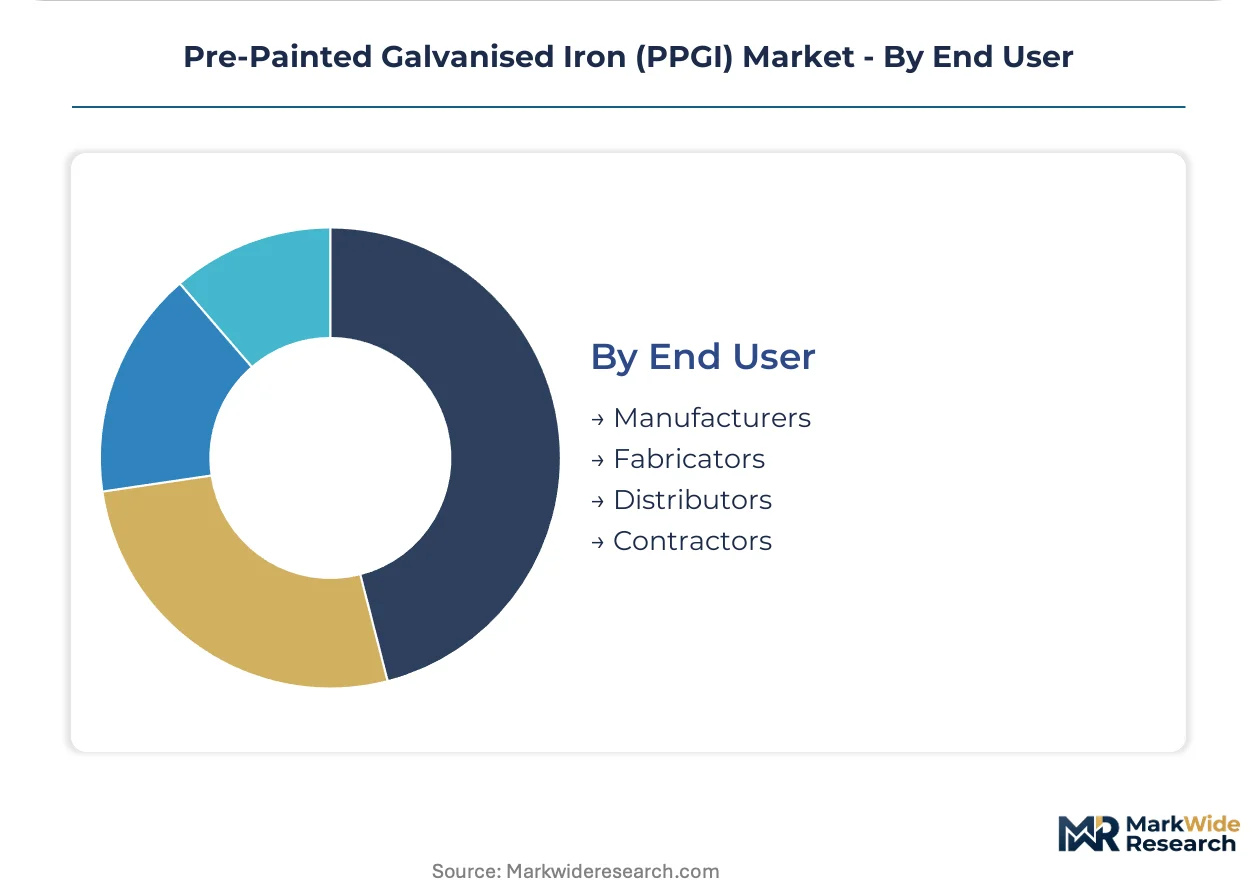
- Fabricators:Mid-stream processors convert mill coils to finished components, requiring technical partnership on coating formulation and forming-lubricant compatibility.
- Contractors:Direct procurement of sheet and pre-engineered panels concentrates in large-scale commercial roofing projects across Thailand and Vietnam.
- Manufacturers:Appliance OEMs and automotive suppliers impose stringent surface-quality audits and lot-traceability requirements.
- Distributors:Stocking intermediaries absorb inventory risk in fragmented regional markets, requiring mills to maintain multiple product specifications across export portfolios.
Fabricators handle the greatest throughput; contractors are gaining share through direct mill relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand through government infrastructure tenders requiring BIS-certified color-coated steel, while China's dual carbon goals reshape coating chemistry investments across Northeast Asian supply chains.
China
Construction contractors in the Yangtze River Delta drive coil-form procurement for commercial roofing systems. The MEE enforces stricter emissions standards that compress supply toward low-VOC acrylic coating systems. Mills in the Pearl River Delta are accelerating chrome-free passivation investments to maintain export qualification.
India
Government infrastructure tenders favor qualified domestic mills supplying BIS-certified polyester-coated sheets for residential roofing programs. The Bureau of Indian Standards mandates quality marks that create non-tariff barriers against unqualified imports. JSW Steel and Tata Steel are expanding color-coating capacity near Mumbai and Pune industrial corridors to capture western India manufacturing clusters.
United States
Commercial roofing contractors in the Southeast and Texas favor cut-to-length sheet formats for rapid site assembly. The EPA and OSHA jointly influence coil-coating operations through VOC emission limits and workplace exposure thresholds. Fabrication clusters in the Midwest maintain multi-source procurement relationships to mitigate zinc input volatility.
Germany
REACH restrictions on hexavalent chromium passivation force reformulation investments across architectural coating supply chains. ECHA compliance timelines extend qualification periods for chrome-free treatments. Industrial building fabricators in the Ruhr region and southern Baden-Württemberg specify high-durability coatings for extended warranty applications.
Japan
Appliance OEMs in the Kanto region demand premium surface-quality PPGI for refrigerator and washing machine panels. METI efficiency standards influence coating line energy consumption targets. POSCO's Northeast Asian supply relationships anchor quality loops for appliance-grade sheet specifications serving Japanese manufacturers.
Pre-Painted Galvanised Iron (PPGI) Market Competitive Landscape
Capacity expansion dominates the current competitive landscape as integrated steel mills add downstream color-coating lines to capture margin pools. The market structure consolidates around large-scale integrated producers with captive hot-dip galvanizing capacity, mid-sized regional specialists, and export-oriented coating service centers. Three archetypes define positioning: substrate-integrated mills controlling quality loops, coating specialists licensing formulation technology, and distribution-anchored service centers managing inventory risk. M&A activity and geographic proximity to industrial corridors represent the dominant competitive moves.
Within the integrated mill tier, Tata Steel Limited exemplifies substrate-backward positioning through its Jamshedpur and Kalinganagar complexes feeding captive color-coating units. ArcelorMittal occupies a position emphasizing European R&D specialization in high-durability formulations. POSCO represents the Northeast Asian archetype with in-house resin production tightening quality control loops for appliance-grade applications.
| Leading Market Players |
|---|
| Tata Steel Limited |
| JFE Steel Corporation |
| ArcelorMittal |
| NIPPON STEEL CORPORATION |
| JSW Steel Limited |
| Baosteel Group |
| Hyundai Steel |
| United States Steel Corporation |
| POSCO |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap coating specialists in India's western industrial corridors maintain disciplined pricing through captive zinc-alloy sourcing and long-term offtake agreements with Mumbai-Pune fabricators. Their ownership structure insulates margin pools from quarterly earnings pressure while enabling patient investment in BIS certification compliance that locks out unqualified imports from government tenders.
Pricing Analysis
Volume concentrates in standard polyester-coated coil serving residential roofing across India and Latin America, while margins pool in PVDF formulations for Middle Eastern coastal construction. Price differentiation rests on certification grade and coating chemistry durability, with BIS-certified domestic mills commanding premiums over unqualified imports. Cost compression in the polyester tier is intensifying because alloy-zinc input volatility squeezes non-integrated processors. Contractors in Thailand and Vietnam commercial roofing show highest price sensitivity, whereas appliance OEMs in Japan's Kanto region absorb premiums for zero-defect surface quality.
Supply Chain Analysis
Multi-supplier qualification mandates from large Southeast Asian fabricators fragment traditional mill-buyer relationships and compress order concentration risk. Geographic supply concentrates in China, India, and South Korea, with substrate production anchored in integrated steel complexes and coating resin drawn from in-house or licensed formulation partners. Raw material dependencies span zinc ingot, organic resins, and chromate or chrome-free passivation chemicals. Single-source vulnerability sits with European architectural markets where REACH hexavalent chromium restrictions exclude mills without qualified chrome-free treatments. Distribution runs through mill-direct relationships with large fabricators, supplemented by regional stocking intermediaries absorbing inventory risk in fragmented markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's BIS certification and Europe's REACH restrictions erect barrier-to-entry moats favoring capital-rich integrated mills over trading-house intermediaries.
For Market Incumbents: Lock in substrate-backward positioning through captive hot-dip galvanizing lines feeding downstream color-coating units, mirroring Tata Steel's Jamshedpur-Kalinganagar complex model. Accelerate chrome-free passivation R&D to preempt REACH exclusion from European architectural tenders. Defend against alloy-zinc volatility by securing long-term concentrate offtake from Australian and Peruvian mining assets.
For New Entrants and Emerging Players: Appliance-grade sheet buyers in Northeast Asia present the most penetrable white-space target, as Japanese and South Korean OEMs demand premium surface-quality PPGI with zero-defect cosmetic standards. Target India's western industrial corridor through toll-coating arrangements with underutilized Mumbai-Pune mills lacking BIS certification. Go-to-market leverage rests on licensing high-durability PVDF formulations from European R&D specialists.
For Investors and Strategic Acquirers: Distressed-cycle entries favor coating-service-center operators in Southeast Asia with established multi-source procurement relationships and qualified supplier status with Thai and Vietnamese commercial roofing contractors. Long-term viability hinges on proximity to industrial corridors and regulatory qualification breadth. Watch alloy-zinc price volatility as the inflection signal: sustained input cost elevation accelerates consolidation toward integrated mills with captive galvanizing capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc-Alloy Smelting | Captive concentrate sourcing from Australian mining assets insulates margin pools from London Metal Exchange volatility. |
| Chrome-Free Passivation Qualification | Silane-based and zirconium-based treatments unlock European architectural tenders under REACH hexavalent chromium restrictions. |
| Industrial Corridor Proximity Expansion | Color-coating capacity near Mumbai and Pune captures logistics advantages for western India manufacturing clusters. |
| PVDF Formulation Licensing Agreement | European R&D specialist partnerships transfer chalk-resistance warranties exceeding twenty years to coastal construction markets. |
| BIS Certification Acceleration Program | Quality mark attainment creates preferential access in Indian government infrastructure tenders against unqualified imports. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating line plant managers, procurement leads at downstream fabricators, distribution channel partners, and technical R&D directors specializing in low-VOC resin systems. Secondary sources included Bureau of Indian Standards certification databases, European Chemicals Agency REACH compliance registers, China's Ministry of Ecology and Environment emissions filings, and steel trade association production statistics. Bottom-up coil and sheet volume estimates triangulated against top-down construction and appliance end-use consumption models.
Data-stream reconciliation across shipment tonnage, coating chemistry mix, and end-use qualification requirements informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product format, paint coating chemistry, application sector, and end-user channel structure, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from historical volume trajectories adjusted for capacity addition timelines and qualification period extensions under tightening emissions standards. Forecast inputs incorporated zinc price volatility assumptions and chrome-free treatment adoption curves.
Revisions become necessary when alloy-zinc supply disruptions, REACH enforcement acceleration, or BIS certification scope expansion materialize beyond baseline assumptions. Deviation in China's dual carbon policy implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Middle-East and Africa Lithium Market