
 Aluminum Extrusion Market | 2026-2036
Aluminum Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Extrusion Market Intelligence
The increasing reliance on large-scale project financing for infrastructure and renewable energy developments is reconfiguring competitive dynamics for extrusion suppliers. Norsk Hydro leverages its extensive vertical integration from primary aluminum production to customized profiles to secure these large contracts. In contrast, Kaiser Aluminum Corporation specializes in high-value aerospace and automotive applications, differentiating on technical certification and product performance. Hindalco Industries competes through its significant scale in Asia and a focus on both standard and specialized profiles for regional markets.
Aluminum extrusion is a process where an aluminum alloy billet, often from the 6000-series, is forced through a die with a specific cross-sectional profile. This manufacturing method enables the creation of lightweight, strong, and intricate shapes used for structural components and enclosures. Within applications, the building & construction segment remains the largest volume consumer, driven by demand for architectural frames and structural profiles. However, components for transportation OEMs, particularly for electric vehicles, and parts for the renewable energy sector represent the fastest-growing end-use areas.
Regulatory frameworks such as the EU's REACH directive and RoHS standards govern the material composition and recyclability of extruded aluminum products. Simultaneously, ISO 9001 quality management standards and specific building codes in the United States and Germany dictate performance requirements for structural applications. Stakeholders must now decide how to balance investments in recycled aluminum capacity against the higher performance demands of advanced engineering applications.
Market Dynamics
The primary dynamic is the collision between demand for high-performance, certified extrusions in transportation and the industrial-scale economics of primary aluminum production, heavily concentrated in China. This tension shapes investment in both advanced alloys and recycled content capacity.
Growth Catalysts
- Electric Vehicles:Demand for lightweight battery enclosures, crash management systems, and body-in-white structures from automotive OEMs is a primary growth vector.
- Emissions Standards:Regulations such as the EU's vehicle CO2 targets incentivize the use of aluminum to reduce vehicle weight and improve efficiency.
- Renewable Energy Infrastructure:Growth in solar and wind power installations requires vast quantities of aluminum extrusions for mounting frames and structural towers.
Market Restraints
- Energy Price Volatility:The aluminum smelting process is extremely energy-intensive, making extrusion costs highly sensitive to fluctuations in global electricity and natural gas prices.
- Recycled Content Limitations:High-performance applications in aerospace and automotive often require primary aluminum, limiting the use of recycled scrap due to alloy contamination concerns.
- Substitution from Composites:In certain high-end applications, carbon fiber composites present a substitution threat, offering greater weight savings albeit at a higher cost.
Strategic Opportunities
- Advanced Alloys:Development of new alloys, including those with scandium or zirconium, opens opportunities in demanding aerospace and defense applications.
- Infrastructure in India:Government-led infrastructure and urban development initiatives in India present a significant, underpenetrated market for building and construction profiles.
- Digitalization of Dies:Integrating simulation software and 3D printing for die design and prototyping can significantly reduce lead times for custom profiles.
Industry Challenges
- Certification Timelines:The lengthy and rigorous process for obtaining material and process certifications for aerospace and automotive parts creates significant barriers to entry.
- Capital for Press Modernization:Upgrading or replacing aging extrusion presses to handle harder alloys and more complex profiles requires substantial capital investment for extruders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Extrusion Market |
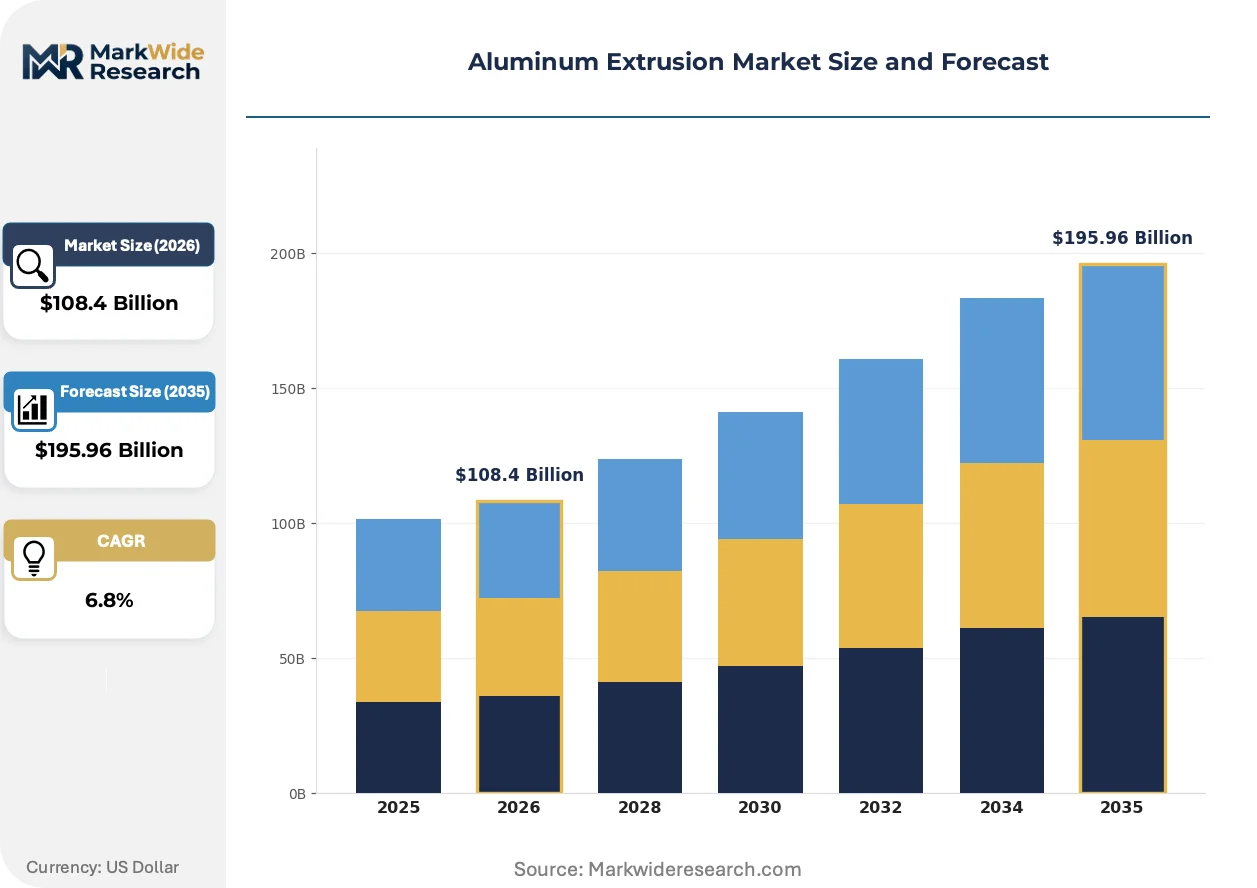
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Profiles, Heat Sink Profiles, Transportation Components, Architectural Frames, Industrial Profiles Technology: Direct Extrusion, Indirect Extrusion, Hydrostatic Extrusion, Impact Extrusion, Continuous Extrusion Application: Building & Construction, Electrical Equipment, Consumer Electronics, Aerospace Components, Packaging Solutions End Use Industry: Transportation OEMs, Telecommunications, Renewable Energy, Furniture Manufacturing, General Engineering |
| Companies Covered | Kaiser Aluminum Corporation, Hindalco Industries, Norsk Hydro, Hydro Extrusion, China Zhongwang Holdings Limited, Constellium, Arconic Corporation, Emirates Global Aluminium, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Extrusion Market Strategic Shifts & Innovations
A fundamental re-evaluation of material lifecycle is underway, driven by carbon accounting and performance requirements. The industry is moving beyond simple lightweighting to embed sustainability and traceability into the core of its manufacturing and supply chain models.
Advanced friction stir welding allows for the joining of dissimilar aluminum alloys and even aluminum to steel without melting. Automotive manufacturers are adopting this process for creating complex, multi-alloy vehicle structures like battery trays. This technique is collapsing the traditional separation between casting, extrusion, and sheet metal design, enabling monolithic, optimized components.
The European Union's Carbon Border Adjustment Mechanism (CBAM) introduces a levy on imported aluminum based on its embedded carbon emissions. This policy directly impacts the cost-competitiveness of extrusions produced using carbon-intensive energy sources. Aluminum producers in jurisdictions with cleaner energy grids or high recycling rates gain a distinct commercial advantage in the EU market.
Large-volume buyers are shifting from transactional purchasing to long-term, collaborative partnerships for capacity and development. This model displaces the role of generalist distributors for strategic components in favor of direct-from-mill relationships. The trend is most pronounced in the electric vehicle sector, where OEMs secure multi-year supply for critical body and battery system profiles.
Aluminum Extrusion Market Segmentation
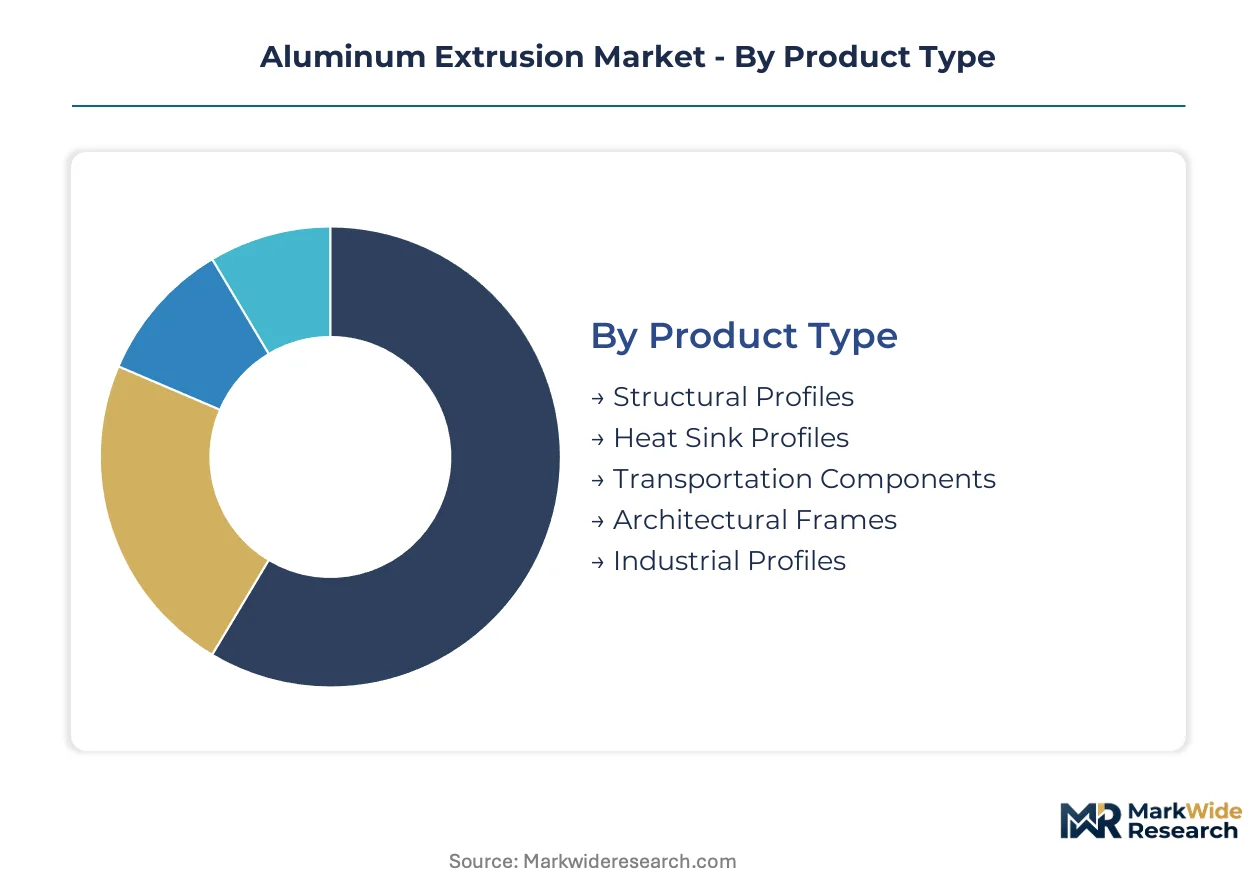
The Aluminum Extrusion market segmentation highlights the diverse demand drivers and technological nuances across its value chain. This granular view helps stakeholders understand where specific product forms and manufacturing methods create value, informing strategic investment and market entry decisions.
Product Type:
The various physical forms of extruded aluminum define distinct market functions and performance requirements.
- Structural Profiles:Used for load-bearing frameworks in construction and industrial machinery, often requiring specific strength-to-weight ratios. Demand concentrates in infrastructure projects in India.
- Transportation Components:Engineered for automotive, rail, and marine applications, emphasizing lightweighting and crashworthiness. Electric vehicle manufacturing drives this segment.
- Architectural Frames:These profiles form window frames, door frames, and curtain walls for residential and commercial buildings.
- Heat Sink Profiles:Designed with intricate fins to dissipate heat efficiently from electronic devices and LED lighting.
- Industrial Profiles:Standard and custom shapes serve diverse manufacturing equipment, automation systems, and general engineering needs.
Structural Profiles commands the established base. The steepest expansion runs through Transportation Components.
Technology:
The processing method chosen for aluminum extrusion significantly impacts profile complexity, material properties, and production efficiency.
- Direct Extrusion:The most common method, pushing the billet directly through the die, suitable for a wide range of profiles. Adoption is widespread in China's industrial sector.
- Indirect Extrusion:The die moves into the stationary billet, reducing friction for thinner walls and complex shapes. Aerospace applications drive demand due to precision.
- Hydrostatic Extrusion:Uses pressurized fluid to force the billet through the die, enabling extrusion of harder alloys.
- Impact Extrusion:A high-speed, high-pressure process producing seamless tubes and cans from aluminum slugs.
- Continuous Extrusion:Produces long, continuous profiles, often used for electrical conductors and small diameter rods.
Direct Extrusion holds the largest volume share. Indirect Extrusion is expanding most quickly due to its technical advantages.
Application:
The end-use application dictates the specific performance characteristics and design requirements for extruded aluminum products.
- Building & Construction:Utilizes extrusions for windows, doors, facades, and structural elements, valuing durability and design flexibility. Urban development in Southeast Asia drives this segment.
- Aerospace Components:Requires high-strength, lightweight extrusions for aircraft frames, wing spars, and interior structures, driven by strict certification. New aircraft programs increase demand.
- Electrical Equipment:Extrusions are used for busbars, motor housings, and heat sinks in power distribution and electronic systems.
- Consumer Electronics:Components like laptop casings, smartphone frames, and television bezels leverage aluminum for aesthetics and thermal management.
- Packaging Solutions:Includes aluminum tubes, aerosol cans, and specialized containers, valued for barrier properties and recyclability.
Building & Construction represents the largest consumption area. Aerospace Components is gaining share fastest due to new material requirements.
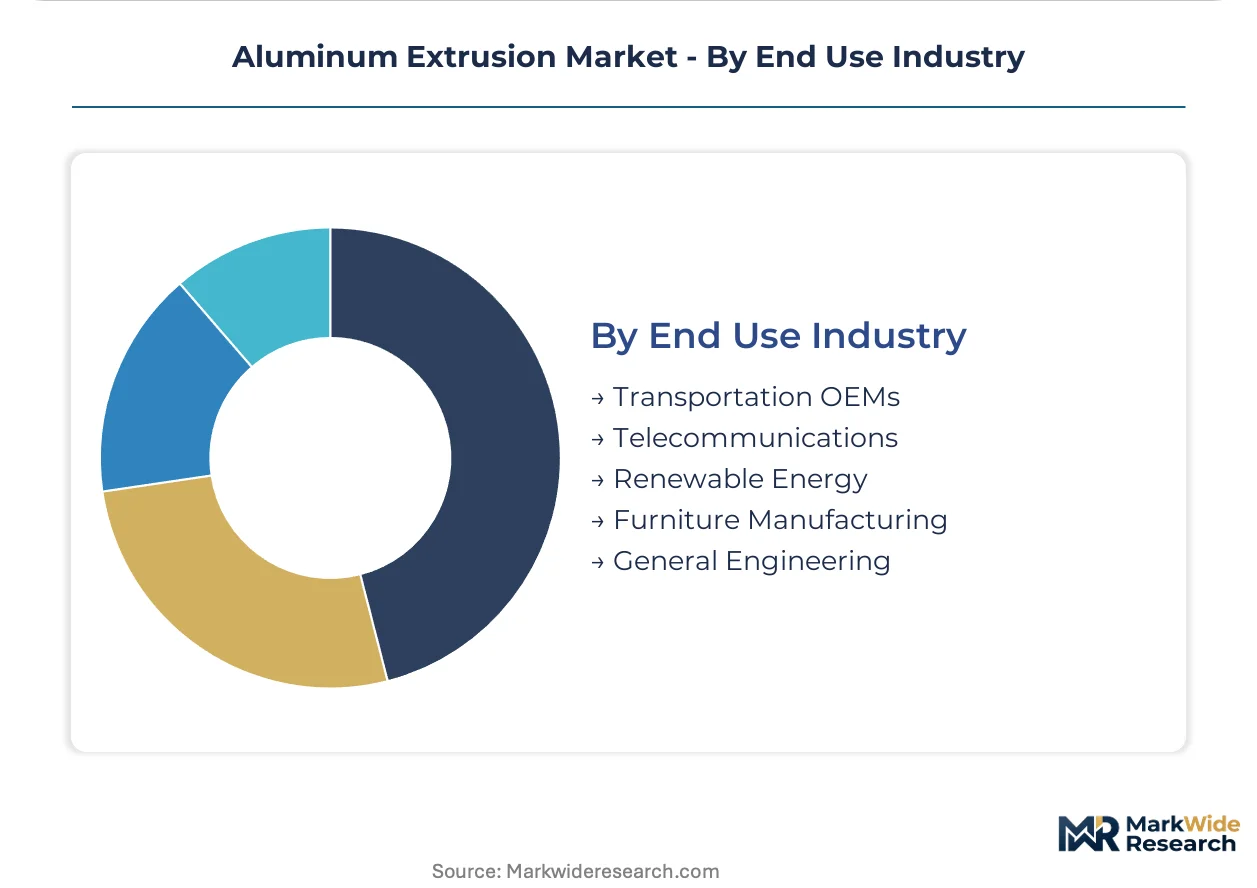
End Use Industry:
Different industrial sectors exhibit unique procurement patterns and technical specifications for aluminum extrusion.
- Transportation OEMs:Automakers, rail manufacturers, and marine builders source extrusions for lightweighting and crash protection. Electric vehicle production targets influence this industry.
- Renewable Energy:Solar panel frames, wind turbine components, and energy storage enclosures use aluminum for corrosion resistance. Investments in US solar farms drive demand.
- Telecommunications:Extrusions are used for antenna housings, server racks, and fiber optic cable protection in network infrastructure.
- General Engineering:This broad category includes custom machinery parts, jigs, fixtures, and various industrial equipment components.
- Furniture Manufacturing:Aluminum extrusions create lightweight, durable frames for office furniture, outdoor seating, and display systems.
Transportation OEMs are the dominant buyers. Renewable Energy is experiencing the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly shapes regional demand for aluminum extrusions. Large-scale infrastructure projects and electric vehicle manufacturing drive substantial consumption in specific geographies. Regulatory frameworks and industrial development patterns directly influence market dynamics across the globe.
China
Demand for structural profiles and industrial applications remains robust in China's industrial and construction sectors. The national dual carbon goals encourage the use of lighter, more sustainable materials across various industries. Industrial clusters in the Yangtze River Delta actively integrate advanced extrusion technologies for high-volume production.
India
Government-led infrastructure and urban development initiatives fuel demand for building and construction profiles in India. The PLI scheme for automotive and electronics manufacturing also incentivizes domestic production and local sourcing. Major construction hubs like Maharashtra and Gujarat are experiencing significant growth in aluminum extrusion consumption.
United States
Growth in solar and wind power installations requires vast quantities of aluminum extrusions for mounting frames and structural towers in the United States. Building codes and energy efficiency standards influence material selection for commercial and residential construction. The automotive manufacturing belt in the Midwest is increasing its use of extrusions for electric vehicle components.
Germany
Strict EU vehicle CO2 targets and building performance requirements stimulate demand for lightweight aluminum extrusions in Germany. The EU Green Deal promotes material efficiency and circular economy principles across industries. Automotive OEMs in Bavaria and Baden-Württemberg actively collaborate with extruders for advanced body-in-white structures.
Japan
Advanced manufacturing and high-speed rail projects drive demand for precision aluminum extrusions in Japan. METI initiatives support innovation in material science and energy-efficient production processes for industrial applications. The industrial zones around Tokyo and Osaka are key centers for specialized profiles in electronics and transportation.
Aluminum Extrusion Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in aluminum extrusion. The market structure exhibits a tiered approach, featuring large, vertically integrated corporations alongside numerous regional fabricators and niche technology providers. Strategic archetypes include global material suppliers, regional specialists serving diverse industrial needs, and technology-focused innovators pushing performance boundaries for advanced applications. Capacity expansion, particularly in high-growth segments like electric vehicles, and strategic partnerships with OEMs remain dominant competitive moves across the industry.
Within the global material suppliers segment, Norsk Hydro exemplifies extensive vertical integration, spanning primary aluminum production to customized profiles for large-scale contracts, particularly in infrastructure. Kaiser Aluminum Corporation occupies a distinct position as a high-value specialist, focusing on technically demanding aerospace and automotive applications where certification and performance are critical. Hindalco Industries, with its significant scale and broad product portfolio, anchors the regional market in Asia, providing both standard and specialized profiles for construction and industrial sectors, leveraging its manufacturing footprint.
| Leading Market Players |
|---|
| Kaiser Aluminum Corporation |
| Hindalco Industries |
| Norsk Hydro |
| Hydro Extrusion |
| China Zhongwang Holdings Limited |
| Constellium |
| Arconic Corporation |
| Emirates Global Aluminium |
| Alcoa Corporation |
| Others |
Cost & Logistics Intelligence
The global shipping lanes, particularly those connecting Asian production hubs to European and North American markets, directly influence aluminum extrusion cost dynamics and downstream price differentiation. Supply concentration in China dictates significant pricing power for standard profiles, while specialized applications command premium pricing based on technical certification and performance requirements.
Pricing Analysis
Cost-plus contract patterns, often indexed to the London Metal Exchange (LME) aluminum price, characterize large-volume, long-term supply agreements. Price differentiation stems from material quality grades, specific certification levels like ISO 9001 for structural components, and the complexity of custom profiles. Pricing pressure stems from energy price volatility, which significantly impacts energy-intensive smelting and extrusion processes. General engineering applications exhibit the highest price sensitivity, whereas aerospace and high-performance automotive parts are less sensitive due to stringent performance demands.
Supply Chain Analysis
Extrusion capacity is heavily concentrated among large, vertically integrated corporations such as Norsk Hydro and China Zhongwang Holdings Limited. Geographic supply concentration primarily centers in China, followed by significant production in India, the United States, and Germany. The supply chain draws from primary aluminum production and a growing reliance on recycled scrap, with specific alloy billets (e.g., 6000-series) as critical inputs. A structural risk is the alloy contamination concerns limiting recycled content in high-performance applications. Distribution runs through direct-from-mill relationships for strategic OEMs and generalist distributors for standard industrial profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aluminum Extrusion market presents a defensive-moat story, primarily due to the high switching costs associated with material qualification and supply chain integration for critical components.
For Market Incumbents: Harden core market positions by deepening backward integration into primary aluminum production or expanding recycled capacity in key regions. This move counters energy price volatility and secures raw material supply. Invest in advanced alloy development and certification processes for aerospace and electric vehicle applications to fend off substitution threats from composites.
For New Entrants and Emerging Players: Establish a beachhead in underserved regional markets like India, leveraging government infrastructure initiatives. Focus on niche segments requiring rapid prototyping and custom profiles, where digitalization of dies offers a competitive advantage. Target specialized industrial profiles and architectural frames for regional building and construction projects.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core aluminum extrusion assets. The long-term viability of this market hinges on sustained demand for lightweighting across transportation and renewable energy. Monitor the rate of electric vehicle platform consolidation as a key inflection indicator for specialized extrusion demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in EV Segments | Secures long-term supply for automotive OEMs and supports electric vehicle manufacturing growth. |
| Advanced Alloy R&D Investment | Enables higher-performance extrusions for aerospace and defense, meeting stringent material requirements. |
| Digitalization of Die Design | Reduces lead times for custom profiles, enhancing responsiveness for specialized industrial applications. |
| Strategic Partnerships with Renewable Energy Developers | Ensures consistent demand for structural profiles in solar and wind power installations. |
| Recycled Aluminum Capacity Buildout | Aligns with EU Green Deal principles and mitigates carbon border adjustment mechanism impacts for European markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through a comprehensive primary interview program, validated with extensive secondary research. Interviews included automotive OEMs, construction contractors, renewable energy developers, and extrusion plant managers. Secondary data sources encompassed industry association reports, government economic surveys, OEM sustainability reports, and patent databases, enabling robust bottom-up and top-down triangulation.
The analytical framework involved calibrating historical data against current market dynamics to project future growth across the modeling period. Segmentation dimensions included product type, technology, application, end-use industry, and regional consumption patterns. Compound annual growth rates (CAGRs) were derived by analyzing historical trends and future demand projections, with electric vehicle production forecasts and global infrastructure spending plans serving as key inputs.
Sensitivities concentrate around energy price volatility, geopolitical trade policies such as the EU's Carbon Border Adjustment Mechanism, and raw material availability. Forecasts reflect assumptions documented through this rigorous process. Quarterly review of global economic indicators and major infrastructure project announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Global Aluminium Wire Rod Market
Metals
Aluminum Casting Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Metal Alloys Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Silver Cyanide Market
Metals
Metal Coil Lamination Market
Metals
Tinplate Market
Metals
Vietnam Aluminum Market
Metals
High Purity Tungsten Market
Metals
Steel Drums and Ibcs Market
Metals
Global Copper Cathode Market
Metals
Motor Lamination Material Market
Metals
Smelting Chemicals Market
Metals
Tantalum and Niobium Material Market