
 Platinum Compounds Market | 2026-2036
Platinum Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum Compounds Market Outlook
Long-term supply contracts with embedded price-adjustment clauses is recalibrating how platinum compounds move from refiners to end-users. Johnson Matthey leverages its precious metals trading infrastructure to anchor catalyst supply chains across European chemical producers. Anglo American Platinum sustains mine-to-market verticality that controls concentrate quality for pharmaceutical-grade output. Heraeus Holding differentiates through refined powder specifications that meet semiconductor deposition standards.
Platinum compounds are coordination complexes of platinum in +2 or +4 oxidation states, typically synthesized via chloroplatinic acid reduction or direct metal dissolution in aqua regia, serving primarily as homogeneous and heterogeneous catalyst precursors and as active pharmaceutical ingredients. Platinum(II) compounds dominate oncology APIs where cisplatin and oxaliplatin anchor chemotherapy protocols, while platinum(IV) prodrug variants represent the fastest-growing category as researchers engineer reduced-toxicity analogues. Catalyst applications occupy the largest volume share across petroleum refining and fine chemical synthesis, with bimetallic platinum-ruthenium and platinum-palladium systems capturing expanding margin pools in fuel cell electrode manufacturing.
EMA pharmacovigilance requirements and FDA current Good Manufacturing Practice standards govern batch consistency and impurity profiles for injectable platinum APIs, while REACH registration mandates full toxicological dossiers for industrial catalyst precursors imported into the European Union. China's NMPA accelerates local approval pathways for generic platinum-based cytostatics, reshaping competitive access for domestic versus imported active pharmaceutical ingredients. Stakeholders must monitor how dual carbon goals in Beijing and Brussels redirect platinum catalyst demand from conventional automotive catalytic converters toward hydrogen energy and pharmaceutical applications.
Market Dynamics
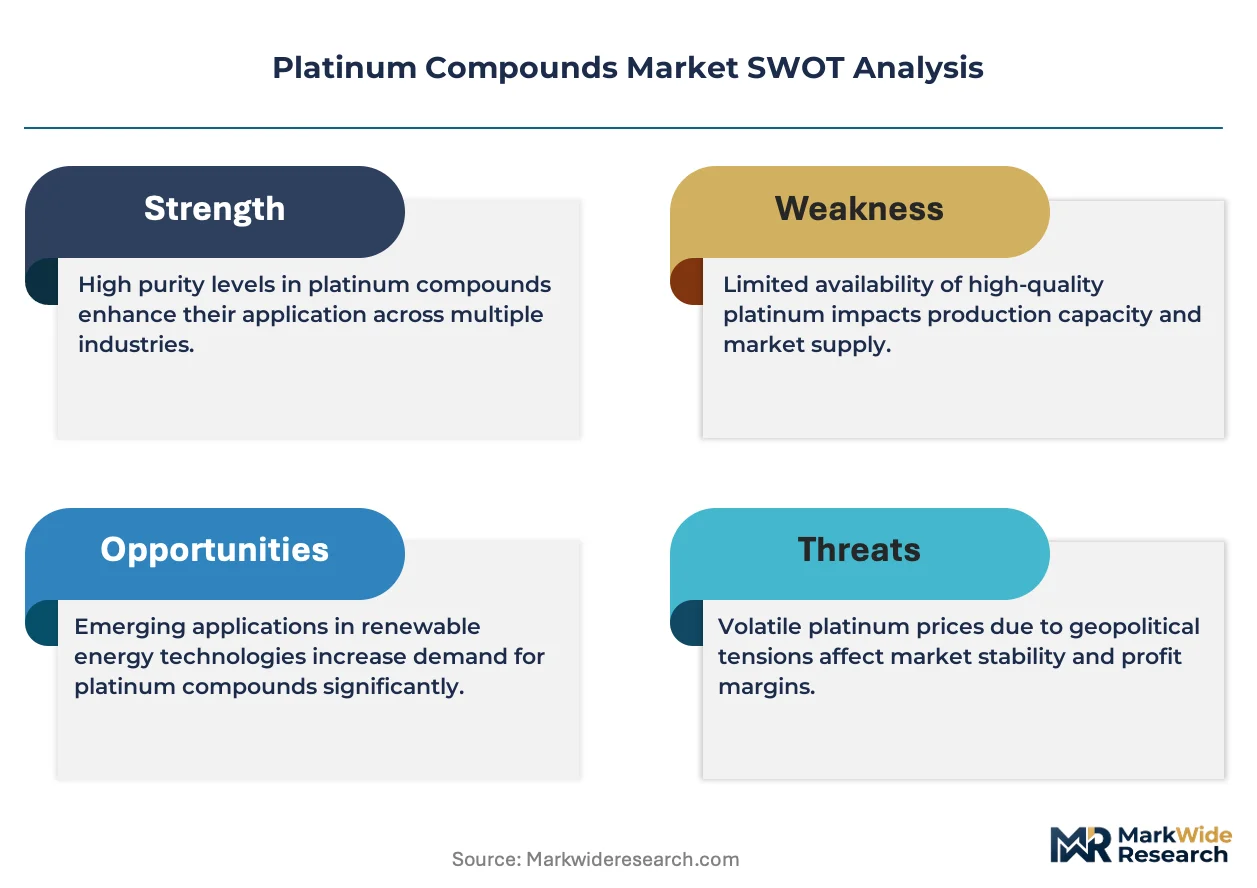
The platinum compounds market pivots on pharmaceutical-grade purity requirements colliding with hydrogen energy catalyst demand, forcing refiners to reallocate metallurgical capacity between oncology APIs and fuel cell electrode materials.
Growth Catalysts
- NMPA Acceleration:China's national pharmaceutical regulator compresses approval timelines for generic platinum cytostatics, expanding domestic manufacturing of cisplatin and oxaliplatin APIs.
- REACH Registration:Industrial catalyst precursors face mandatory toxicological dossiers under ECHA mandates, creating compliance barriers that favor established European refiners with existing registration portfolios.
- Fuel Cell Electrode Demand:Bimetallic platinum-ruthenium deposition systems are displacing pure platinum in proton exchange membrane stacks, opening new volume channels for refined powder specifications.
Market Restraints
- Concentrate Supply Concentration:South African platinum group metal mining controls 70% of global ore feedstock, exposing pharmaceutical and catalyst manufacturers to geopolitical and labor disruption risk.
- Palladium Substitution:Automotive catalytic converter manufacturers substitute palladium for platinum in gasoline applications, reducing traditional offtake volumes from precious metals traders.
- Batch Consistency Costs:FDA current Good Manufacturing Practice standards for injectable platinum APIs impose analytical and validation burdens that elevate production costs for smaller compound manufacturers.
Strategic Opportunities
- Platinum(IV) Prodrug Development:Reduced-toxicity analogues of existing chemotherapy agents offer patent-expiration defense and lifecycle extension for oncology portfolios.
- Semiconductor Deposition:Electronic-grade platinum salts for advanced packaging applications remain underpenetrated relative to gold and copper alternatives, with purity benchmarks tightening under RoHS frameworks.
- Dual Carbon Policy Alignment:Beijing's emissions targets redirect state-backed research funding toward hydrogen energy catalysts, creating procurement preference for domestic platinum compound producers.
Industry Challenges
- Chloroplatinic Acid Synthesis Expertise:The specialized knowledge required for aqua regia dissolution and reduction chemistry concentrates among aging workforces at European and Japanese refiners.
- Cross-Contamination Controls:Facilities producing both pharmaceutical-grade and industrial-grade platinum compounds face capital-intensive segregation requirements to meet EMA pharmacovigilance standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum Compounds Market |
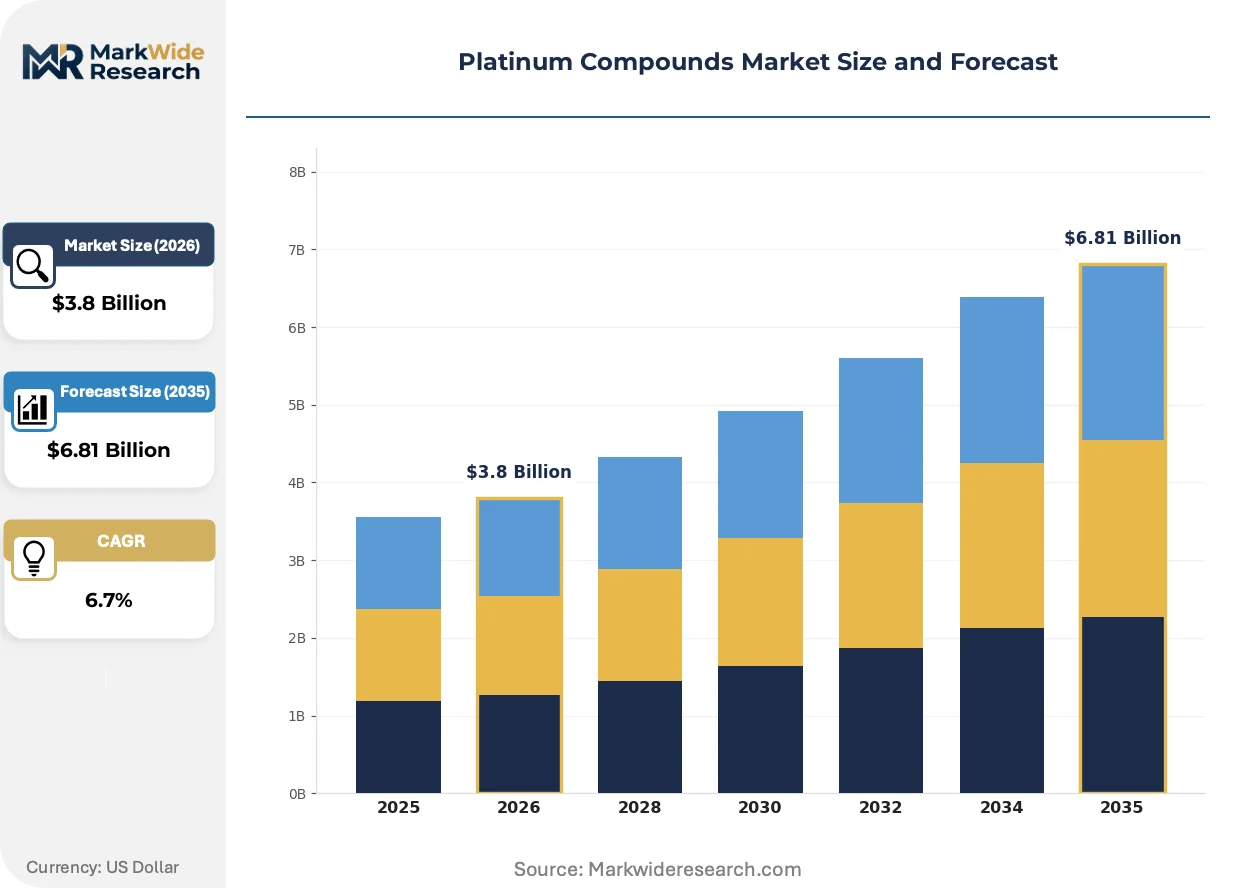
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum(II) Compounds, Platinum(IV) Compounds, Bimetallic Compounds, Metal Alloys Application: Catalysts, Electronics, Anticancer Drugs, Chemical Synthesis End User: Pharmaceuticals, Electronics Manufacturers, Chemical Industries, Research Institutions Form: Aqueous Solution, Solid, Powder, Precursors |
| Companies Covered | Umicore, Anglo American Platinum, Impala Platinum Holdings Limited, Johnson Matthey, Sibanye-Stillwater, Norilsk Nickel, Heraeus Holding, Northam Platinum Limited, Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum Compounds Market Strategic Shifts
Platinum compound innovation clusters around toxicity reduction in oncology, regulatory harmonization across pharmaceutical and industrial applications, and the emergence of hydrogen economy demand as a structural demand anchor.
Platinum(IV) prodrug architectures incorporate axial ligands that reduce systemic toxicity while maintaining DNA cross-linking efficacy. Oncology researchers at major academic medical centers are advancing these compounds through Phase II trials at accelerated pace. The technology is converging with immuno-oncology combination protocols, creating new protocol slots for platinum-based agents previously excluded from checkpoint inhibitor regimens.
EMA pharmacovigilance requirements now mandate real-world safety monitoring for all platinum-containing injectables, extending post-market surveillance obligations beyond traditional Phase IV commitments. European compound manufacturers absorb these costs through dedicated pharmacovigilance departments. Smaller API producers without existing EU regulatory infrastructure face exclusion from hospital procurement tenders that require EMA-compliant safety databases.
Hospital purchasing consortia consolidate platinum-based chemotherapy procurement under single-source contracts with embedded price-adjustment mechanisms tied to London Metal Exchange pricing. Generic API suppliers compete on batch-release speed rather than molecule innovation. This concentration is most visible in China's tier-one oncology centers, where provincial procurement platforms aggregate demand from multiple affiliated hospitals.
Platinum Compounds Market Segmentation
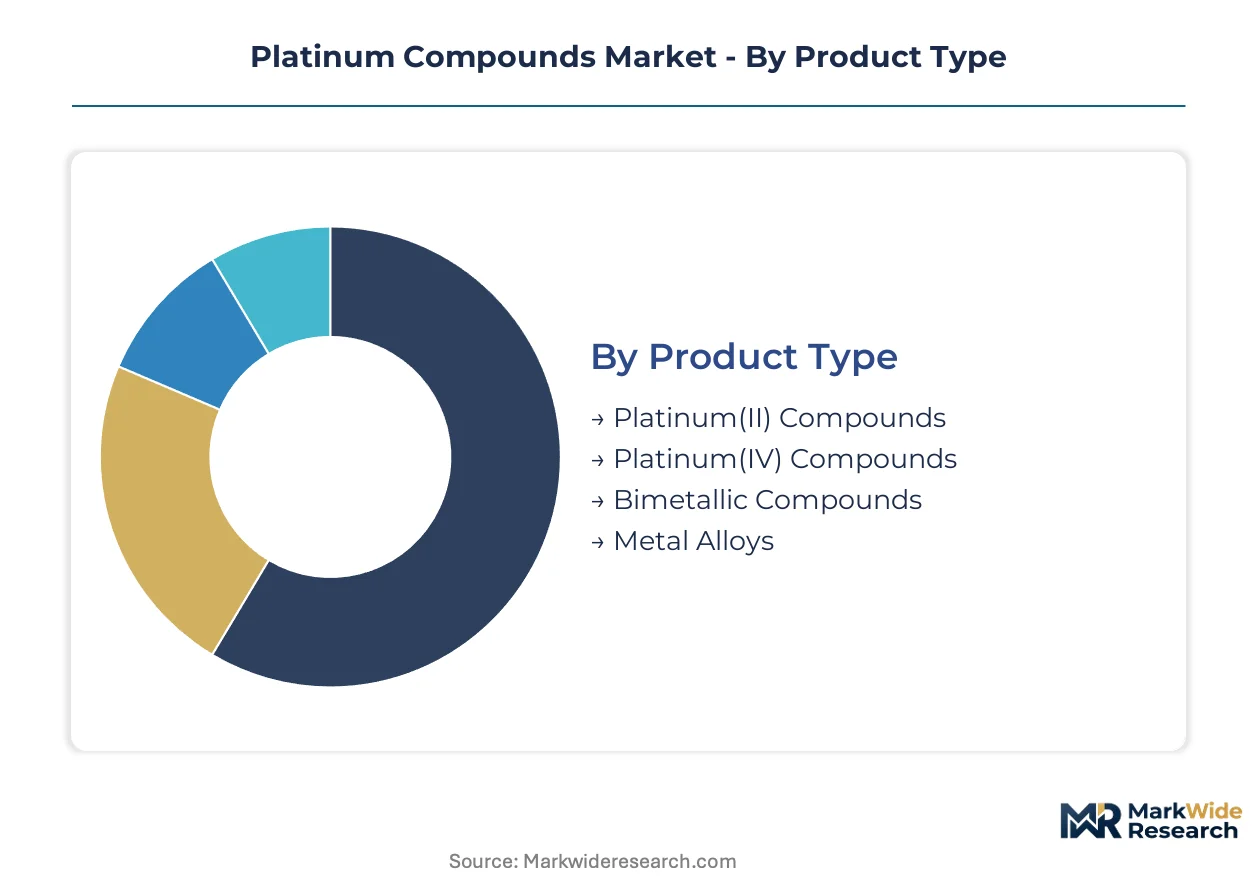
Platinum compound specifications diverge sharply across pharmaceutical, catalytic, and electronic applications, with purity grades and oxidation states determining addressable market tiers. Refiners must maintain parallel production lines to serve FDA-validated oncology APIs alongside industrial catalyst precursors under REACH registration mandates.
Product Type:
Upgrade cycles in platinum compound portfolios center on toxicity reduction and deposition precision, driving substitution between oxidation states and alloy architectures.
- Platinum(II) Compounds:Square planar coordination complexes including cisplatin and oxaliplatin serve as foundational oncology APIs with established DNA cross-linking mechanisms. Hospital procurement in China concentrates demand for injectable formulations as NMPA accelerates generic approval pathways.
- Platinum(IV) Compounds:Octahedral prodrug variants incorporate axial ligands engineered for reduced systemic toxicity and tumor-selective activation. Academic medical centers in Germany and the United States are advancing these compounds through Phase II trials for immuno-oncology combination protocols.
- Bimetallic Compounds:Platinum-ruthenium and platinum-palladium systems optimize catalytic surface area for proton exchange membrane fuel cell electrodes.
- Metal Alloys:Homogeneous solid solutions with controlled grain structures address semiconductor packaging requirements under tightening RoHS purity benchmarks.
Platinum(II) Compounds sit at the top of the volume ranking, with Platinum(IV) Compounds climbing the fastest.
Application:
Cost tier differentiation separates commodity catalyst precursors from pharmaceutical-grade APIs validated under FDA current Good Manufacturing Practice standards.
- Catalysts:Homogeneous and heterogeneous platinum compound precursors drive petroleum refining, fine chemical synthesis, and automotive emission control. European chemical producers rely on Johnson Matthey's precious metals trading infrastructure for long-term supply contracts with embedded price-adjustment clauses tied to London Metal Exchange pricing.
- Anticancer Drugs:Injectable platinum APIs require batch consistency documentation and impurity profiling governed by EMA pharmacovigilance requirements. Anglo American Platinum's mine-to-market verticality controls concentrate quality for pharmaceutical-grade output destined for oncology centers in China and Europe.
- Electronics:Electronic-grade platinum salts for advanced packaging applications remain underpenetrated relative to gold alternatives.
- Chemical Synthesis:Chloroplatinic acid derivatives serve as hydrosilylation catalysts in silicone production and cross-coupling reagents.
Catalysts command the largest volume position, while Anticancer Drugs are gaining share fastest on NMPA acceleration and EMA post-market surveillance expansion.
End User:
Customer type determines specification stringency, with pharmaceutical manufacturers demanding EMA-compliant pharmacovigilance databases that smaller compound producers cannot sustain.
- Pharmaceuticals:Oncology-focused drug manufacturers procure platinum APIs under single-source hospital purchasing consortia contracts with price-adjustment mechanisms. Tier-one oncology centers in China's provincial procurement platforms aggregate demand from multiple affiliated hospitals, compressing margins for generic API suppliers competing on batch-release speed.
- Electronics Manufacturers:Semiconductor fabricators specify refined powder grades for deposition processes with contamination thresholds measured in parts per billion.
- Chemical Industries:Petrochemical and fine chemical producers consume industrial-grade catalyst precursors subject to REACH registration dossiers.
- Research Institutions:Academic laboratories drive platinum(IV) prodrug development through sponsored research agreements with state-backed funding aligned to Beijing's dual carbon goals.
Pharmaceuticals anchor the volume ranking, with Research Institutions expanding most quickly on hydrogen energy catalyst research redirection.
Form:
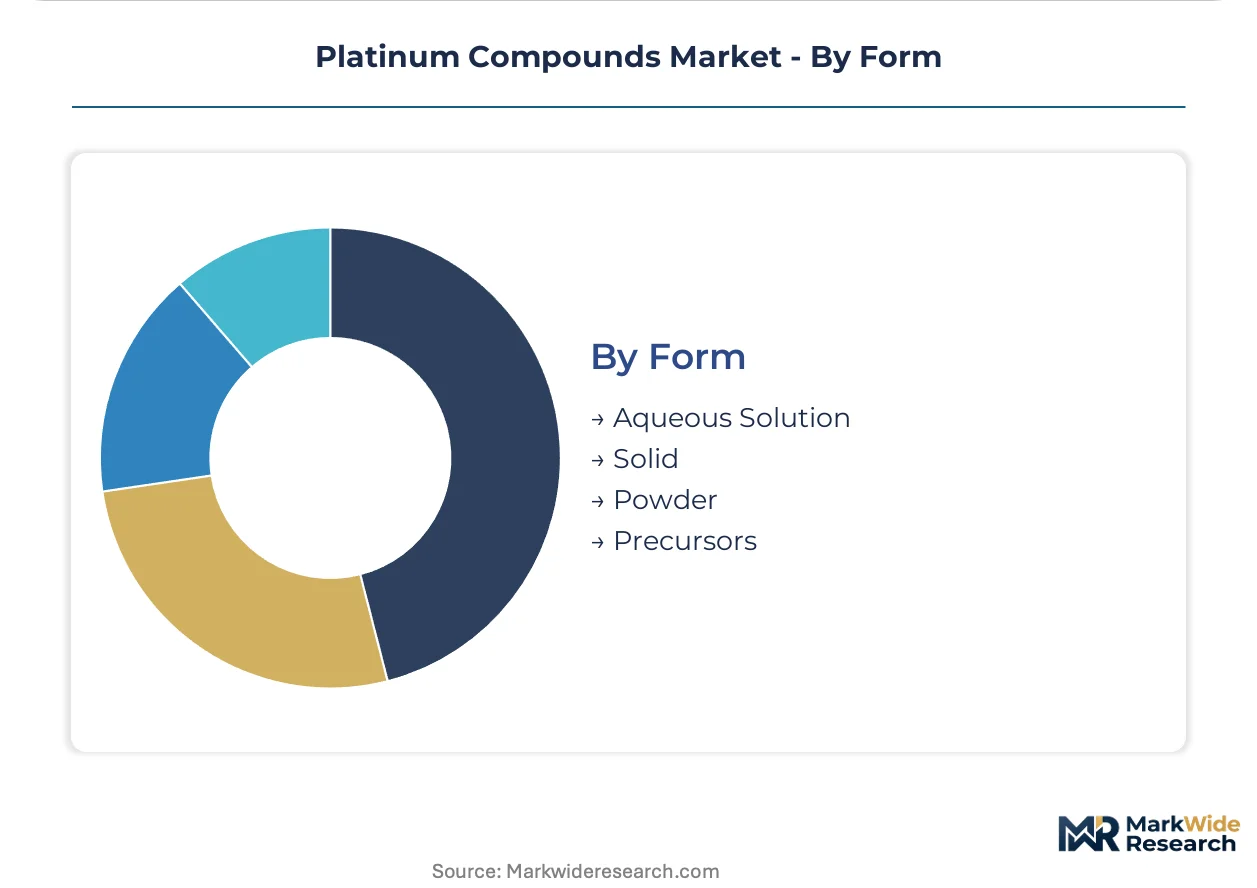
Supply concentration in aqueous solution production reflects the specialized expertise required for aqua regia dissolution and controlled reduction chemistry.
- Aqueous Solution:Chloroplatinic acid solutions serve as the primary feedstock for downstream platinum compound synthesis, with aging workforces at European and Japanese refiners concentrating specialized knowledge.
- Precursors:Intermediate compounds for chemical vapor deposition and atomic layer deposition enable precise thickness control in fuel cell electrode manufacturing.
- Powder:Refined platinum powders meet semiconductor deposition standards with particle size distributions specified by Heraeus Holding for bimetallic systems.
- Solid:Crystalline platinum compounds support long-term storage stability for pharmaceutical API manufacturing.
Aqueous Solution leads by volume, with Precursors showing the steepest expansion trajectory on fuel cell electrode demand growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China compresses approval timelines for generic platinum cytostatics while South Africa concentrates 70% of global ore feedstock, creating divergent supply and demand dynamics across major markets.
United States
FDA current Good Manufacturing Practice standards govern batch consistency for injectable platinum APIs used in oncology protocols. Academic medical centers in Boston and Houston advance platinum(IV) prodrug candidates through Phase II trials. The National Cancer Institute sponsors research into reduced-toxicity analogues for immuno-oncology combinations.
China
NMPA acceleration expands domestic manufacturing of cisplatin and oxaliplatin APIs for tier-one oncology centers. Provincial procurement platforms in Beijing and Shanghai aggregate hospital demand under single-source contracts. State-backed research funding aligns with dual carbon goals to redirect platinum catalyst demand toward hydrogen energy applications.
Germany
REACH registration mandates under ECHA create compliance barriers favoring established refiners with existing toxicological dossiers. The Rhine-Ruhr chemical corridor hosts specialized facilities for chloroplatinic acid synthesis. EMA pharmacovigilance requirements extend post-market surveillance obligations for platinum-containing injectables.
South Africa
Anglo American Platinum and Impala Platinum Holdings Limited sustain mine-to-market verticality controlling concentrate quality. Labor disruptions and energy constraints expose pharmaceutical and catalyst manufacturers to supply volatility. The Bushveld Complex anchors global ore feedstock for pharmaceutical-grade output.
Japan
METI oversees standards for electronic-grade platinum salts used in semiconductor deposition processes. Aging workforces at Osaka and Tokyo refiners concentrate specialized knowledge in aqua regia dissolution chemistry. Domestic pharmaceutical manufacturers rely on imported APIs while maintaining in-house catalyst precursor production.
Platinum Compounds Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade supply chains, while mid-tier refiners compete on industrial catalyst precursors under REACH registration mandates. The vendor base stratifies across mine-to-market integrated miners, precious metals trading houses with long-term contract infrastructure, and specialized powder refiners meeting semiconductor purity benchmarks. Strategic archetypes include vertical integrators controlling concentrate quality, trading specialists embedding price-adjustment clauses, and deposition-grade powder specialists. Dominant competitive moves encompass backward integration into mining assets and portfolio diversification toward fuel cell electrode materials.
Among mine-to-market integrated players, Anglo American Platinum exemplifies upstream control over pharmaceutical-grade concentrate quality. Johnson Matthey occupies a position representing precious metals trading infrastructure with embedded price-adjustment mechanisms. Heraeus Holding anchors the specialized powder tier serving semiconductor deposition standards.
| Leading Market Players |
|---|
| Umicore |
| Anglo American Platinum |
| Impala Platinum Holdings Limited |
| Johnson Matthey |
| Sibanye-Stillwater |
| Norilsk Nickel |
| Heraeus Holding |
| Northam Platinum Limited |
| Glencore |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange platinum pricing cascades through pharmaceutical and industrial supply chains, embedding volatility clauses into long-term contracts that separate pharmaceutical-grade APIs from commodity catalyst precursors. South African concentrate supply concentration amplifies this transmission mechanism, forcing refiners to maintain dual pricing tiers validated under divergent regulatory standards.
Pricing Analysis
Capacity additions in China's pharmaceutical manufacturing base are reshaping price floors for generic platinum cytostatics. Contract-based long-term offtake dominates, with price differentiation hinging on EMA pharmacovigilance compliance and FDA batch validation tiers. Cost compression in standard-grade catalyst precursors is intensifying because REACH registration barriers limit supplier pools. Hospital purchasing consortia in China exhibit highest price sensitivity, while semiconductor fabricators purchasing electronic-grade salts show lowest sensitivity due to purity-contamination risk premiums.
Supply Chain Analysis
Beijing's dual carbon procurement preferences and domestic-content mandates for hydrogen energy catalysts are reshaping sourcing patterns for state-backed research institutions. The supply chain draws from South Africa, China, and Russia for ore feedstock, with chloroplatinic acid synthesis and bimetallic powder refinement as critical processing stages. Single-source vulnerability concentrates at the Bushveld Complex mining operations. Distribution runs through precious metals trading houses with embedded price-adjustment infrastructure, then branches to pharmaceutical compounders or industrial catalyst formulators based on purity specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platinum compounds market represents a late-cycle quality story where pharmaceutical-grade purity requirements and fuel cell electrode specifications are elevating premium-tier demand. NMPA acceleration in China and EMA pharmacovigilance expansion in Europe are compressing margins for undifferentiated suppliers while rewarding validated manufacturers.
For Market Incumbents: Hedge concentrate supply exposure through backward integration into South African mining assets or long-term offtake agreements with Anglo American Platinum. Secure EMA-compliant pharmacovigilance databases to defend hospital procurement tender access against smaller API producers. Palladium substitution in automotive catalytic converters threatens traditional trading volumes; redirect metallurgical capacity toward pharmaceutical-grade and fuel cell electrode specifications. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms in China's tier-one oncology centers offer the most penetrable route for generic platinum cytostatic suppliers. Target electronic-grade platinum salts for advanced semiconductor packaging, where RoHS tightening and underpenetration relative to gold alternatives create whitespace. Pursue sponsored research agreements with German and U.S. academic medical centers advancing platinum(IV) prodrug candidates through Phase II trials. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized powder refiners possessing semiconductor deposition expertise and existing REACH registration portfolios. The five-to-ten year viability window favors compound manufacturers with parallel pharmaceutical and industrial production lines, given cross-contamination control capital requirements that deter pure-play entrants. Watch NMPA approval velocity for generic oncology APIs as the inflection signal for Chinese domestic manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Anglo American Platinum's Bushveld Complex verticality secures concentrate quality for pharmaceutical-grade output. |
| EMA Pharmacovigilance Database Investment | European compound manufacturers absorb surveillance costs to maintain hospital procurement tender eligibility. |
| Platinum(IV) Prodrug Pipeline Development | German and U.S. academic medical centers advance reduced-toxicity candidates through Phase II immuno-oncology combinations. |
| Fuel Cell Electrode Material Diversification | Platinum-ruthenium bimetallic systems capture hydrogen energy demand redirected by Beijing's dual carbon procurement. |
| Electronic-Grade Salt Purity Certification | Heraeus Holding's refined powder specifications meet RoHS tightening for semiconductor deposition alternatives to gold. |
Study Parameters
Direct dialogue with pharmaceutical manufacturing executives, oncology procurement managers at Chinese tier-one hospitals, precious metals trading specialists, and chloroplatinic acid synthesis technicians grounded the qualitative foundation. Secondary validation drew from FDA current Good Manufacturing Practice guidance documents, EMA pharmacovigilance safety databases, NMPA generic approval filings, and London Metal Exchange platinum price series. Bottom-up segmentation modeling and top-down macroeconomic anchoring were triangulated to ensure cross-verification across stakeholder perspectives and published regulatory sources.
Bottom-up volume and value outputs reflect patient-treatment projections for oncology APIs, fuel cell stack deployment trajectories, and semiconductor packaging demand curves across the analysis window. Segmentation dimensions encompassed oxidation state chemistry, application-grade purity tiers, end-user specification stringency, and regional regulatory cluster alignment. CAGRs were derived from weighted average growth contributions across pharmaceutical, catalytic, and electronic demand channels, with hydrogen energy catalyst research funding flows and NMPA approval velocity as industry-specific forecast inputs.
The model assumes a particular technology adoption path for proton exchange membrane fuel cell commercialization; alternative pathways for solid-oxide or alkaline electrolysis would alter platinum-ruthenium demand outlooks. Forecasts reflect assumptions regarding South African mining labor stability, REACH registration enforcement consistency, and NMPA generic approval timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminium Collars Market
Metals
GCC Metal Forging Market
Metals
Global Tin Market
Metals
Powder Metallurgy Market
Metals
Metal Recycling Market
Metals
Europe Aluminum Extrusion Market
Metals
United States Aluminum Extrusion Market
Metals
Global Copper Sputtering Target Market
Metals
Seamless Stainless Steel Products Market
Metals
Global Brass Rods Market
Metals
Global Tantalum Market
Metals
US Metal Fabrication Market
Metals
Galvanizing Market
Metals
Molybdenum Market
Metals
Potassium Platinochloride Market
Metals
Copper and Brass Flat Products Market