
 North America Metal Casting Market | 2026-2036
North America Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Casting Market Insights
Aftermarket service revenue is reshaping profitability pools across the North America metal casting value chain. Pace Industries leverages its multi-plant footprint to dominate high-volume aluminum die casting for automotive transmission housings. Gibbs Die Casting Group anchors its position through captive magnesium and aluminum capacity serving Tier-1 powertrain suppliers. Shiloh Industries differentiates via process automation and lightweighting expertise for electric vehicle structural castings.
Metal casting encompasses the pouring of molten ferrous or non-ferrous alloys into shaped molds to produce engineered components with tolerances typically ranging from ±0.5 mm to ±3 mm depending on process control. The technique generates near-net-shape parts for load-bearing applications where machining from solid stock would waste material and extend cycle times. Die casting commands the largest value share among product types owing to its dimensional repeatability and surface finish quality suited to mass production. Sand casting retains structural importance for large ferrous components in heavy machinery and energy equipment where low tooling costs offset slower cycle speeds. Investment casting posts the fastest expansion trajectory as aerospace and medical device OEMs specify complex geometries in titanium and cobalt-chrome alloys that resist conventional machining.
EPA foundry MACT standards and OSHA permissible exposure limits for respirable crystalline silica directly elevate capital requirements for emission control and worker protection equipment. The Department of Commerce Section 232 tariffs on imported steel and aluminum reshape raw material sourcing economics for captive melt operations. State-level environmental regulations in California and Michigan add compliance layering that favors larger facilities with dedicated regulatory staff. Stakeholders must weigh reshoring premiums against automation payback periods when evaluating greenfield capacity decisions.
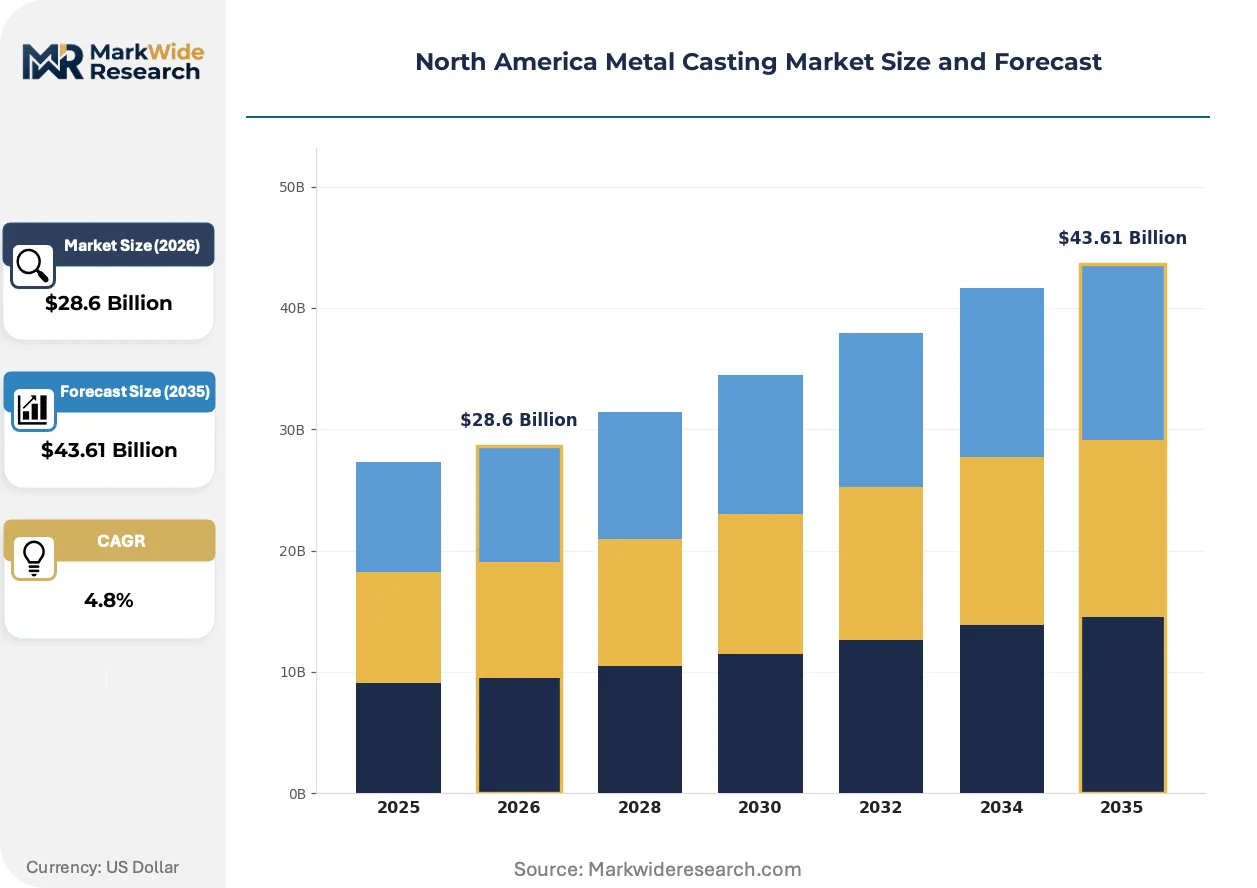
Market Dynamics
EPA foundry MACT standards and OSHA silica exposure limits are compressing foundry economics across the Great Lakes corridor, forcing capital reallocation toward emission controls and automation while reshoring premiums reshape greenfield investment calculus.
Growth Catalysts
- Aerospace OEM specifications:Lightweight titanium and nickel superalloy castings for airframe and engine components are pulling capacity expansion across Michigan, Ohio, and Indiana foundry clusters.
- Clean Air Act compliance:EPA emissions standards are accelerating foundry consolidation toward larger facilities with dedicated environmental engineering staff and captive scrubber systems.
- Electric vehicle structural demand:Battery enclosure and motor housing castings in aluminum and magnesium alloys are displacing stamped steel assemblies in Detroit Three supply chains.
Market Restraints
- Scrap aluminum price volatility:Section 232 tariff distortions on imported primary metal create input cost instability for captive melt operations in Indiana and Ohio.
- Silica exposure liability:OSHA permissible exposure limits for respirable crystalline silica impose recurring PPE, monitoring, and ventilation capital burdens on sand casting facilities.
- Investment casting substitution:Additive manufacturing of titanium aerospace brackets is eroding geometric-complexity premiums previously captured by lost-wax foundries.
Strategic Opportunities
- Canadian reshoring corridors:Ontario's proximity to Detroit powertrain clusters offers tariff-advantaged aluminum die casting capacity for cross-border Tier-1 supply.
- Medical device cobalt-chrome expansion:Orthopedic implant OEMs are qualifying additional investment casting sources for complex acetabular cups and femoral stems.
- State-level clean manufacturing incentives:Michigan business development grants for emission-control retrofits are offsetting MACT compliance costs for mid-cap foundries.
Industry Challenges
- Toolmaker and patternmaker attrition:Sand casting facilities face acute shortages of skilled craftsmen capable of hand-finishing complex core assemblies for energy equipment castings.
- Legacy ERP integration:Foundries adopting real-time melt monitoring and predictive maintenance sensors struggle to interface new data streams with decades-old production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Casting Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand Casting, Die Casting, Investment Casting, Centrifugal Casting Industry Vertical: Aerospace, Automotive, Oil & Gas, Heavy Machinery Technology: 3D Printing, Green Sand, Cold Box, Hot Box End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fabricators |
| Companies Covered | Foundrion Group, Quaker City Castings, Inc., Gibbs Die Casting Group, Midwest Metal Products, Inc., CAB Worldwide, Pace Industries, Benton Foundry Inc., Brost Foundry Co., Shiloh Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Casting Market Trends and Innovations
Digital thread technologies are penetrating foundry floor operations from melt chemistry to dimensional inspection, compressing feedback loops between casting simulation and first-article qualification.
Computational fluid dynamics coupled with thermal simulation software is digitizing gating and riser design for aluminum permanent mold operations. Tier-1 automotive suppliers in Ohio are deploying these tools to reduce porosity defects and shrink lead times for transmission housing prototypes. The technology is digitizing what previously required multiple physical iterations and skilled patternmaker judgment.
EPA's pending updates to foundry MACT standards for hazardous air pollutants are mandating enhanced fume capture and thermal oxidizer upgrades across ferrous sand casting operations. The regulatory pressure is accelerating facility consolidation as smaller Michigan job shops lack capital for compliant scrubber installations. Heavy machinery and energy equipment segments with large ductile iron casting demand face the steepest compliance cost escalation.
Powertrain procurement teams at Detroit Three OEMs are compressing supplier qualification cycles and demanding real-time defect traceability via cloud-based quality portals. Tier-1 die casters in Indiana are replacing periodic audit relationships with continuous data sharing agreements. This behavioral shift is most pronounced in electric vehicle programs where battery enclosure castings require 100% radiographic inspection documentation.
North America Metal Casting Market Segmentation
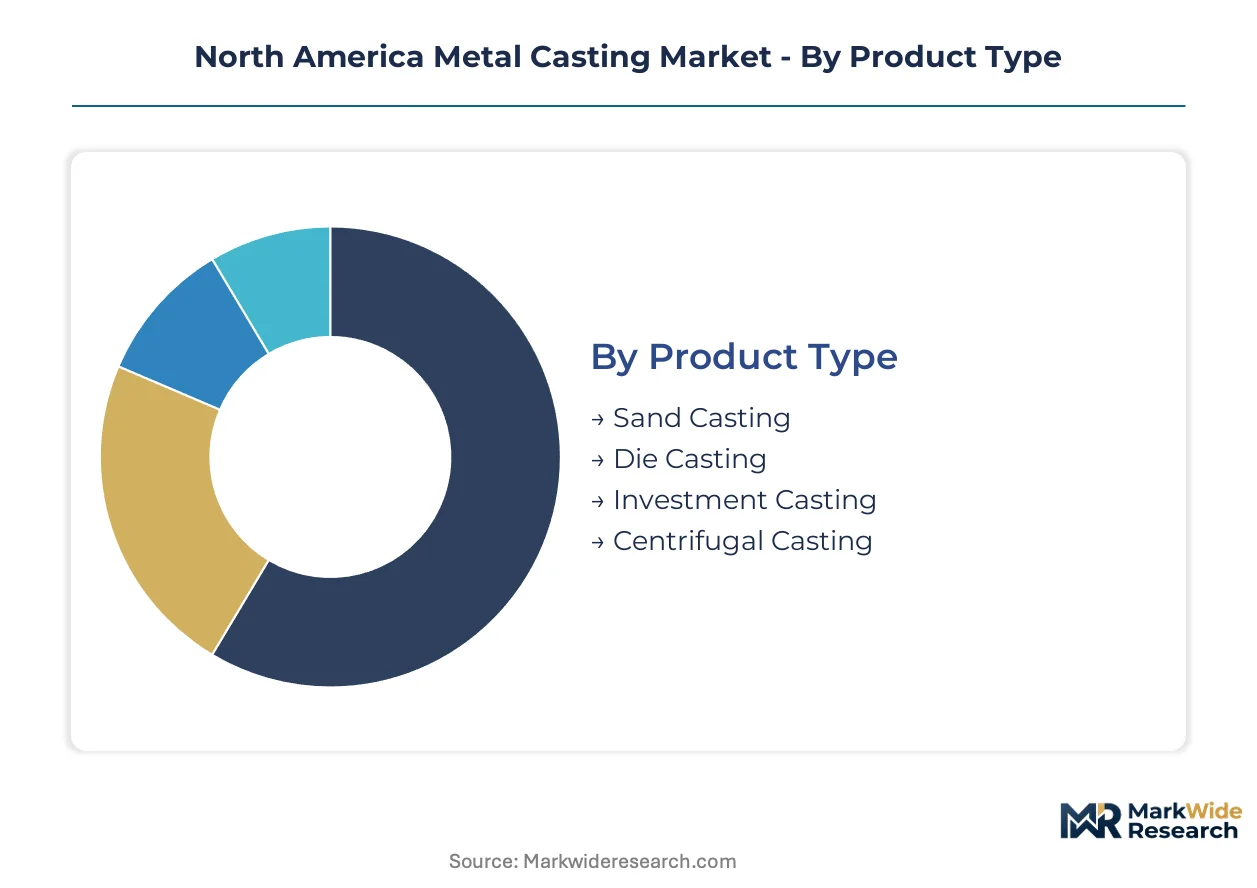
Process selection in North American metal casting hinges on dimensional tolerance requirements, production volume economics, and alloy compatibility. Each segmentation dimension reveals distinct competitive dynamics across the Great Lakes industrial corridor and Canadian reshoring corridors.
Product Type:
Use-case spectrum spans from single-digit prototype runs to million-unit automotive programs, with process economics dictating foundry specialization across Michigan, Ohio, and Indiana clusters.
- Die Casting:High-pressure injection of molten aluminum or magnesium into hardened steel dies achieves dimensional repeatability within ±0.1 mm. Automotive transmission housings and electric vehicle battery enclosures in Indiana and Ohio pull capacity expansion as Detroit Three OEMs displace stamped steel assemblies. Tooling costs exceeding $250,000 per die set favor dedicated high-volume programs.
- Sand Casting:Green sand or chemically bonded molds accommodate ferrous alloys in single-piece castings exceeding 50 tons. Heavy machinery and energy equipment manufacturers across the Great Lakes corridor specify ductile iron components where low pattern costs offset slower cycle speeds. EPA MACT compliance costs disproportionately burden smaller job shops lacking captive scrubber systems.
- Investment Casting:Lost-wax ceramic shell processes yield near-net-shape titanium and cobalt-chrome geometries. Aerospace OEMs in California and medical device manufacturers specify complex brackets and orthopedic implants resisting conventional machining.
- Centrifugal Casting:Rotational force distributes molten metal against mold walls for cylindrical symmetry. Pipe and bearing applications in oil & gas equipment leverage the process for dense, directional grain structures.
Established volume favors die casting; emerging adoption favors investment casting.
Industry Vertical:
Customer concentration and qualification cycles vary dramatically, with automotive procurement compressing supplier onboarding while aerospace mandates multi-year certification protocols.
- Automotive:Powertrain and structural castings dominate aluminum and magnesium demand as electrification reshapes material specifications. Tier-1 suppliers in Michigan and Ohio operate captive melt capacity or sole-source relationships with high-volume die casters. Real-time defect traceability via cloud portals is becoming contractual standard.
- Aerospace:Airframe and engine OEMs specify titanium and nickel superalloy castings with 100% radiographic inspection documentation. Michigan and Indiana foundry clusters are expanding vacuum investment casting capacity to serve Boeing and Gulfstream supply chains.
- Oil & Gas:Downhole equipment and valve bodies in corrosion-resistant alloys require sand casting expertise for thick-walled pressure containment. Houston-area fabricators source from Ohio ferrous foundries with NORSOK qualification.
- Heavy Machinery:Construction and mining equipment frames in ductile iron specify sand casting for load-bearing weldments. Caterpillar and Deere procurement teams prioritize proximity to Midwest machining centers.
Procurement concentration sits with automotive; margin expansion concentrates in aerospace.
Technology:
Process control sophistication determines scrap rates, energy intensity, and regulatory compliance burden across captive and job-shop operations.
- 3D Printing:Binder jet and sand printing of complex cores eliminates patternmaking lead times. Ohio automotive suppliers deploy the technology for transmission housing prototypes, compressing iteration cycles from weeks to days.
- Green Sand:Clay-bonded silica molds remain dominant for ferrous castings in heavy machinery. Michigan foundries face OSHA silica exposure liability requiring ventilation upgrades and respiratory protection programs.
- Cold Box:Phenolic urethane no-bake binders enable rapid core production for aluminum permanent molds. Indiana die casters favor the chemistry for dimensional stability in thin-wall automotive castings.
- Hot Box:Heated core boxes with furan resins suit high-volume production of small, intricate cores. The process commands premium economics in aerospace investment casting workflows.
Environmental compliance favors cold box adoption; geometric complexity favors 3D printing integration.
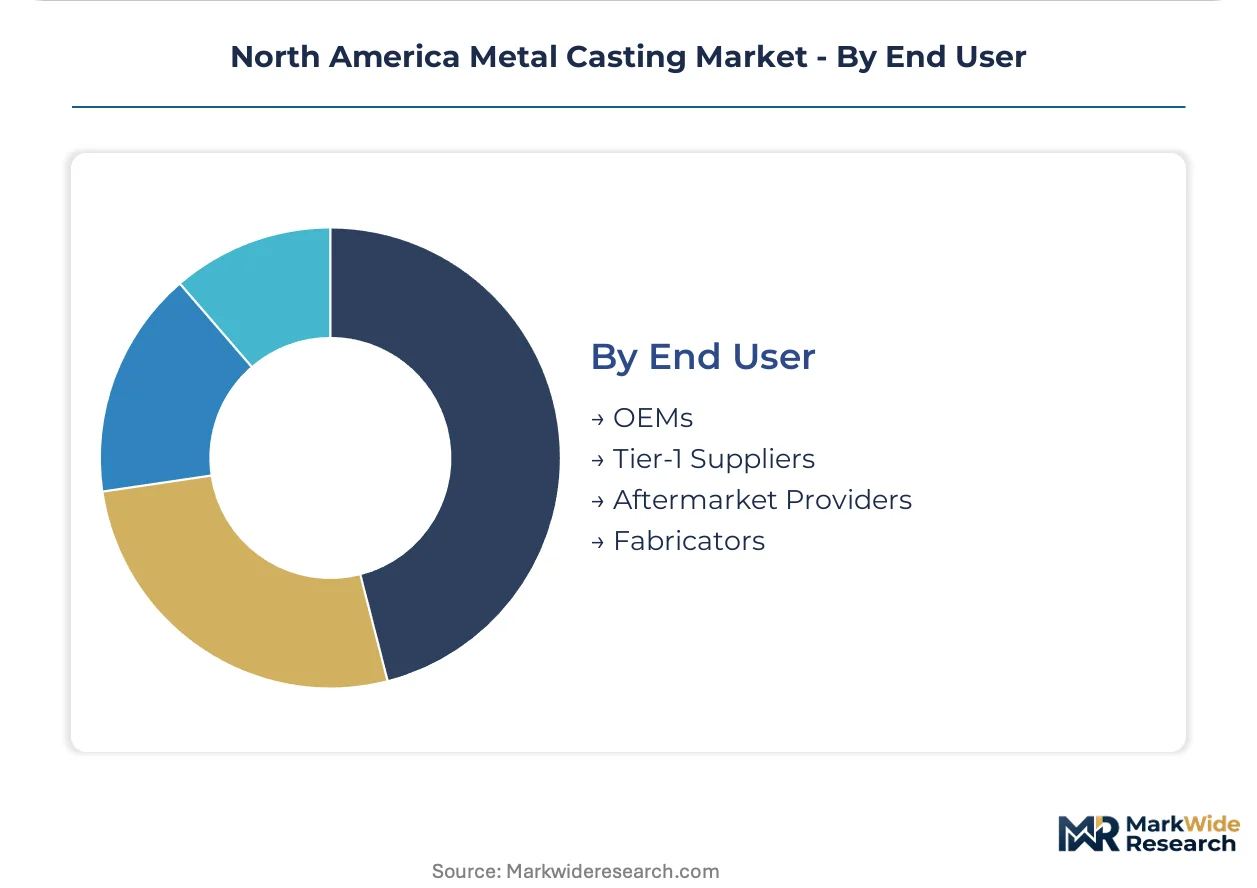
End User:
Supply chain position dictates technical specification authority, inventory risk allocation, and aftermarket service revenue capture.
- OEMs:Detroit Three and major aerospace manufacturers retain design authority and direct foundry relationships for critical castings. Ford and GM procurement teams are consolidating supplier bases toward Tier-1 die casters with multi-plant footprints.
- Tier-1 Suppliers:Magna, Lear, and similar integrators operate captive casting capacity or strategic partnerships for powertrain housings and structural nodes. Their qualification standards are becoming industry benchmarks.
- Aftermarket Providers:Independent distributors and remanufacturers source replacement castings for legacy equipment. Service revenue pools are reshaping profitability across the value chain.
- Fabricators:Job shops and weldment specialists procure rough castings for secondary machining and assembly. Price sensitivity is acute in this segment, favoring Mexican and Canadian import competition.
Specification authority concentrates with OEMs; margin resilience concentrates with aftermarket providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity clusters along the Great Lakes industrial corridor, with Michigan, Ohio, and Indiana anchoring ferrous and non-ferrous output. EPA foundry MACT standards and OSHA silica exposure limits are compressing economics and accelerating consolidation toward larger, compliant facilities.
United States
Detroit Three OEM procurement teams are consolidating supplier bases toward Tier-1 die casters with multi-plant footprints for electric vehicle battery enclosures. EPA foundry MACT standards mandate enhanced fume capture and thermal oxidizer upgrades across ferrous sand casting operations. Indiana and Ohio foundry clusters are expanding vacuum investment casting capacity to serve Boeing and Gulfstream aerospace supply chains.
Canada
Ontario's proximity to Detroit powertrain clusters offers tariff-advantaged aluminum die casting capacity for cross-border Tier-1 supply. Health Canada and PMRA coordinate with EPA on emissions benchmarking for foundries operating near the Great Lakes basin. Windsor and Hamilton industrial corridors host magnesium and aluminum die casting operations serving Magna and Lear procurement networks.
Mexico
Nuevo León and the Bajío Region attract reshoring investment from US-based fabricators seeking labor cost arbitrage for automotive structural castings. Mexican environmental regulators align SEMARNAT standards with EPA protocols for cross-border supply chain compliance. Querétaro and San Luis Potosí foundry parks are qualifying new capacity for Detroit Three electric vehicle programs.
North America Metal Casting Market Competitive Landscape
Multi-plant die casting specialists and regional sand casting job shops split the market across volume-tiered segments. Consolidation pressure from EPA compliance costs favors larger facilities with dedicated environmental engineering staff. Three archetypes dominate: captive melt operations serving single OEM programs, independent high-volume die casters with automation scale, and specialized investment casting foundries for aerospace qualification. Competitive moves center on M&A absorption of distressed mid-cap facilities and strategic partnerships for real-time defect traceability systems.
Within the high-volume die casting tier, Pace Industries and Gibbs Die Casting Group exemplify multi-plant footprint strategies. Shiloh Industries occupies a position at the automation-intensive end of the structural casting segment. Among regional sand casting specialists, Benton Foundry Inc. and Quaker City Castings, Inc. represent the independent job-shop archetype facing acute silica exposure liability and toolmaker attrition challenges.
| Leading Market Players |
|---|
| Foundrion Group |
| Quaker City Castings, Inc. |
| Gibbs Die Casting Group |
| Midwest Metal Products, Inc. |
| CAB Worldwide |
| Pace Industries |
| Benton Foundry Inc. |
| Brost Foundry Co. |
| Shiloh Industries |
| Others |
Pricing and Supply Chain Analysis
Section 232 tariff exposure on imported primary aluminum and steel determines both the premium-mid-economy pricing differentiation across die casting tiers and the geographic concentration of captive melt capacity in Indiana and Ohio.
Pricing Analysis
EPA foundry MACT standards dictate the pricing tier structure by imposing fixed compliance costs that smaller sand casting job shops cannot absorb. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified investment casters from automotive die casters and commodity ferrous job shops. Cost compression in the economy tier is intensifying because Mexican and Canadian import competition captures fabricator demand. Tier-1 automotive suppliers exhibit least price sensitivity due to sole-source qualification requirements, while independent fabricators demonstrate acute sensitivity to landed cost differentials.
Supply Chain Analysis
Scrap aluminum and primary magnesium feedstock draws from Canadian smelters, domestic secondary processors, and tariff-affected imports from China and Russia. Cold box binder chemicals and ceramic shell refractories rest on specialized chemical suppliers in Ohio and Pennsylvania. Single-source vulnerability concentrates in high-purity titanium sponge for aerospace investment casting. Distribution runs through Tier-1 supplier consolidation toward Detroit Three OEMs, with aftermarket channels serving legacy equipment remanufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
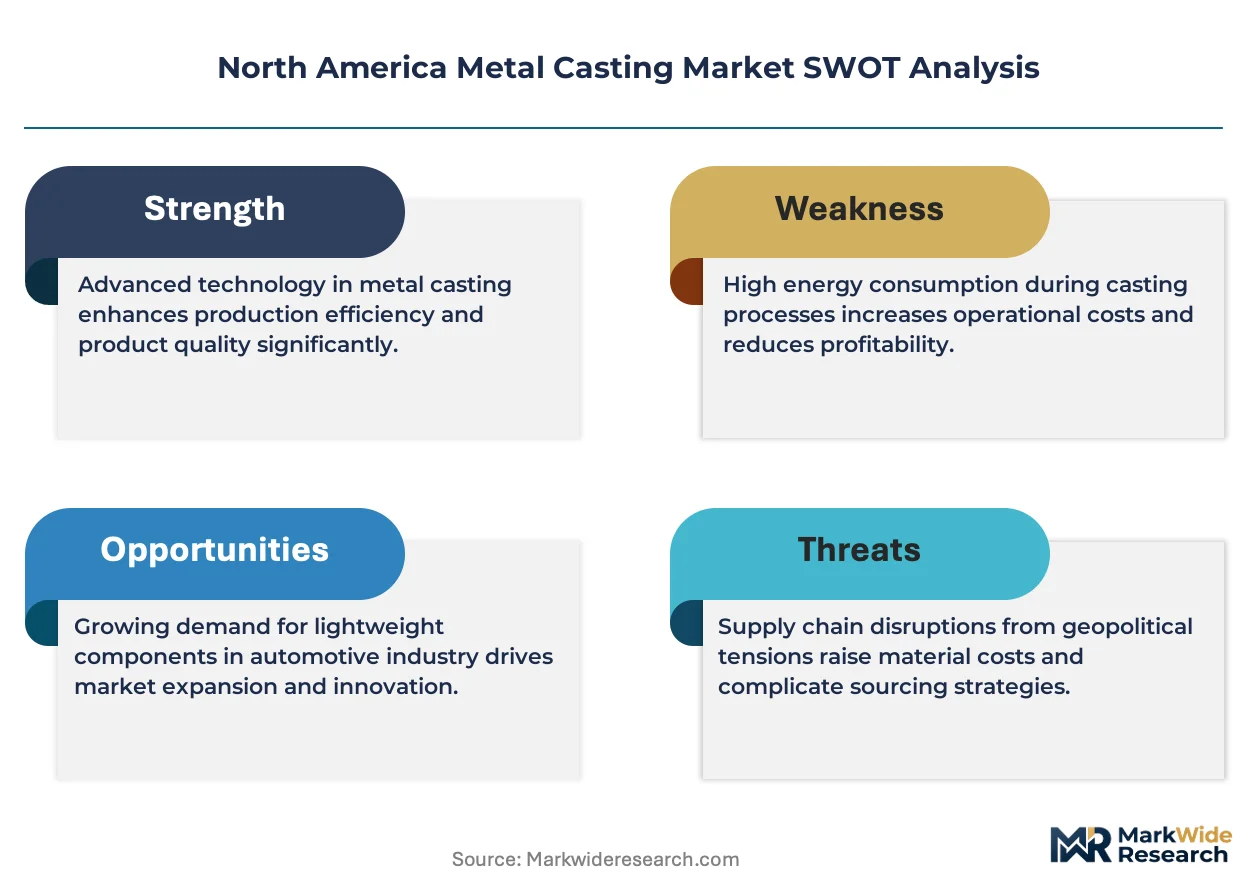
Additive manufacturing of titanium aerospace brackets threatens geometric-complexity premiums that investment casting foundries have historically captured. Incumbents must defend against this substitution while navigating EPA compliance cost escalation.
For Market Incumbents: Pre-empt additive substitution by qualifying hybrid casting-forging workflows for complex titanium brackets before Boeing and Gulfstream procurement teams complete AM supplier onboarding. Absorb distressed mid-cap sand casting facilities in Michigan to capture EPA-compliant capacity at distressed asset valuations. Vertical integration into captive scrap processing insulates against Section 232 tariff volatility. For New Entrants and Emerging Players: Build out Canadian reshoring corridors in Windsor and Hamilton to exploit tariff-advantaged aluminum supply for cross-border Tier-1 die casting contracts. Target medical device orthopedic implant casting as the most penetrable segment, where FDA qualification timelines deter incumbent expansion. Lead with real-time defect traceability portals that match Detroit Three contractual standards. For Investors and Strategic Acquirers: EPA's pending MACT standard updates reshape the acquisition landscape by accelerating distressed facility availability across the Great Lakes corridor. Mid-cap ferrous sand casters with compliant scrubber installations represent the priority acquisition archetype for consolidation plays. Watch for OSHA silica enforcement actions in Michigan as the signal indicating further capacity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt Capacity Expansion | Insulates Tier-1 suppliers from Section 232 tariff exposure on imported primary aluminum. |
| Emission-Control Retrofit Program | Qualifies Michigan sand casters for Michigan business development grants offsetting MACT compliance. |
| Real-Time Defect Traceability Portal | Meets Detroit Three contractual requirements for 100% radiographic inspection documentation. |
| Canadian Cross-Border Footprint | Exploits tariff-advantaged aluminum supply for Magna and Lear procurement networks. |
| Medical Device Qualification Pathway | Captures orthopedic implant OEM demand for cobalt-chrome acetabular cup casting. |
Research Methodology
Operator-level perspectives from foundry plant managers, Tier-1 supplier procurement leads, EPA compliance officers, and aftermarket distribution heads anchored the qualitative base. Primary interviews combined with secondary validation against EPA enforcement databases, OSHA silica exposure incident reports, Department of Commerce Section 232 tariff filings, and Detroit Three supplier quality portals. Bottom-up capacity surveys across Michigan, Ohio, and Indiana foundry clusters triangulated against top-down aluminum and magnesium consumption estimates from regional trade flows.
Scenario-bracketing framed demand projections across the analysis window, modeling process type, industry vertical, alloy category, and end-user supply chain position as core segmentation dimensions. CAGRs derived from production capacity expansion announcements, OEM program launch timelines, and regulatory compliance cost trajectories. Aerospace OEM specification shifts toward titanium superalloy castings and electric vehicle structural demand for aluminum battery enclosures served as primary volume drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing equipment suppliers or unexpected EPA enforcement surges would shift outcomes. Cross-checking against North American light vehicle production forecasts and Boeing order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Long Products Market
Metals
Ferrosilicon Market
Metals
High-End Copper Foil Market
Metals
Global Superconducting Wire Market
Metals
Galvanized Steel Coil Market
Metals
Industrial Metal Strips Market
Metals
High Carbon Bearing Steel Market
Metals
Niobium Market
Metals
Global Aluminium Wire Rod Market
Metals
Global Tantalum Market
Metals
Scandium Market
Metals
HSLA Steel Plate Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Vietnam Aluminum Market
Metals
Copper Chromium Black Market
Metals
316 Stainless Steel Container Market