
 Philippines Ceramic Tiles Market | 2026-2036
Philippines Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Ceramic Tiles Market Analytics
Multi-source procurement among large-scale distributors is consolidating around vertically integrated suppliers with captive clay reserves and in-house glazing operations. Mariwasa Siam Ceramics anchors its position through deep backward integration into local raw-material basins in Batangas and Quezon. RAK Ceramics PJSC competes on premium porcelain technology imported from its UAE-based R&D centers. Eurotiles Industrial Corporation leverages its Luzon manufacturing footprint to control logistics costs to NCR contractors.
Philippine ceramic tiles are fired clay products, typically composed of kaolin, feldspar, and silica, shaped by dry pressing or extrusion and sintered at temperatures exceeding 1,200°C to achieve Mohs hardness ratings above 5. These specifications suit high-traffic commercial floors and moisture-prone residential wet areas. Floor tiles occupy the dominant volume position due to repetitive replacement cycles in retail and hospitality fit-outs, while porcelain tiles command premium positioning for their near-zero water absorption rates below 0.5%. The residential application segment leads absolute consumption, though commercial projects generate higher per-square-meter margins through specification-grade large-format requirements.
The Department of Trade and Industry's Philippine Standard (PNS) certification and BPS product safety marks govern dimensional tolerances and lead-content thresholds, filtering out substandard imports at port of entry. The Department of Public Works and Highways' infrastructure procurement rules further channel public project demand toward locally certified manufacturers. Stakeholders must monitor pending amendments to the National Building Code of the Philippines, as proposed seismic-resilience clauses could mandate thicker, reinforced tile substrates for high-rise construction.
Market Dynamics
Metro Manila's construction boom is concentrating procurement power among vertically integrated developers who now dictate specifications directly to manufacturers, bypassing traditional distributor networks. This shift toward direct-contracting models is compressing margins for intermediaries while rewarding producers with captive raw-material reserves and in-house technical service capabilities.
Growth Catalysts
- Philippine Green Building Code compliance mandates:The Department of Public Works and Highways now requires LEED-equivalent certification for government buildings above 10,000 square meters, forcing tile selection toward low-emission, recycled-content products that local manufacturers with modern kilns can supply.
- Calabarzon industrial corridor expansion:Manufacturing zones in Laguna and Batangas are attracting Japanese and Korean electronics firms whose worker housing and cleanroom facilities demand anti-static, chemical-resistant porcelain flooring in volumes that domestic suppliers can reach within 48-hour delivery windows.
- Dry-pressed digital inkjet technology:Local producers adopting Italian-designed printing systems can now replicate natural stone and wood grain patterns at 600 dpi resolution, matching import aesthetics while undercutting landed costs from Chinese and Spanish competitors by 15-20 percent.
Market Restraints
- Natural gas price volatility:Kiln operations depend on Malampaya field supply contracts indexed to regional LNG benchmarks, and periodic shortages force manufacturers to switch to diesel-fired backup systems that raise unit energy costs by 40 percent.
- Import concentration in premium porcelain:Italian and Spanish producers control the specification-grade large-format segment above 60x120 cm, leaving domestic manufacturers competing primarily in commodity 30x30 and 40x40 formats with thinner margins.
- Kaolin reserve depletion in Quezon Province:Decades of extraction have degraded ore quality, forcing longer haul distances from Mindoro or import dependence for high-plasticity clays essential for vitrified body formulation.
Strategic Opportunities
- Visayas construction acceleration:Cebu and Iloilo are experiencing commercial and hospitality build-outs that outpace local tile supply, creating first-mover advantages for Luzon-based manufacturers willing to establish regional distribution depots.
- Cool roof tile demand from Philippine Energy Efficiency and Conservation Act incentives:Solar-reflective glazed tiles with SRI values above 29 qualify for tax deductions under building envelope improvement provisions, opening a premium product category with limited current domestic supply.
- Direct-to-contractor digital platforms:Construction material e-procurement portals such as Mule and Gawin are aggregating small contractor demand into volume bundles that manufacturers can fulfill with factory-direct pricing, disintermediating traditional three-layer distribution.
Industry Challenges
- Glaze chemist talent scarcity:Formulation expertise for zircon-opacified and matte-finish glazes resides primarily with expatriate technicians from Italy and Spain, and local engineering programs produce few specialists in ceramic materials science.
- Bureau of Product Standards certification timeline:PNS mark acquisition requires 90-120 days of third-party testing for new product lines, delaying market entry for seasonal color introductions and allowing uncertified gray-market imports to capture early demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Ceramic Tiles Market |
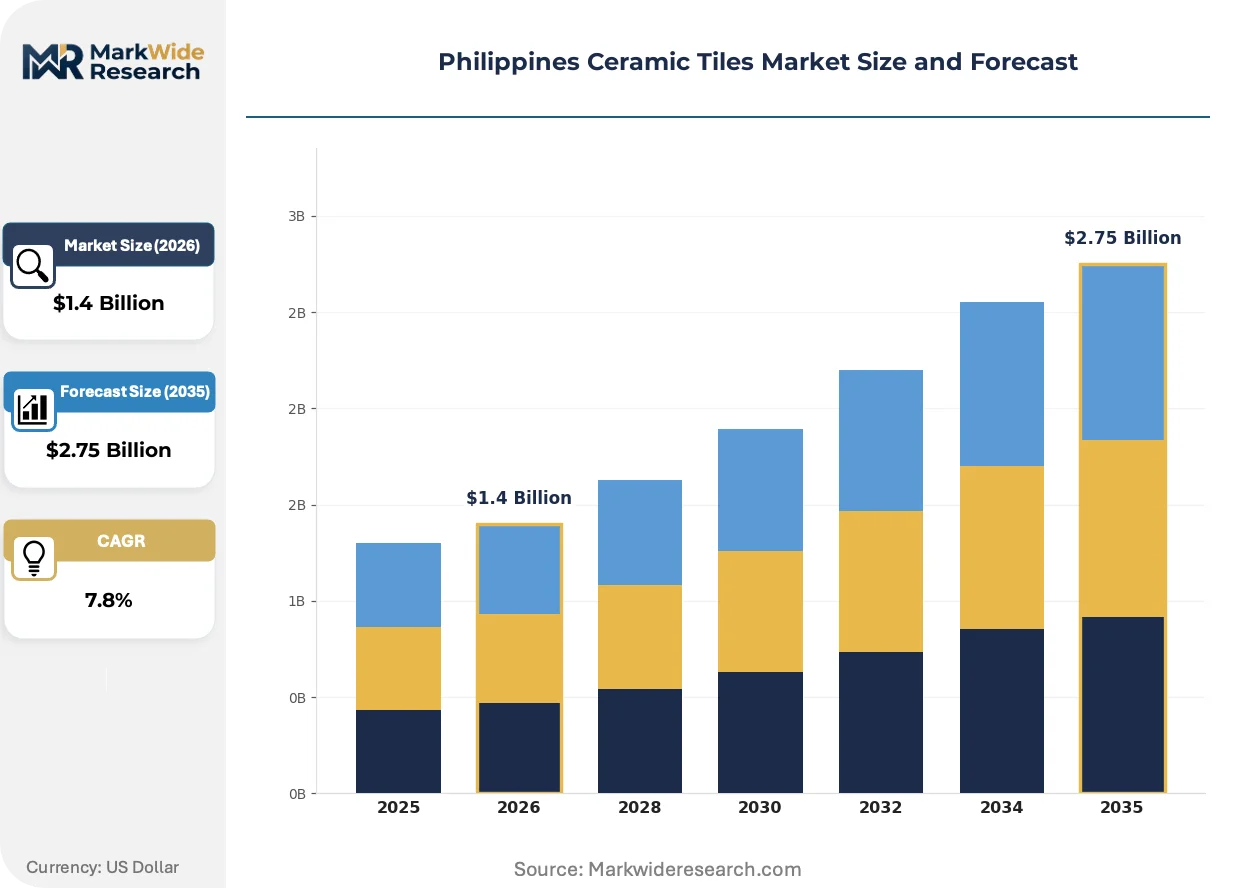
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Tiles, Floor Tiles, Porcelain Tiles, Glazed Tiles Application: Residential, Commercial, Industrial, Outdoor Material: Ceramic, Stoneware, Earthenware, Terracotta Distribution Channel: Online Retail, Home Improvement Stores, Specialty Shops, Wholesalers |
| Companies Covered | RAK Ceramics PJSC, Mohawk Industries Inc., Mariwasa Siam Ceramics Inc., China Ceramics Co. Ltd., Kajaria Ceramics Ltd., Eurotiles Industrial Corporation, PORCELANOSA Grupo, Guangdong Dongpeng Ceramic Co., Ltd., SCG Ceramics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Ceramic Tiles Market Evolving Landscape
Digital manufacturing systems and regulatory pressure on embodied carbon are converging to reshape how Philippine tile producers compete. The market is witnessing a decisive shift toward specification-grade capabilities that were previously import-dependent.
Single-pass digital inkjet decoration combined with dry-pressed body formation is rewriting the economics of premium tile production in Batangas and Bulacan plants. Large-format porcelain slabs up to 160x320 cm can now be manufactured with consistent color matching across batches, enabling local suppliers to bid on hotel and retail fit-outs that previously specified Italian imports exclusively. Mall developers in Ortigas and Bonifacio Global City are specifying these domestic alternatives for 40 percent of their flooring packages.
The Department of Trade and Industry's proposed amendments to PNS ISO 13006 are tightening water absorption and breaking strength thresholds for tiles used in high-rise construction. Manufacturers with roller-hearth kilns capable of precise temperature profiling above 1,220°C will capture public infrastructure contracts, while intermittent kiln operators face technical obsolescence. DPWH-funded school and hospital projects are already pre-qualifying bidders based on demonstrated compliance with draft standards.
Consolidation among NCR-based general contractors is concentrating purchasing decisions within fewer procurement departments, shifting negotiation leverage toward volume-commitment contracts with 90-day payment terms. Small distributors in Quezon City and Pasig are responding by forming buying cooperatives to aggregate orders and secure manufacturer-direct pricing previously reserved for national developers. This channel restructuring is most visible in mid-rise residential projects across Cavite and Laguna where cooperative members now supply 25 percent of tile packages.
Philippines Ceramic Tiles Market Segmentation
Philippine ceramic tile procurement splits across technical specifications, end-use requirements, and supply chain access points. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
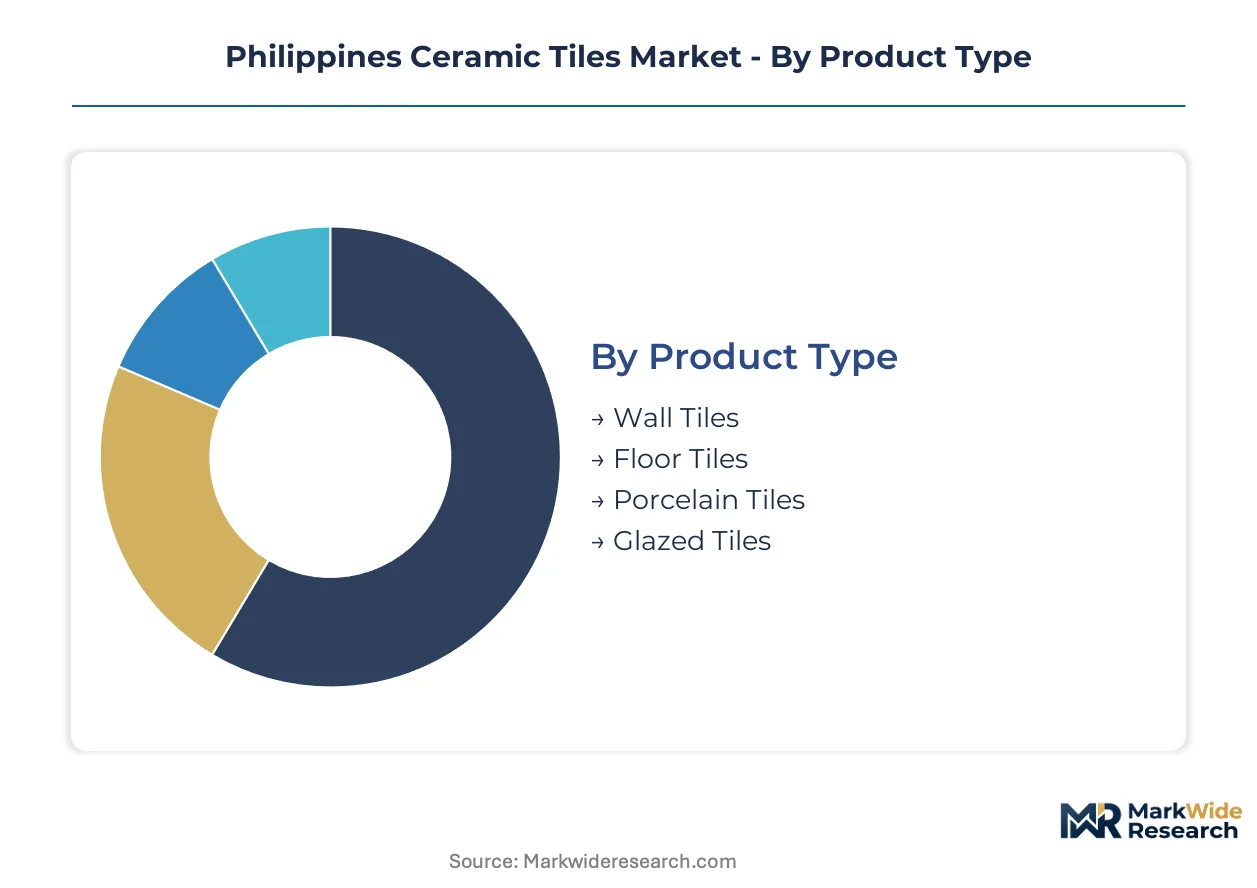
Product Type:
Technical performance thresholds separate commodity positioning from premium specification capture in Philippine tile manufacturing.
- Wall Tiles:Lower-density ceramic bodies with water absorption rates between 10-20% suit vertical surfacing in bathrooms and kitchens. Metro Manila condominium developers specify these for unit turnover packages where cost-per-square-meter drives procurement decisions.
- Floor Tiles:Higher-density pressed bodies fired above 1,150°C achieve Mohs hardness ratings of 5-6 for high-traffic retail and hospitality installations. Calabarzon manufacturing clusters dominate supply to NCR contractors through 48-hour delivery commitments.
- Porcelain Tiles:Vitrified bodies with sub-0.5% water absorption command specification-grade positioning for commercial projects requiring chemical resistance and freeze-thaw durability.
- Glazed Tiles:Surface-coated ceramics offering aesthetic variety through digital inkjet decoration, with glaze chemistries determining stain resistance and slip coefficients for wet-area applications.
Floor tiles lead on scale; porcelain tiles lead on momentum.
Application:
End-use differentiation determines volume concentration versus margin extraction across Philippine construction verticals.
- Residential:Single-family housing and mid-rise condominium projects generate repetitive replacement cycles, with developers in Cavite and Laguna specifying 30x30 and 40x40 formats for cost-optimized unit packages.
- Commercial:Mall fit-outs in Ortigas and Bonifacio Global City demand large-format porcelain slabs up to 160x320 cm with consistent batch color matching previously sourced from Italian imports.
- Industrial:Electronics manufacturing facilities in Calabarzon require anti-static, chemical-resistant flooring with specific resistivity ratings for cleanroom operations.
- Outdoor:Elevated installation exposure drives specification toward frost-resistant porcelain with enhanced breaking strength for Philippine tropical climate cycling.
Residential commands absolute volume; commercial generates premium margin per square meter.
Material:
Body composition and firing temperature create tiered performance categories with distinct raw-material sourcing requirements.
- Ceramic:Standard pressed clay bodies using local Batangas and Quezon kaolin deposits, fired at 1,050-1,150°C for general-purpose wall and floor applications.
- Stoneware:Higher vitrification through elevated firing temperatures and flux-rich formulations, delivering density suitable for commercial flooring with lower water absorption than standard ceramic.
- Earthenware:Porous low-fire bodies with higher water absorption, limited to decorative and non-structural applications in residential interiors.
- Terracotta:Unglazed, low-density clay products for aesthetic architectural surfacing with minimal mechanical load requirements.
Ceramic dominates production scale; stoneware gains share fastest in commercial specification.
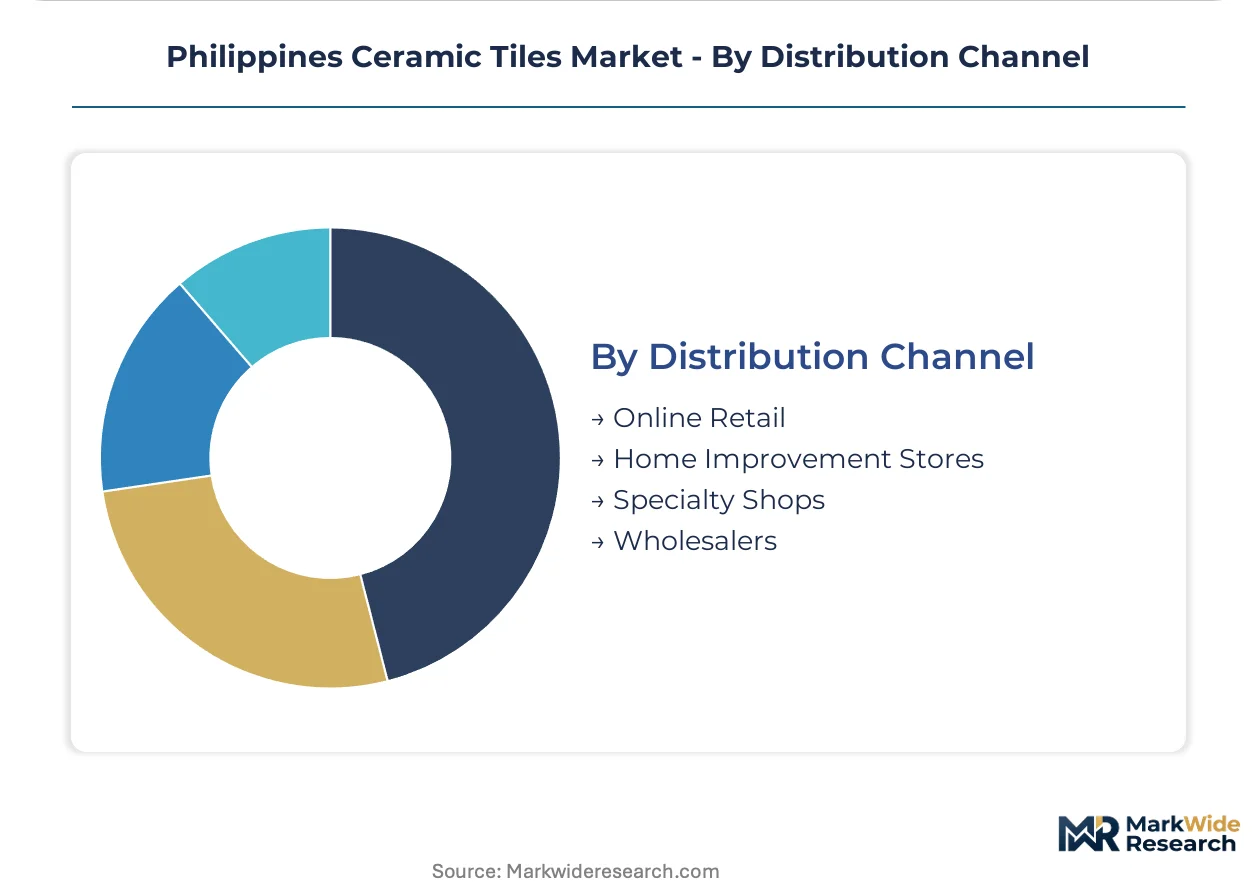
Distribution Channel:
Channel structure determines pricing transparency and manufacturer margin retention in Philippine tile supply.
- Online Retail:Construction material e-procurement portals aggregate small contractor demand into volume bundles, enabling factory-direct pricing that compresses traditional distributor margins.
- Home Improvement Stores:Wilcon Depot and CW Home Depot chains stock mid-range formats for retail walk-in and project contractor accounts, with private-label programs pressuring branded suppliers.
- Specialty Shops:Design-focused showrooms in Makati and Quezon City specify imported and domestic premium porcelain for high-end residential and hospitality projects.
- Wholesalers:Traditional three-layer distribution networks in provincial hubs face disintermediation as vertically integrated developers contract directly with manufacturers.
Wholesalers retain volume leadership; online retail expands most quickly through contractor aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calabarzon anchors Philippine ceramic tile production through its Laguna-Batangas manufacturing corridor, where kiln operations cluster within 100 kilometers of Metro Manila's construction demand epicenter. This geographic concentration shapes procurement patterns across the archipelago's three major island groups.
Metro Manila and Calabarzon
Condominium developers in Makati and Quezon City specify 30x30 and 40x40 floor tiles for mid-rise residential packages, driving repetitive volume orders. The Department of Trade and Industry's Philippine Standard certification requirements filter substandard imports at Manila and Batangas ports. Manufacturing plants in Santa Rosa and Lipa supply 48-hour delivery commitments to National Capital Region contractors through dedicated logistics fleets.
Central Visayas
Cebu's commercial and hospitality build-outs generate demand for large-format porcelain slabs that outpace local manufacturing capacity. The Philippine Green Building Code compliance mandates for government buildings above 10,000 square meters channel specification-grade procurement toward certified suppliers. Mall developers in Cebu City and Mandaue are establishing direct-contracting relationships with Luzon-based manufacturers willing to maintain regional distribution depots.
Davao Region
Mindanao's emerging residential developments in Davao City and surrounding provinces consume standard ceramic formats for cost-optimized housing projects. Bureau of Product Standards certification timelines create supply gaps that gray-market imports occasionally exploit. Construction material distributors in Davao del Sur aggregate provincial demand into volume bundles for manufacturer-direct fulfillment.
Western Visayas
Iloilo's commercial construction acceleration creates first-mover opportunities for suppliers establishing Panay Island distribution networks. The National Building Code of the Philippines pending seismic-resilience amendments could mandate thicker tile substrates for high-rise projects. Industrial zones in Iloilo City attract electronics firms whose worker housing demands anti-static flooring specifications.
Cagayan Valley
Northern Luzon agricultural processing facilities and provincial retail developments sustain modest ceramic tile consumption outside major urban corridors. Department of Public Works and Highways infrastructure procurement rules channel public school and hospital projects toward locally certified manufacturers. Tuguegarao and Santiago City serve as distribution hubs for Cordillera Administrative Region construction activity.
Philippines Ceramic Tiles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium porcelain technology and direct-to-contractor digital channels. The vendor base clusters around three strategic archetypes: vertically integrated domestic manufacturers with captive clay reserves, import-dependent distributors of specification-grade large-format products, and multinational producers leveraging overseas R&D for technology transfer. Dominant competitive moves include backward integration into raw-material basins and the formation of buying cooperatives among traditional distributors to aggregate volume leverage.
Among Philippines-based fabricators, Mariwasa Siam Ceramics Inc. exemplifies the integrated domestic archetype through its deep position in Batangas and Quezon raw-material territories. Eurotiles Industrial Corporation occupies a scale-driven position within the Luzon manufacturing footprint. RAK Ceramics PJSC represents the multinational technology-transfer tier, anchoring premium positioning through UAE-based research capabilities. These three entities illustrate the competitive vectors shaping procurement relationships with Metro Manila's consolidated developer base.
| Leading Market Players |
|---|
| RAK Ceramics PJSC |
| Mohawk Industries Inc. |
| Mariwasa Siam Ceramics Inc. |
| China Ceramics Co. Ltd. |
| Kajaria Ceramics Ltd. |
| Eurotiles Industrial Corporation |
| PORCELANOSA Grupo |
| Guangdong Dongpeng Ceramic Co., Ltd. |
| SCG Ceramics |
| Others |
Value Network & Pricing Analysis
Captive clay reserves in Batangas and Quezon anchor supply-side positioning for domestic manufacturers, translating directly into pricing power against import-dependent distributors. This backward integration into raw-material basins insulates integrated producers from kaolin reserve depletion pressures while enabling volume-commitment contracts with 90-day payment terms demanded by consolidated NCR developers.
Pricing Analysis
Natural gas price volatility indexed to Malampaya field supply contracts drives input-cost pass-through into finished tile pricing. Three-tier pricing structure across premium, standard, and economy levels separates porcelain slabs with sub-0.5% water absorption from commodity 30x30 and 40x40 ceramic formats. Cost compression in standard-grade segments is intensifying because dry-pressed digital inkjet technology allows local producers to undercut Chinese and Spanish landed costs by 15-20 percent. Small provincial contractors exhibit highest price sensitivity, while specification-grade large-format procurement for Ortigas and Bonifacio Global City mall fit-outs prioritizes batch consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Cebu and Davao extend hub-and-spoke patterns from Calabarzon manufacturing clusters, reducing delivery windows to 48 hours for NCR contractors. Philippine production draws from local Batangas and Quezon kaolin deposits, Italian-designed digital inkjet printing systems, and zircon-opacified glaze chemistries formulated by expatriate technicians. Single-source vulnerability in high-plasticity clay supply from Mindoro creates exposure as Quezon ore quality degrades. Distribution runs through vertically integrated developer direct contracts, home improvement retail chains, and emerging e-procurement portals aggregating contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippine Green Building Code functions as a regulatory compounder, mandating LEED-equivalent certification for government buildings above 10,000 square meters and forcing tile selection toward low-emission, recycled-content products that only modern kiln operators can supply.
For Market Incumbents: Extend specification-grade capabilities into large-format porcelain slabs up to 160x320 cm to capture hotel and retail fit-outs currently specifying Italian imports. Deepen captive supply of high-plasticity clays through Mindoro reserve development or long-term offtake agreements before Quezon depletion accelerates. Invest in roller-hearth kilns capable of precise temperature profiling above 1,220°C to meet pending PNS ISO 13006 amendments for high-rise seismic-resilience mandates. For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms such as Mule and Gawin to aggregate small contractor demand into volume bundles with factory-direct pricing, bypassing traditional three-layer distribution. Target Visayas construction acceleration in Cebu and Iloilo where commercial and hospitality build-outs outpace local supply, creating first-mover advantages for Luzon-based manufacturers establishing regional depots. Prioritize anti-static, chemical-resistant porcelain flooring specifications for Calabarzon electronics manufacturing facilities. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated domestic manufacturers with captive clay reserves because consolidation concentrates procurement power among fewer NCR developers demanding direct-contracting relationships. Five-to-ten year viability hinges on kiln technology modernization and glaze chemist talent development. Watch pending National Building Code seismic-resilience amendments as the inflection indicator for substrate thickness requirements and reinforced tile demand in high-rise construction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw-Material Basins | Captive clay reserves in Batangas and Quezon insulate margin pressure from kaolin depletion and import dependence. |
| Digital Inkjet Technology Adoption | Italian-designed printing systems enable 600 dpi natural stone replication while undercutting Spanish and Chinese landed costs. |
| Regional Distribution Depot Establishment | Cebu and Iloilo depots capture commercial build-out demand outpacing local Visayas manufacturing capacity. |
| Cool Roof Tile Product Line Launch | Solar-reflective glazed tiles with SRI values above 29 qualify for Philippine Energy Efficiency and Conservation Act tax deductions. |
| Direct-to-Contractor E-Procurement Platform Partnership | Construction material portals aggregate fragmented small contractor demand into manufacturer-direct volume bundles. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down kiln capacity and raw-material extraction tracking forms the analytical core. Primary interviews with plant managers at Calabarzon manufacturing clusters, procurement leads at NCR-based general contractors, distribution channel partners in Cebu and Davao, and glaze chemist expatriate technicians combine with secondary validation from Department of Trade and Industry Philippine Standard certification records, Bureau of Product Standards testing timelines, DPWH infrastructure procurement rules, and customs data on ceramic tile imports. Triangulation between demand-side project pipelines and supply-side production capacity yields volume estimates.
Input-output matrices map kaolin extraction volumes, natural gas consumption rates per kiln firing cycle, and digital decoration throughput to finished tile output across product type, application, material, and distribution channel dimensions. Growth trajectories derive from construction activity indices, green building code compliance mandates, and technology adoption curves for dry-pressed digital inkjet systems. Forecast inputs include Malampaya field supply contract volatility, Quezon reserve depletion rates, and pending National Building Code seismic-resilience amendment implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas shortage scenarios forcing diesel-fired backup systems or accelerated kaolin reserve depletion requiring Mindoro import dependence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Alumina Slurry Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Calcined Kaolin Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Strontium Carbonate Market
Ceramics
Global Ceramic Balls Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Boiler Refractory Material Market
Ceramics
Calcined Alumina Market
Ceramics
Engineering Ceramics Market
Ceramics
Graphite Crucibles Market
Ceramics
Colloidal Alumina Market
Ceramics
Vaterite Market