
 Global Tantalum Market | 2026-2036
Global Tantalum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tantalum Market Analysis
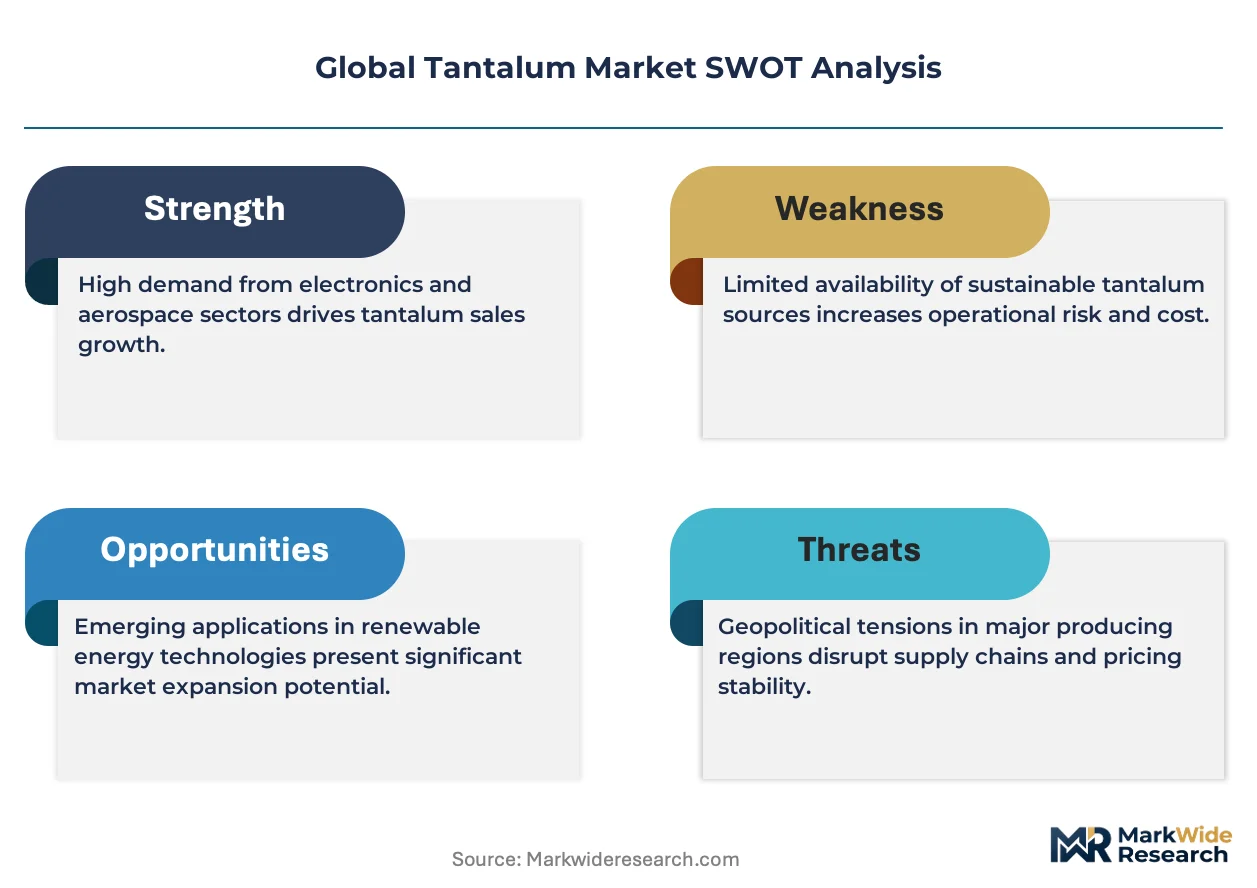
Geologist and metallurgical engineer availability is collapsing across Central African tantalum belt operations, constraining upstream expansion and forcing processors to compete for scarce technical talent. Ningxia Orient Tantalum Industry Co. Ltd dominates capacitor-grade powder output from its vertically integrated Chinese facilities. Global Advanced Metals Pty Ltd anchors Western supply security through its Australian and Ethiopian mine-to-metal pipeline. H.C. Starck GmbH specializes in high-purity tantalum for semiconductor sputtering targets, leveraging decades of German refining expertise.
Tantalum is a refractory transition metal with atomic number 73, melting point 3,017°C, and exceptional corrosion resistance from a dense pentoxide surface film; producers extract it primarily from tantalite-columbite ores through gravity separation and liquid-liquid extraction before reduction to metal via sodium or electrolytic processes. Capacitor applications command the largest value share due to tantalum's unmatched volumetric efficiency in miniaturized electronics, while superalloy demand for jet engine turbine blades represents the fastest-growing segment driven by single-crystal casting requirements. Biomedical-grade tantalum occupies a concentrated premium niche for cranial implants and bone scaffolding, where ASTM F560 compliance creates significant qualification barriers for new entrants.
US SEC conflict minerals disclosure rules and EU Conflict Minerals Regulation together reshape procurement patterns, compelling end-users to document smelter and refiner audit trails or face market exclusion. China's SAMR oversees domestic tantalum product standards through GB classifications that govern import substitution in strategic electronics applications. Stakeholders must monitor evolving due diligence frameworks and smelter verification protocols to secure qualified supply positions before compliance thresholds tighten further.
Market Dynamics
Conflict-free sourcing mandates from the EU and US are fragmenting tantalum supply chains into audited and non-audited tiers, forcing processors to absorb compliance costs while capacitor-grade powder concentrates in East Asian fabrication clusters.
Growth Catalysts
- Electric vehicle powertrain electrification:Battery management systems and onboard chargers require high-reliability capacitors that tolerate thermal cycling, pulling tantalum demand from automotive OEMs in Germany, Japan, and South Korea.
- US Dodd-Frank Section 1502:SEC disclosure rules for conflict minerals create procurement preference for smelters with CFSI-compliant audit trails, rewarding early adopters with locked-in supply contracts from tier-one electronics manufacturers.
- 5G base station deployment:Massive MIMO antenna arrays and power amplifiers demand miniaturized capacitors with stable capacitance across temperature extremes, concentrating orders with Japanese and South Korean fabricators.
Market Restraints
- Geologist and metallurgical engineer scarcity:Technical talent availability is collapsing across Central African tantalum belt operations, constraining upstream brownfield expansion and greenfield project development.
- Niobium substitution in mid-performance capacitors:Ceramic and aluminum alternatives capture cost-sensitive consumer electronics segments where volumetric efficiency requirements relax.
- Input cost volatility in sodium reduction:Energy-intensive metal reduction processes expose margins to electricity and reagent price swings in Chinese refining centers.
Strategic Opportunities
- Ethiopian upstream development:Greenfield tantalite deposits in the Kenticha belt offer conflict-free ore potential for Western-aligned processors seeking supply chain diversification beyond Central African sources.
- Biomedical-grade tantalum for additive manufacturing:ASTM F560-compliant powder for cranial implants and patient-specific bone scaffolds commands 3-4x capacitor-grade pricing with limited qualified competition.
- EU Critical Raw Materials Act:Strategic stockpiling mandates and domestic processing incentives create offtake security for European smelters achieving Oeko-Tex and Responsible Minerals Initiative certification.
Industry Challenges
- Smelter and refiner audit trail documentation:Downstream OEMs demand granular chain-of-custody records spanning artisanal mine sites to capacitor fabrication, stretching IT infrastructure and field verification capabilities.
- Single-crystal superalloy casting qualification:Jet engine turbine blade manufacturers require 18-24 month metallurgical certification cycles for new tantalum suppliers, freezing out mid-tier entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tantalum Market |
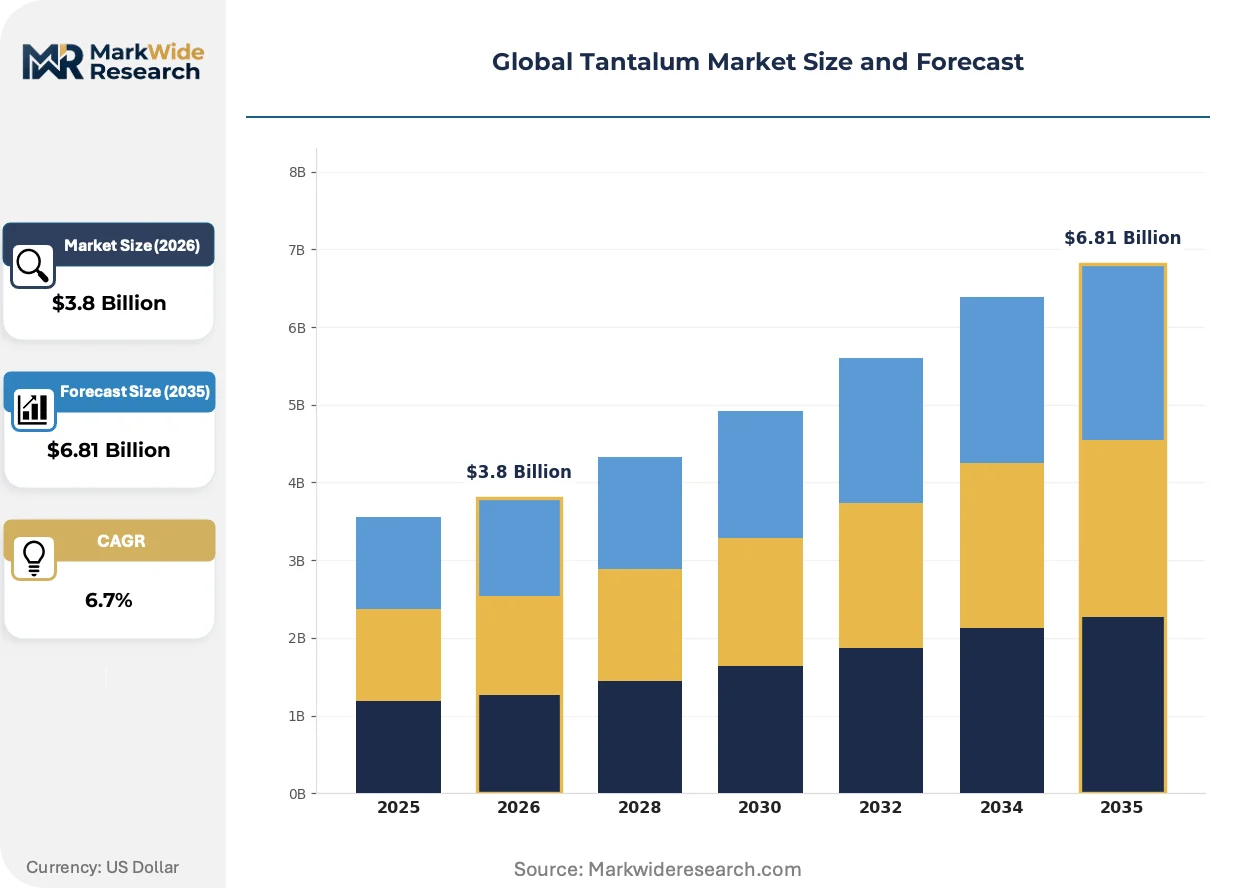
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tantalum Powders, Tantalum Bars, Tantalum Sheets, Tantalum Wires Grade: Standard, High Purity, Alloyed, Special Purpose End User: Aerospace, Electronics, Medical Devices, Defense Application: Capacitors, Superalloys, Semiconductor Manufacturing, Biomedical |
| Companies Covered | Ningxia Orient Tantalum Industry Co. Ltd, Minsur, Global Advanced Metals Pty Ltd, Cabot Corp, Jiangxi Tungsten Industry Group Co. Ltd, AMG Advanced Metallurgical Group, H.C. Starck GmbH, Ethiopian Mineral Development Share Company, Pilbara Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tantalum Market Emerging Trajectories
Capacitor-grade powder production is splitting between high-purity semiconductor sputtering targets and commodity electronics grades, while regulatory compliance becomes a product differentiator rather than a cost center.
Polymer tantalum capacitor technology is bifurcating the traditional manganese dioxide segment. Automotive and aerospace buyers adopt polymer cathodes for their lower equivalent series resistance and benign failure modes under short-circuit conditions. This split is compressing margins on legacy manganese dioxide grades while premium polymer variants capture design wins in Munich and Detroit power electronics programs.
REACH authorization requirements for tantalum pentoxide are tightening industrial chemical registration obligations across EU member states. Downstream capacitor manufacturers now face extended substance volume tracking and safety data sheet obligations. German and French electronics fabricators are responding by consolidating supplier lists to pre-registered smelters with established only-representative arrangements.
Long-term offtake contracting is displacing spot market procurement among tier-one automotive and defense buyers. Japanese trading houses and South Korean electronics conglomerates now lock in multi-year tantalum concentrate supply directly with Ethiopian and Australian mine operators. This behavior is most visible in Tokyo and Seoul, where capacitor manufacturers seek insulation from artisanal supply disruptions in the Great Lakes region of Africa.
Global Tantalum Market Segmentation
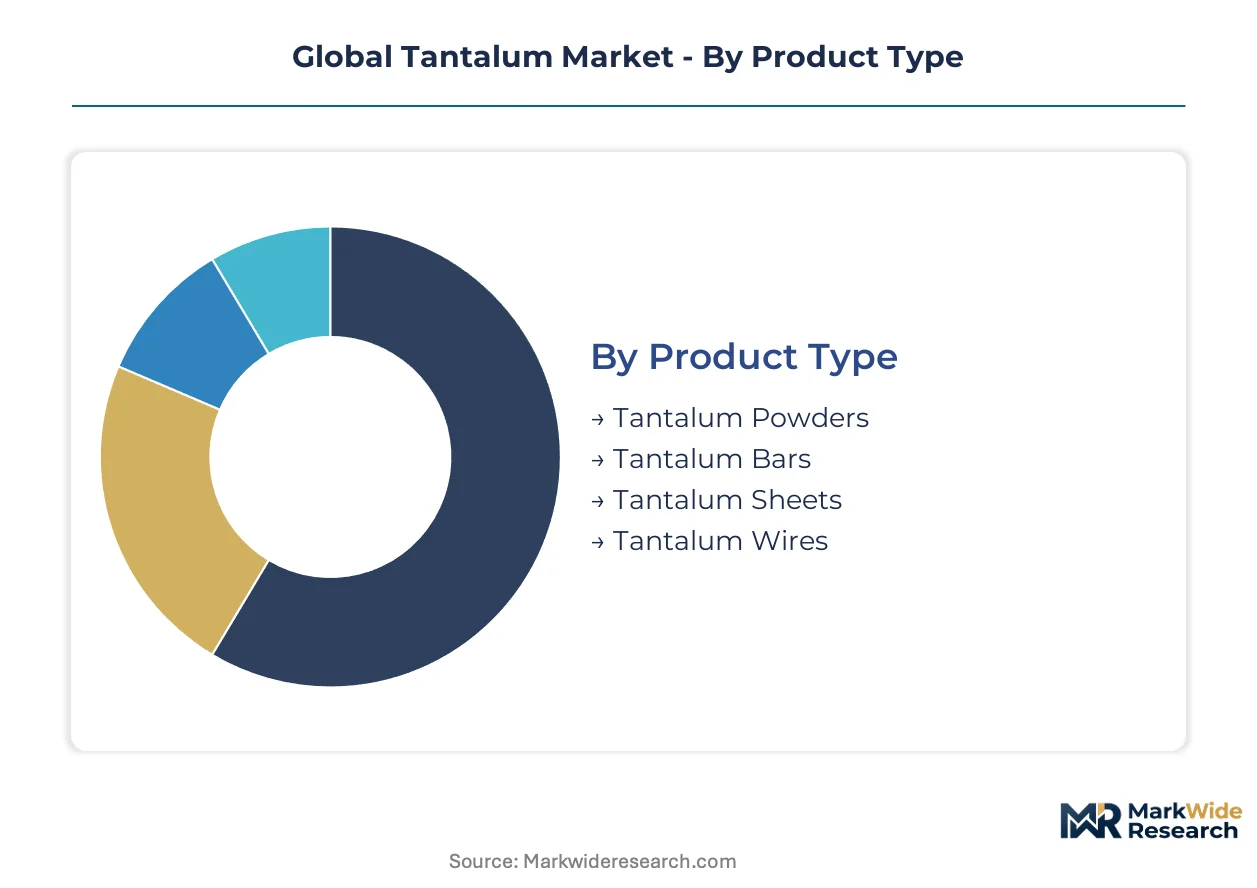
Tantalum's value chain splits sharply between capacitor-grade powder commanding premium pricing and wrought forms serving industrial fabrication. Segmentation discipline matters because alloy specifications and purity thresholds determine which smelters qualify for automotive and aerospace offtake contracts.
Product Type:
Channel distribution varies by form factor, with powders flowing through chemical processors to capacitor fabricators while mill products reach machine shops and superalloy casters.
- Tantalum Powders:Spherical and angular morphologies produced via sodium reduction or electrolytic methods, with particle size distributions tailored to anode formation in solid-state capacitors. Demand concentrates in Japanese and South Korean electronics clusters where surface area specifications exceed 3.0 m²/g for high-voltage automotive grades. Polymer cathode adoption in Munich and Detroit power electronics programs is pulling premium powder volumes away from legacy manganese dioxide formulations.
- Tantalum Bars:Vacuum-arc remelted ingots and rolled bar stock for superalloy master alloy addition and corrosion-resistant process equipment. German turbine blade casters and French chemical processors anchor Western demand, with ASTM B365 compliance mandatory for aerospace procurement. Long qualification cycles with jet engine OEMs freeze out unproven suppliers.
- Tantalum Sheets:Cold-rolled plate and foil for chemical processing equipment, sputtering target backing plates, and heat exchangers. Specified by thickness tolerance and grain structure for acid-resistant linings in German and Belgian chemical plants.
- Tantalum Wires:Drawn filament for surgical sutures, vacuum furnace heating elements, and evaporation sources. Medical device fabricators in Switzerland and the US specify ASTM F560 compliance for implantable applications.
By volume, tantalum powders lead. By growth pace, tantalum bars for superalloy feedstock are climbing the fastest.
Grade:
Cost tiers separate commodity electronics feedstock from qualification-intensive aerospace and medical grades, with purity premiums expanding as semiconductor sputtering targets demand 4N5+ material.
- Standard:2N5 to 3N purity capacitor-grade powder for consumer electronics and general industrial applications, produced at scale in Chinese refining centers.
- High Purity:4N to 5N material for semiconductor sputtering targets and superalloy additions, with oxygen and nitrogen specifications below 100 ppm. German and Japanese fabricators dominate qualification and capture 40-60% price premiums over standard grades.
- Alloyed:Tantalum-tungsten and tantalum-niobium compositions for corrosion-resistant tubing and high-temperature fasteners, specified by ASTM B521 and B708 for chemical service.
- Special Purpose:ASTM F560-compliant biomedical stock and custom compositions for defense radiation shielding, with lot-level certification and full metallurgical traceability mandatory.
Standard grade moves the most volume. Special purpose commands the steepest margin expansion trajectory.
End User:
Customer type determines contracting structure, with defense and medical buyers demanding multi-year supply agreements while electronics procurement shifts toward spot-indexed or quarterly pricing.
- Aerospace:Single-crystal turbine blade casters in the US, UK, and France require 18-24 month metallurgical certification cycles for new tantalum suppliers, locking in incumbent relationships.
- Electronics:Capacitor fabricators in Japan and South Korea concentrate orders with CFSI-audited smelters, with polymer cathode adoption accelerating in automotive-qualified product lines.
- Medical Devices:Cranial implant manufacturers and orthopedic scaffold developers in Switzerland and the US source ASTM F560-certified powder at 3-4x capacitor-grade pricing, with limited qualified competition.
- Defense:Radiation-hardened electronics and shaped charge liners require domestic-sourced or allied-nation material under ITAR and national security procurement rules.
Electronics generates the largest revenue pool. Medical devices deliver the fastest margin expansion.
Application:
Application maturity varies sharply, with capacitors representing a commoditized volume base while biomedical additive manufacturing remains a concentrated premium niche.
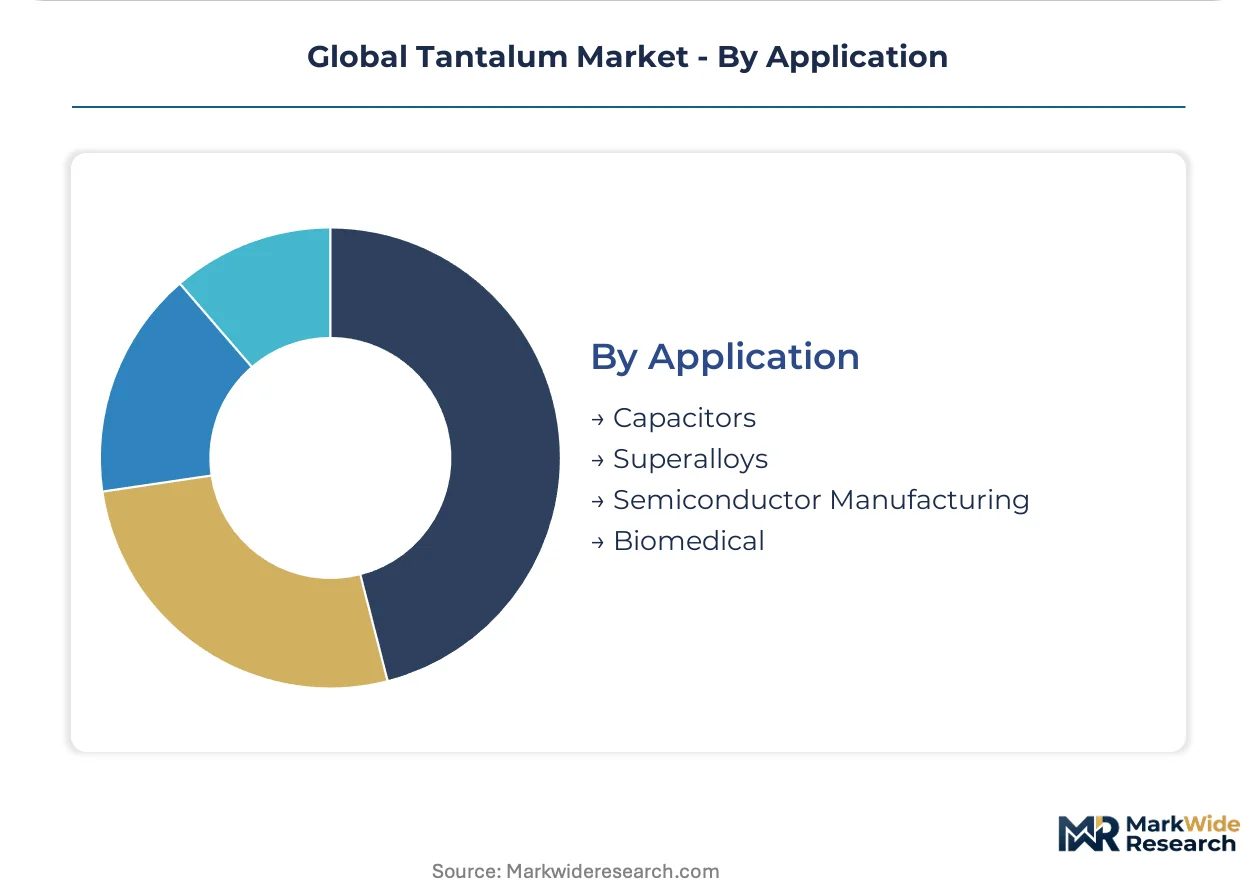
- Capacitors:Tantalum pentoxide dielectric layers deliver unmatched volumetric efficiency for miniaturized electronics, with manganese dioxide cathodes losing share to polymer alternatives in automotive and aerospace programs.
- Superalloys:Tantalum additions to nickel-based single-crystal castings improve creep resistance in jet engine turbine blades, with demand tied to Rolls-Royce, Pratt & Whitney, and Safran production schedules.
- Semiconductor Manufacturing:High-purity sputtering targets for copper diffusion barriers and 300mm wafer fabrication equipment, with H.C. Starck and Ningxia Orient competing on purity certification.
- Biomedical:Porous tantalum scaffolds for bone ingrowth and cranial reconstruction, with ASTM F560 compliance creating significant qualification barriers for new powder suppliers.
Capacitors dominate by volume. Biomedical applications are expanding most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the dominant geography through GB standards that govern strategic electronics applications and import substitution mandates. The regulatory framework splits procurement between audited and non-audited supply tiers.
China
Capacitor-grade powder production concentrates in Ningxia and Jiangxi provinces where vertically integrated refiners serve domestic electronics fabrication. SAMR's GB classifications enforce purity thresholds for semiconductor applications. The Yangtze River Delta cluster absorbs the majority of high-voltage automotive-grade output for EV powertrain programs.
United States
Defense and aerospace demand pulls specialty alloys and radiation-hardened materials through ITAR-compliant channels. The SEC's conflict minerals disclosure rules under Dodd-Frank Section 1502 compel electronics OEMs to document smelter audit trails. Greater Boston hosts biomedical device fabricators sourcing ASTM F560-certified wire for cranial implants.
Japan
Capacitor fabricators in the Kanto region lock in multi-year tantalum concentrate offtake directly with Ethiopian and Australian mine operators. METI oversees strategic stockpiling protocols for critical raw materials. Tokyo-based trading houses coordinate polymer cathode adoption for automotive-qualified product lines.
Germany
Turbine blade casters in Bavaria and North Rhine-Westphalia require 18-24 month metallurgical certification cycles for superalloy feedstock. REACH authorization requirements for tantalum pentoxide tighten industrial chemical registration obligations. H.C. Starck's refining expertise in high-purity sputtering targets anchors Western semiconductor supply security.
Australia
Greenfield tantalite development in Western Australia offers conflict-free ore potential for Western-aligned processors. The federal government's critical minerals strategy prioritizes downstream processing incentives. Pilbara Minerals and Global Advanced Metals anchor mine-to-metal pipelines serving European and Japanese offtake contracts.
Global Tantalum Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capacitor-grade powder production concentrating in East Asian chemical processors and high-purity refining anchored in European facilities. The structure rewards backward integration into ore sources and captive supply of metallurgical expertise. Three archetypes dominate: vertically integrated Chinese refiners, Western security-of-supply anchors with African ore access, and German-Japanese high-purity specialists. Competitive moves center on long-term offtake contracting with automotive OEMs and qualification cycles for aerospace superalloy feedstock.
Among Chinese integrated players, Ningxia Orient Tantalum Industry Co. Ltd exemplifies the scale-driven archetype through its vertically structured refining complex. Global Advanced Metals Pty Ltd occupies a position as a Western-aligned security anchor with Australian and Ethiopian upstream assets. H.C. Starck GmbH represents the high-purity specialist tier, leveraging German metallurgical expertise for semiconductor and superalloy applications.
| Leading Market Players |
|---|
| Ningxia Orient Tantalum Industry Co. Ltd |
| Minsur |
| Global Advanced Metals Pty Ltd |
| Cabot Corp |
| Jiangxi Tungsten Industry Group Co. Ltd |
| AMG Advanced Metallurgical Group |
| H.C. Starck GmbH |
| Ethiopian Mineral Development Share Company |
| Pilbara Minerals |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month metallurgical certification cycles for aerospace-grade tantalum feedstock concentrate pricing power with incumbent suppliers while locking out unqualified competitors. This lead-time band reinforces supply chain segmentation between CFSI-audited and non-audited tiers, with capacitor-grade powder commanding premiums in East Asian electronics clusters.
Pricing Analysis
Price spreads between German high-purity sputtering targets and Chinese standard-grade capacitor powder reflect certification-driven differentiation. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F560 biomedical stock from superalloy feedstock and commodity electronics grades. Cost compression in legacy manganese dioxide formulations is intensifying because polymer cathode adoption accelerates in automotive-qualified product lines. Electronics fabricators in Japan and South Korea exhibit the highest price sensitivity, while medical device manufacturers in Switzerland accept steep premiums for lot-level traceability.
Supply Chain Analysis
China and Australia anchor upstream tantalum concentrate production, with Ethiopian greenfield development expanding conflict-free ore availability. Downstream fabrication draws from sodium-reduced powders, electrolytic high-purity metal, and vacuum-arc remelted ingots as primary inputs. Single-source vulnerability concentrates in Japanese capacitor fabricators dependent on CFSI-audited smelter networks. Distribution runs through vertically integrated refiners serving domestic electronics clusters and Western-aligned mine-to-metal pipelines securing European and North American offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified metallurgical engineers and geologists capable of certifying single-crystal superalloy feedstock represent the scarcest capability layer in this market, constraining brownfield expansion across Central African and Australian operations.
For Market Incumbents: Fortify captive supply of technical talent through apprenticeship pipelines with German and Australian mining universities. Lock in multi-year offtake contracts with Ethiopian and Australian mine operators before compliance thresholds tighten further under EU Conflict Minerals Regulation enforcement. Priority levers include backward integration into Kenticha belt ore sources and Oeko-Tex certification investment for European strategic stockpiling eligibility.
For New Entrants and Emerging Players: Differentiate on ASTM F560-compliant biomedical powder production where 3-4x pricing premiums and limited qualified competition create defendable positioning. Target additive manufacturing scaffold developers in Switzerland and Greater Boston seeking patient-specific cranial implant feedstock. Go-to-market angle centers on lot-level metallurgical traceability and rapid qualification support for orthopedic device OEMs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with non-core tantalum assets in stable jurisdictions. Long-term viability hinges on securing conflict-free ore positions before EU Critical Raw Materials Act stockpiling mandates fully activate. Watch for polymer cathode adoption rates in Munich and Detroit power electronics programs as inflection indicators for premium powder demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethiopian Ore Sources | Secures conflict-free supply positioning ahead of EU compliance threshold tightening. |
| ASTM F560 Certification Investment | Unlocks biomedical-grade pricing premiums with Swiss and US implant manufacturers. |
| Polymer Cathode Capacity Expansion | Captures design wins from Munich and Detroit automotive power electronics programs. |
| Long-term Offtake Contracting with Japanese Trading Houses | Insulates against artisanal supply disruptions in Central African tantalum belt. |
| Oeko-Tex and RMI Certification Achievement | Qualifies European smelters for EU strategic stockpiling and domestic processing incentives. |
Methodological Framework
A spread of perspectives from tantalum smelter operations managers, capacitor fabricator procurement leads, aerospace superalloy casters, and biomedical device quality directors converged on the working assumptions. Primary interview insights combined with secondary validation from SEC conflict minerals filings, EU smelter and refiner audit databases, and Japanese METI critical raw materials stockpile reports. Bottom-up concentrate flow modeling and top-down electronics demand estimation provided triangulation across the analysis window.
Segmentation dimensions modeled include product form factor, purity grade tier, end-use industry application, and regional regulatory compliance cluster. CAGRs derived from installed base growth in electric vehicle powertrains and 5G infrastructure deployment trajectories. Forecast inputs incorporated polymer cathode adoption curves in automotive-qualified capacitor lines and single-crystal turbine blade production schedules at Rolls-Royce, Pratt & Whitney, and Safran.
Material uncertainties — artisanal supply disruptions in Central African operations, niobium substitution acceleration in mid-performance capacitors, and REACH authorization scope expansion for tantalum pentoxide — sit outside the modeled envelope. Forecasts reflect assumptions about CFSI audit trail maintenance and smelter verification protocol stability. Recalibration cycles align with material shifts in EU Conflict Minerals Regulation enforcement and US SEC disclosure rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Casting Market
Metals
Cobalt Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Silver Powder and Flakes Market
Metals
Metallic Rope Cords Market
Metals
Huntite Market
Metals
Iron and Steel Market
Metals
Industrial Silver Market
Metals
North America and Europe Metal Powder Market
Metals
Global Flat Carbon Steel Market
Metals
Qatar Metalworking Market
Metals
Steel Salvage Drums Market
Metals
Global Copper Cathode Market
Metals
Refined Nickel Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Global Bronze Market