
 Global Titanium Metal Market | 2026-2036
Global Titanium Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Titanium Metal Market Foresight
Project finance tied to long-term offtake agreements from aerospace OEMs is tilting competitive dynamics toward capital-rich producers. VSMPO-AVISMA leverages its fully integrated titanium sponge-to-mill-product chain to sustain cost discipline across volatile feedstock cycles. BAOTI Group anchors its position through captive ilmenite sourcing and state-backed capacity expansions in Shaanxi Province. ATI competes by specializing in premium titanium alloys for jet engine rotating components, where metallurgical consistency commands pricing power.
Titanium metal encompasses elemental titanium and its alloys, characterized by a density of 4.51 g/cm³, a melting point of 1,668°C, and exceptional strength-to-weight ratios achieved through vacuum arc remelting or electron beam melting of titanium sponge derived from Kroll-process reduction of titanium tetrachloride. The aerospace application segment leads value generation, with titanium alloy ingots for structural airframes and engine components capturing the deepest margin pools due to stringent certification barriers and dual-source requirements from Boeing and Airbus. Powder metallurgy is gaining traction for near-net-shape biomedical implants, where hydride-dehydride titanium powder enables complex geometries unattainable through conventional forging.
FAA airworthiness standards and EASA certification protocols dictate microstructural uniformity and ultrasonic testing regimens for aerospace-grade titanium, effectively filtering out non-specialist producers. China's GB/T standards for titanium sponge purity, administered by SAMR, are converging with ASTM B299 specifications, easing qualified supplier status for export-oriented Chinese mills. Stakeholders must monitor how the EU AI Act and emerging CSRD traceability mandates reshape documentation burdens across titanium supply chains serving European defense and medical device end users.
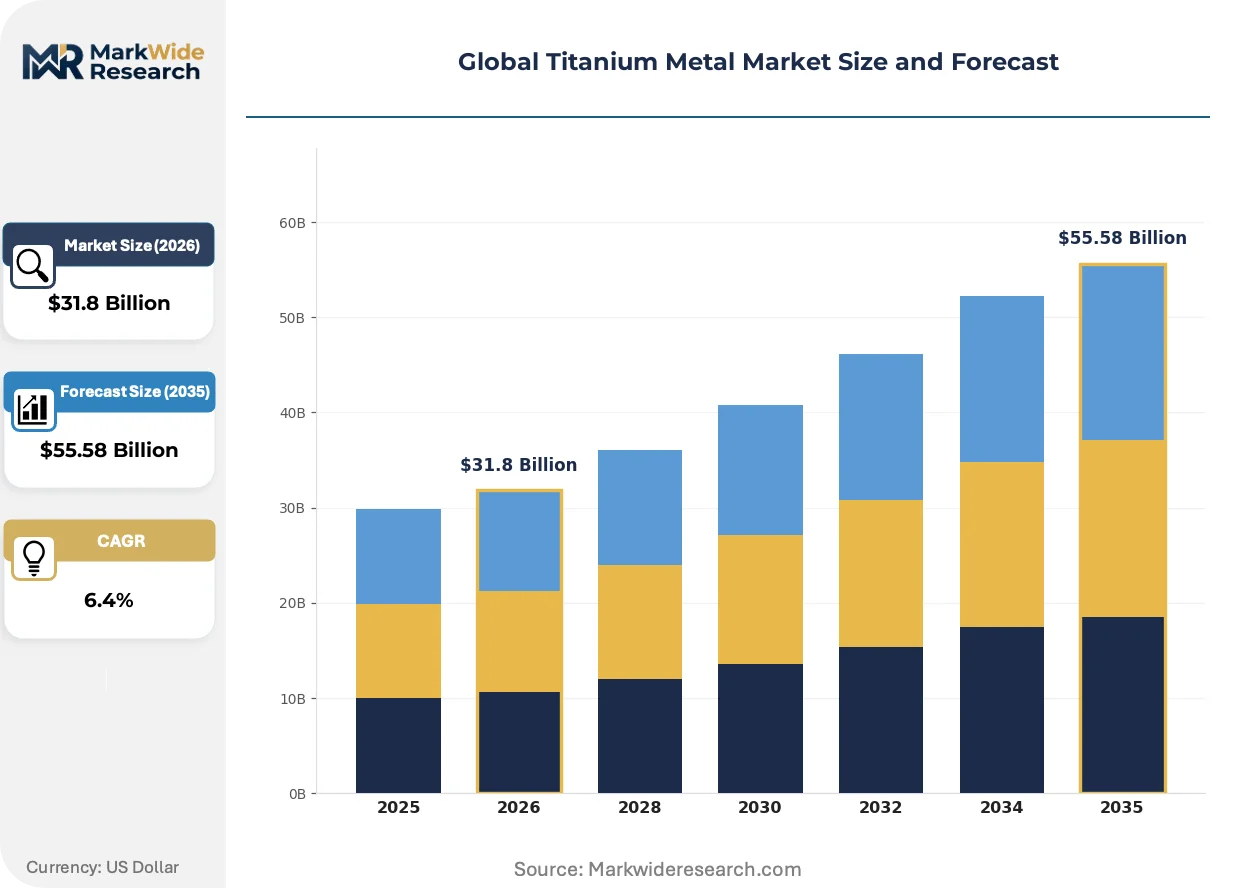
Market Dynamics
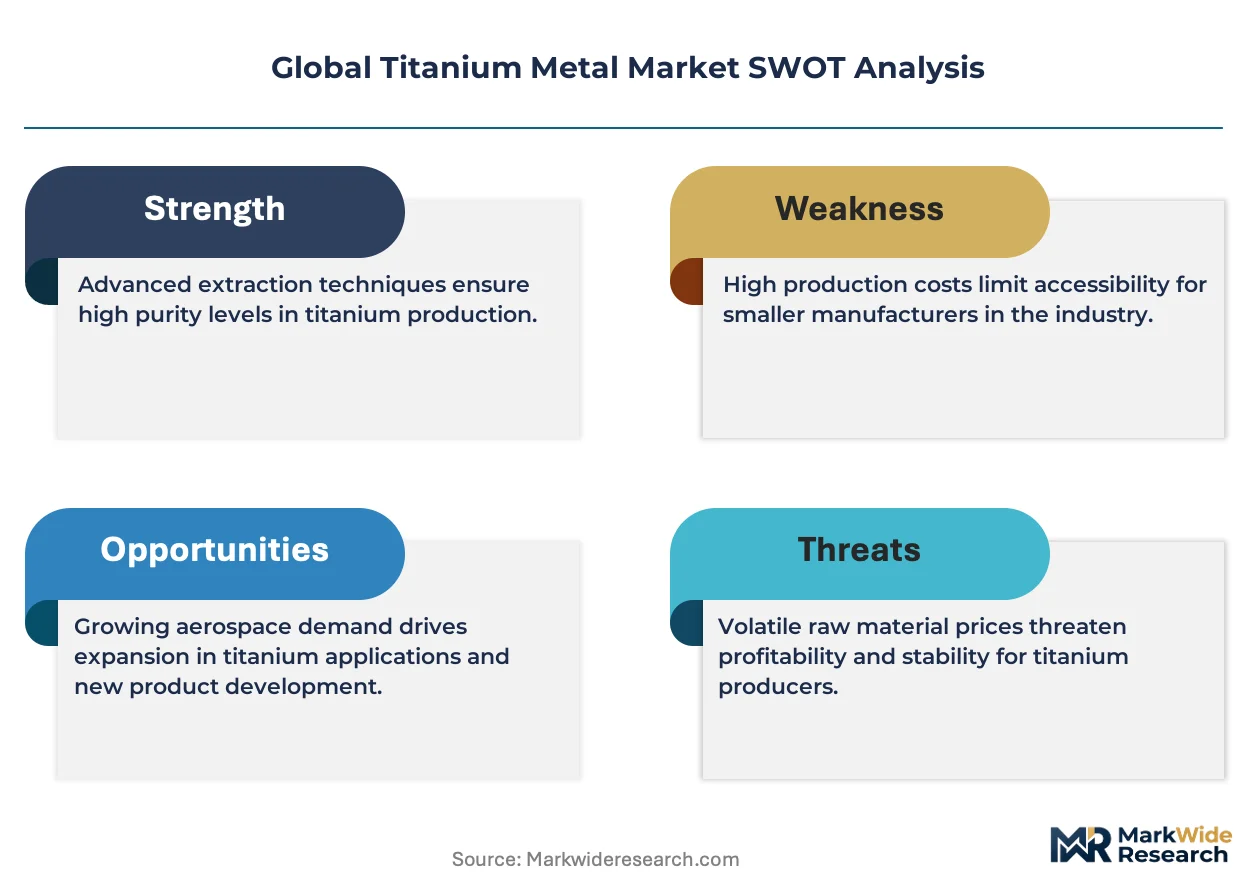
Long-term offtake agreements from aerospace OEMs are concentrating procurement power among capital-rich producers, forcing mid-tier mills to secure feedstock through costly spot markets or abandon aerospace certification paths entirely.
Growth Catalysts
- FAA and EASA airworthiness directives:Tightening material traceability requirements for structural airframes and engine rotating components are locking in qualified suppliers and extending contract durations.
- Powder metallurgy for biomedical implants:Hydride-dehydride titanium powder enables near-net-shape geometries for complex orthopedic devices, opening premium margin pools outside aerospace.
- China's titanium sponge production clusters:State-backed capacity expansions in Shaanxi Province are compressing feedstock costs for export-oriented alloy fabricators.
Market Restraints
- Kroll process energy intensity:Titanium sponge production requires 60-100 MWh per tonne of metal, exposing margins to volatile electricity tariffs and carbon border adjustments.
- Russian titanium sponge concentration:VSMPO-AVISMA's integrated chain controls roughly one-third of global aerospace-grade sponge supply, creating single-source vulnerability.
- Carbon fiber substitution in airframes:Boeing 787 and Airbus A350 already deploy 50%+ composite structures, capping titanium's structural weight share expansion.
Strategic Opportunities
- India's defense localization:The country's PLI scheme for aerospace components is creating qualified supplier slots for titanium alloy mills willing to co-invest in forging and heat-treatment capacity.
- EU Green Deal carbon accounting:CSRD traceability mandates favor producers with verified low-carbon sponge sources, rewarding early movers in electrolytic reduction R&D.
- Additive manufacturing convergence:Electron beam melting of titanium powder is digitizing spare part production for aging military airframes, compressing lead times from months to days.
Industry Challenges
- Vacuum arc remelting metallurgist scarcity:The specialized skill pool for controlling alpha-case formation and beta-transus uniformity in aerospace ingots is thinning across US and European mills.
- Dual-source certification timelines:Boeing and Airbus qualification protocols for new titanium suppliers span 18-36 months, freezing out capital-constrained entrants.
- Legacy ERP integration with blockchain traceability:EU AI Act and emerging defense procurement rules require immutable batch records, forcing expensive middleware upgrades at mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Titanium Metal Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Sponge, Titanium Alloy, Titanium Ingots, Titanium Fabricated Products Technology: Vacuum Arc Remelting, Cold Hearth Melting, Electron Beam Melting, Hydride-Dehydride Process, Powder Metallurgy Application: Aerospace Components, Biomedical Implants, Sports Equipment, Marine Equipment, Chemical Processing Equipment End User Industry: OEMs, Aftermarket Providers, Research Institutes, Defense Contractors, Heavy Machinery Manufacturers |
| Companies Covered | Toho Titanium Co., Ltd., BAOTI Group, VSMPO-AVISMA Corporation, Carpenter Technology, Kobe Steel, ATI, OSAKA Titanium Technologies Co., Ltd., UST-Kamenogorsk Titanium and Magnesium Plant JSC, Timet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Titanium Metal Market Shifts & Advancements
Digital thread technologies and automated inspection systems are compressing certification cycles while regulatory pressure on carbon intensity is forcing process innovation across the sponge-to-mill-product chain.
Electron beam cold hearth melting is digitizing titanium scrap recycling and alloy recovery, enabling aerospace-grade remelt from machine turnings and rejected ingots. Tier-one engine OEMs are adopting this technology to secure captive feedstock. The process is digitizing inventory management by converting waste streams into certifiable input material.
The EU AI Act's risk classification framework is mandating algorithmic transparency in ultrasonic testing and automated defect recognition systems used for aerospace plate and forging certification. European mills must now document training data provenance and model drift for AI-assisted inspection. Medical device manufacturers sourcing from EU-certified suppliers face parallel documentation burdens under MDR Article 10.
Defense procurement agencies are unbundling long-term service contracts from initial hardware purchases, shifting titanium component suppliers toward performance-based availability guarantees. This model disrupts traditional spot-market metal sales and rewards integrated producers with in-house NDT and repair capabilities. The shift is most visible in US Navy and Royal Australian Air Force sustainment contracts for F-35 and P-8 platforms.
Global Titanium Metal Market Segmentation
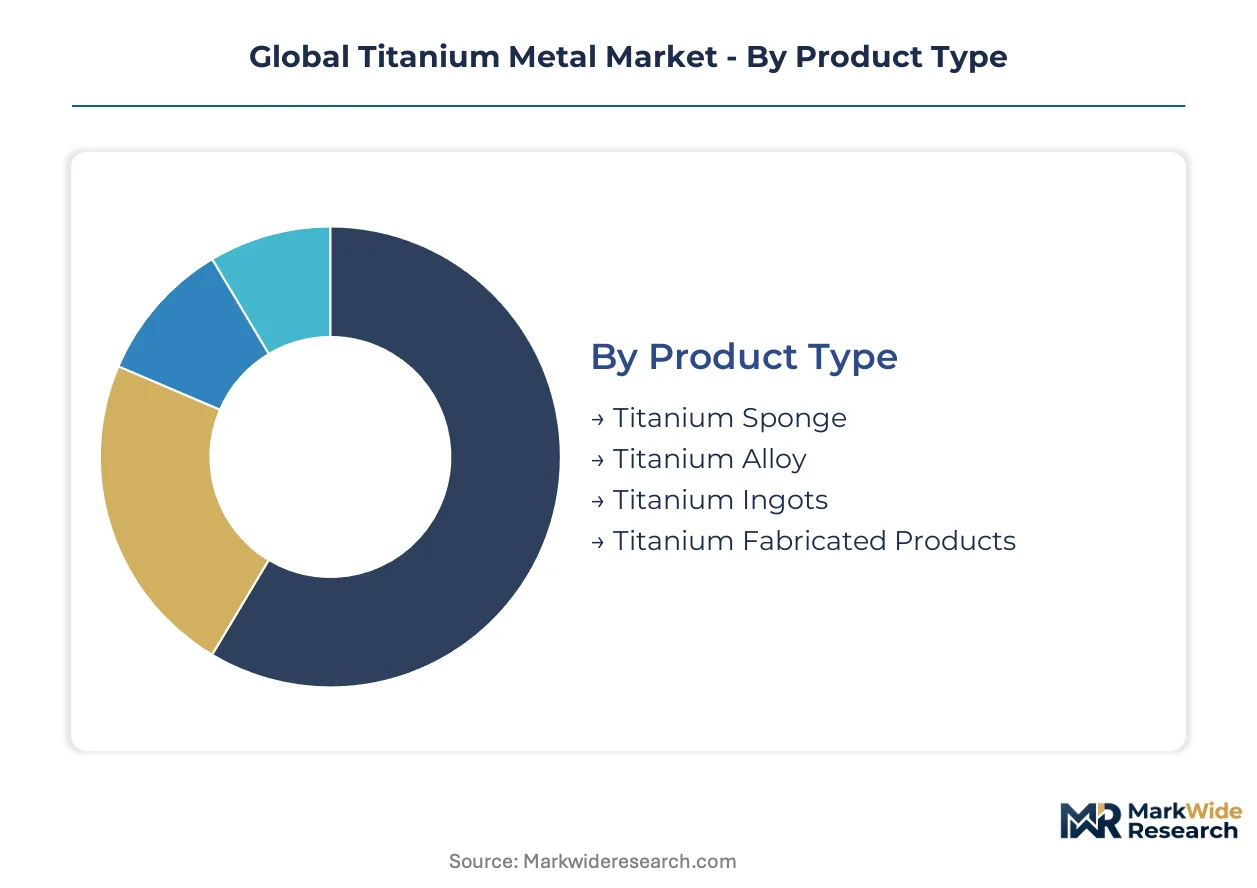
Titanium metal segmentation reveals how value migrates through distinct processing stages and certification tiers. Product form and melting technology determine margin capture, while application end-use dictates qualification barriers and contract duration.
Product Type:
Cost tier separates commodity feedstock from value-added mill products, with each ascending stage demanding greater metallurgical control and capital intensity.
- Titanium Sponge:Porous metallic titanium produced via Kroll-process reduction of titanium tetrachloride, typically measuring 99.6-99.9% purity. China's Shaanxi Province clusters and Russia's integrated producers dominate supply, with energy costs and ilmenite access determining competitive position.
- Titanium Alloy:Vacuum arc remelted ingots of Ti-6Al-4V, Ti-5Al-2.5Sn, and other aerospace grades, commanding premium pricing through dual-source certification from Boeing and Airbus. Demand concentrates in jet engine rotating components where metallurgical consistency is non-negotiable.
- Titanium Ingots:Primary mill feedstock for forging and rolling operations, produced through single or double vacuum arc remelting.
- Titanium Fabricated Products:Finished plates, bars, tubes, and wire meeting ASTM B265 and AMS specifications for structural applications.
Titanium alloy commands the established base. The steepest expansion runs through titanium sponge as Chinese state-backed capacity compresses feedstock economics for downstream fabricators.
Technology:
Melting and powder processes stratify by certification grade capability, with aerospace-qualified methods requiring multi-million dollar furnace investments and specialized metallurgical expertise.
- Vacuum Arc Remelting:Conventional double or triple melting in inert atmosphere, producing ingots with controlled macrostructure for aerospace plate and forging stock. Boeing and Airbus qualification protocols mandate this method for structural airframe components, locking in established suppliers with certified furnace histories.
- Cold Hearth Melting:Electron beam or plasma cold hearth furnaces enabling scrap recycling and alloy recovery with superior inclusion removal. Tier-one engine OEMs adopt this technology to convert machine turnings into certifiable aerospace feedstock, digitizing inventory management.
- Electron Beam Melting:Additive manufacturing process for near-net-shape titanium components, compressing lead times for defense spare parts.
- Hydride-Dehydride Process:Mechanical comminution of titanium hydride to produce spherical powder for biomedical and additive applications.
- Powder Metallurgy:Press-and-sinter or hot isostatic pressing of titanium powder for complex geometries in orthopedic implants.
Vacuum arc remelting anchors aerospace certification requirements. The steepest expansion trajectory belongs to cold hearth melting as scrap recycling economics improve and sustainability pressures mount.
Application:
End-use maturity determines pricing power, with aerospace and biomedical segments sustaining premiums through regulatory barriers while industrial applications compete on cost.
- Aerospace Components:Structural airframes, landing gear, and engine rotating parts requiring Ti-6Al-4V and Ti-6Al-2Sn-4Zr-2Mo alloys. FAA and EASA airworthiness directives enforce material traceability, extending contract durations for qualified suppliers and filtering out non-specialist producers.
- Biomedical Implants:Orthopedic devices and dental fixtures utilizing commercially pure titanium or Ti-6Al-4V ELI for biocompatibility. Hydride-dehydride powder enables near-net-shape geometries unattainable through forging, opening premium margin pools in spinal and cranial implants.
- Sports Equipment:Bicycle frames, golf clubs, and racing components where strength-to-weight ratio justifies material cost.
- Marine Equipment:Propeller shafts, desalination components, and subsea hardware exploiting corrosion resistance.
- Chemical Processing Equipment:Heat exchangers, reactors, and piping for chloride-containing environments.
Aerospace components dominate revenue concentration. Biomedical implants are gaining share fastest as aging demographics expand orthopedic procedure volumes and powder metallurgy reduces machining waste.
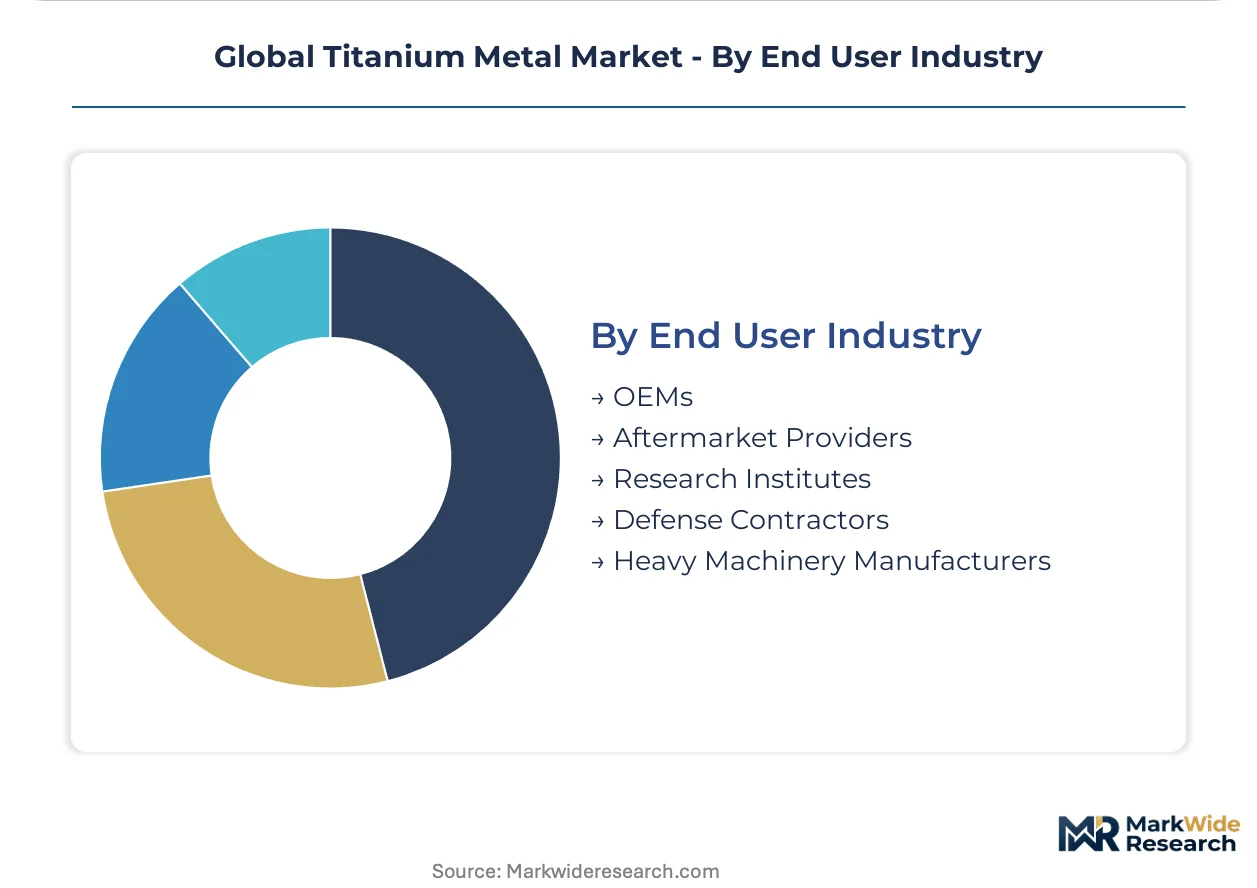
End User Industry:
Customer type determines contract structure, with OEMs and defense agencies locking in long-term offtake while aftermarket and research buyers operate on spot or project-based procurement.
- OEMs:Boeing, Airbus, Safran, and Rolls-Royce operating dual-source procurement with 18-36 month qualification timelines. Long-term offtake agreements concentrate purchasing power among capital-rich producers, forcing mid-tier mills toward spot markets or non-aerospace segments.
- Defense Contractors:Lockheed Martin, BAE Systems, and national arsenals with performance-based availability guarantees replacing traditional hardware purchases. US Navy and Royal Australian Air Force sustainment contracts for F-35 and P-8 platforms reward integrated producers with in-house NDT capabilities.
- Aftermarket Providers:MRO operators and spare part distributors serving aging military and commercial fleets.
- Research Institutes:National laboratories and university programs developing next-generation alloys and processing methods.
- Heavy Machinery Manufacturers:Industrial equipment builders sourcing titanium for corrosion-critical components.
OEMs anchor procurement volume through multi-year supply agreements. Defense contractors are climbing fastest as sustainment contracts unbundle service from initial hardware and digitize spare part production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace OEM procurement power concentrates among qualified suppliers in the United States, China, Russia, Japan, and Germany, where dual-source certification requirements and defense sustainment contracts reshape competitive positioning.
United States
Boeing and Lockheed Martin sustainment contracts for F-35 and P-8 platforms drive demand for certified titanium alloys. FAA airworthiness directives enforce material traceability through ultrasonic testing regimens. ATI and Carpenter Technology anchor production in Pennsylvania and Pennsylvania-adjacent corridors, serving jet engine rotating component specifications.
China
State-backed capacity expansions in Shaanxi Province compress titanium sponge feedstock costs for downstream fabricators. SAMR-administered GB/T standards for titanium sponge purity are converging with ASTM B299 specifications, easing qualified supplier status for export-oriented mills. BAOTI Group anchors captive ilmenite sourcing and alloy production in the province's titanium production clusters.
Russia
VSMPO-AVISMA's fully integrated sponge-to-mill-product chain controls roughly one-third of global aerospace-grade sponge supply. EASA and FAA airworthiness protocols maintain qualified supplier status despite geopolitical friction. The company's integrated operations in the Ural region sustain cost discipline across volatile feedstock cycles.
Japan
Precision alloy fabrication corridors in Osaka and Kobe serve medical device and aerospace OEMs with hydride-dehydride powder capabilities. METI industrial policy supports titanium powder metallurgy for near-net-shape biomedical implants. Toho Titanium and OSAKA Titanium Technologies occupy positions in the Kansai region's specialty materials ecosystem.
Germany
Airbus dual-source procurement requirements and EU Green Deal carbon accounting reshape supplier documentation burdens. CSRD traceability mandates favor producers with verified low-carbon sponge sources, rewarding early movers in electrolytic reduction R&D. Precision forging operations in Bavaria and Baden-Württemberg serve engine OEM specifications.
Global Titanium Metal Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where capital-rich integrated producers capture aerospace offtake agreements. The vendor base stratifies between sponge producers with captive feedstock, alloy specialists with dual-source certification, and powder metallurgy entrants targeting biomedical margins. Three archetypes dominate: fully integrated sponge-to-mill chains, premium alloy specialists with furnace certification histories, and powder process innovators. Competitive moves concentrate on capacity expansion in low-cost energy jurisdictions and strategic partnerships for defense sustainment contracts.
Among integrated Russian and Chinese producers, VSMPO-AVISMA and BAOTI Group exemplify the sponge-integrated archetype with captive control over feedstock economics. ATI represents the premium alloy specialist tier, occupying a position defined by metallurgical consistency in aerospace rotating components. These three anchors illustrate how certification barriers and capital intensity filter competitive participation.
| Leading Market Players |
|---|
| Toho Titanium Co., Ltd. |
| BAOTI Group |
| VSMPO-AVISMA Corporation |
| Carpenter Technology |
| Kobe Steel |
| ATI |
| OSAKA Titanium Technologies Co., Ltd. |
| UST-Kamenogorsk Titanium and Magnesium Plant JSC |
| Timet |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into titanium alloy pricing differentials between Chinese sponge-integrated mills and European precision forgers, amplifying margin compression for mid-tier fabricators lacking captive feedstock or long-term offtake coverage.
Pricing Analysis
Cost-plus contracts with magnesium and chlorine feedstock indexation dominate aerospace-grade titanium sponge procurement, insulating VSMPO-AVISMA and BAOTI Group from spot volatility while exposing non-integrated mills to margin erosion. Pricing stratifies across aerospace-certified, industrial-grade, and commodity sponge tiers, with certification level and furnace history commanding substantial premia. Cost compression in industrial-grade ingots is intensifying because Chinese state-backed capacity expansions in Shaanxi Province flood export markets with lower-purity feedstock. Defense contractors and tier-one engine OEMs exhibit the lowest price sensitivity due to dual-source mandates and performance guarantees, while commodity chemical processors face acute substitution risk to nickel alloys.
Supply Chain Analysis
Export-control restrictions under US Bureau of Industry and Security regulations limit electron beam cold hearth melting technology transfers to Chinese fabricators, constraining their ascent into aerospace-grade alloy production. Supply concentrates in Russia's Ural region, China's Shaanxi Province, and Japan's Kansai corridor, with ilmenite access and energy cost structures determining competitive position. The chain draws from titanium tetrachloride, magnesium reductant, and vacuum arc remelting furnace capacity as critical inputs. Single-source vulnerability around VSMPO-AVISMA's sponge production creates structural risk for Western aerospace OEMs. Distribution runs through qualified mill product distributors and direct long-term contracts to Boeing, Airbus, and defense procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boeing and Airbus dual-source consolidation has concentrated procurement power among three qualified suppliers per alloy grade, fragmenting pricing leverage for mid-tier mills and forcing exit from aerospace certification paths.
For Market Incumbents: Pre-empt carbon border adjustment exposure by securing verified low-carbon sponge sources through electrolytic reduction partnerships or EU Green Deal-compliant supply chains. Lock in defense sustainment contracts with performance-based availability guarantees before tier-one engine OEMs bring electron beam cold hearth melting in-house for scrap recycling. Carbon fiber substitution in next-generation airframes threatens structural titanium weight share expansion.
For New Entrants and Emerging Players: India's defense localization under the PLI scheme for aerospace components offers the most penetrable entry point for titanium alloy mills willing to co-invest in forging and heat-treatment capacity alongside state-backed offset partners. Hydride-dehydride powder for biomedical implants presents parallel white-space opportunity with lower certification barriers than aerospace. Target hospital procurement committees and spinal implant OEMs with near-net-shape geometry capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core titanium alloy divisions lacking dual-source certification from Boeing or Airbus. Long-term viability hinges on furnace certification histories and captive sponge access rather than commodity metal exposure. Watch for electrolytic reduction breakthroughs as the inflection signal that would rewrite feedstock economics and disqualify Kroll-process incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Mining | BAOTI Group's captive sourcing in Shaanxi Province insulates margins from volatile feedstock cycles. |
| Electron Beam Cold Hearth Melting Adoption | Rolls-Royce and Pratt & Whitney convert machine turnings into certifiable aerospace feedstock, digitizing inventory. |
| EU Green Deal Carbon Accounting Certification | CSRD traceability mandates favor producers with verified low-carbon sponge sources in German precision forging corridors. |
| Defense Sustainment Contract Unbundling | US Navy and Royal Australian Air Force F-35 contracts reward integrated producers with in-house NDT capabilities. |
| Hydride-Dehydride Powder Capacity Expansion | Toho Titanium and OSAKA Titanium Technologies target spinal implant OEMs with near-net-shape geometries. |
Research Methodology
Desk research of customs trade data, SAMR-administered GB/T standards filings, and EASA certification registries preceded structured interviews with vacuum arc remelting metallurgists, aerospace procurement directors at Boeing and Airbus, defense contract officers, and biomedical implant OEM supply chain leads. Primary fieldwork triangulated against secondary validation from SEC 10-K disclosures, titanium sponge import statistics, and ASTM/AMS specification updates. Bottom-up alloy demand modeling and top-down aerospace bill-of-materials analysis converged on segment-level outputs.
Assumptions held Kroll-process energy intensity, dual-source certification timelines, and FAA/EASA airworthiness directive stringency constant across the projection horizon while varying Chinese sponge capacity expansion rates and EU carbon border adjustment implementation. Segmentation by product type, melting technology, application end-use, and end-user industry drove volume allocation. CAGRs derived from elasticity-adjusted aerospace build rates and orthopedic procedure volume forecasts. Forecast inputs included Boeing and Airbus delivery schedules, F-35 production lot commitments, and METI-funded titanium powder metallurgy adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese producers to secure EASA qualified supplier status ahead of schedule would shift outcomes. Material shifts in electrolytic reduction commercialization or Russia-Ukraine conflict escalation affecting VSMPO-AVISMA supply continuity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rare Earth Metals Market
Metals
Nickel Market
Metals
Metal Forging Parts Market
Metals
High Purity Pig Iron Market
Metals
Brazil Aluminum Market
Metals
Zinc Plating Market
Metals
Global Bronze Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Global Brass Rods Market
Metals
Recycled Metal Market
Metals
Platinum Market
Metals
High Purity Boron Market
Metals
Beryllium Market
Metals
Aluminum Extrusion Market
Metals
Copper Foil Market
Metals
Nickel Sulfate Market