
 US and Mexico Stainless Steel Market | 2026-2036
US and Mexico Stainless Steel Market Size, Share, and Industry Trends Forecast 2026-2036
US and Mexico Stainless Steel Market Intelligence
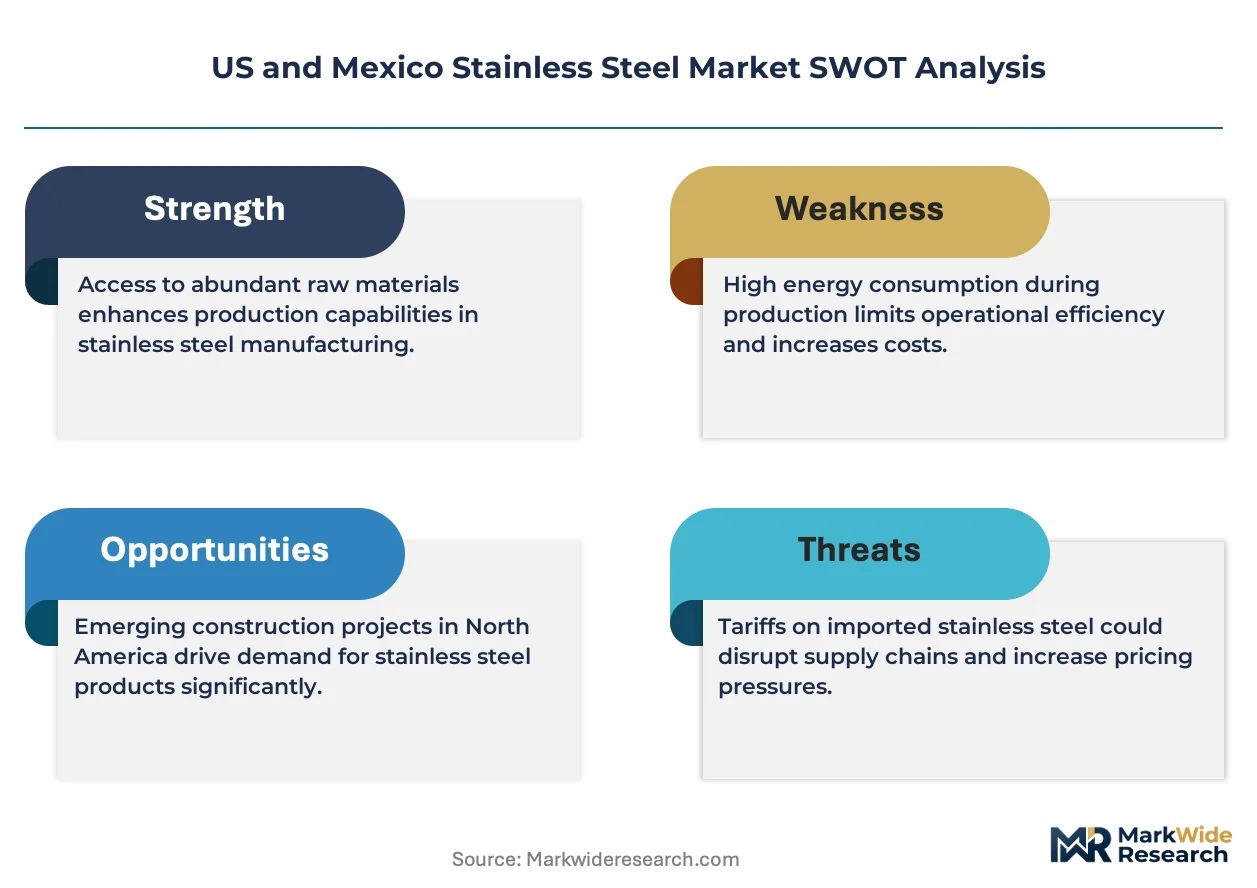
Asset-light leasing arrangements for melt shop equipment is tilting competitive dynamics toward firms that can scale without owning full production footprints. ArcelorMittal leverages its integrated mini-mill network to control slab-to-coil conversion costs across the Great Lakes region. North American Stainless anchors its position through captive chromium and nickel logistics from European parent operations. ATI specializes in high-performance austenitic and duplex grades for aerospace and chemical processing applications.
Stainless steel denotes iron-chromium alloys containing minimum ten-point-five percent chromium by mass, with nickel, molybdenum, and nitrogen additions engineered for corrosion resistance, oxidation tolerance, and cryogenic performance across process environments. Flat products dominate volume flows into construction cladding and automotive exhaust systems, while duplex grades command premium positioning in offshore oil and desalination infrastructure. The thickness segmentation reveals heavy gauge absorbing disproportionate capital allocation as US petrochemical expansion and Mexican energy infrastructure drive plate and thick-walled tube demand.
US EPA emissions standards under the Clean Air Act and OSHA hexavalent chromium exposure limits shape melt shop investment requirements and finishing line automation decisions. Mexico's SECRETARÍA DE ECONOMÍA enforces NOM standards for structural stainless in public works, aligning with US ASTM specifications for cross-border project eligibility. Buyers must monitor how NHTSA vehicle lightweighting mandates and evolving IRA domestic content thresholds regrade supplier qualification criteria across the integrated North American supply base.
Market Dynamics
US Inflation Reduction Act domestic content provisions are redirecting capital toward North American melt-and-pour capacity, compressing lead times for qualified suppliers while raising barriers for import-dependent fabricators serving federal procurement streams.
Growth Catalysts
- Automotive electrification:Battery enclosure and thermal management systems demand higher-grade austenitic and duplex alloys with enhanced corrosion resistance. OEMs are qualifying new material specifications for electric powertrain architectures.
- US Gulf Coast infrastructure corridor:Petrochemical expansion and LNG export terminal construction absorb heavy-gauge plate and thick-walled tube volumes at premium pricing tiers.
- IRA domestic content thresholds:Federal procurement rules now require specified percentages of North American melt-and-pour content, accelerating localized supply chain investment.
Market Restraints
- Nickel and chromium price volatility:LME price swings for these alloying elements compress mill margins and complicate long-term contract pricing for fabricators.
- European parent dependency:Captive raw material logistics from overseas group operations create currency and transit risk for US-based melt shops.
- High-performance grade substitution:Advanced polymer composites and titanium alloys displace duplex stainless in select aerospace and offshore applications.
Strategic Opportunities
- Mexican energy infrastructure:CFE power generation and Pemex refinery modernization programs generate demand for corrosion-resistant piping and pressure vessel grades.
- Desalination plant construction:Severe drought conditions across the US Southwest and northern Mexico drive specification of super-duplex alloys for reverse osmosis systems.
- Digital melt shop integration:AI-driven furnace control and predictive maintenance platforms reduce energy intensity and improve yield rates for early adopters.
Industry Challenges
- Skilled furnace operator scarcity:Electric arc furnace and argon oxygen decarburization expertise commands premium wages as experienced cohorts retire.
- ASTM-NOM cross-border alignment:Mexican SECRETARÍA DE ECONOMÍA structural standards and US specifications require dual certification for integrated project eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Mexico Stainless Steel Market |
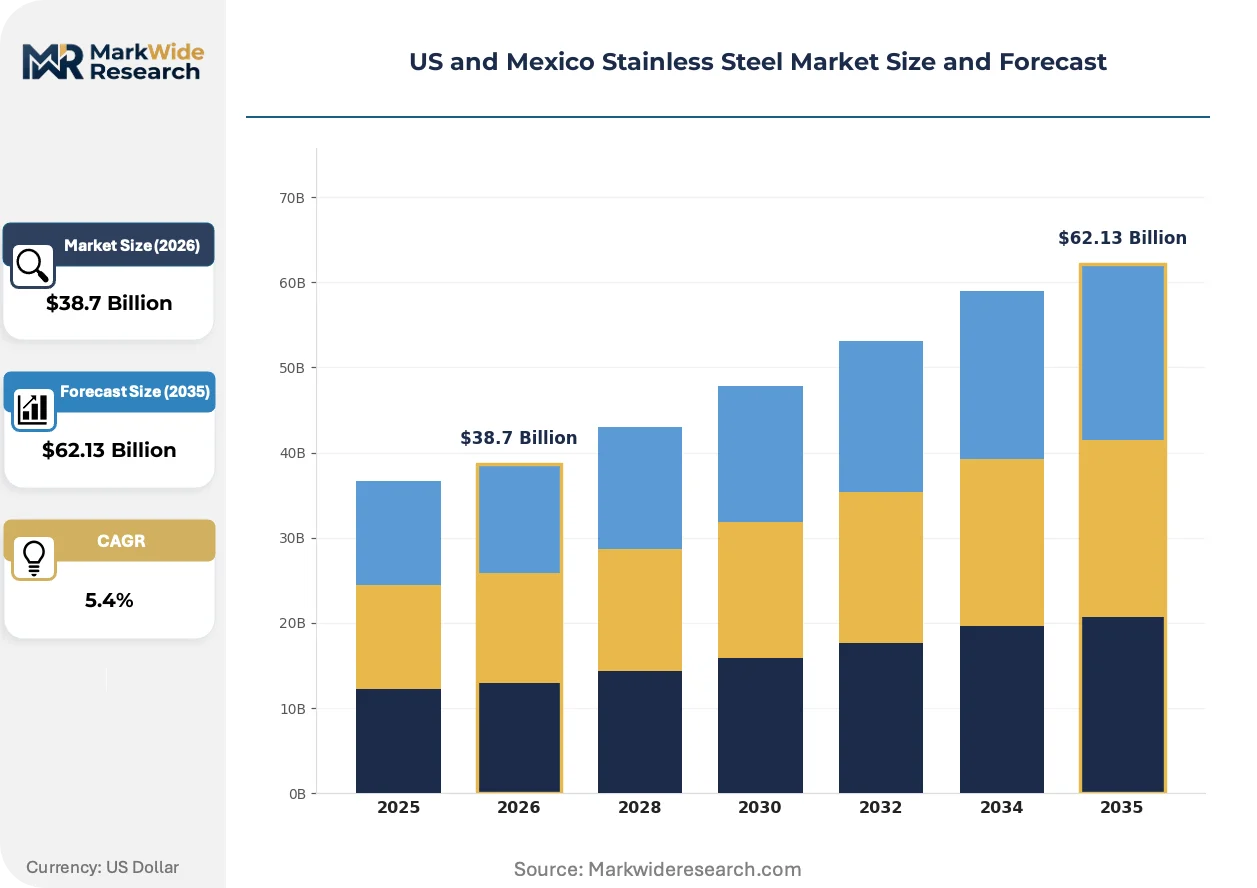
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Products, Long Products, Tubes, Bars End User: Construction, Automotive Parts, Appliances, Electronics Thickness: Light Gauge, Medium Gauge, Heavy Gauge, Ultra Heavy Gauge Grade: Austenitic, Ferritic, Martensitic, Duplex |
| Companies Covered | ArcelorMittal, Aperam Stainless, North American Stainless, Universal Stainless, AK Steel International, Outokumpu, POSCO, Continental Steel & Tube Company, ATI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Mexico Stainless Steel Market Strategic Shifts & Innovations
Active transformation across the US and Mexico stainless steel market centers on metallurgical precision, regulatory compliance automation, and buyer consolidation reshaping supplier relationships.
Advanced duplex and super-duplex grades are hybridizing corrosion resistance with mechanical strength for subsea umbilical and chemical processing applications. Offshore oil operators and desalination engineering firms are accelerating specification of these alloys. The technology is hybridizing what were separate material selection decisions for strength and corrosion into unified procurement frameworks.
OSHA hexavalent chromium exposure limits are tightening melt shop ventilation and automation requirements. Facilities must retrofit fume capture systems and reduce manual finishing operations. Heavy-gauge plate producers serving petrochemical clients face the steepest compliance costs and longest implementation timelines.
Consolidated procurement by EPC firms and automotive tier-ones is compressing supplier bases and demanding integrated mill-to-fabricator service bundles. Long-term offtake agreements with volume commitments are displacing spot market purchases. The US Gulf Coast petrochemical corridor exhibits this concentration most acutely, with major contractors qualifying only two to three approved mill sources per grade family.
US and Mexico Stainless Steel Market Segmentation
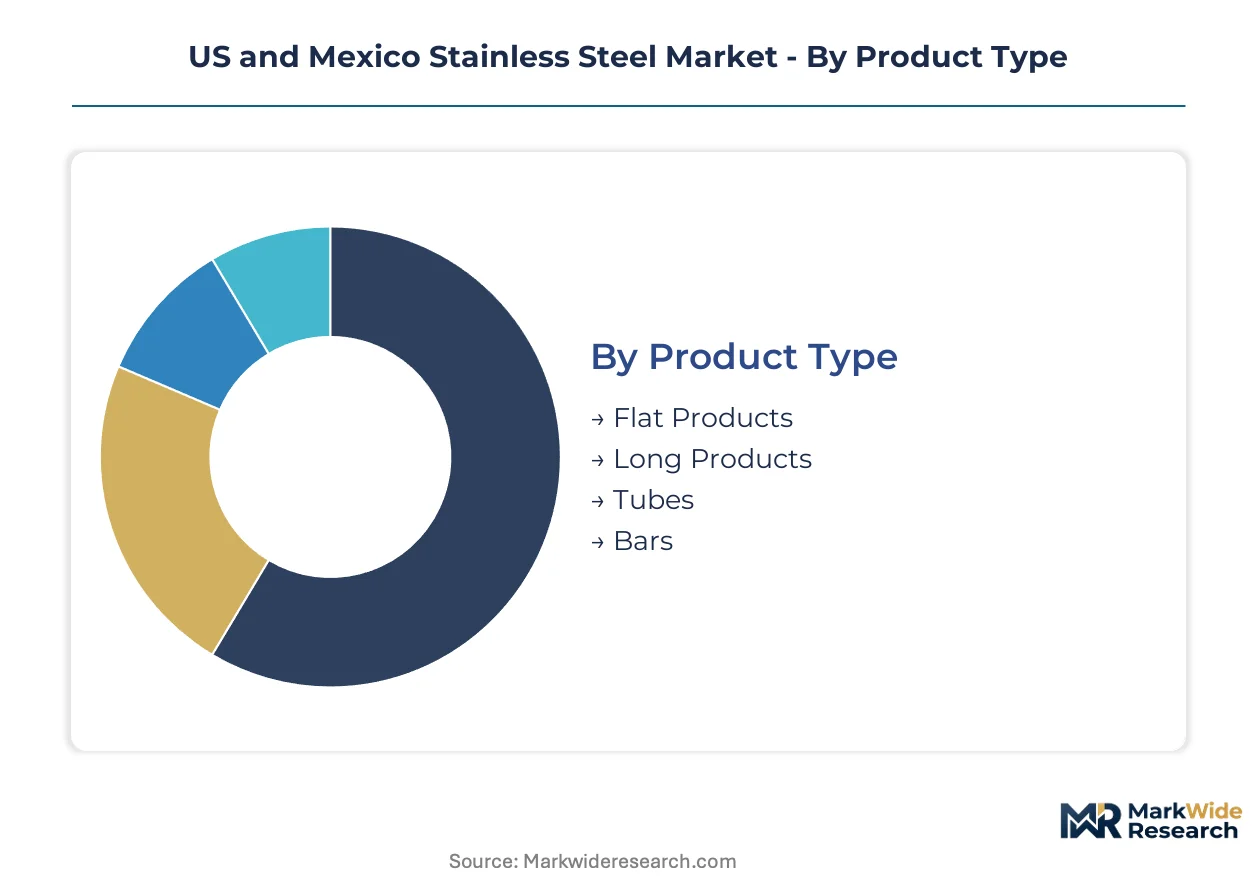
Segmentation in the US and Mexico stainless steel market reveals how product specifications, end-use requirements, and processing constraints create distinct competitive arenas. Each dimension—product form, application, thickness, and metallurgical grade—carries different margin profiles and qualification barriers that reshape supplier positioning across North American melt shops.
Product Type:
Cost tier differentiation separates commodity coil from engineered long products and precision tubes, with conversion economics varying sharply by rolling mill configuration.
- Flat Products:Hot-rolled and cold-rolled coils and sheets dominate tonnage flows. Construction cladding and automotive exhaust systems absorb the majority of volumes across the US Gulf Coast corridor and Mexican manufacturing hubs. Mills with continuous annealing lines capture premium pricing for surface-critical architectural grades.
- Long Products:Angles, channels, and structural sections serve infrastructure and industrial fabrication. Pemex refinery modernization and CFE power generation projects in Mexico specify these forms for structural supports and process piping frameworks.
- Tubes:Seamless and welded tubular products span heat exchangers, hydraulic lines, and pressure vessels. ASTM A312 and NOM-aligned specifications govern cross-border project eligibility.
- Bars:Round, square, and hexagonal bar stock feeds machining centers and forging operations. Tooling and fastener manufacturers in the US Midwest and northern Mexico represent core demand clusters.
Flat products command the established base. The steepest expansion runs through tubes serving petrochemical and energy infrastructure.
End User:
Application intensity varies dramatically, with some sectors demanding certified melt-and-pour provenance while others prioritize spot availability.
- Construction:Architectural cladding, structural framing, and roofing systems specify austenitic grades for corrosion resistance. US Gulf Coast petrochemical facilities and Mexican public works projects drive heavy-gauge plate consumption.
- Automotive Parts:Battery enclosures, thermal management systems, and exhaust components require higher-grade austenitic and duplex alloys. NHTSA lightweighting mandates and IRA domestic content thresholds regrade supplier qualification criteria.
- Appliances:Refrigerator interiors, dishwasher tubs, and cooking surfaces utilize ferritic grades for cost efficiency. Surface finish requirements separate premium from standard appliance tiers.
- Electronics:Precision strip and foil serve connectors, shielding, and semiconductor processing equipment. Miniaturization trends push toward ultra-thin cold-rolled specifications.
Construction retains the volume anchor. Automotive parts are climbing the fastest as electrification regrades material specifications.
Thickness:
Volume distribution skews toward lighter gauges, yet capital allocation concentrates disproportionately on heavy plate capacity.
- Light Gauge:Material below 3mm thickness serves automotive body panels, appliance skins, and electronics substrates. Continuous cold mills with tension leveling deliver the surface quality required for visible applications.
- Medium Gauge:3mm to 12mm plate balances structural adequacy with forming flexibility. General industrial fabrication across Texas and northern Mexico represents steady demand.
- Heavy Gauge:12mm to 50mm plate absorbs the majority of US petrochemical expansion and LNG export terminal construction. Quench-and-temper capabilities separate qualified suppliers from commodity producers.
- Ultra Heavy Gauge:Above 50mm plate serves pressure vessels, reactor components, and offshore platform structures. Limited North American rolling capacity creates supply bottlenecks for thick-walled specifications.
Light gauge holds the broadest installed base. Ultra heavy gauge is gaining share fastest as energy infrastructure projects absorb available capacity.
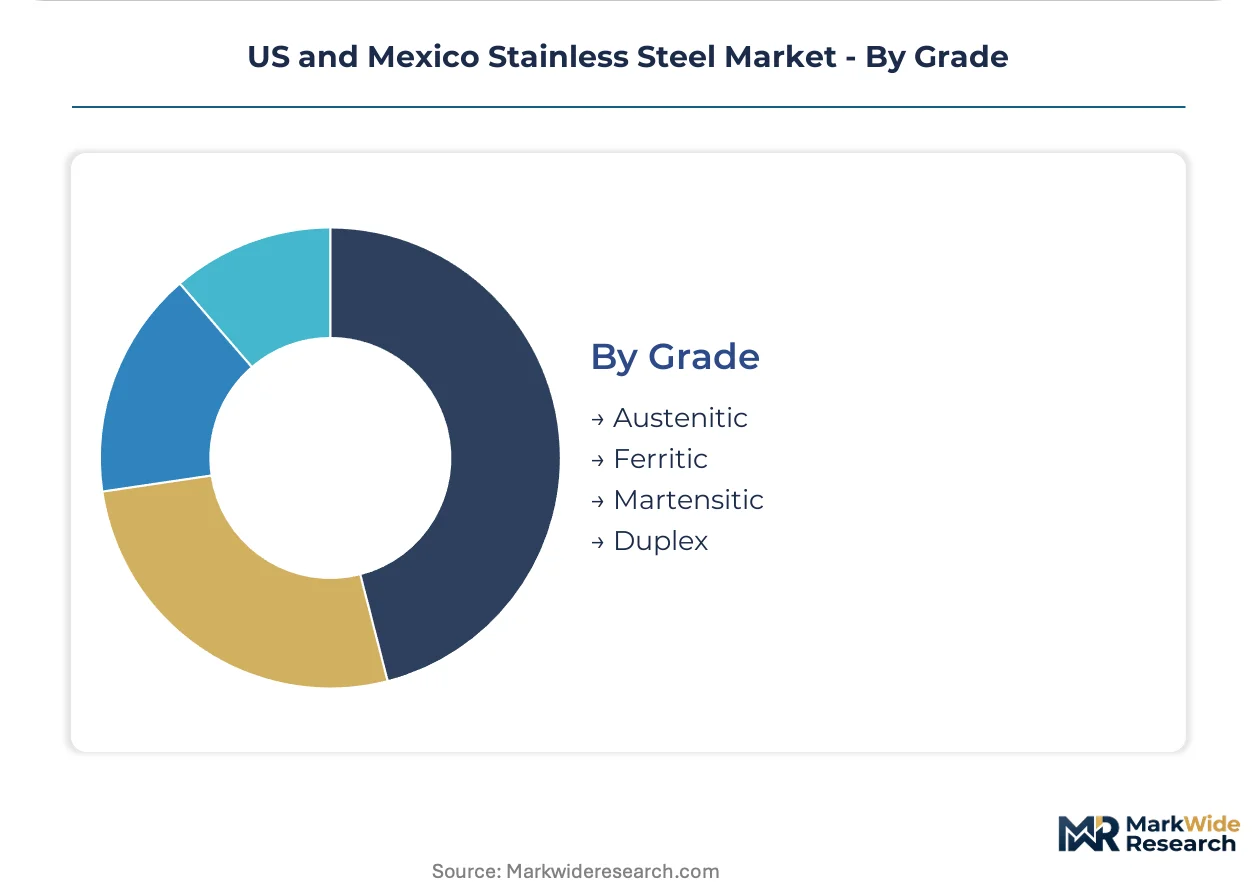
Grade:
Metallurgical sophistication determines corrosion resistance, mechanical properties, and pricing tier, with alloy content driving raw material exposure.
- Austenitic:Chromium-nickel alloys in the 300 series deliver superior corrosion resistance and formability. Food processing, chemical handling, and architectural applications specify these grades most heavily.
- Ferritic:Chromium grades without nickel addition offer cost advantages for less demanding environments. Automotive exhaust systems and appliance interiors represent primary outlets.
- Martensitic:Hardenable chromium grades serve cutting tools, surgical instruments, and wear-resistant components. Heat treatment capabilities constrain supplier participation.
- Duplex:Balanced austenitic-ferritic microstructures combine strength with chloride resistance. Desalination plants across the US Southwest and offshore oil applications specify super-duplex variants.
Austenitic grades anchor the established base. Duplex alloys are expanding most quickly as offshore and desalination engineering firms accelerate specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows between the US and Mexico concentrate on semi-finished slab and coil movements, with Mexican fabricators importing US melt-and-pour material to satisfy IRA domestic content thresholds for re-export to American federal procurement streams.
United States Gulf Coast
Petrochemical expansion and LNG export terminal construction absorb heavy-gauge plate volumes at premium pricing tiers. EPA Clean Air Act emissions standards under Title V shape melt shop investment requirements across Texas and Louisiana facilities. The Houston Ship Channel corridor hosts concentrated demand from EPC firms qualifying limited approved mill sources per grade family.
US Great Lakes Region
Automotive battery enclosure and thermal management systems demand higher-grade austenitic and duplex alloys with enhanced corrosion resistance. NHTSA vehicle lightweighting mandates regrade supplier qualification criteria for OEM qualification programs. Detroit-Windsor automotive clusters drive specification of surface-critical grades for visible powertrain components.
Mexico Northern Border States
Maquiladora fabricators serving US federal procurement streams require certified North American melt-and-pour provenance to satisfy IRA domestic content thresholds. SECRETARÍA DE ECONOMÍA enforces NOM standards for structural stainless in public works, aligning with US ASTM specifications. Nuevo León and Chihuahua host concentrated stamping and exhaust component operations for tier-one automotive suppliers.
Mexico Central Highlands
CFE power generation and Pemex refinery modernization programs generate demand for corrosion-resistant piping and pressure vessel grades. Mexican energy infrastructure investment directs specification toward duplex and super-duplex variants for process environments. The Bajío Region's industrial corridor absorbs medium-gauge structural sections for manufacturing facility construction.
US Southwest
Severe drought conditions drive specification of super-duplex alloys for reverse osmosis systems in desalination plant construction. OSHA hexavalent chromium exposure limits tighten finishing line automation decisions for regional fabricators. Arizona and southern California host engineering procurement concentrated on chloride-resistant grades for municipal water infrastructure.
US and Mexico Stainless Steel Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower conversion scope. The US and Mexico stainless steel market structures around integrated melt-to-coil operators, toll-processing specialists, and distribution-focused service centers. Three archetypes dominate: European-parented multinationals with captive raw material logistics, North American mini-mill networks optimizing slab-to-coil conversion costs, and high-performance alloy specialists serving aerospace and chemical processing niches. Competitive moves concentrate on capacity expansion for heavy-gauge plate and strategic partnerships securing IRA-qualified domestic content streams.
Among European-parented operators, ArcelorMittal and North American Stainless occupy positions anchored to overseas group logistics for chromium and nickel supply security. ATI represents the high-performance specialist archetype, sitting within the premium-grade tier for aerospace and chemical processing applications. These three exemplify how competitive positioning stratifies across commodity coil, engineered long products, and precision specification tiers.
| Leading Market Players |
|---|
| ArcelorMittal |
| Aperam Stainless |
| North American Stainless |
| Universal Stainless |
| AK Steel International |
| Outokumpu |
| POSCO |
| Continental Steel & Tube Company |
| ATI |
| Others |
Cost & Logistics Intelligence
The Houston Ship Channel corridor concentrates heavy-gauge plate capacity for US Gulf Coast petrochemical expansion, translating supply scarcity into sustained pricing leverage for qualified mills serving EPC firms with limited approved supplier lists.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that displace spot market purchases. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale commitments. Cost compression in commodity coil is intensifying because nickel and chromium LME volatility squeezes mill margins. Automotive tier-one suppliers exhibit highest price sensitivity due to IRA domestic content threshold pressures, while desalination engineering firms show lowest sensitivity for super-duplex specifications.
Supply Chain Analysis
Tariff exposure between the US and European Union dominates supply chain risk planning for chromium and nickel logistics. Raw material sourcing draws from South Africa, Indonesia, and Russia for ferrochrome and nickel pig iron. Single-source vulnerability concentrates in European parent-dependent captive supply chains. Distribution runs through mill-direct arrangements with EPC firms and automotive tier-ones, bypassing traditional service center intermediaries for qualified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and technical specification support expand faster than base metal tonnage, rewarding suppliers that bundle metallurgical consulting with physical delivery.
For Market Incumbents: Pre-empt substitution pressure from advanced polymer composites in aerospace applications by deepening captive supply of super-duplex grades and securing NHTSA-qualified positions for battery enclosure specifications. Add heavy-gauge quench-and-temper capacity in the US Gulf Coast corridor to defend against import-dependent fabricators.
For New Entrants and Emerging Players: Pursue toll-processing arrangements for IRA-qualified domestic content streams serving Mexican maquiladora re-export operations. The most penetrable white-space sits in digital melt shop integration platforms for mid-tier mills lacking AI-driven furnace control capabilities. Lead with outcome-based energy reduction guarantees rather than equipment sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors high-performance alloy specialists with aerospace and chemical processing certifications over commodity coil producers. Long-term viability hinges on desalination and offshore oil specification momentum. Watch Pemex refinery modernization contract awards as inflection indicators for Mexican energy infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Gauge Capacity Expansion | Captures premium pricing from US Gulf Coast LNG terminal construction and petrochemical plate demand. |
| Backward Integration into Nickel Logistics | Reduces European parent dependency and LME volatility exposure for melt shop operations. |
| Digital Melt Shop Integration | Lowers energy intensity and improves yield rates through AI-driven furnace control platforms. |
| Long-Term Supply Agreement with EPC Firms | Secures qualified supplier status for federal procurement streams under IRA domestic content rules. |
| Joint Venture for Mexican Energy Infrastructure | Positions for CFE and Pemex corrosion-resistant piping specifications in refinery modernization programs. |
Research Approach
A spread of perspectives from melt shop operations directors, EPC procurement leads, automotive tier-one metallurgists, and SECRETARÍA DE ECONOMÍA standards officials converged on the working assumptions for capacity and demand modeling. Primary fieldwork combined with secondary validation from USGS mineral commodity summaries, LME price data, SEC 10-K filings for listed mill operators, and ASTM specification databases. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to test internal consistency.
Demand-supply balance dynamics across the analysis window were modeled through grade-specific consumption coefficients by end-use sector. Segmentation dimensions included product form, thickness tier, metallurgical grade family, and regional production cluster. CAGRs were derived from regression against historical consumption patterns and project pipeline visibility. Forecast inputs incorporated NHTSA lightweighting mandate implementation trajectories and IRA domestic content threshold phase-in schedules.
Sensitivities concentrate around nickel and chromium price volatility, Pemex capital expenditure execution, and OSHA hexavalent chromium compliance timeline shifts. Forecasts reflect documented assumptions on electrification-driven specification upgrades and cross-border trade flow continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
High-End Copper Foil Market
Metals
Carbotanium Market
Metals
Neodymium Market
Metals
Global Copper Cathode Market
Metals
Potassium Platinochloride Market
Metals
Ferrochrome Market
Metals
High Purity Iron Powder Market
Metals
Aluminium Conductors Market
Metals
Global Tin Market
Metals
Anodized Titanium Market
Metals
Silver Sulphate Market
Metals
Lightweight Aluminium Pistons Market
Metals
Scandium Market
Metals
Global Tool Steel Market
Metals
Global Duplex Stainless Steel Market