
 Qatar Metalworking Market | 2026-2036
Qatar Metalworking Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Metalworking Market Insights
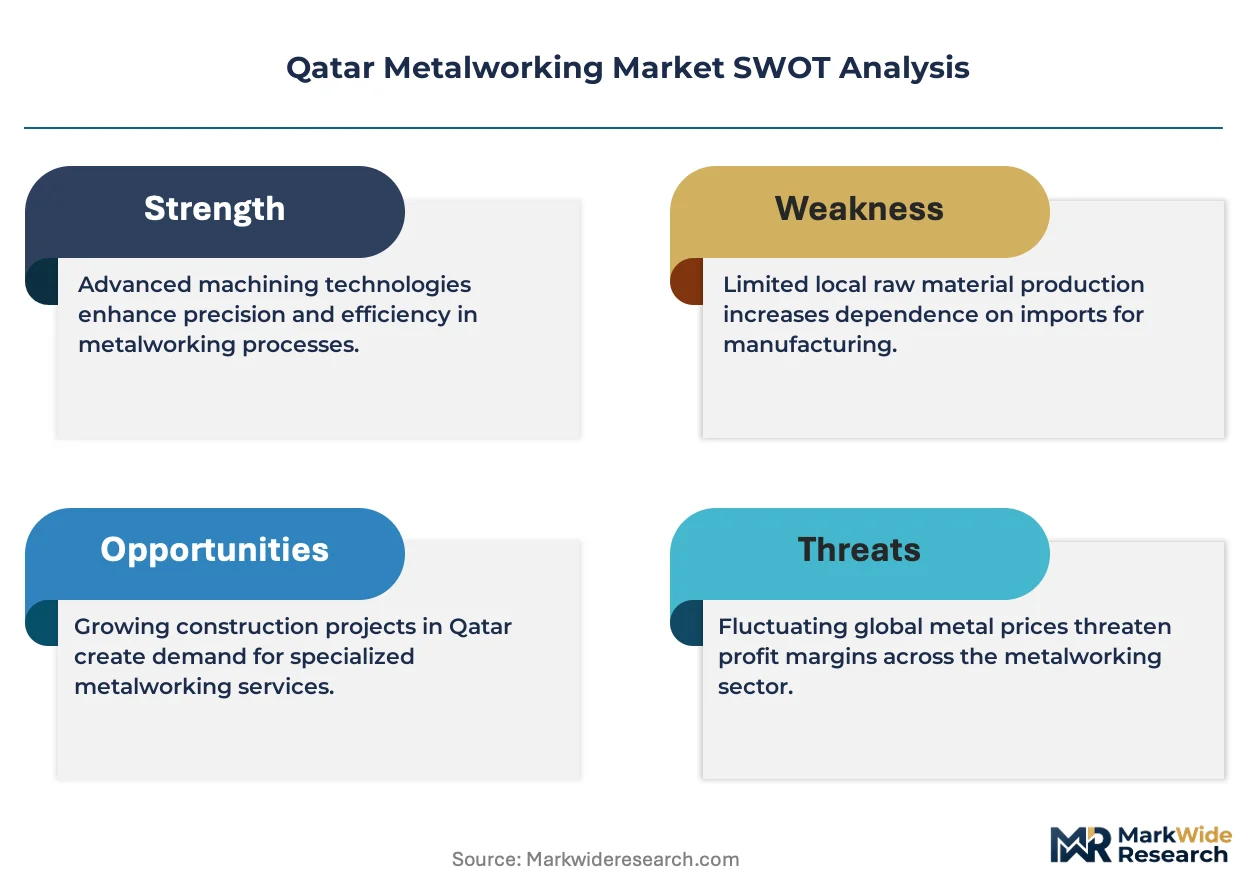
Project finance tied to Qatar's infrastructure pipeline is reshaping competitive access for metalworking suppliers. Qatar Steel Company leverages captive billet supply to sustain cost advantages across rebar and structural sections. Eversendai Group anchors its position through fabrication capacity co-located with major project sites. Pioneer Metal Company differentiates via specialized architectural metalwork for premium developments.
Qatar metalworking encompasses the cutting, forming, joining, and finishing of metallic materials to produce industrial components, typically involving tolerances from sub-millimeter precision to heavy-section fabrication for load-bearing structures. The primary purpose spans supply of processed metals to construction, energy, and transportation infrastructure where mechanical integrity and dimensional accuracy determine safety margins. Machinery and equipment categories lead current revenue pools as contractors prioritize automated fabrication for speed and repeatability on megaproject timelines. CNC Machining and Welding technologies capture expanding share as project specifications tighten on joint quality and geometric precision for complex structural nodes.
Qatar's Ministry of Commerce and Industry administers import conformity programs that filter substandard metal products from entering project supply chains. The Qatar General Organization for Standardization (QS) mandates compliance with Gulf Standardization Organization (GSO) technical regulations for structural steel and welding consumables. Contractors and fabricators must monitor evolving certification requirements as Qatar advances localization targets under its national industrial strategy.
Market Dynamics
Project finance concentration around Qatar's infrastructure pipeline is compressing supplier selection timelines while elevating certification requirements for structural steel imports. Fabricators must now pre-qualify billet sources and welding consumables before tender submission to state-backed megaproject consortia.
Growth Catalysts
- QS-GSO Conformity Mandates:The Qatar General Organization for Standardization enforces Gulf Standardization Organization technical regulations for structural steel, filtering substandard imports and elevating certified fabricator margins.
- Megaproject Pipeline Density:Doha's industrial zone clusters concentrate demand from stadium, port, and rail contractors requiring precision-fabricated nodes with sub-millimeter tolerances.
- CNC-Welding Hybrid Systems:Automated fabrication cells combining computer numerical control machining with robotic welding are compressing production cycles for complex geometric joints on stadium roof structures.
Market Restraints
- Billet Import Dependency:Qatar lacks primary steelmaking capacity, exposing fabricators to scrap metal and hot-rolled coil price volatility from GCC and Asian suppliers.
- Specialized Labor Scarcity:Certified welders qualified to AWS D1.1 and ISO 9606-1 standards remain concentrated among a handful of Doha-based contractors, constraining capacity expansion.
- Subcontractor Tier Fragmentation:Small architectural metalwork shops dominate secondary fabrication, creating quality inconsistency for premium development facades requiring precision finishing.
Strategic Opportunities
- Lusail Smart City Infrastructure:The new city district's integrated utility tunnels and transit nodes demand corrosion-resistant stainless fabrication for coastal exposure conditions.
- Localization Incentives:Qatar's national industrial strategy offers preferential procurement access to fabricators achieving 40% local value-add in steel processing operations.
- Digital Twin Integration:Building information modeling-to-fabrication workflows are enabling just-in-time delivery of structural components directly to megaproject sites, compressing inventory carrying costs.
Industry Challenges
- Certification Timeline Compression:QS import conformity assessments for welding consumables now require 8-12 week validation cycles, misaligning with 4-6 week project mobilization schedules.
- Multi-Standard Welder Qualification:Fabricators must maintain parallel ASME, AWS, and ISO welding procedure qualifications to serve oil & gas and construction sectors simultaneously, elevating training overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Metalworking Market |
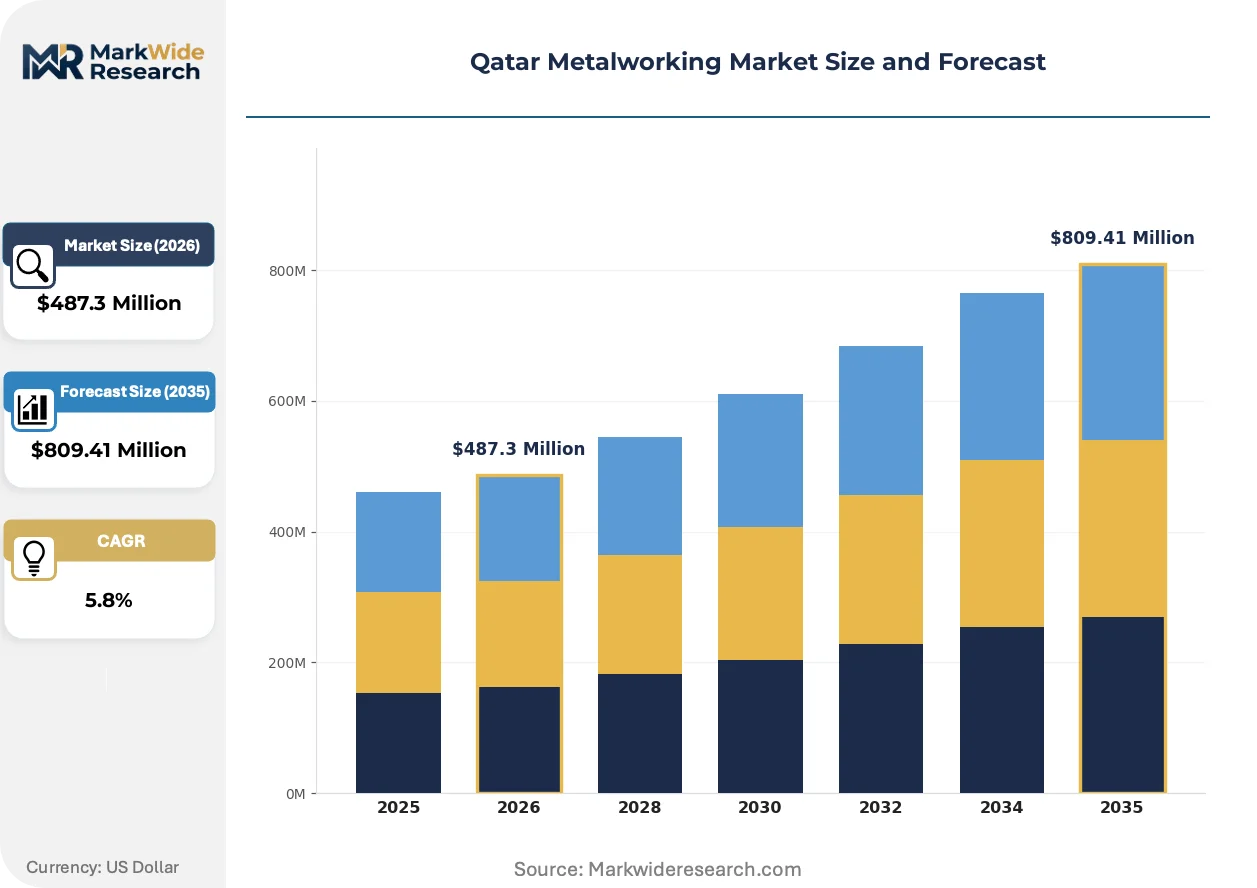
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machinery, Tools, Equipment, Components Material Type: Ferrous, Non-Ferrous, Alloys, Composites End User: Aerospace, Automotive OEMs, Construction, Marine Technology: Additive Manufacturing, CNC Machining, Welding, Casting |
| Companies Covered | Eversendai Group, Qatar Blue Steel Factory WLL, CLIC Qatar Trading Company WLL, Qatar Reinforcement Company, Pioneer Metal Company, Qatar Steel Company, Qatar Technical International Co., Al Watania Steel, Axis Engineering & Mechanical Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Metalworking Market Trends and Innovations
Digital fabrication workflows and regulatory digitization are compressing the traditional design-to-delivery cycle for structural metal components in Qatar's project-driven market. These shifts are reconfiguring competitive advantage around data integration rather than pure production scale.
Building information modeling is virtualizing the traditional steel detailing and shop drawing process, enabling clash detection and automated nesting before material procurement. Major stadium and transit contractors now mandate BIM Level 2 compliance for structural steel packages, forcing fabricators to invest in interoperability with Tekla and Revit platforms. This virtualization is compressing rework rates and enabling just-in-time delivery windows that align with megaproject crane schedules.
The Qatar General Organization for Standardization is digitizing its QS mark conformity assessment portal, streamlining import documentation for structural steel and welding consumables. Industrial users now submit test reports and factory audit certificates through an integrated online system, reducing physical document processing from weeks to days. Fabricators serving multiple megaproject sites are consolidating their certification management through this portal to maintain tender eligibility.
Buyer concentration among state-backed project developers is consolidating procurement authority into centralized engineering-procurement-construction management firms. Tier-one contractors now bundle structural steel packages across multiple sites, displacing fragmented site-by-site purchasing. This concentration is most visible in Doha's Msheireb and Lusail districts, where single procurement entities coordinate fabrication schedules across residential, commercial, and infrastructure verticals.
Qatar Metalworking Market Segmentation
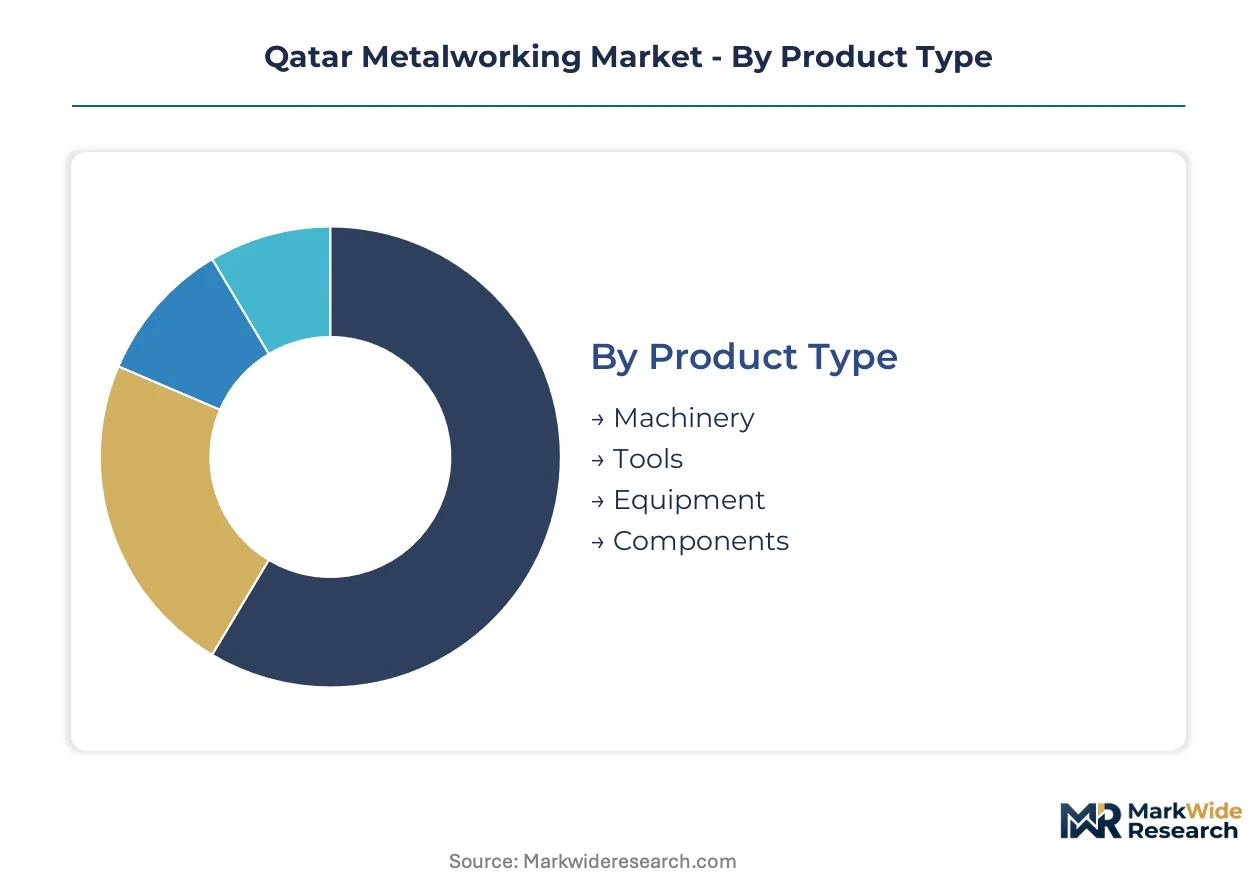
Segmentation in Qatar's metalworking market reveals how procurement patterns split between project-driven bulk fabrication and precision-component supply. Understanding these divisions exposes where service intensity, certification requirements, and margin structures diverge across customer tiers.
Product Type:
After-sales service intensity varies sharply across product categories, with machinery requiring dedicated technical support contracts while components demand minimal post-sale engagement.
- Machinery:Heavy fabrication systems including CNC plasma cutters, hydraulic presses, and robotic welding cells demand intensive commissioning support and preventive maintenance programs. Doha's industrial zone clusters concentrate demand from megaproject contractors requiring 24/7 uptime guarantees on automated production lines serving stadium and transit infrastructure timelines.
- Equipment:Auxiliary systems such as material handling rigs, positioning tables, and fume extraction units carry moderate service attachment rates. Demand concentrates among mid-tier fabricators in Ras Laffan Industrial City expanding capacity to serve oil & gas maintenance contracts.
- Tools:Consumable and portable equipment including cutting discs, measuring instruments, and hand power tools generate minimal service revenue. Procurement flows through distributor networks serving small architectural metalwork shops.
- Components:Precision-fabricated parts and sub-assemblies require quality certification documentation rather than ongoing technical support. Lusail Smart City contractors source these through just-in-time delivery contracts.
By volume, Components lead. By growth pace, Machinery is ahead.
Material Type:
Cost tier differentiation structures supplier relationships, with premium alloys commanding dedicated technical advisory while commodity ferrous metals trade on price and availability.
- Ferrous:Carbon steel and cast iron dominate structural fabrication for load-bearing applications. Qatar Steel Company's captive billet supply anchors domestic rebar and section production for construction contractors.
- Non-Ferrous:Aluminum and copper alloys serve electrical, HVAC, and marine corrosion applications. Demand concentrates in Lusail's coastal infrastructure requiring salt-resistant material specifications.
- Alloys:Stainless and specialty steel grades command premium positioning for architectural facades and process equipment. QS-GSO conformity mandates filter substandard imports, elevating certified distributor margins.
- Composites:Metal-matrix and fiber-reinforced hybrid materials occupy niche aerospace and high-performance segments. Limited local demand restricts stocking levels among Doha-based distributors.
Ferrous materials anchor volume throughput. Alloys are climbing the fastest on certification premiums.
End User:
Application-specific requirements fragment procurement authority, with construction bundling large packages while aerospace demands traceable single-source qualification.
- Construction:Megaproject contractors drive the dominant revenue pool, procuring structural steel packages across stadium, port, rail, and residential verticals. Centralized engineering-procurement-construction management firms in Msheireb and Lusail coordinate fabrication schedules.
- Automotive OEMs:Limited local vehicle assembly restricts this segment to aftermarket parts and service center equipment. Specialized tool suppliers serve dealership maintenance networks.
- Aerospace:Qatar Airways maintenance facilities and Al Udeid Air Base generate precision machining demand. AS9100 certification requirements constrain qualified supplier pools.
- Marine:Port expansion and offshore support vessel maintenance drive corrosion-resistant fabrication. Ras Laffan shipyards source specialized welding consumables through approved vendor lists.
Construction commands the largest share. Marine applications are expanding most quickly on port infrastructure timelines.
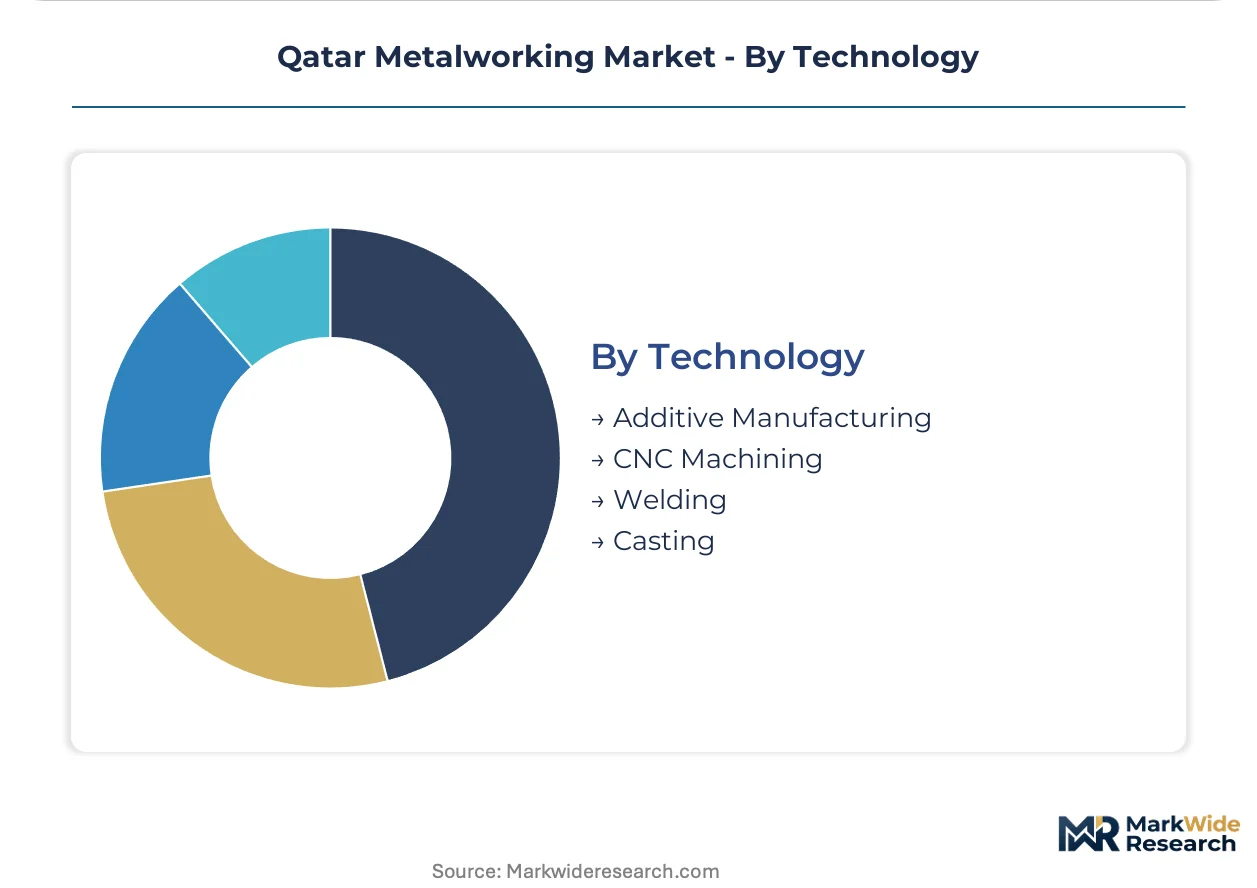
Technology:
Customer type splits between automated fabrication adopters prioritizing speed and repeatability versus conventional shops defending established process investments.
- CNC Machining:Computer-controlled milling, turning, and grinding systems deliver sub-millimeter precision for complex structural nodes. Stadium roof contractors mandate BIM-integrated nesting to minimize material waste.
- Welding:Manual and automated joining processes remain central to structural fabrication. Certified welders qualified to AWS D1.1 and ISO 9606-1 standards concentrate among Doha-based tier-one contractors.
- Casting:Foundry production of complex geometric components serves valve, pump, and machinery OEMs. Limited local capacity pushes procurement toward GCC suppliers.
- Additive Manufacturing:Metal 3D printing occupies prototype and spare part production niches. Oil & gas operators trial directed energy deposition for obsolete component replacement.
Welding leads by installed base. Additive Manufacturing is gaining share fastest on digitalization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's national industrial strategy channels investment into localized metal fabrication capacity, with preferential procurement access tied to value-add thresholds. The Ministry of Commerce and Industry enforces QS-GSO conformity mandates that filter import supply chains. Industrial demand clusters in Doha's specialized zones serving megaproject contractors.
Doha Industrial Zone
The capital's concentrated fabrication capacity serves stadium, port, and rail contractors requiring precision-fabricated structural nodes. The Qatar General Organization for Standardization administers import conformity programs from offices in Doha. Msheireb Downtown and Lusail districts host centralized engineering-procurement-construction management firms coordinating multi-site fabrication schedules.
Ras Laffan Industrial City
Oil and gas maintenance contracts drive demand for corrosion-resistant fabrication and specialized welding consumables. The Ministry of Commerce and Industry monitors compliance with Gulf Standardization Organization technical regulations for offshore structural applications. Shipyards and energy contractors source approved vendor list materials through cluster distributors.
Al Wakrah Municipality
Port expansion timelines accelerate marine-grade metalwork demand for vessel maintenance and offshore support infrastructure. QS-GSO mandates govern structural steel imports for coastal exposure conditions. Industrial users in the southern corridor consolidate procurement through digitized conformity assessment portals.
Umm Salal Municipality
Logistics and warehousing development generates secondary demand for material handling systems and light structural fabrication. The national industrial strategy's localization incentives attract fabricators seeking preferential access to state-backed project pipelines. Emerging industrial zones here process steel components for redistribution to northern megaproject sites.
Al Khor Municipality
Northern infrastructure corridors connecting to industrial hinterlands require heavy-section fabrication for load-bearing transportation structures. Municipal planning aligns with Qatar's broader supply chain security objectives for processed metals. Fabricators here leverage proximity to port facilities for billet and hot-rolled coil receipt.
Qatar Metalworking Market Competitive Landscape
On the supply side, the industry is tiered between integrated primary producers, project-co-located fabricators, and specialized architectural metalwork shops. Qatar Steel Company anchors the upstream tier through captive billet supply. Eversendai Group and Pioneer Metal Company occupy distinct mid-market and premium positioning vectors. Capacity expansion and certification pre-qualification constitute the dominant competitive moves as tender timelines compress.
Within the integrated production tier, Qatar Steel Company exemplifies backward integration into primary steelmaking inputs that sustains cost positioning across rebar and structural sections. Among project-co-located fabricators, Eversendai Group occupies a position tied to fabrication capacity sited near major construction timelines. Pioneer Metal Company represents the specialized architectural metalwork archetype, serving premium development facades where precision finishing commands margin differentiation. These three anchors illustrate how competitive positioning splits across supply chain control, site proximity, and craft specialization vectors.
| Leading Market Players |
|---|
| Eversendai Group |
| Qatar Blue Steel Factory WLL |
| CLIC Qatar Trading Company WLL |
| Qatar Reinforcement Company |
| Pioneer Metal Company |
| Qatar Steel Company |
| Qatar Technical International Co. |
| Al Watania Steel |
| Axis Engineering & Mechanical Co. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in GCC billet supply is compressing fabrication margins while elevating price volatility for Qatar's import-dependent metalworkers, forcing procurement teams toward long-term offtake contracts to stabilize input costs and protect tender competitiveness.
Pricing Analysis
Certification level under QS-GSO technical regulations creates the primary spread between premium and commodity-grade structural steel. Project-based long-term contracts dominate megaproject procurement, with price differentiation resting on welding procedure qualification depth and BIM integration capability. Cost compression in standard-grade rebar is intensifying because Qatar Steel Company's captive billet supply anchors domestic production. Tier-one contractors show lowest price sensitivity, while small architectural metalwork shops face acute margin pressure from scrap metal volatility.
Supply Chain Analysis
Billet import dependency between GCC suppliers and East Asian mills dominates supply chain risk exposure for Qatar fabricators. Geographic supply concentrates in Saudi Arabia, the UAE, and South Korea for hot-rolled coil and scrap metal inputs. Raw material dependencies rest on iron ore derivatives, welding consumables, and specialized alloying elements. Single-source vulnerability in QS-certified welding consumables creates procurement bottlenecks during megaproject mobilization windows. Distribution runs through Doha-based cluster distributors serving industrial zone contractors with just-in-time delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's metalworking sector is entering a cyclical upswing as infrastructure investment accelerates through the national industrial strategy's localization mandates, creating procurement preference windows for certified domestic fabricators.
For Market Incumbents: Insulate margin structures by deepening backward integration into billet trading partnerships and securing parallel ASME-AWS-ISO welding qualifications before tender timelines compress further. Threat exposure from specialized labor scarcity demands preemptive training academy investments. Certification investment represents the priority defensive lever against emerging GCC competitors.
For New Entrants and Emerging Players: Lusail Smart City's corrosion-resistant stainless fabrication requirements for coastal utility infrastructure represent the most penetrable entry point, given limited qualified local capacity. Secondary targets include digital twin-enabled BIM-to-fabrication workflow services for stadium contractors. Go-to-market positioning should emphasize QS-GSO pre-certification to bypass incumbent qualification barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CNC-welding hybrid system deployments as automation replaces manual fabrication. Long-term viability favors vertically integrated fabricators with captive billet arrangements or project-co-located capacity. The signal to watch is QS digitization timeline acceleration, which will consolidate certification management into platform-enabled players.
| Strategic Initiative | Industry Significance |
|---|---|
| QS-GSO Certification Pre-Qualification | Secures tender eligibility for state-backed megaproject consortia under tightening conformity mandates. |
| CNC-Welding Hybrid System Deployment | Compresses production cycles for complex stadium roof nodes requiring sub-millimeter tolerances. |
| BIM-to-Fabrication Workflow Integration | Enables just-in-time delivery aligned with megaproject crane schedules in Msheireb and Lusail. |
| Localization Value-Add Expansion | Unlocks preferential procurement access under national industrial strategy thresholds. |
| Specialized Welder Training Academy | Addresses certified labor scarcity constraining capacity expansion among Doha-based contractors. |
Research Methodology
A standing panel of fabrication plant managers, megaproject procurement leads, welding engineering supervisors, and QS certification officers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from customs trade data, Gulf Standardization Organization technical regulations, Qatar Chamber of Commerce industry reports, and Ministry of Commerce and Industry licensing records. Bottom-up project pipeline aggregation and top-down industrial capacity assessment were triangulated to reconcile volume estimates.
Scenario-bracketing around infrastructure investment pace and billet price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-use application, and technology adoption intensity. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization trajectories. Forecast inputs incorporated megaproject award timelines and QS digitization rollout schedules.
Macroeconomic conditions sit as an overlay; deviation in oil-linked government spending and GCC trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding localization incentive continuity and certification timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Forging Market
Metals
Metal Coil Lamination Market
Metals
Aluminum Flat-Rolled Products Market
Metals
North America Aluminum Casting Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Industrial Metal Strips Market
Metals
Saudi Arabia Aluminum Market
Metals
Europe Metal Casting Market
Metals
Copper and Copper Alloy Foil Market
Metals
Iron Ore Market
Metals
Copper Clad Aluminum Wire Market
Metals
Nickel Powder Plating Market
Metals
Barium Market
Metals
Recycled Metal Market
Metals
Nickel Sulfate Market
Metals
Global Brazing Consumable Market