
 Global Brass Rods Market | 2026-2036
Global Brass Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brass Rods Market Foresight
Premium brass rod specifications is decoupling from commodity grades as alloy purity tolerances tighten and traceability requirements multiply. Wieland Group anchors its position through captive smelting and rolling capacity across European manufacturing clusters. Hailiang Group dominates volume production of standard and free-cutting grades for Asian fabrication networks. Mueller Industries specializes in precision-drawn hexagonal and custom profiles for North American plumbing and HVAC distributors.
Brass rods are extruded or drawn copper-zinc alloy bars, typically containing 60-70% copper with controlled lead or aluminum additions for machinability or corrosion resistance, serving as semifinished feedstock for machining, forging, and fitting fabrication. Free-cutting brass rods with controlled lead content occupy the highest machining throughput segments, while high-strength aluminum brass variants command premium positioning in marine and desalination hardware. Round rods in standard diameters represent the mature volume base, whereas custom profiles and hexagonal forms capture expanding margin pools in precision mechanical engineering and specialized electrical connectors.
REACH restrictions on lead content in finished goods and China's GB standards on heavy metal emissions from metal processing are reshaping alloy formulations and smelter compliance investments across major supply basins. The EU F-Gas Regulation and associated building efficiency codes indirectly stimulate brass rod demand through heat exchanger and valve replacement cycles in climate systems. Stakeholders must monitor the pace of lead substitution in free-cutting grades against machining performance benchmarks to calibrate R&D allocation and customer transition timelines.
Market Dynamics
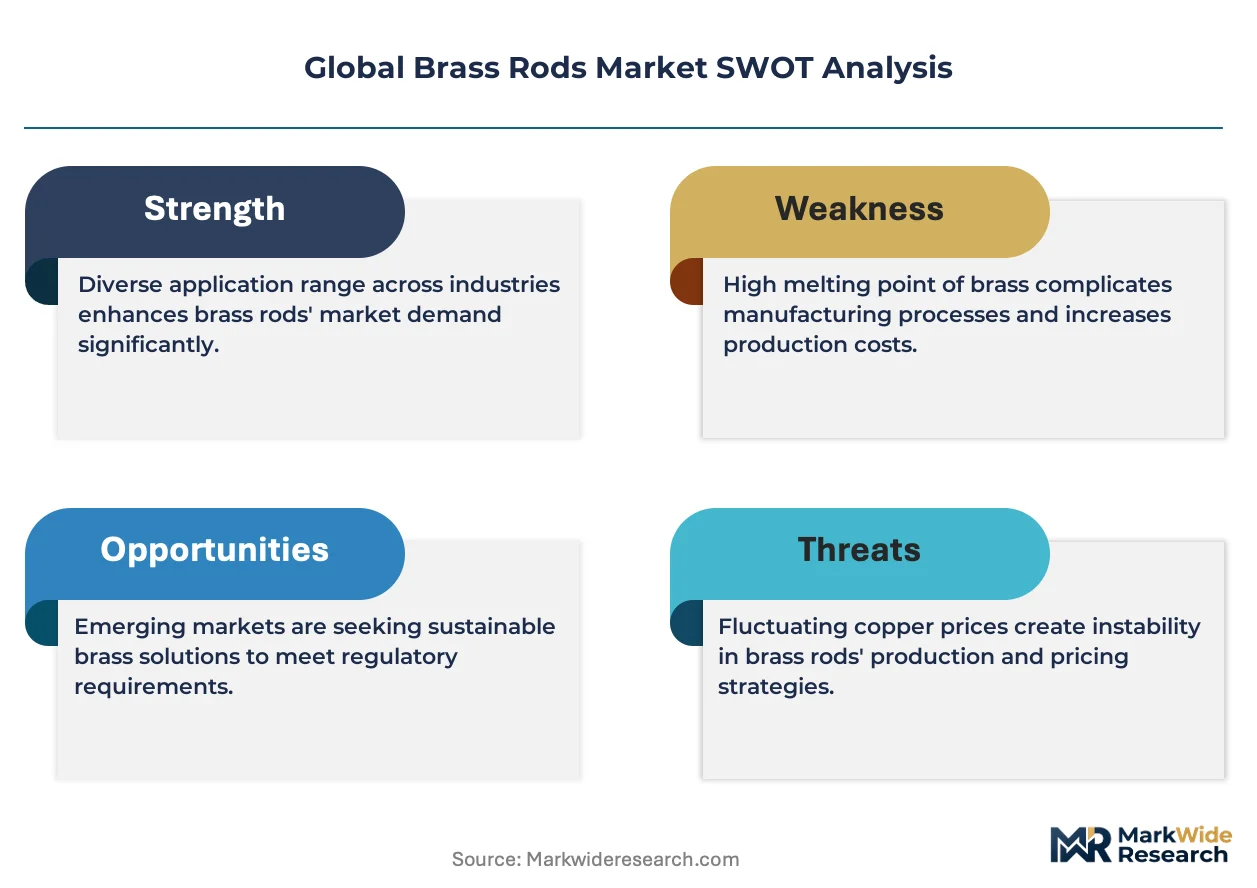
Lead-free alloy conversion is compressing margins across free-cutting brass grades while simultaneously opening premium positioning for compliant formulations in plumbing and medical device feedstock.
Growth Catalysts
- EU F-Gas Regulation:Heat exchanger replacement cycles in climate systems are accelerating brass rod consumption for valve and fitting fabrication across German and Italian HVAC supply chains.
- India:Domestic plumbing infrastructure expansion in Gujarat and Maharashtra industrial corridors is concentrating demand for standard diameter round rods in municipal water distribution networks.
- Aluminum brass variants:Desalination plant construction in the Middle East is pulling high-strength corrosion-resistant grades into marine hardware specifications.
Market Restraints
- Copper price volatility:LME copper futures swings above 8% monthly amplitude are destabilizing rod producer hedging strategies and contract pricing stability.
- Scrap supply concentration:Chinese smelters control 60% of global brass scrap processing capacity, creating chokepoint vulnerability for European and North American extrusion mills.
- REACH lead restrictions:ECHA substance evaluation timelines are extending certification cycles for legacy free-cutting grades by 18-24 months.
Strategic Opportunities
- Brazil:Underpenetrated precision mechanical engineering sector offers white space for custom hexagonal and square profile rods serving automotive component subcontractors.
- Indonesia:PLI scheme incentives for domestic manufacturing are creating localized demand for standard grade feedstock in electrical connector fabrication.
- ISO 6506 hardness testing:Convergence of mechanical testing standards with traceability requirements is enabling premium pricing for certified-batch rod shipments to aerospace distributors.
Industry Challenges
- Lead-free machinability:Bismuth and silicon substitution in free-cutting formulations requires retraining CNC programming specialists and retooling chip management systems.
- Dual certification timelines:Simultaneous GB standard compliance for China exports and REACH registration for EU access is stretching quality assurance departments across divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brass Rods Market |
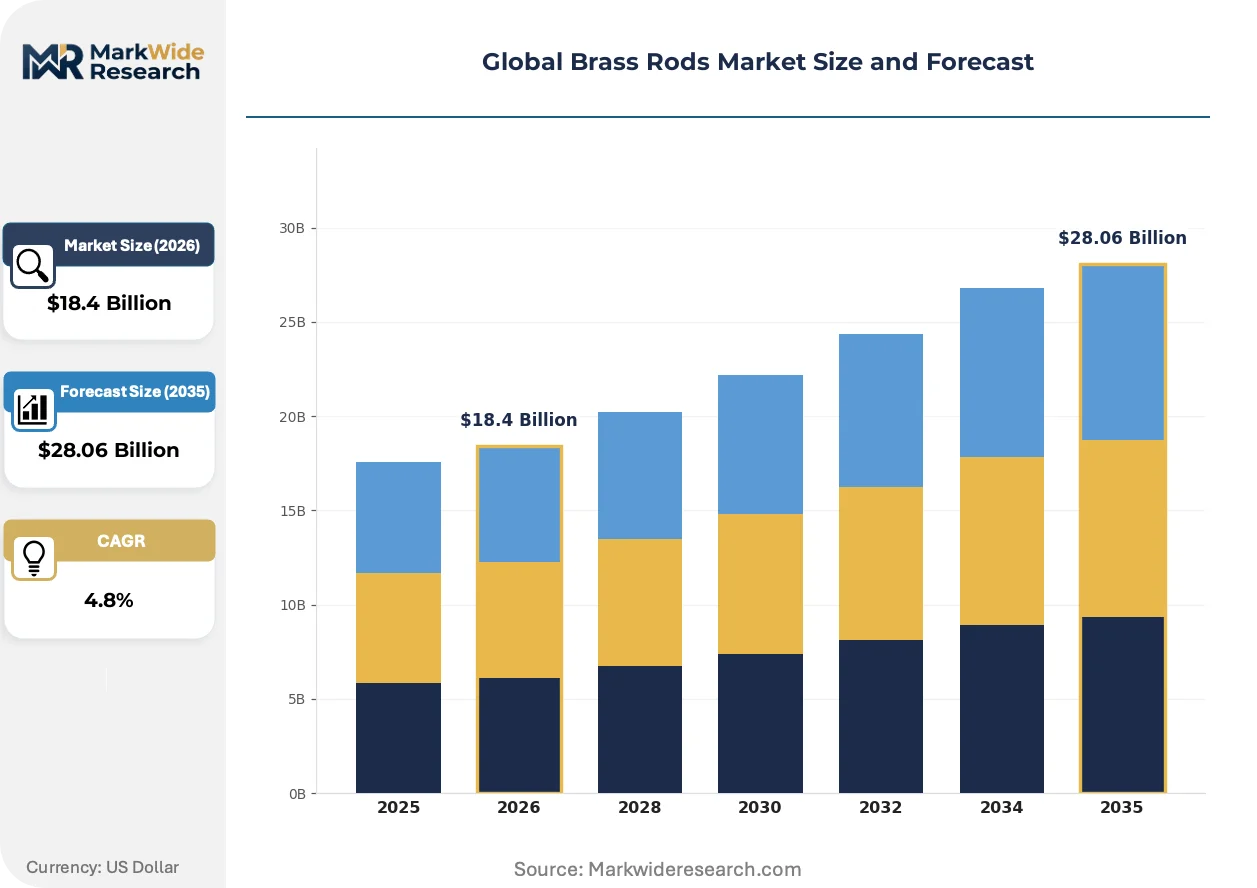
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Brass Rods, Free-Cutting Brass Rods, High Strength Brass Rods, Lead Brass Rods, Aluminum Brass Rods Application: Electrical Components, Plumbing Fixtures, Automotive Parts, Musical Instruments, Mechanical Engineering End User Industry: Construction Contractors, Electronics Manufacturers, Vehicle Assemblers, Instrument Makers, Machinery Fabricators Form: Round Rods, Square Rods, Hexagonal Rods, Flat Bars, Custom Profiles |
| Companies Covered | Tongling Nonferrous Metals Group, Hailiang Group, Wieland Group, Daechang, ALMAG SPA, KME Group, Mueller Industries, Chase Brass and Copper Company, Ningbo Jintian Copper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brass Rods Market Shifts & Advancements
Alloy formulation science and digital traceability systems are converging to separate compliant premium grades from commodity pricing tiers, with regulatory pressure as the primary accelerant.
Near-net-shape continuous casting is unifying melting and forming stages into single-process flow, reducing solidification cracking in high-zinc alloys. Japanese precision component manufacturers are adopting this for electrical connector rod feedstock at pilot scale. The technology is compressing capital requirements for mid-volume specialty producers while tightening dimensional tolerances previously achievable only through multi-stage drawing.
China's GB standards on heavy metal emissions from metal processing are forcing smelter retrofits and closed-loop wastewater systems across Shandong and Zhejiang manufacturing clusters. Rod producers serving export markets must dual-certify against both domestic discharge limits and customer-facing substance declarations. Small-scale extruders without captive environmental infrastructure are exiting or consolidating into larger integrated groups.
Consolidated distributor purchasing is displacing fragmented spot buying among North American plumbing and HVAC contractors. Large regional distributors now specify alloy certification, lot traceability, and just-in-time delivery as baseline requirements. This pattern is most visible in Texas and Florida construction corridors where project-scale procurement has concentrated buying power among three national distribution networks.
Global Brass Rods Market Segmentation
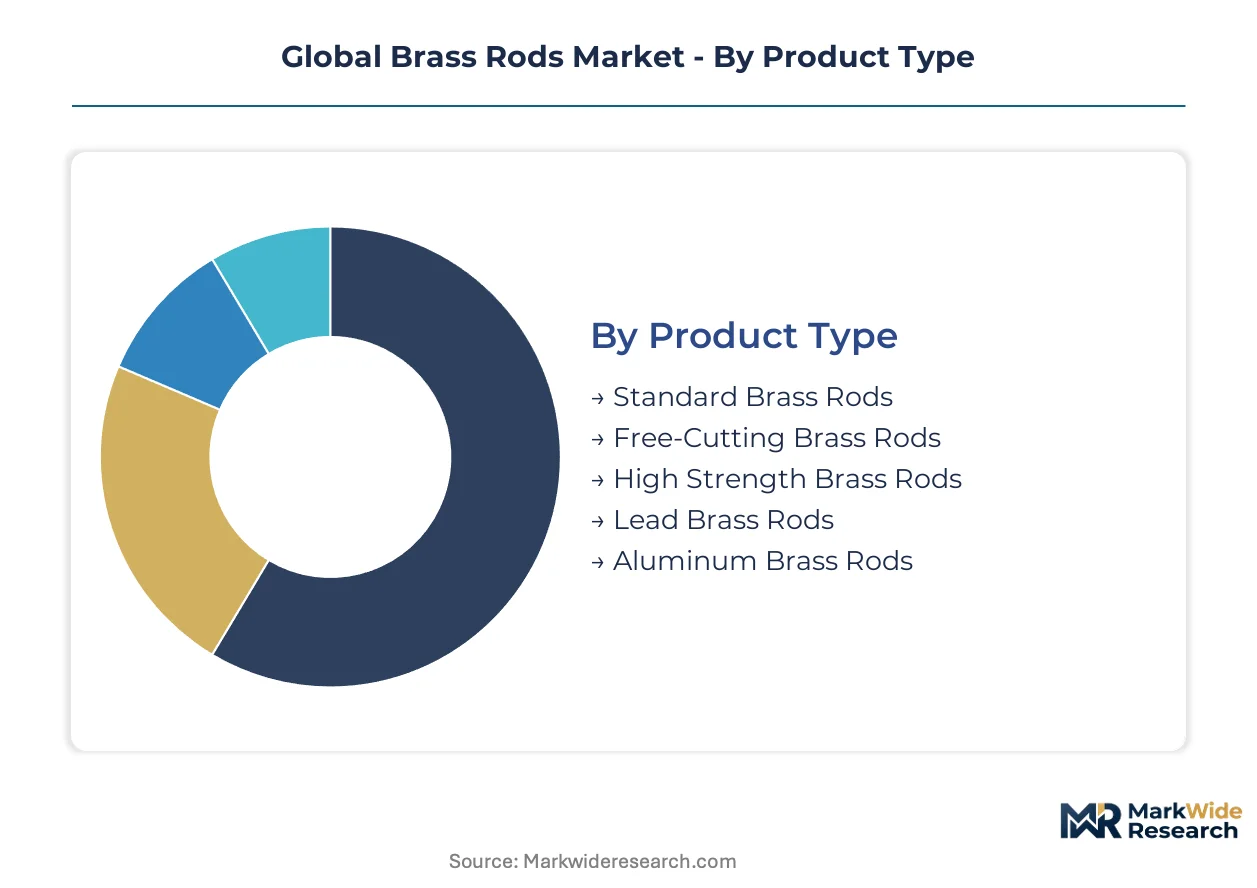
Brass rod producers face divergent technical requirements across end-use applications, forcing alloy formulation and dimensional precision to align with specific customer specifications rather than universal standards. Segmentation reveals where margin pools concentrate and where volume commoditization pressures dominate.
Product Type:
Customization intensity varies from commodity-grade formulations to precision-engineered alloys with traceability documentation.
- Free-Cutting Brass Rods:Lead or bismuth additions enhance machinability for high-speed CNC operations. Demand concentrates in German and Italian precision component shops facing REACH substance evaluation timelines. Machining throughput requirements sustain premium positioning despite regulatory compliance costs.
- High Strength Brass Rods:Aluminum and manganese alloying elevates tensile properties for load-bearing applications. Vehicle assemblers in Stuttgart and Detroit are expanding intake for transmission shafts and fuel system hardware as powertrain specifications tighten.
- Standard Brass Rods:Conventional copper-zinc compositions serve general fabrication networks across Indian municipal plumbing contractors.
- Lead Brass Rods:Legacy free-cutting formulations face contracting demand as China's GB standards and EU REACH restrictions accelerate phase-out timelines.
- Aluminum Brass Rods:Corrosion-resistant variants command marine hardware specifications in Middle Eastern desalination plant construction.
Most installed capacity flows through Standard Brass Rods. Expansion is steepest in High Strength Brass Rods.
Application:
End-use performance requirements determine alloy certification depth and lot traceability obligations.
- Automotive Parts:Precision-drawn feedstock for fuel injectors, transmission valves, and sensor housings. Stuttgart-based tier-one suppliers specify hardness testing to ISO 6506 standards with full metallurgical documentation.
- Plumbing Fixtures:Lead-free formulations dominate municipal water distribution specifications in Gujarat and Maharashtra industrial corridors. India's domestic infrastructure scaling concentrates demand for certified potable-grade feedstock.
- Electrical Components:Conductivity-optimized alloys serve connector fabrication for Japanese precision electronics manufacturers.
- Mechanical Engineering:Custom profile rods support precision machinery builders in Brazil's underpenetrated component subcontractor base.
- Musical Instruments:Acoustic property requirements sustain niche demand for specific copper-zinc ratios in artisanal fabrication.
Volume concentration sits with Plumbing Fixtures. Margin expansion is most pronounced in Automotive Parts.
End User Industry:
Procurement sophistication separates specification-driven buyers from price-sensitive spot purchasers.
- Vehicle Assemblers:Long-term supply agreements with alloy certification and just-in-time delivery requirements. Detroit and Stuttgart OEMs mandate environmental compliance documentation alongside mechanical property guarantees.
- Construction Contractors:Project-scale procurement concentrates buying power among national distribution networks in Texas and Florida. Distributors now specify lot traceability as baseline for municipal plumbing contracts.
- Electronics Manufacturers:Japanese precision component producers pilot near-net-shape continuous casting for connector feedstock.
- Machinery Fabricators:Brazilian mechanical engineering subcontractors represent white space for custom hexagonal and square profile adoption.
- Instrument Makers:Small-batch artisanal demand sustains specialty alloy production with acoustic property specifications.
Contract volume aggregates with Construction Contractors. Technical specification intensity peaks with Vehicle Assemblers.
Form:
Dimensional complexity correlates with margin tier and customer switching costs.
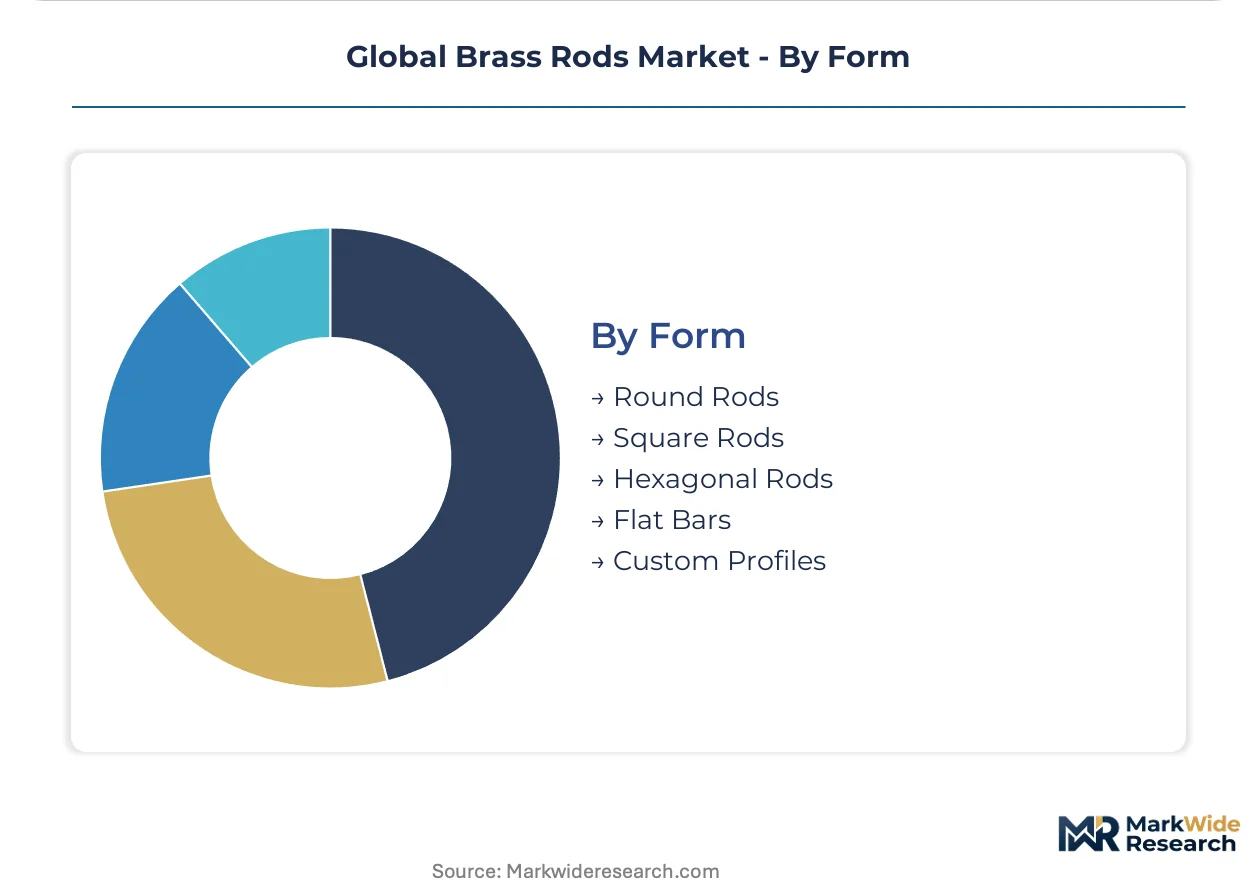
- Round Rods:Standard diameter extrusions represent the mature volume base across global fabrication networks. Indian plumbing infrastructure scaling and Indonesian electrical connector fabrication pull commodity-grade throughput.
- Custom Profiles:Application-specific cross-sections capture expanding margin pools in precision mechanical engineering. Near-net-shape continuous casting compresses capital requirements for mid-volume specialty producers.
- Hexagonal Rods:Precision-drawn six-sided feedstock serves North American HVAC valve and fitting distributors.
- Square Rods:Structural applications in machinery frames and architectural hardware.
- Flat Bars:Plate-form feedstock for stamping and machining operations in general fabrication.
Production throughput concentrates in Round Rods. Value capture is climbing fastest in Custom Profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgical workforces in Germany's precision engineering clusters and China's Yangtze River Delta anchor brass rod fabrication capacity. Tool-and-die specialists in Stuttgart and Ningbo sustain high-throughput extrusion and drawing operations. Regulatory divergence between REACH substance evaluations and GB standards on heavy metal emissions is fragmenting alloy certification requirements across supply basins.
China
Vehicle assemblers in Shanghai and Guangzhou are expanding intake of high-strength brass rods for fuel system components. GB standards on lead content in copper alloys are pushing manufacturers toward lead-free formulations across Shandong and Zhejiang manufacturing clusters. Ningbo Jintian Copper and Tongling Nonferrous Metals Group operate integrated smelting capacity serving domestic and export fabrication networks.
Germany
Stuttgart-based tier-one automotive suppliers specify ISO 6506 hardness testing with full metallurgical documentation for transmission valve feedstock. ECHA substance evaluation timelines are extending certification cycles for legacy free-cutting grades by 18-24 months. Wieland Group anchors captive smelting and rolling operations across European manufacturing clusters.
India
Domestic plumbing infrastructure scaling in Gujarat and Maharashtra industrial corridors is concentrating demand for standard diameter round rods. BIS certification requirements for potable water contact materials are tightening alloy purity tolerances. Municipal water distribution contractors in Ahmedabad and Mumbai are consolidating procurement through project-scale agreements.
United States
Heat exchanger replacement cycles under EPA F-Gas compliance are accelerating brass rod consumption for HVAC valve fabrication. Consolidated distributor purchasing among Texas and Florida construction corridors is displacing fragmented spot buying. Mueller Industries and Chase Brass and Copper Company occupy positions in precision-drawn feedstock for North American plumbing and climate system distributors.
Italy
German and Italian precision component shops facing REACH substance evaluation timelines sustain premium positioning for free-cutting brass grades. EU F-Gas Regulation indirectly stimulates demand through building efficiency codes driving heat exchanger replacement. ALMAG SPA exemplifies European fabrication specialists navigating dual certification requirements for alloy formulations.
Global Brass Rods Market Competitive Landscape
Top-tier vendors anchor integrated smelting-to-extrusion operations, while mid-scale specialists concentrate on precision-drawn custom profiles. The vendor base stratifies across three archetypes: captive smelters with backward integration into mining and refining, precision fabricators with specialized drawing and heat-treatment capabilities, and volume extruders serving commodity-grade fabrication networks. Dominant competitive moves include capacity consolidation through asset acquisitions and geographic expansion via distributor partnerships in underpenetrated precision mechanical engineering sectors.
Among Chinese integrated producers, Tongling Nonferrous Metals Group and Hailiang Group occupy positions exemplifying volume-scale smelting and extrusion capacity. Wieland Group represents the European captive-smelter archetype with rolling operations across manufacturing clusters. These three companies anchor divergent competitive vectors: scale-driven throughput in Asian fabrication networks versus premium-grade certification depth in European automotive supply chains.
| Leading Market Players |
|---|
| Tongling Nonferrous Metals Group |
| Hailiang Group |
| Wieland Group |
| Daechang |
| ALMAG SPA |
| KME Group |
| Mueller Industries |
| Chase Brass and Copper Company |
| Ningbo Jintian Copper |
| Others |
Supply & Pricing Matrix
Consolidated distributor purchasing among Texas and Florida construction corridors is forcing rod producers to bundle alloy certification and lot traceability with just-in-time delivery, compressing margins on unbundled spot transactions while rewarding integrated service providers with contract stability.
Pricing Analysis
Contract-based long-term offtake dominates automotive and HVAC supply chains, while spot pricing persists in fragmented plumbing contractor procurement. Price differentiation rests on REACH-compliant certification tiers and volume scale, with German tier-one suppliers paying premiums for ISO 6506 hardness documentation. Cost compression in free-cutting grades is intensifying because bismuth and silicon substitution raises raw material input costs. Small-scale extruders serving Indian municipal contractors exhibit highest price sensitivity; Stuttgart-based vehicle assemblers demonstrate lowest sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Regional distribution centers in Houston and Miami anchor hub-and-spoke patterns serving North American HVAC and plumbing networks. Supply concentrates in China, Germany, and India, with Chinese smelters controlling the majority of global brass scrap processing capacity. Raw material flows draw from copper concentrate imports, zinc alloy additions, and recycled scrap feedstock. Single-source vulnerability concentrates in Chinese scrap processing chokepoints. Distribution runs through national distributor networks consolidating project-scale procurement in construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Brass Rods Market functions as a stable compounder, with infrastructure replacement cycles and regulatory-mandated alloy reformulations providing steady demand visibility across automotive, plumbing, and climate system applications.
For Market Incumbents: Hedge against scrap supply concentration by securing captive recycling capacity or long-term offtake agreements with independent scrap processors. Expand lead-free formulation R&D to defend margin position as ECHA substance evaluation timelines extend certification cycles for legacy grades. For New Entrants and Emerging Players: Begin with Brazil's underpenetrated precision mechanical engineering sector, where custom hexagonal and square profile demand outpaces domestic supply capability. Partner with regional distributors in Texas and Florida to bypass entrenched national network relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale precision fabricators possessing specialized drawing capabilities and dual-certification infrastructure for both GB standards and REACH compliance. Watch the pace of lead substitution in free-cutting grades against machining performance benchmarks as the inflection indicator for R&D allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Processing | Captive recycling capacity insulates margins from Chinese smelter chokepoint vulnerability. |
| Lead-Free Alloy Certification Investment | ECHA registration acceleration opens premium positioning in EU plumbing and medical device feedstock. |
| Near-Net-Shape Continuous Casting Adoption | Japanese precision electronics manufacturers pilot this technology for connector feedstock dimensional tolerance gains. |
| Regional Distribution Partnership Expansion | Texas and Florida construction corridors concentrate buying power among three national distribution networks. |
| Dual-Certification Quality Assurance Buildout | Simultaneous GB standard and REACH compliance stretches documentation capabilities across divergent requirements. |
Research Methodology
Multiple input streams — extrusion plant managers, procurement leads at German automotive tier-one suppliers, North American HVAC distributor category buyers, and technical R&D directors at alloy formulation labs — were reconciled against customs and trade data, SEC filings from publicly traded producers, and ECHA substance evaluation databases. Bottom-up volume estimates from fabrication network throughput were triangulated with top-down demand projections from end-use industry consumption patterns.
Data-stream reconciliation across the projection horizon modeled alloy grade tier, end-use industry application, form complexity, and regional production hub segmentation. CAGRs were derived from trend extrapolation of vehicle assembler intake rates, infrastructure scaling timelines, and regulatory phase-out schedules. Forecast inputs included LME copper futures volatility patterns and desalination plant construction pipelines in the Middle East.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration of lead content restrictions, abrupt copper price dislocation events, and trade policy interventions affecting scrap flow patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High-End Copper Foil Market
Metals
North America Metal Finishing Market
Metals
High Purity Aluminium Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
North America Iron Casting Market
Metals
US Copper Scrap Market
Metals
Steel Drums Market
Metals
Nickel Powder Plating Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Global Vanadium Market
Metals
High Purity Lead Market
Metals
Barium Market
Metals
North America Aluminum Casting Market
Metals
Ferrosilicon Market
Metals
Steel Sheet for Home Appliances Market
Metals
Beryllium Copper for Telecommunication Market