
 Global Immersion Oil Market | 2026-2036
Global Immersion Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immersion Oil Market Foresight
Subscription-based reagent replenishment programs is pivoting how laboratories manage immersion oil inventory, shifting capital expenditure into operational budgets. Cargille-Sacher Laboratories leverages its century-old formulation archives to sustain premium positioning in synthetic oil grades. Thermo Fisher Scientific anchors North American distribution through integrated life sciences supply contracts. Nikon Corporation competes by bundling oil specifications with microscope warranty terms, tightening vendor lock-in.
Immersion oil is a high-refractive-index liquid, typically formulated from synthetic hydrocarbons or refined natural oils with refractive indices near 1.515, designed to eliminate light refraction at the glass-specimen interface during high-magnification microscopy. Its primary purpose is to maximize numerical aperture and resolution in oil-immersion objectives used for cellular pathology, semiconductor defect inspection, and materials science. Synthetic oil commands the largest revenue share due to thermal stability and low autofluorescence, while blended oil represents the fastest-expanding category as manufacturers balance performance with cost in educational settings. Laboratory research applications generate the densest margin pools, though educational institutions drive the highest unit volumes through standardized microscope kits.
FDA optical device regulations and EPA chemical substance reporting requirements in the United States, alongside REACH registration mandates administered by ECHA in the European Union, are elevating documentation burdens and reformulation costs for immersion oil producers. ISO 8036 standards for immersion liquids are gaining traction as procurement specifications in contract research organizations. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate formulation portfolios accordingly.
Market Dynamics
REACH registration mandates administered by ECHA are forcing reformulation cycles that compress product lifecycles and elevate R&D burn rates for immersion oil manufacturers serving European laboratories.
Growth Catalysts
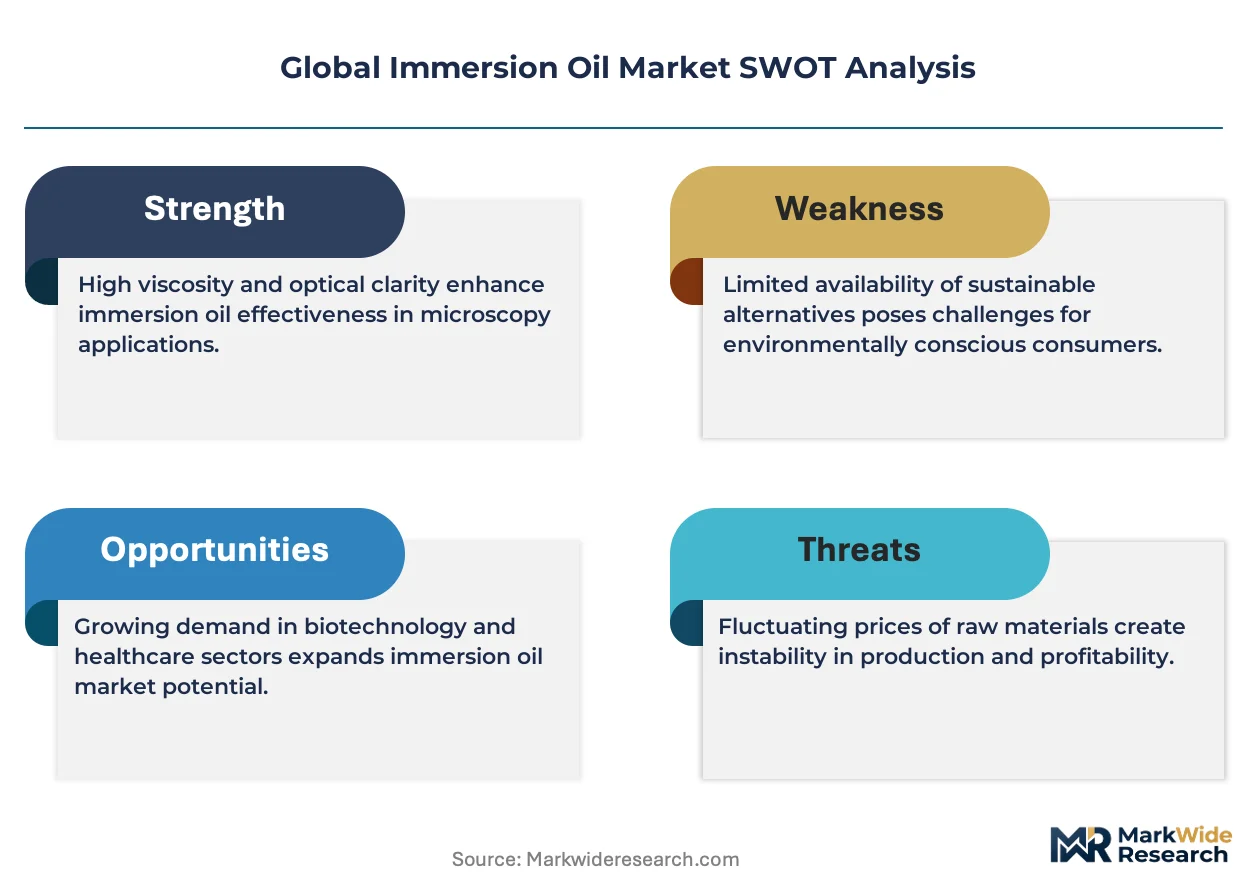
- Fluorescence microscopy advancement:Life sciences laboratories in Germany and the United States are expanding synthetic oil procurement as confocal and super-resolution protocols demand lower autofluorescence substrates.
- ISO 8036 standardization:Contract research organizations are embedding this immersion liquid specification into procurement contracts, creating quality-tier segmentation that rewards certified suppliers.
- Semiconductor defect inspection:Wafer fabrication facilities in Japan are driving high-viscosity synthetic oil volumes as node shrinkage below 7nm demands sub-diffraction-limit optical resolution.
Market Restraints
- Refined natural oil feedstock volatility:Purified cedarwood oil prices fluctuate with forestry harvest cycles in North America, compressing margin stability for blended formulation producers.
- German optics cluster concentration:Precision microscope objective manufacturing concentrates in Baden-Württemberg and Bavaria, creating single-region demand dependency for premium synthetic grades.
- Autofluorescence floor:Even synthetic hydrocarbons exhibit residual fluorescence under 405nm excitation, limiting applicability in advanced live-cell imaging protocols.
Strategic Opportunities
- Indian diagnostic laboratory expansion:Pathology chains in Mumbai and Bangalore are upgrading from dry to oil-immersion objectives, creating first-time buyer segments for mid-tier synthetic products.
- Subscription replenishment models:North American academic consortia are piloting reagent-as-a-service contracts that convert capital equipment purchases into recurring revenue streams for oil suppliers.
- EU Green Deal chemical substitution:Bio-based immersion oil precursors derived from algae lipids qualify for sustainable procurement preferences in ECHA-registered formulations.
Industry Challenges
- Refractive index calibration expertise:Formulation chemists capable of tuning oils to 1.5150 ± 0.0002 precision are concentrated at legacy optics firms, constraining new entrant scale-up.
- Legacy microscope compatibility:Decades-old equipment in educational institutions requires viscosity-matched oils that differ from modern synthetic standards, fragmenting SKU requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immersion Oil Market |
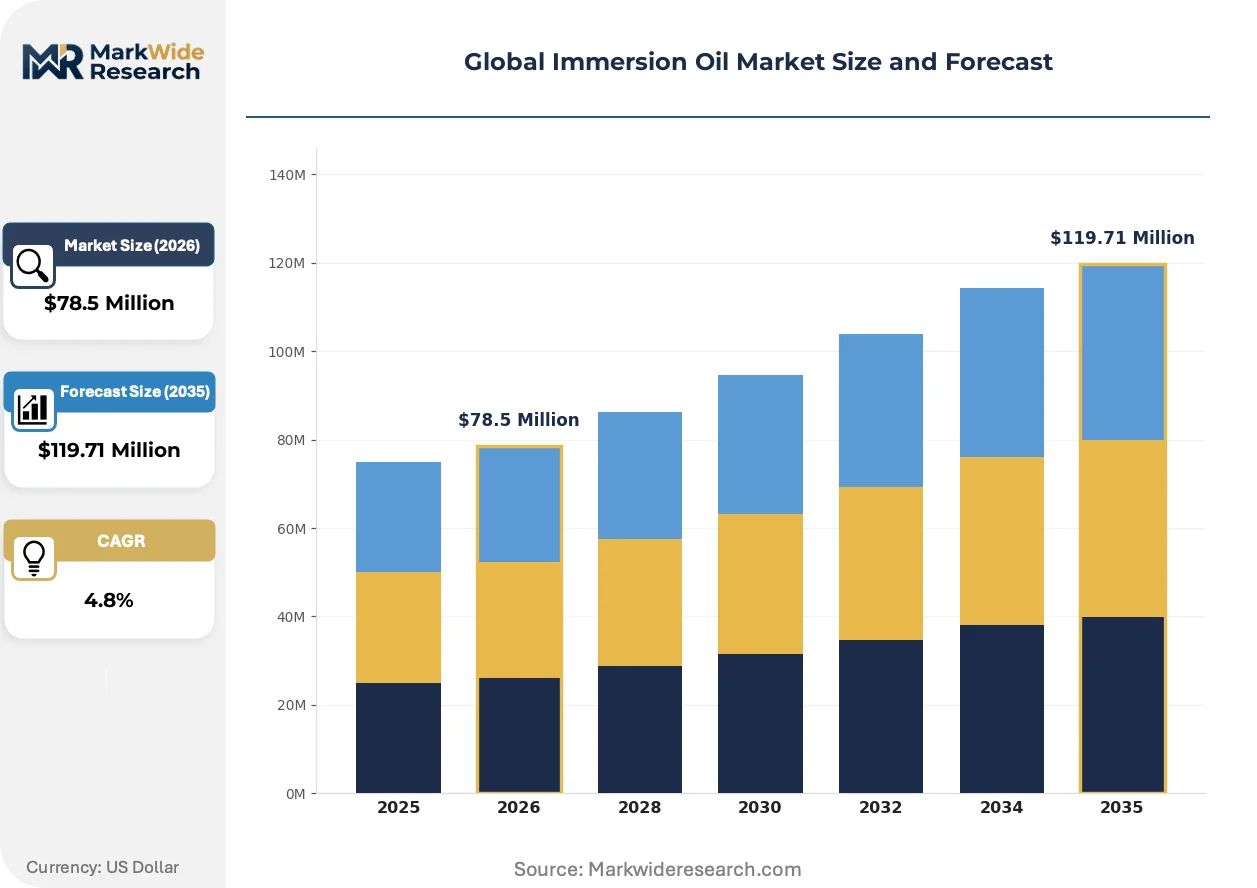
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $119.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Natural Oil, Mineral Oil, Blended Oil Application: Microscopy, Laboratory Research, Industrial Usage, Educational Purposes End User: Laboratories, Educational Institutions, Pharmaceutical Companies, Research Organizations Packaging Type: Glass Bottles, Plastic Bottles, Bulk Containers, Sachets |
| Companies Covered | Cargille-Sacher Laboratories Inc., Honeywell International Inc., Flinn Scientific, Leica Microsystems, Nikon Corporation, Olympus Corporation, Merck KGaA, Thermo Fisher Scientific Inc., Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immersion Oil Market Shifts & Advancements
Immersion oil chemistry is converging with semiconductor metrology demands and sustainable procurement mandates, compressing the gap between optical performance specifications and environmental compliance requirements.
Silica nanoparticle-doped synthetic formulations are absorbing thermal expansion stresses that previously caused focal drift during extended time-lapse microscopy. Pharmaceutical screening facilities in Basel and Boston are adopting these thermally stabilized grades for high-content imaging workflows. The technology is absorbing volume from conventional hydrocarbon oils in applications exceeding 12-hour continuous acquisition protocols.
ECHA's 2023 update to REACH Annex XVII restricted substance lists is compelling reformulation of halogenated viscosity modifiers used in high-temperature immersion oils. German and French manufacturers are accelerating substitution timelines to avoid authorization bottlenecks. Semiconductor inspection applications face the tightest compliance windows due to their reliance on specialized high-thermal-stability grades.
Academic purchasing consortia are consolidating microscope oil procurement through centralized e-procurement platforms that bypass traditional distributor markups. The University of California system and Max Planck Society have established direct manufacturer contracts. This channel compression is most advanced in North American and German research institutions with standardized equipment fleets exceeding 500 oil-immersion objectives.
Global Immersion Oil Market Segmentation
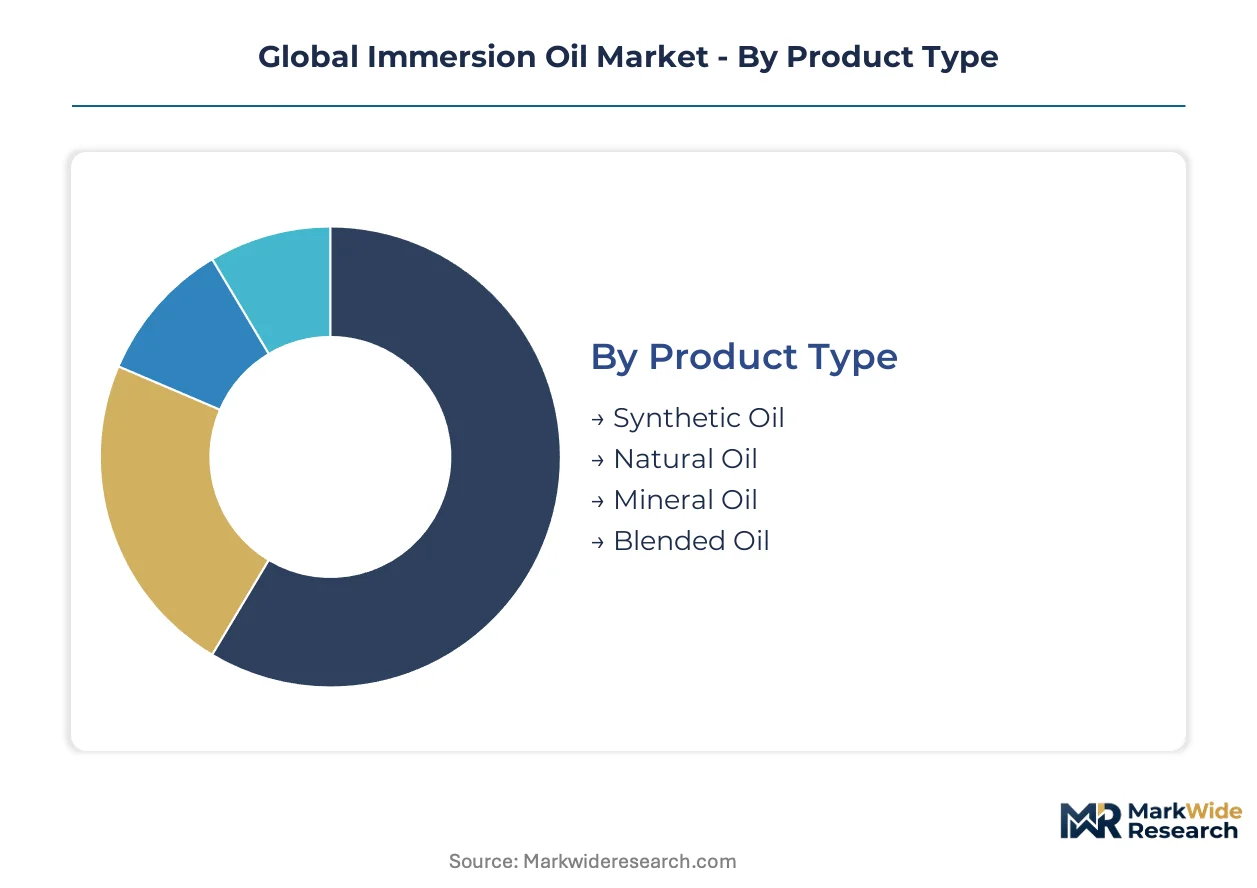
Immersion oil procurement patterns diverge sharply across product chemistry, use case, and institutional buyer type. Capital allocation, regulatory exposure, and supply chain configuration all pivot on which segmentation lens procurement teams apply.
Product Type:
Synthetic formulations demand the heaviest upfront R&D investment due to precision refractive index calibration and thermal stability engineering.
- Synthetic Oil:Formulated from refined hydrocarbon polymers with refractive indices tuned to 1.5150 ± 0.0002 precision. Demand concentrates in German and Japanese semiconductor inspection facilities where node shrinkage below 7nm requires sub-diffraction-limit resolution and minimal thermal drift during extended acquisition protocols.
- Blended Oil:Combines synthetic base stocks with purified natural oil fractions to balance performance against unit economics. Educational consortia in the United States are expanding procurement of mid-tier blended grades as capital budgets tighten and microscope fleet standardization programs advance.
- Natural Oil:Historically derived from cedarwood and sandalwood distillates with inherent autofluorescence limitations. Forestry harvest volatility in North American supply basins constrains formulation consistency.
- Mineral Oil:Refined petroleum distillates serving cost-sensitive educational markets. Viscosity instability limits adoption in precision research applications.
Most installed capacity flows through Synthetic Oil. Expansion is steepest in Blended Oil.
Application:
Laboratory protocols impose the most stringent purity specifications, creating margin tiering that separates research-grade from instructional applications.
- Microscopy:Cellular pathology workflows in Basel and Boston pharmaceutical screening facilities require low-autofluorescence substrates compatible with 405nm excitation. ISO 8036 certification is becoming a mandatory procurement filter.
- Laboratory Research:Confocal and super-resolution imaging in German life sciences institutes drives specification creep toward thermally stabilized nanoparticle-doped formulations.
- Industrial Usage:Semiconductor wafer fabrication in Japan consumes high-viscosity synthetic grades for defect inspection at sub-10nm process nodes.
- Educational Purposes:Standardized microscope kits for undergraduate biology programs prioritize cost containment over optical performance, favoring mineral and blended oil categories.
Revenue density peaks in Laboratory Research. Volume leadership sits with Educational Purposes.
End User:
Pharmaceutical companies carry the highest compliance burden, with FDA oversight of optical device adjuncts and EPA chemical substance reporting requirements elevating documentation costs.
- Pharmaceutical Companies:High-content imaging facilities in Basel and Boston require REACH-compliant synthetic grades with batch-level traceability for GMP-adjacent workflows.
- Research Organizations:Max Planck Society and University of California system consortia are consolidating procurement through direct manufacturer contracts, bypassing traditional distributor markups.
- Laboratories:Diagnostic chains in Mumbai and Bangalore are upgrading from dry to oil-immersion objectives, creating first-time buyer segments for mid-tier synthetic products.
- Educational Institutions:Legacy equipment compatibility requirements fragment SKU needs, as decades-old microscopes demand viscosity-matched oils that differ from modern synthetic standards.
Contract value concentrates with Pharmaceutical Companies. Unit velocity is highest in Educational Institutions.
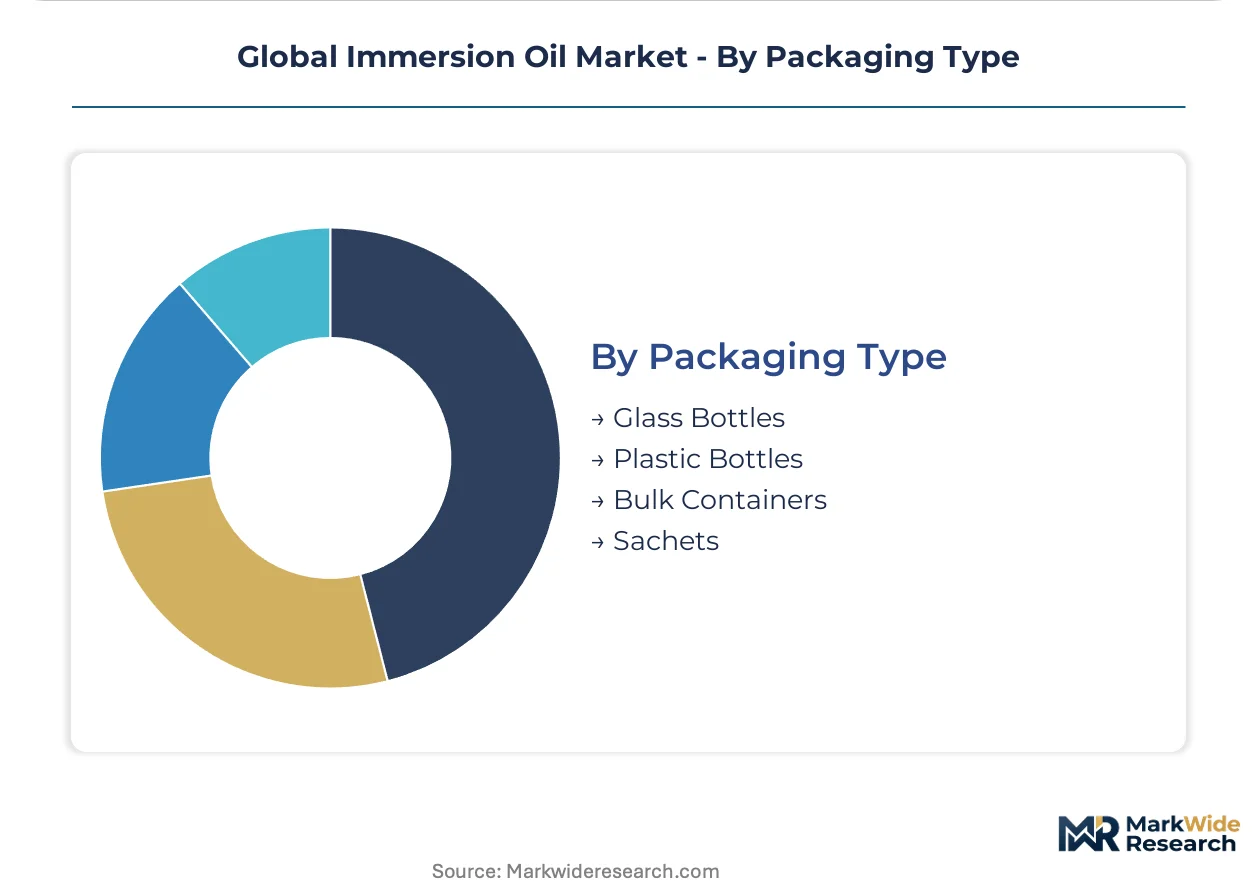
Packaging Type:
Bulk container infrastructure locks in the largest capital commitments, with specialized filling and contamination-control systems requiring dedicated production lines.
- Bulk Containers:Industrial-scale semiconductor fabrication facilities in Japan and pharmaceutical screening centers in Germany procure multi-liter volumes through scheduled replenishment contracts.
- Glass Bottles:Premium synthetic grades for research applications require amber glass with inert sealing to prevent oxidative degradation and maintain refractive index stability.
- Plastic Bottles:Polypropylene containers serve cost-optimized educational and routine diagnostic segments where shelf-life requirements are less stringent.
- Sachets:Single-use foil pouches eliminate cross-contamination risks in clinical pathology workflows and field microscopy deployments.
Shipment value aggregates in Bulk Containers. Packaging innovation is most active in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States sustain parallel but structurally distinct demand profiles for immersion oil, with precision optics manufacturing clustering in Baden-Württemberg and semiconductor metrology protocols driving procurement in Arizona and Massachusetts.
United States
FDA optical device regulations and EPA chemical substance reporting requirements elevate documentation burdens for immersion oil producers supplying pharmaceutical screening facilities in Boston and San Diego. REACH-equivalent state-level chemical disclosure laws in California are compressing formulation flexibility. The University of California system anchors direct manufacturer contracting models that bypass traditional distributor markups.
Germany
Precision microscope objective manufacturing concentrates in Baden-Württemberg and Bavaria, creating single-region demand dependency for premium synthetic grades. ECHA-administered REACH registration mandates are forcing reformulation cycles that compress product lifecycles. Max Planck Society consortia are consolidating procurement through centralized e-procurement platforms.
Japan
Wafer fabrication facilities in Tokyo and Osaka are driving high-viscosity synthetic oil volumes as node shrinkage below 7nm demands sub-diffraction-limit optical resolution. METI industrial standards for optical materials are tightening purity specifications for semiconductor inspection applications. Nikon Corporation bundles oil specifications with microscope warranty terms, tightening vendor lock-in across domestic research institutes.
India
Diagnostic laboratory chains in Mumbai and Bangalore are upgrading from dry to oil-immersion objectives, creating first-time buyer segments for mid-tier synthetic products. CDSCO medical device regulations are elevating traceability requirements for clinical pathology workflows. BIS standards adoption is accelerating in institutional procurement specifications for research-grade microscopy.
Switzerland
Pharmaceutical screening facilities in Basel require REACH-compliant synthetic grades with batch-level traceability for GMP-adjacent workflows. Swissmedic oversight of optical device adjuncts elevates compliance costs relative to neighboring EU markets. Precision optics research clusters in Zurich and Geneva sustain demand for thermally stabilized nanoparticle-doped formulations.
Global Immersion Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with century-old formulation archives commanding premium positioning in synthetic oil grades while integrated life sciences distributors anchor volume through supply contracts. The market structure tiers across precision refractive index calibration expertise, regulatory compliance depth, and microscope OEM bundling relationships. Three archetypes dominate: legacy optics specialists with proprietary formulation libraries, diversified chemicals conglomerates with REACH-registered portfolios, and microscope OEMs leveraging warranty lock-in. Competitive moves concentrate on direct manufacturer contracting with academic consortia and substitution of halogenated viscosity modifiers ahead of ECHA authorization deadlines.
Within the legacy specialist tier, Cargille-Sacher Laboratories Inc. exemplifies premium positioning sustained through century-old formulation archives. Thermo Fisher Scientific Inc. occupies the diversified distribution archetype, anchoring North American volume through integrated life sciences supply contracts. Nikon Corporation represents the OEM bundling strategy, tightening vendor lock-in by embedding oil specifications within microscope warranty terms.
| Leading Market Players |
|---|
| Cargille-Sacher Laboratories Inc. |
| Honeywell International Inc. |
| Flinn Scientific |
| Leica Microsystems |
| Nikon Corporation |
| Olympus Corporation |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Idemitsu Kosan Co., Ltd. |
| Others |
Supply & Pricing Matrix
Formulation chemists capable of precision refractive index calibration concentrate in Baden-Württemberg and Bavaria, creating labor-cost differentials that widen pricing-tier spreads between German-manufactured synthetic grades and volume-oriented blended alternatives from North American contract producers.
Pricing Analysis
Capacity additions in India are reshaping price floors for mid-tier synthetic grades as diagnostic laboratory chains in Mumbai and Bangalore expand first-time procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 8036 certification status and thermal stability specifications. Cost compression in educational mineral oil segments is intensifying because of procurement consolidation through academic consortia. Educational institutions exhibit highest price sensitivity; semiconductor fabrication facilities in Japan show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Japanese wafer fabrication facilities and German pharmaceutical screening centers, bypassing distributor markups. Manufacturing concentrates in Germany, the United States, and Japan. Feedstock supply draws from refined hydrocarbon polymer streams, purified cedarwood distillates, and emerging algae lipid precursors. Single-source vulnerability persists in halogenated viscosity modifier supply ahead of ECHA authorization deadlines. Distribution runs through academic consortia platforms, life sciences distributors, and microscope OEM bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with ECHA's 2023 REACH Annex XVII update forcing reformulation cycles that compress product lifecycles and elevate R&D burn rates.
For Market Incumbents: To counter vendor lock-in by microscope OEMs bundling oil specifications with warranty terms, legacy formulation specialists should deepen direct manufacturer contracting with Max Planck Society and University of California system consortia while accelerating halogenated viscosity modifier substitution ahead of ECHA authorization bottlenecks.
For New Entrants and Emerging Players: Silica nanoparticle-doped thermal stabilization technology offers entry into pharmaceutical screening workflows exceeding 12-hour continuous acquisition protocols. White-space targets include Indian diagnostic laboratory chains upgrading from dry to oil-immersion objectives and EU Green Deal-compliant bio-based precursor formulations. Go-to-market positioning should emphasize REACH-registered sustainable procurement preferences.
For Investors and Strategic Acquirers: Diversified life sciences distributors are the most active acquirer in this space, seeking formulation archives and REACH-registered portfolios to anchor integrated supply contracts. Long-term viability hinges on regulatory compliance depth rather than commodity volume scale. Watch for ECHA authorization timeline announcements as inflection indicators for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Manufacturer Contracting | University of California and Max Planck Society consortia bypass distributor markups through centralized e-procurement platforms. |
| Halogenated Viscosity Modifier Substitution | German and French manufacturers accelerate reformulation to avoid ECHA authorization bottlenecks in semiconductor inspection grades. |
| Nanoparticle-Doped Thermal Stabilization | Basel and Boston pharmaceutical screening facilities adopt extended-acquisition protocols displacing conventional hydrocarbon oils. |
| Bio-Based Precursor Development | Algae lipid-derived formulations qualify for EU Green Deal sustainable procurement preferences in ECHA-registered products. |
| Subscription Replenishment Models | North American academic consortia pilot reagent-as-a-service contracts converting capital equipment purchases into recurring revenue. |
Research Methodology
Multiple input streams — formulation chemist interviews, procurement manager surveys, and regulatory filing analysis — were reconciled against trade flow databases and patent landscape mapping. Primary engagement encompassed optical device R&D directors, life sciences procurement leads at pharmaceutical screening facilities, academic laboratory managers, and REACH compliance officers at ECHA-registered manufacturers. Secondary validation drew from FDA optical device guidance documents, ECHA restricted substance list updates, ISO 8036 standard revisions, and SEC filings from diversified chemicals conglomerates. Bottom-up volume modeling and top-down market sizing were cross-checked for triangulation integrity.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation modeling across product chemistry tiers, application intensity levels, end-user compliance burdens, and regional regulatory clusters. CAGRs were derived from slope analysis of annualized volume trajectories, stress-tested against semiconductor node shrinkage timelines and fluorescence microscopy protocol advancement curves. Forecast inputs incorporated refractive index calibration expertise scarcity, legacy microscope fleet viscosity requirements, and academic consortia procurement consolidation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timeline shifts, cedarwood harvest cycle volatility, and nanoparticle-doped formulation adoption rates in extended-acquisition pharmaceutical workflows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Organosilicon Electrolyte Market