
 Galvanized Iron Pipes Market | 2026-2036
Galvanized Iron Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanized Iron Pipes Market Insights
The EU Green Deal's embodied-carbon disclosure requirements for construction materials is realigning specification sheets across European public works tenders. GF Piping Systems leverages its thermoplastic-hybrid expertise to compete in low-carbon retrofit segments. Valmont Tubing anchors North American agricultural irrigation demand through controlled distribution networks. Seah Steel dominates Korean shipyard and offshore scaffolding offtake with specialized corrosion-resistant grades.
Galvanized iron pipes are zinc-coated steel tubes produced through hot-dip or electro-galvanization processes, typically carrying 40-600 grams per square meter of zinc coating weight to resist atmospheric and soil corrosion in pressurized fluid conveyance and structural support systems. Round pipes lead volume in water supply and gas distribution backbone networks where hoop stress tolerance governs specification, while corrugated pipes represent the fastest-growing product configuration for culvert and drainage applications where flexural adaptability reduces bedding costs. Among end users, municipal bodies command the largest committed spend cycles, though plumbing contractors capture disproportionate margin pools through specification influence and installation bundling.
China's SAMR enforces GB/T 3091 standards for welded galvanized steel tubes used in fluid transport, while India's BIS mandates IS 1239 and IS 3589 compliance for municipal water and structural applications respectively, creating divergent testing and certification burdens for cross-border suppliers. The US EPA's Lead and Copper Rule revisions indirectly bolster galvanized iron substitution where lead service line replacement programs prioritize corrosion-resistant alternatives. Stakeholders must monitor how evolving embodied-carbon accounting in public procurement reshapes material preference hierarchies before specification lock-in hardens.
Market Dynamics
Municipal water infrastructure renewal across India and Southeast Asia is realigning procurement toward corrosion-resistant piping, while China's dual carbon goals accelerate substitution away from uncoated steel. This structural force compresses specification timelines and rewards suppliers with certified low-carbon product lines.
Growth Catalysts
- India's BIS IS 1239 mandate:Municipal water authorities in Uttar Pradesh and Gujarat are specifying zinc-coated steel for new distribution networks, creating committed demand cycles that extend 7-10 years.
- Hot-dip galvanization process refinements:Continuous strip galvanizing lines now achieve 275 grams per square meter coating weights with 40% less energy input, lowering lifecycle costs for agricultural irrigation buyers.
- Urbanization clusters:India's northern industrial corridor combines metropolitan expansion with canal modernization, concentrating offtake in a geography with limited local coated-steel capacity.
Market Restraints
- Zing price volatility:Zinc ingot costs on the London Metal Exchange swing 15-25% within quarterly windows, compressing margin predictability for coating-dependent producers.
- High-density polyethylene substitution:HDPE pipe manufacturers in Vietnam and Thailand are capturing culvert and drainage specifications where flexural adaptability outweighs pressure ratings.
- China's GB/T 3091 compliance burden:Cross-border suppliers face divergent testing protocols between SAMR-certified domestic mills and export-oriented facilities, fragmenting quality assurance systems.
Strategic Opportunities
- Indonesia's trans-Java irrigation spine:The national strategic project plans 3,000 kilometers of pressurized distribution piping, with specifications still unsettled between metallic and thermoplastic alternatives.
- EU Green Deal embodied-carbon accounting:Public works tenders in Germany and France are introducing environmental product declarations that favor suppliers with Scope 3-certified zinc coatings.
- Corrugated pipe drainage applications:Road and rail infrastructure projects in Bangladesh and Myanmar are specifying annular corrugated profiles for reduced bedding depth and faster installation cycles.
Industry Challenges
- Skilled welder scarcity:Galvanized steel field joining requires certified procedures to avoid zinc fume exposure and brittle heat-affected zones, constraining installation capacity in rural Vietnam and Cambodia.
- Dual certification timelines:Suppliers seeking simultaneous BIS India and SAMR China approvals face 18-24 month validation windows that lock working capital in pre-production inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanized Iron Pipes Market |
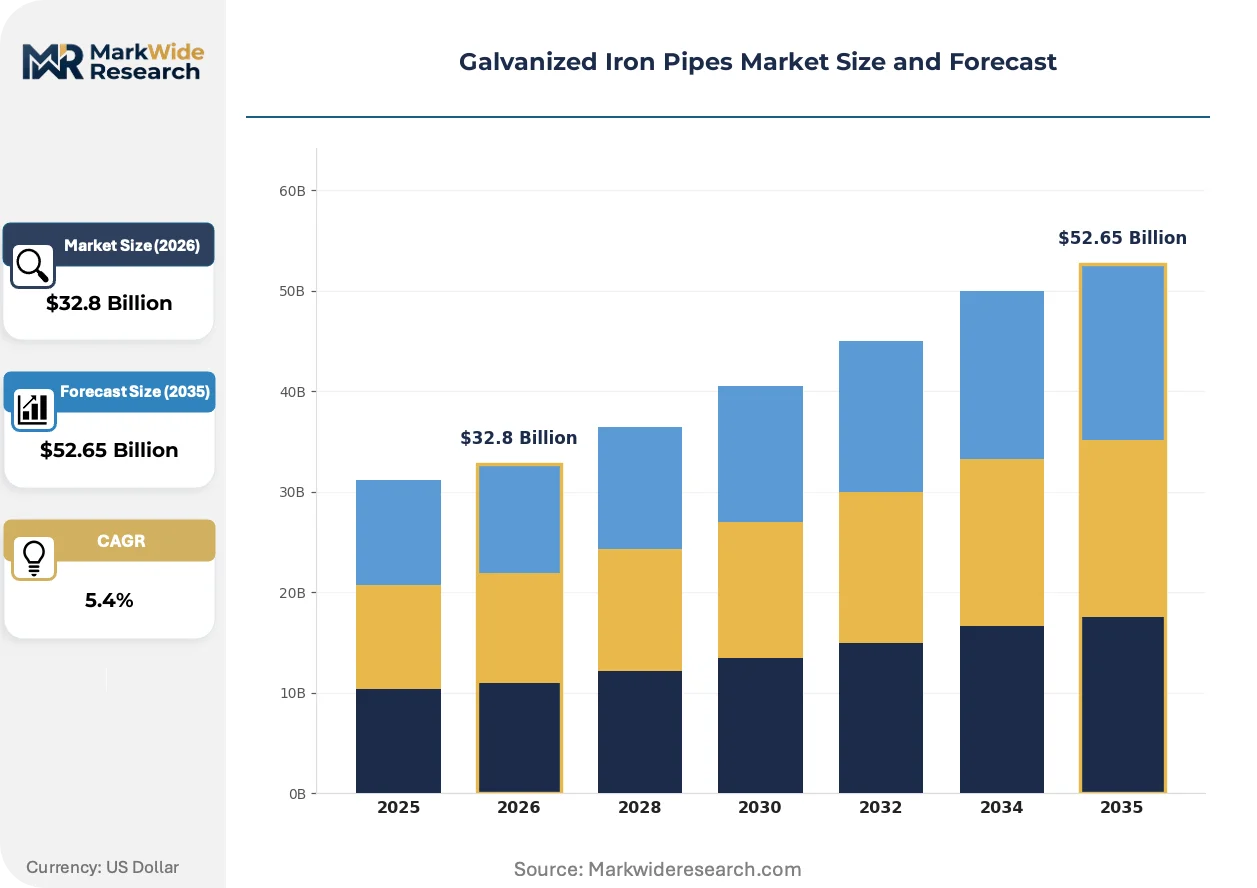
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Pipes, Square Pipes, Rectangular Pipes, Corrugated Pipes Application: Water Supply, Gas Distribution, Construction Framework, Scaffolding Installation Type: Above Ground, Underground, Submerged, Indoor End User: Municipal Bodies, Manufacturing Facilities, Agricultural Estates, Plumbing Contractors |
| Companies Covered | Baling Steel, GF Piping Systems, Aquatherm, IPEX USA LLC, BRUGG GROUP COMPANY, Valmont Tubing, Seah Steel, Tubos de Acero de Mexico, Husteel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanized Iron Pipes Market Trends and Innovations
Coating chemistry and joining technology are converging to extend service life in aggressive soil conditions while reducing installation labor. These developments are compressing the total cost of ownership calculus that municipal engineers apply when specifying materials.
Aluminum-zinc alloy coatings (55% aluminum, 43.4% zinc, 1.6% silicon by weight) are integrating into municipal water specifications where chloride-rich soils accelerate conventional zinc corrosion. Australian water utilities pioneered this specification shift, and Indian state irrigation departments are now piloting similar standards for coastal Maharashtra and Gujarat networks. The technology is integrating lifecycle cost analysis into procurement scoring matrices, disadvantaging pure zinc coatings in corrosive environments.
China's updated GB standards for construction materials now mandate recycled content disclosure in structural steel products, including galvanized tubes. MIIT enforcement inspections began in 2024, creating compliance differentiation between integrated steel mills with scrap-fed electric arc furnaces and blast furnace-dependent producers. Export-oriented fabricators in Jiangsu and Shandong are restructuring supply chains to secure domestic scrap flows and maintain European market access.
Specification influence is migrating from general contractors to specialized plumbing and mechanical engineering firms with direct municipal relationships. These intermediaries bundle material procurement with installation warranties, capturing margin pools that formerly accrued to distributors. The pattern is most visible in India's tier-2 city water privatization projects, where engineering-procurement-construction contractors now source directly from coating mills and manage subcontractor installation quality.
Galvanized Iron Pipes Market Segmentation
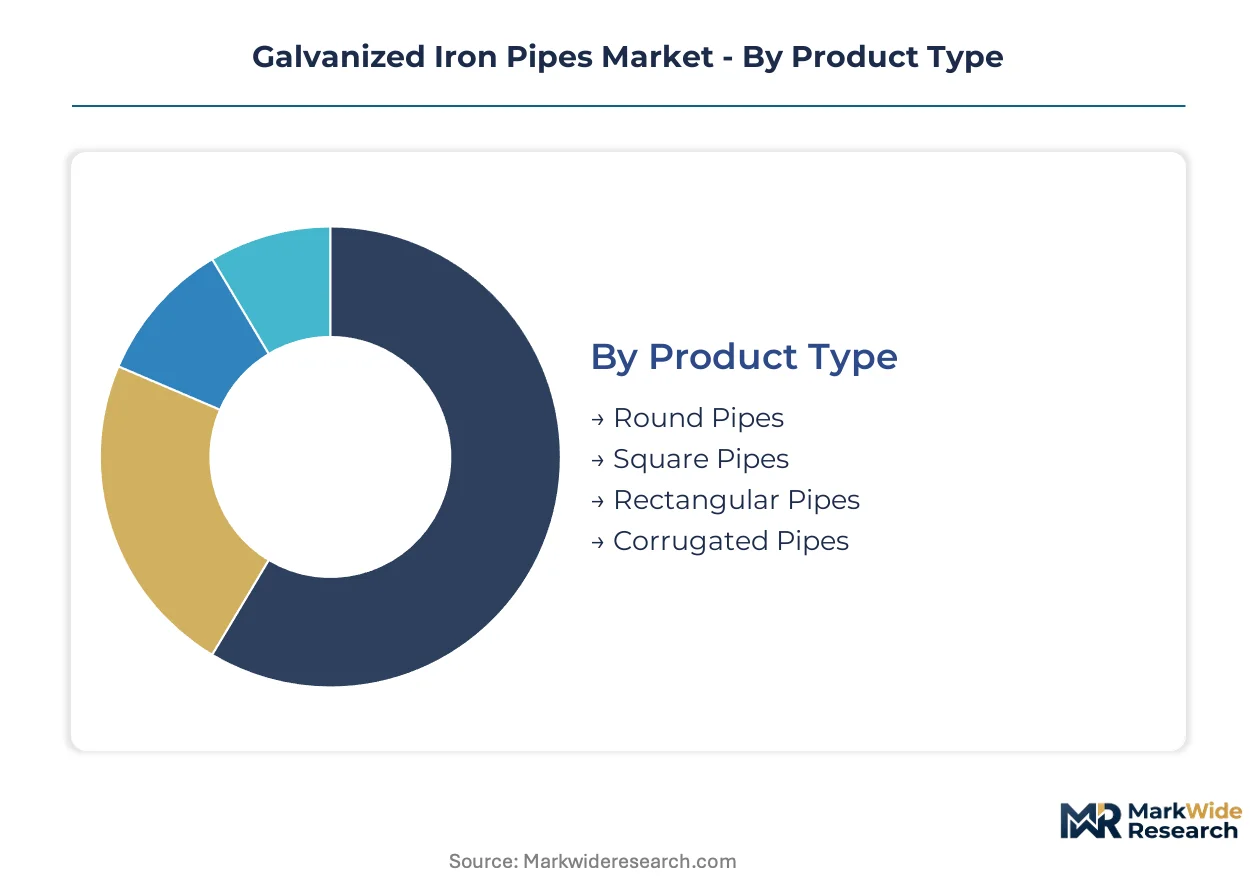
Specification diversity in galvanized iron pipes creates distinct procurement channels where geometry, pressure ratings, and corrosion exposure govern alloy selection. Engineers match product configurations to soil chemistry, fluid chemistry, and structural load requirements, fragmenting demand across specialized manufacturing lines.
Product Type:
Replacement cycles for buried infrastructure favor geometries that minimize field joints and extend service intervals in aggressive environments.
- Round Pipes:Seamless or welded circular cross-sections dominate pressurized fluid networks where hoop stress calculations govern wall thickness specifications. Uttar Pradesh municipal water authorities specify IS 1239-compliant round profiles for distribution mains, prioritizing pressure integrity over material savings in high-head irrigation zones.
- Corrugated Pipes:Annular or helical profiles with circumferential ribs provide flexural compliance for culvert and drainage bedding. Bangladesh road projects specify corrugated configurations to reduce excavation depth and accelerate installation cycles in monsoon-prone terrain where rigid pipe bedding costs escalate.
- Square Pipes:Uniform wall thickness across four faces suits structural frameworks and machinery guards where torsional stiffness matters. Fabricators in Gujarat's industrial corridor source square profiles for factory mezzanines and equipment enclosures.
- Rectangular Pipes:Asymmetric cross-sections optimize material efficiency in architectural facades and conveyor support systems. Maharashtra construction contractors specify rectangular profiles for aesthetic cladding substructures.
Round pipes sit at the top of the volume ranking, with corrugated profiles climbing the fastest as drainage specifications favor adaptability over pressure ratings.
Application:
Cost tier differentiation separates specification authority between municipal engineers with lifecycle budgets and contractors optimizing first-install economics.
- Water Supply:Potable and non-potable fluid conveyance demands zinc coating weights above 275 grams per square meter for soil corrosion resistance. India's northern industrial corridor concentrates offtake where canal modernization and urban expansion coincide, stretching local coated-steel capacity.
- Construction Framework:Load-bearing columns and trusses require controlled galvanization to preserve weldability in field assembly. Chinese MIIT enforcement of recycled content disclosure in GB standards is restructuring supply chains for structural tube exports to European markets.
- Gas Distribution:Medium-pressure fuel networks specify seamless or high-frequency welded tubes with leak-test certification. Korean shipyards source specialized corrosion-resistant grades for offshore platform piping.
- Scaffolding:Temporary access structures prioritize rapid assembly and impact resistance over coating longevity. Vietnamese construction sites face skilled welder scarcity for field jointing, constraining installation capacity.
Water supply commands the largest committed spend, while construction framework gains share fastest as China's dual carbon goals accelerate substitution from uncoated structural steel.
Installation Type:
Customer type fragmentation separates specification influence between municipal bodies with 20-year asset horizons and plumbing contractors capturing margin through installation bundling.
- Underground:Buried placement demands coating systems resistant to chloride-rich soils and stray electrical currents. Australian water utilities pioneered aluminum-zinc alloy specifications now piloted in coastal Maharashtra and Gujarat networks.
- Above Ground:Exposed installations prioritize UV-stable topcoats and drainage weep holes to prevent internal condensation. Agricultural irrigation networks in Indonesia's trans-Java corridor evaluate above-ground pressurized distribution against buried alternatives.
- Submerged:Permanent water immersion requires specialized barrier coatings beyond standard zinc layers. Offshore scaffolding applications in Korean shipyards specify enhanced corrosion-resistant grades.
- Indoor:Controlled environments permit lighter coating weights where atmospheric corrosion is minimal. Plumbing contractors in India's tier-2 city privatization projects bundle indoor specification with installation warranties.
Underground placement dominates municipal procurement volumes, with above-ground configurations expanding most quickly in agricultural retrofit segments.
End User:
Supply concentration in coating-capable mills creates procurement bottlenecks where specification authority has migrated from distributors to engineering-procurement-construction contractors.
- Municipal Bodies:City and regional water authorities operate 7-10 year committed demand cycles with lifecycle cost scoring. Uttar Pradesh and Gujarat authorities specify zinc-coated steel for new distribution networks, creating procurement queues at BIS-certified mills.
- Plumbing Contractors:Installation specialists capture margin pools through direct mill relationships and subcontractor quality management. India's tier-2 city privatization projects concentrate specification influence with firms bundling material and labor.
- Agricultural Estates:Irrigation cooperatives prioritize first-cost economics and rapid field repairability. Continuous strip galvanizing with reduced energy input is lowering lifecycle costs for this price-sensitive segment.
- Manufacturing Facilities:Industrial process water and fire suppression networks demand pressure-rated specifications with maintenance access. Factories in Vietnam and Thailand face HDPE substitution pressure in non-pressurized drainage.
Municipal bodies anchor procurement volumes, with plumbing contractors gaining specification influence fastest through bundled service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hot-dip galvanization originated in 18th-century France and industrialized across British foundries before scaling through American steel mills. The technology diffused to Asia-Pacific manufacturing bases during post-war reconstruction programs. Contemporary demand concentrates in infrastructure renewal corridors where coating weight specifications govern procurement.
China
MIIT enforcement of recycled content disclosure in GB standards began restructuring supply chains during 2024. SAMR-certified domestic mills with scrap-fed electric arc furnaces now hold compliance differentiation over blast furnace-dependent producers. Jiangsu and Shandong export fabricators scramble to secure domestic scrap flows for European market access.
India
Uttar Pradesh and Gujarat municipal water authorities specify IS 1239-compliant zinc-coated steel for distribution networks. BIS mandates create 7-10 year committed demand cycles that stretch local coated-steel capacity. The northern industrial corridor concentrates offtake where canal modernization and metropolitan expansion coincide.
United States
EPA Lead and Copper Rule revisions indirectly bolster galvanized iron substitution in lead service line replacement programs. Valmont Tubing anchors agricultural irrigation demand through controlled distribution networks across the Great Plains. Midwestern municipal engineers prioritize corrosion-resistant alternatives in aging water infrastructure assessments.
Germany
EU Green Deal embodied-carbon disclosure requirements for construction materials realign specification sheets across public works tenders. GF Piping Systems leverages thermoplastic-hybrid expertise to compete in low-carbon retrofit segments. Environmental product declarations in federal infrastructure procurement now favor Scope 3-certified coating suppliers.
South Korea
Seah Steel dominates Korean shipyard and offshore scaffolding offtake with specialized corrosion-resistant grades. Domestic yards specify enhanced coating systems for permanent saltwater immersion applications. Busan-Ulsan industrial clusters drive premium-grade demand for platform piping and marine construction.
Galvanized Iron Pipes Market Competitive Landscape
Capital-heavy integrated steel mills compete with asset-light coating specialists for specification influence in municipal procurement. The vendor base fragments across three tiers: multinational mills with captive galvanizing lines, regional fabricators serving single-country infrastructure programs, and niche specialists in corrugated or alloy-coated profiles. Two strategic moves dominate competitive positioning: backward integration into zinc coating capacity and forward integration into installation bundling through plumbing contractor partnerships.
Among Asia-Pacific-based producers, Baling Steel and Husteel occupy positions within the scale-driven mill tier, while Seah Steel exemplifies the corrosion-resistant specialist archetype serving marine applications. GF Piping Systems represents the hybrid-material competitor segment challenging metallic piping in low-carbon specification environments. These three anchors illustrate how geographic origin and product focus stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Baling Steel |
| GF Piping Systems |
| Aquatherm |
| IPEX USA LLC |
| BRUGG GROUP COMPANY |
| Valmont Tubing |
| Seah Steel |
| Tubos de Acero de Mexico |
| Husteel |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap coating specialists across India's Gujarat and Maharashtra states anchor supply discipline through generational control of BIS-certified galvanizing lines, translating into pricing power during municipal procurement cycles when specification windows compress.
Pricing Analysis
Contract-based long-term offtake agreements dominate municipal water authority procurement, with price differentiation resting on BIS certification tier and coating weight compliance. Three-tier pricing structure across premium, standard, and economy levels separates alloy-coated corrosion-resistant grades from conventional zinc coatings. Cost compression in standard-grade round pipe is intensifying because HDPE substitution pressure in drainage applications forces metallic suppliers to absorb zinc volatility. Agricultural estates exhibit highest price sensitivity, while municipal engineers with lifecycle budgets tolerate premium positioning for certified low-carbon alternatives.
Supply Chain Analysis
Single-source vulnerability sits with zinc ingot supply concentrated in Australia, China, and Peru, where London Metal Exchange pricing volatility feeds directly into coating cost structures. Raw material dependencies center on steel strip from blast furnace and electric arc furnace routes, zinc ingot for hot-dip baths, and aluminum-silicon alloy inputs for corrosion-resistant grades. Regulatory restriction risk manifests in China's MIIT recycled content disclosure mandates fragmenting export certification pathways. Distribution runs through engineering-procurement-construction contractors who have displaced traditional distributor networks in India's tier-2 city privatization projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS IS 1239 mandate and China's GB/T 3091 enforcement create sustained specification demand cycles that outlast commodity pricing cycles.
For Market Incumbents: Anticipate HDPE substitution acceleration in Vietnam and Thailand drainage specifications by securing aluminum-zinc alloy coating capacity for chloride-rich soil applications. Backward integration into scrap-fed electric arc furnace steelmaking addresses China's MIIT recycled content disclosure requirements for European market access. Prioritize direct contractor relationships in India's northern industrial corridor where plumbing bundling captures margin pools.
For New Entrants and Emerging Players: Plumbing contractors in India's tier-2 city privatization projects represent the most accessible channel partner type for specification influence without legacy mill infrastructure. Target corrugated pipe configurations for Bangladesh and Myanmar road and rail infrastructure where bedding cost reduction drives procurement decisions. Lead with installation warranty bundling to differentiate against established distributors.
For Investors and Strategic Acquirers: Integrated steel mills with captive galvanizing lines are the most active acquirer in this space, seeking coating specialists to secure BIS and SAMR dual certification capabilities. Five-to-ten year viability rests on low-carbon product line positioning as EU Green Deal embodied-carbon accounting hardens specification hierarchies. Monitor Indonesia's trans-Java irrigation spine specification decisions between metallic and thermoplastic alternatives as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Coating Capacity | Captures margin from volatile London Metal Exchange ingot pricing while ensuring BIS certification control. |
| Aluminum-Zinc Alloy Coating Scale-Up | Addresses Australian and Indian coastal utility specifications where chloride corrosion accelerates conventional zinc degradation. |
| Dual Certification Investment | Unlocks simultaneous BIS India and SAMR China market access despite 18-24 month validation timelines. |
| Plumbing Contractor Partnership Programs | Secures specification influence in India's tier-2 city privatization projects where bundling captures margin pools. |
| Scope 3-Certified Coating Supply | Qualifies for EU Green Deal environmental product declaration requirements in German and French public works tenders. |
Research Methodology
Multiple input streams — primary interviews with municipal procurement officers, coating mill operations directors, and plumbing contractor specification influencers; secondary validation through BIS certification databases, SAMR GB standard filings, and London Metal Exchange zinc price series; plus customs trade data for galvanized steel tube flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from infrastructure project developers across the analysis window. Segmentation dimensions modeled include product geometry, coating chemistry tier, installation type, and end-user procurement authority. CAGRs were derived from curve-fitting approaches applied to committed municipal spend cycles and agricultural irrigation replacement patterns, with zinc price volatility and regulatory compliance timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to China's dual carbon policy enforcement intensity and EU embodied-carbon accounting adoption speed. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market