
 Hafnium Foil Market | 2026-2036
Hafnium Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Hafnium Foil Market Insights
Zirconium-hafnium co-processing is consolidating supply economics as producers seek to capture value from chemically inseparable ore streams. American Elements leverages captive refining capacity to secure feedstock access across nuclear and semiconductor grades. Stanford Advanced Materials sustains broad catalog breadth spanning research quantities through production volumes. Advanced Engineering Materials specializes in tight-tolerance foils for neutron absorption applications.
Hafnium foil denotes cold-rolled or vacuum-annealed sheet stock ranging from 0.025 mm to 0.5 mm thickness, valued for neutron absorption cross-section, thermal stability in oxidizing environments, and dielectric properties in metal-oxide-semiconductor stacks. High-purity foil commands premium positioning where semiconductor gate stacks require sub-50 ppm zirconium contamination limits. Specialty foil for nuclear control rods represents a mature, specification-driven segment with long qualification cycles. Aerospace thermal barrier applications occupy a faster-growing niche driven by next-generation turbine inlet temperature requirements.
The US Nuclear Regulatory Commission governs hafnium deployment in reactor control assemblies through 10 CFR Part 50 licensing, while China's NMPA and MIIT jointly oversee semiconductor material import substitution targets under national IC development frameworks. REACH registration requirements in Europe constrain hafnium tetrachloride precursor sourcing for foil producers serving EU end users. Stakeholders must weigh zirconium-hafnium separation capacity investments against downstream qualification timelines in both nuclear and semiconductor verticals.
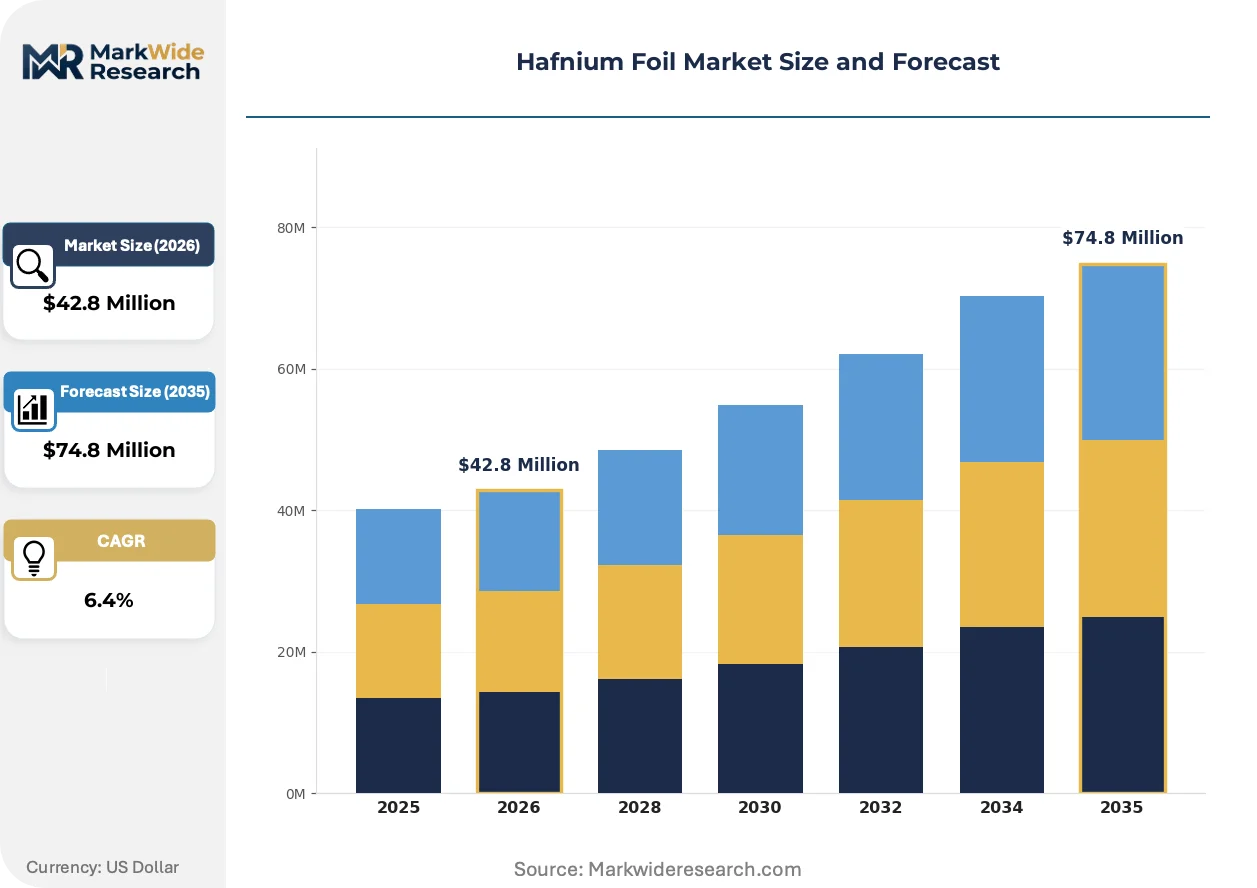
Market Dynamics
Zirconium-hafnium co-processing economics are tightening as chemically inseparable ore streams force producers to optimize dual-stream value capture. Semiconductor gate dielectric specifications and nuclear control rod qualification cycles create divergent purity requirements that strain separation capacity allocation.
Growth Catalysts
- Semiconductor scaling requirements:Sub-3nm transistor nodes demand hafnium-based high-k dielectrics for gate oxide stacks. Foundries in Taiwan and South Korea are expanding hafnium foil qualification programs.
- China's dual carbon framework:MIIT emissions intensity targets are accelerating material efficiency mandates across domestic semiconductor fabrication. Hafnium foil substitution reduces thermal barrier coating weight in turbine applications.
- Advanced reactor deployments:Small modular reactor designs specify hafnium control rod configurations. The US Nuclear Regulatory Commission 10 CFR Part 50 licensing pathway is streamlining qualification for next-generation reactor vendors.
Market Restraints
- Zirconium-hafnium separation concentration:Commercial separation capacity clusters with titanium mineral processors in Australia and South Africa. Feedstock access bottlenecks constrain independent foil producers.
- High-purity contamination limits:Semiconductor-grade foil requires sub-50 ppm zirconium content. Achieving these specifications demands vacuum arc remelting capacity with limited installed base.
- REACH registration compliance:ECHA hafnium tetrachloride precursor registration requirements constrain EU-serving producers. Registration costs and timeline uncertainty deter new market entrants.
Strategic Opportunities
- Aerospace thermal barrier coatings:Next-generation turbine inlet temperature requirements are expanding hafnium foil adoption for bond coat applications. GE Aerospace and Rolls-Royce are qualifying new foil specifications.
- India's PLI scheme for semiconductors:Ministry of Electronics and Information Technology production-linked incentives are attracting foundry investments. Domestic hafnium foil demand will emerge as fabrication capacity scales.
- Thin-film deposition convergence:Atomic layer deposition and physical vapor deposition toolmakers are standardizing hafnium precursor delivery systems. Equipment-foil integration partnerships can lock in specification leadership.
Industry Challenges
- Vacuum metallurgy talent scarcity:Electron beam melting and zone refining expertise concentrates with retiring specialists. Training programs at Colorado School of Mines and Tohoku University cannot replenish workforce gaps.
- Dual-use export control complexity:Nuclear-grade hafnium foil falls under NSG Guidelines and national export licensing. Producers must maintain separate production lines and documentation systems.
- Semiconductor qualification timeline compression:Foundry tape-out schedules demand 18-month foil qualification cycles. Material suppliers cannot accelerate thermal cycling and electrical characterization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hafnium Foil Market |
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $74.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Foil, High-Purity Foil, Specialty Foil, Tailored Foil Application: Aerospace, Nuclear Reactors, Semiconductor, Medical Devices Distribution Channel: Direct Sales, Online Retail, Distributor Networks, Third-Party Resellers End User: Manufacturers, Research Institutions, Defense Contractors, Electronics Firms |
| Companies Covered | American Elements, Stanford Advanced Materials, Advanced Engineering Materials, Jin Rui Industrial, Yunzhong Metal, Alfa Aesar, Goodfellow, MaTecK, Fushel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hafnium Foil Market Trends and Innovations
Process intensification in zirconium-hafnium separation is reshaping feedstock economics. Digital twin deployment in vacuum metallurgy and specification-driven procurement models are compressing traditional supply arrangements.
Electrochemical separation methods are decentralizing zirconium-hafnium feedstock production. American and Australian research consortia are piloting molten salt electrolysis as an alternative to liquid-liquid extraction. This technology is decentralizing separation capacity away from titanium mineral processing hubs and enabling regionalized high-purity metal production.
REACH authorization requirements for hafnium tetrachloride are tightening precursor supply chains. ECHA sunset date pressures are forcing foil producers to secure alternative chloride sources or invest in in-house chlorination. Semiconductor-grade producers serving EU end-users are most affected and are vertically integrating into precursor production.
Specification-driven procurement is consolidating buyer power around certified suppliers. Taiwan Semiconductor Manufacturing and Samsung Foundry are narrowing approved vendor lists to dual-qualified nuclear-semiconductor producers. This concentration is most visible in East Asian semiconductor clusters where foundry consolidation amplifies sourcing leverage.
Hafnium Foil Market Segmentation
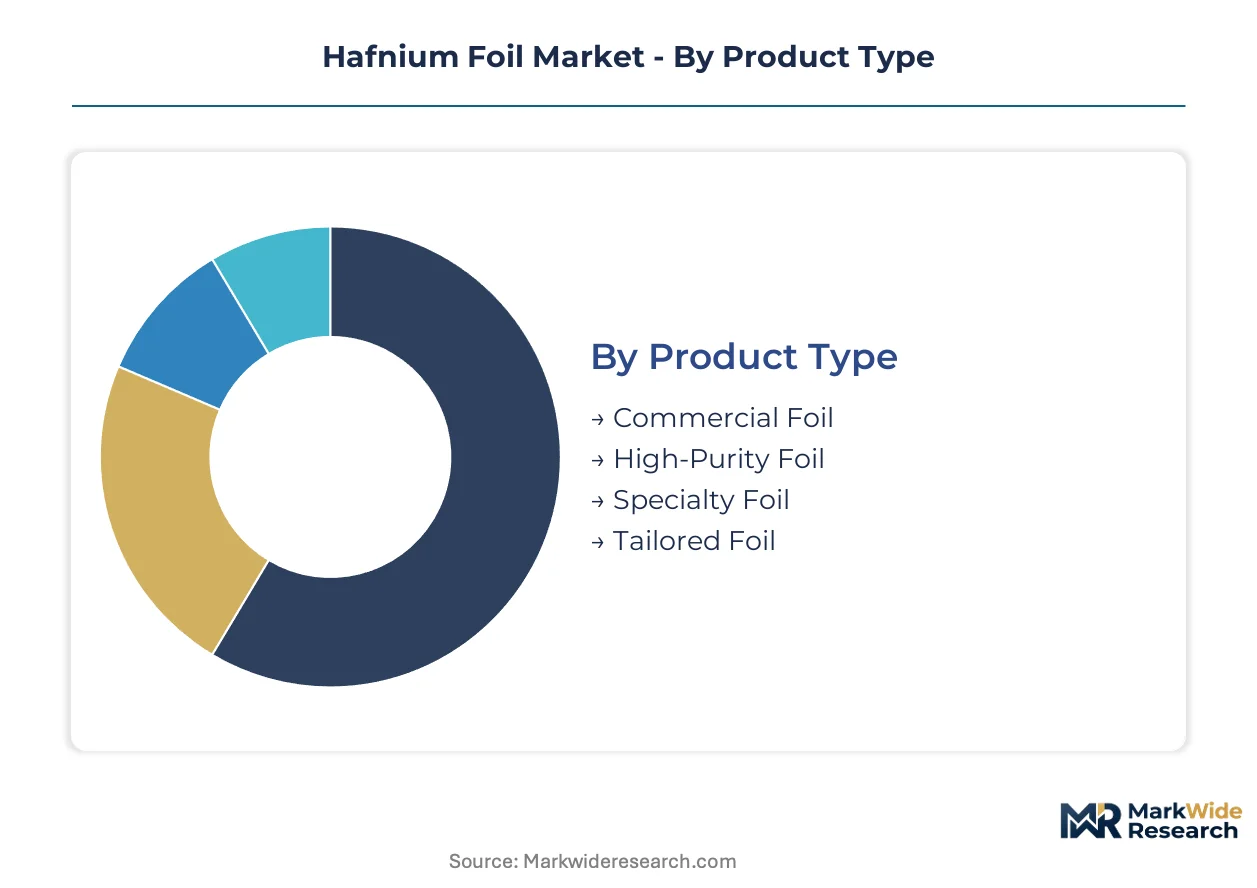
Hafnium foil segmentation reflects divergent purity requirements across nuclear, semiconductor, and aerospace verticals. Each category captures distinct procurement patterns, qualification timelines, and price elasticity profiles that shape supplier positioning.
Product Type:
Buyers differentiate primarily by contamination tolerance and certification burden rather than unit economics alone.
- Commercial Foil:Cold-rolled sheet stock with standard metallurgical grades serves industrial thermal barrier and general research applications. Demand concentrates in university laboratories and materials testing facilities across the United States and Germany where budget constraints override extreme purity requirements.
- High-Purity Foil:Vacuum-arc-remelted material with sub-50 ppm zirconium content addresses semiconductor gate dielectric specifications. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement programs are concentrating demand in Hsinchu and Pyeongtaek fabrication clusters.
- Specialty Foil:Neutron-optimized grades for nuclear control rod assemblies require US Nuclear Regulatory Commission 10 CFR Part 50 licensing documentation.
- Tailored Foil:Custom thickness and surface finish specifications serve aerospace bond coat prototyping programs at GE Aerospace and Rolls-Royce.
Commercial foil leads volumes today; high-purity foil is gaining share fastest.
Application:
End-use selection hinges on operating environment severity and regulatory exposure.
- Aerospace:Thermal barrier coating substrates for next-generation turbine inlet temperatures demand tight thickness tolerances. Rolls-Royce qualification programs in Derby are expanding specification requirements.
- Nuclear Reactors:Control rod cladding and neutron absorber configurations require dual-use export licensing under NSG Guidelines. Westinghouse and Framatome procurement cycles extend qualification timelines.
- Semiconductor:High-k dielectric gate stacks at sub-3nm nodes command premium positioning. Foundry consolidation in Taiwan and South Korea is narrowing approved vendor lists.
- Medical Devices:Biocompatible implant prototypes and radiotherapy shielding occupy a niche segment with small batch requirements.
Nuclear reactors anchor revenue stability; semiconductor applications show steepest expansion trajectory.
Distribution Channel:
Channel preference tracks order size predictability and technical support intensity.
- Direct Sales:Long-term supply agreements with nuclear utilities and semiconductor foundries specify dedicated account engineering. American Elements and Stanford Advanced Materials maintain direct field presence in Pittsburgh and Salt Lake City.
- Distributor Networks:Regional stocking locations serve research institutions and mid-tier manufacturers with fragmented demand patterns.
- Online Retail:Catalog quantities for academic research and prototyping bypass procurement bureaucracy.
- Third-Party Resellers:Import-export specialists handle REACH documentation and dual-use licensing for cross-border transactions.
Direct sales capture the largest contract value; distributor networks are expanding coverage most aggressively.
End User:
User category determines specification authority and qualification risk tolerance.
- Manufacturers:Tier-1 aerospace and industrial gas turbine producers drive volume with multi-year blanket orders. GE Aerospace sourcing committees in Cincinnati and Evendale set metallurgical benchmarks.
- Defense Contractors:National security classification requirements impose separate production lines and audit protocols. BAE Systems and Naval Nuclear Laboratory specifications restrict supplier pools.
- Research Institutions:National laboratories and university materials science departments generate small-batch demand with high specification variability.
- Electronics Firms:Fabless semiconductor designers and MEMS fabricators require rapid prototyping turnaround with flexible minimum order quantities.
Manufacturers dominate current procurement volume; electronics firms are emerging as the most price-insensitive customer class.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors semiconductor-grade hafnium foil procurement, with foundry consolidation in Taiwan and South Korea driving specification intensity across East Asian fabrication clusters.
United States
Nuclear reactor deployments and aerospace turbine programs sustain demand for neutron-optimized and thermal barrier grades. The US Nuclear Regulatory Commission governs control rod assemblies through 10 CFR Part 50 licensing. Pittsburgh hosts American Elements' refining operations serving dual nuclear-semiconductor supply chains.
China
Domestic semiconductor fabrication expansion and dual carbon emissions targets accelerate material efficiency mandates. MIIT oversees import substitution frameworks under national IC development programs. Yangtze River Delta foundry clusters in Shanghai and Wuxi are qualifying hafnium foil for sub-3nm node production.
Germany
Research institution demand and REACH compliance requirements shape procurement patterns for precursor materials. ECHA registration obligations constrain hafnium tetrachloride sourcing for EU-serving producers. Bavarian materials science centers in Munich drive small-batch specialty foil orders.
Japan
Precision metallurgy heritage and advanced reactor research sustain high-specification foil demand. METI coordinates national energy technology roadmaps including SMR control material specifications. Tohoku University maintains vacuum metallurgy training programs addressing workforce gaps in electron beam melting expertise.
South Korea
Memory and logic foundry investments concentrate procurement power among vertically integrated electronics conglomerates. MFDS and national semiconductor initiatives align material sourcing with domestic fabrication targets. Pyeongtaek semiconductor complexes are narrowing approved vendor lists to dual-qualified suppliers.
Hafnium Foil Market Competitive Landscape
Global majors compete with regional champions across purification and qualification capabilities. The supplier base organizes around captive zirconium-hafnium separation assets, vacuum metallurgy expertise, and dual-use licensing infrastructure. Three archetypes dominate: integrated mineral processors with downstream foil capacity, specialized refractory metal refiners serving nuclear and semiconductor grades, and catalog distributors bridging research and production quantities. Capacity expansion and strategic partnerships with deposition equipment makers represent the primary competitive vectors.
Among North American suppliers, American Elements exemplifies the integrated archetype with captive refining capacity spanning nuclear and semiconductor specifications. Stanford Advanced Materials occupies the catalog breadth position, sustaining research-through-production volume flexibility. Advanced Engineering Materials represents the application-specialist tier, focusing on tight-tolerance configurations for neutron absorption deployments.
| Leading Market Players |
|---|
| American Elements |
| Stanford Advanced Materials |
| Advanced Engineering Materials |
| Jin Rui Industrial |
| Yunzhong Metal |
| Alfa Aesar |
| Goodfellow |
| MaTecK |
| Fushel |
| Others |
Pricing and Supply Chain Analysis
Zirconium-hafnium separation costs cascade through three distinct pricing tiers as chemically inseparable ore streams force producers to allocate scarce vacuum arc remelting capacity between nuclear certification and semiconductor purity requirements. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement programs concentrate buyer power around sub-50 ppm zirconium specifications, while Westinghouse and Framatome sustain premium positioning for neutron-optimized grades through 10 CFR Part 50 licensing documentation.
Pricing Analysis
Input-cost pass-through from Australian and South African titanium mineral processors governs commercial foil pricing, with vacuum metallurgy energy intensity driving premium-mid-economy pricing differentiation across nuclear, semiconductor, and aerospace tiers. Semiconductor-grade foil commands the widest spreads due to contamination limits and electron beam melting scarcity, while research quantities show highest price sensitivity among university laboratories. Cost compression in commercial grades is intensifying as Chinese domestic fabrication scales and challenges incumbent supplier margins.
Supply Chain Analysis
Dual-sourcing requirements from Taiwan Semiconductor Manufacturing and Samsung Foundry mandate multi-supplier qualification programs that strain limited high-purity production capacity. Supply concentrates in Australia, South Africa, and the United States for zirconium-hafnium feedstock, while China and South Korea dominate downstream foil consumption for semiconductor and nuclear applications. The supply chain draws from titanium mineral processing hubs, hafnium tetrachloride precursor networks, and vacuum metallurgy specialists, with single-source vulnerability around electron beam melting expertise representing the dominant structural risk. Distribution runs through direct sales for nuclear utilities and foundries, with regional distributors serving fragmented research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hafnium foil functions as a stable compounder anchored by irreplaceable neutron absorption properties and sub-3nm semiconductor scaling requirements that sustain dual-demand resilience across reactor deployments and logic foundry expansions.
For Market Incumbents: Deepen captive zirconium-hafnium separation investments in Australia and South Africa to defend feedstock access against electrochemical separation disruptors. Secure dual nuclear-semiconductor qualification status with Taiwan Semiconductor Manufacturing and Samsung Foundry to lock in specification leadership before India's PLI scheme attracts new fabrication capacity. For New Entrants and Emerging Players: Capture aerospace thermal barrier coating prototyping demand at GE Aerospace and Rolls-Royce where qualification timelines remain shorter than nuclear or semiconductor cycles. Target India's emerging foundry clusters in Gujarat and Tamil Nadu as domestic semiconductor fabrication scales under Ministry of Electronics and Information Technology incentives, using equipment-foil integration partnerships with atomic layer deposition toolmakers as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum metallurgy talent scarcity and dual-use licensing infrastructure create moats around incumbent refining capacity. The five-to-ten-year viability window favors specialized refractory metal refiners with captive separation assets and existing 10 CFR Part 50 documentation. Watch electrochemical separation pilot results from American and Australian research consortia as the signal indicating potential feedstock economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconium-Hafnium Separation | Captures value from chemically inseparable ore streams and secures feedstock access against titanium mineral processor concentration. |
| Vacuum Arc Remelting Capacity Expansion | Addresses electron beam melting scarcity and qualifies sub-50 ppm zirconium specifications for Taiwan Semiconductor Manufacturing procurement. |
| Dual Nuclear-Semiconductor Qualification Investment | Unlocks 10 CFR Part 50 licensing documentation and foundry approved vendor list inclusion simultaneously. |
| Equipment-Foil Integration Partnership | Locks in specification leadership with atomic layer deposition and physical vapor deposition toolmakers standardizing precursor delivery. |
| Regional Production Footprint in India | Positions supply adjacent to Ministry of Electronics and Information Technology PLI scheme foundry investments in Gujarat and Tamil Nadu. |
Research Methodology
Multiple input streams — primary interviews with vacuum metallurgy specialists, semiconductor foundry procurement directors, and nuclear utility fuel managers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged electron beam melting operators at Colorado School of Mines and Tohoku University, reactor control rod specification engineers at Westinghouse and Framatome, and thin-film deposition equipment specialists. Secondary sources included US Nuclear Regulatory Commission 10 CFR Part 50 licensing databases, ECHA REACH registration filings for hafnium tetrachloride, MIIT semiconductor import substitution policy documents, and customs trade data from Australian and South African titanium mineral processors.
Data-stream reconciliation across product type, application, distribution channel, and end user dimensions anchored volume and value outputs throughout the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and supply capacity constraints, with semiconductor node transition roadmaps and small modular reactor deployment schedules serving as industry-specific forecast inputs alongside zirconium-hafnium separation capacity expansion announcements.
Electrochemical separation technology maturation, REACH authorization timeline shifts for hafnium tetrachloride, and foundry consolidation dynamics in Taiwan and South Korea are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Stainless Steel Round Bar Market
Metals
Seamless Stainless Steel Products Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Stainless Steel 400 Series Market
Metals
Copper Wire Market
Metals
Smelting Chemicals Market
Metals
Iron and Steel Market
Metals
Metal Recycling Market
Metals
Europe Aluminium Cans Market
Metals
North America Metal Finishing Market
Metals
Silver-Platinum Paste Market
Metals
Copper Foil Market
Metals
Huntite Market
Metals
Ferrochrome Market
Metals
Palladium Market
Metals
Steel Wire Market