
 Copper Azoles Market | 2026-2036
Copper Azoles Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Azoles Market Outlook
Specialized formulation chemists and wood preservation technicians is reorganizing competitive capacity across the Copper Azoles landscape. Lonza leverages its integrated active ingredient supply chain to secure raw material continuity for azole synthesis. Koppers Inc. anchors North American distribution through its treated wood service network and rail-tie preservation contracts. Viance LLC differentiates via EPA-registered micronized copper systems that extend preservative penetration depth.
Copper azoles designate a class of organic-inorganic wood preservatives combining soluble copper with triazole fungicides such as tebuconazole or propiconazole, typically formulated at copper-to-azole ratios between 10:1 and 50:1 depending on decay hazard classification. The copper component provides primary protection against brown rot and termite attack, while azole co-biocides address copper-tolerant white rot fungi in above-ground and ground-contact applications. Wood Preservatives dominates application value due to replacement cycles in residential decking, utility poles, and marine pilings, though Coatings represents the fastest-expanding segment as architectural metal protection absorbs copper azole chemistry for corrosion-inhibiting primers. Product type concentration favors CuIAz formulations in North American pressure-treatment facilities, while CuN variants gain traction in European Union markets where propiconazole registrations face stricter ECHA scrutiny under REACH authorization procedures.
EPA Office of Pesticide Programs governs copper azole registration under FIFRA, with ongoing re-evaluation of human health exposure thresholds affecting label rates and end-use restrictions. ECHA implements REACH authorization requirements for certain triazole active substances, compelling reformulation toward alternative azole chemistries or copper-only systems for European wood treaters. Construction sector procurement teams and preservative formulators must monitor regulatory divergence between EPA and ECHA frameworks, as divergent hazard classifications will fragment product portfolios and testing protocols across Atlantic supply chains.
Market Dynamics
EPA re-registration reviews and ECHA REACH authorizations are compressing formulation timelines for copper azole manufacturers, forcing simultaneous compliance with divergent biocide standards across Atlantic supply chains.
Growth Catalysts
- Residential construction recovery:Pressure-treated decking demand in the United States is pulling preservative volumes as housing starts absorb treated lumber for outdoor structures.
- REACH authorization timelines:European wood treaters are accelerating reformulation investments ahead of propiconazole sunset dates, sustaining R&D throughput for alternative azole chemistries.
- Marine infrastructure replacement:Coastal piling and dock reconstruction cycles in ground-contact applications are expanding copper azole uptake for dual-decay protection.
Market Restraints
- Copper price volatility:Electrolytic copper cathode fluctuations directly compress margin structures for formulators lacking long-term concentrate contracts.
- Active ingredient concentration:Azole synthesis capacity clusters in select chemical manufacturing regions, exposing supply continuity risks from single-source dependencies.
- Biocide substitution pressure:Micronized copper carbonate systems without azole co-biocides are capturing share in above-ground applications with simpler regulatory pathways.
Strategic Opportunities
- Coatings segment expansion:Architectural metal primers incorporating copper azole chemistry for corrosion inhibition represent untapped formulation white space beyond wood preservation.
- Utility pole renewal programs:Electric transmission infrastructure replacement schedules in the United States are concentrating demand for ground-contact preservative systems.
- EPA label expansion:Revised FIFRA registrations enabling modified application rates create formulation differentiation opportunities for treaters with accelerated testing capabilities.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in copper-azole compatibility and leaching resistance testing is concentrating among legacy wood preservation laboratories.
- Treatment facility capex cycles:Pressure-plant retort upgrades for micronized copper systems demand capital commitments that smaller treaters cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Azoles Market |
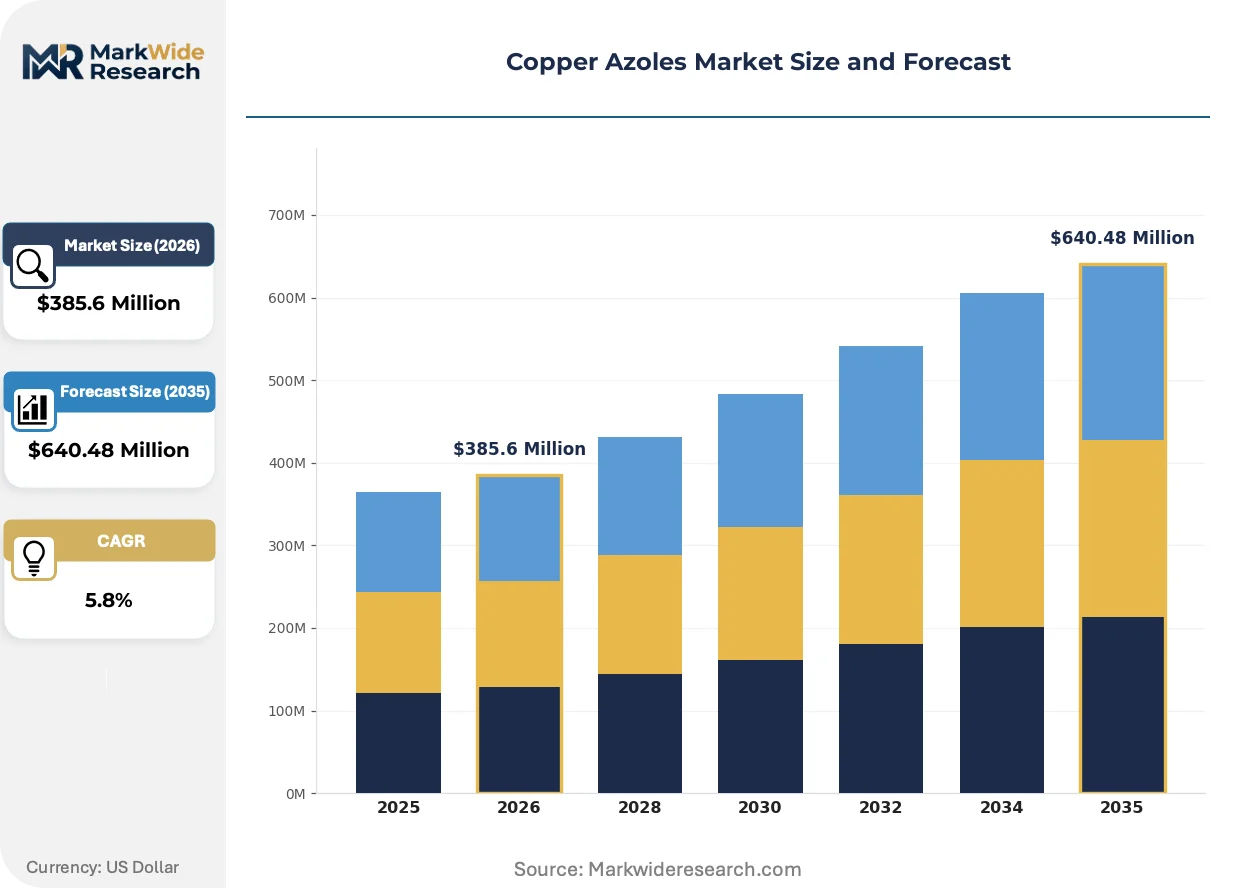
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper 8-Azacol, CuIAz, CuB, CuN Application: Pesticides, Wood Preservatives, Coatings, Textiles End User: Agriculture, Construction, Manufacturing, Automotive Distribution Channel: B2B, Retail, Online, Direct Sales |
| Companies Covered | Koppers Inc., Lonza, UFP Industries, Inc., ACURO ORGANICS LIMITED, COX STUD WELDING, Conrad Forest Products, North Sawn Lumber, Wilson Timbers Pty Ltd, Viance LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Azoles Market Strategic Shifts
Copper azole chemistry is splitting across divergent technical trajectories as regulatory pressure and end-use specialization force simultaneous innovation in both micronized and soluble copper systems.
Micronized copper carbonate technology is bifurcating the wood preservative landscape. The technology delivers sub-micron particle penetration without azole co-biocides for above-ground applications. North American pressure-treatment facilities are retrofitting retort systems to accommodate these formulations. This split is compressing traditional soluble copper azole volumes in residential decking while expanding total addressable preservative demand.
ECHA REACH authorization procedures for triazole active substances are fragmenting European formulation portfolios. The regulatory framework requires substitute biocide evaluation or copper-only system migration before sunset deadlines. Wood treaters in Germany and France are front-loading reformulation trials to secure continuity certifications. This policy compression is accelerating azole chemistry diversification toward propiconazole alternatives.
Specification-driven procurement now dominates commercial construction segments. Architects and structural engineers are mandating third-party certification marks for treated lumber in ground-contact applications. This behavioral shift is displacing price-based supplier selection with performance-guarantee contracting. The pattern is most visible in United States multi-family housing developments where warranty terms determine preservative system approval.
Copper Azoles Market Segmentation
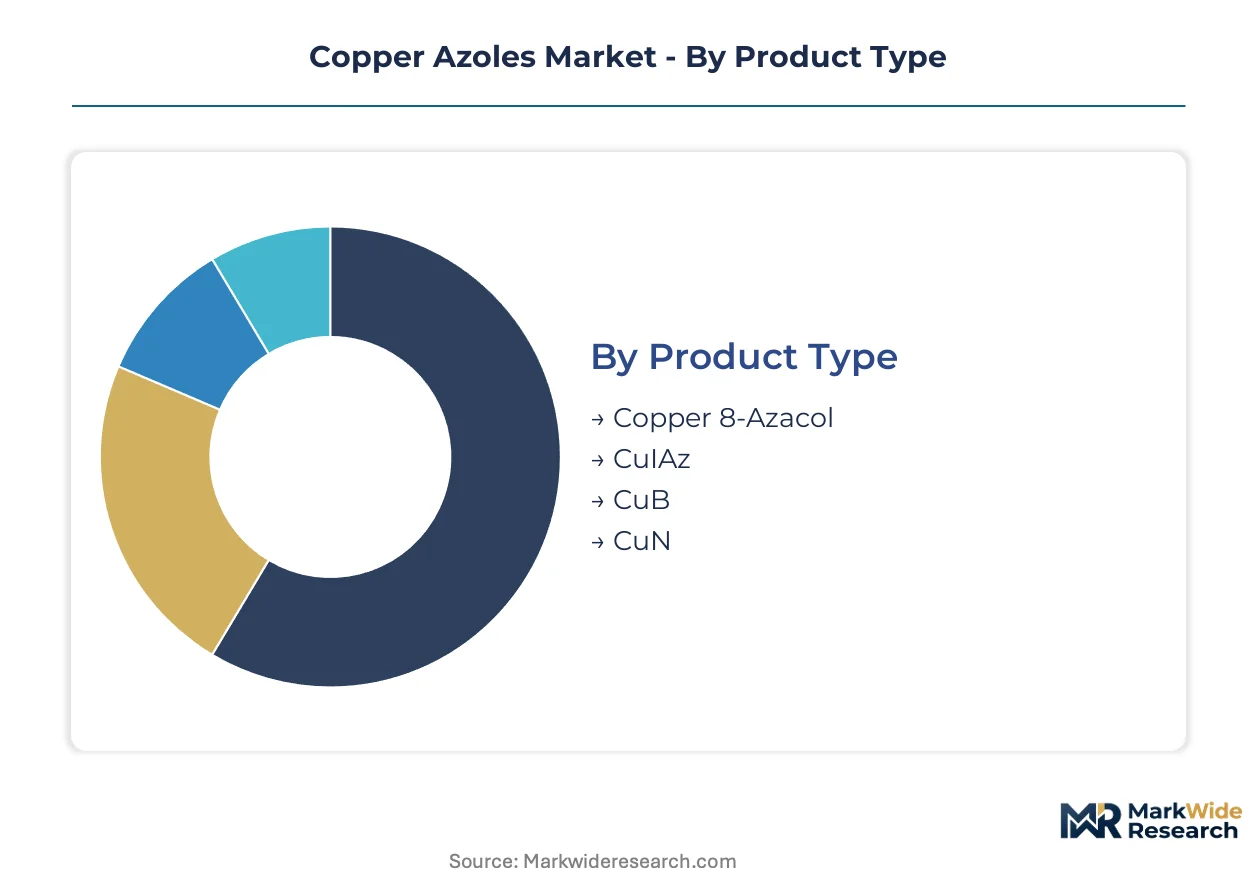
Copper azole formulations vary sharply in copper loading and azole pairing, creating divergent substitution risks from micronized copper systems and alternative biocides. Segmentation reveals where formulation investments concentrate and which chemistries face regulatory compression.
Product Type:
Micronized copper carbonate alternatives exert the strongest substitution pressure on soluble copper azole systems, forcing product-level differentiation around leaching resistance and decay hazard classification.
- CuIAz:Combines soluble copper with tebuconazole in ratios optimized for ground-contact applications. North American pressure-treatment facilities favor this chemistry for residential decking and utility poles where brown rot and termite protection are mandatory. EPA label expansions for modified application rates are sustaining R&D investment despite copper price volatility.
- CuN:Pairs copper with propiconazole, dominant in European Union markets where ECHA REACH authorization timelines are forcing reformulation toward alternative azole chemistries. German and French wood treaters are front-loading certification trials to secure continuity ahead of sunset deadlines.
- Copper 8-Azacol:Specialized azole variant with niche uptake in marine piling applications requiring dual-decay protection against salt-tolerant fungi.
- CuB:Boron-stabilized copper azole formulation offering enhanced fixation in high-moisture climates; limited penetration outside Asia-Pacific treater networks.
CuIAz retains volume leadership; CuN holds the steepest expansion curve as European reformulation accelerates.
Application:
Cost-tier stratification separates commodity wood preservation from specialized coatings where copper azole chemistry commands formulation premiums.
- Wood Preservatives:Pressure-treated lumber for residential decking, utility poles, and marine pilings absorbs the majority of copper azole volume. Replacement cycles in United States housing markets and coastal infrastructure reconstruction are pulling sustained demand despite micronized copper competition in above-ground segments.
- Coatings:Architectural metal primers incorporating copper azole chemistry for corrosion inhibition represent the fastest-expanding application as specification-driven procurement displaces price-based selection in commercial construction.
- Pesticides:Agricultural fungicide formulations with copper azole active ingredients face regulatory scrutiny from EPA and ECHA residue thresholds.
- Textiles:Antimicrobial fabric treatments utilizing copper azole biocides; limited scale due to leaching concerns in wash-cycle applications.
Wood Preservatives dominates absolute volume; Coatings is climbing the fastest as corrosion-inhibition specifications proliferate.
End User:
Customer-type concentration centers on construction procurement teams with warranty-driven specification authority.
- Construction:Multi-family housing developers and commercial general contractors mandate third-party certification marks for treated lumber, displacing price-based supplier selection with performance-guarantee contracting.
- Agriculture:Vineyard and orchard operators utilize copper azole fungicides under residue-monitored application protocols.
- Manufacturing:Pressure-treatment facilities and coatings formulators integrate copper azole chemistry into production lines.
- Automotive:Corrosion-resistant primer applications for underbody coatings; emerging specification niche.
Construction commands procurement volume concentration; Manufacturing absorbs the steepest input cost pressure from copper cathode fluctuations.
Distribution Channel:
Supply concentration among legacy wood preservation laboratories shapes channel access for specialized formulations.
- B2B:Direct supply relationships between azole manufacturers and pressure-treatment facilities; dominant channel for CuIAz and CuN bulk formulations.
- Direct Sales:Technical service agreements linking formulation chemists to treater R&D departments for custom copper-to-azole ratio development.
- Retail:Consumer-accessible wood preservative products for DIY decking maintenance; limited copper azole content due to application complexity.
- Online:Emerging channel for specialty coatings and agricultural pesticide formulations; constrained by hazardous material shipping regulations.
B2B retains channel dominance; Direct Sales is gaining share fastest as reformulation timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper azole consumption patterns diverge sharply by geography. The United States favors ground-contact formulations for residential decking and utility infrastructure. European treaters navigate REACH-driven reformulation toward alternative azole chemistries. Asian markets absorb specialized marine-grade variants for coastal reconstruction.
United States
Pressure-treated lumber demand from multi-family housing developments and outdoor structure construction sustains copper azole volumes. EPA Office of Pesticide Programs governs FIFRA registration reviews that reshape label rates and end-use restrictions. The Southeast housing corridor from Florida through Georgia concentrates treated wood facility capacity and preservative procurement.
Germany
Wood treaters front-load reformulation trials ahead of ECHA REACH authorization deadlines for propiconazole-based systems. The country's national chemical regulator enforces strict biocide hazard classifications that compress formulation timelines. Industrial preservative laboratories in the Rhine-Ruhr cluster accelerate alternative azole chemistry certification.
France
Ground-contact applications in coastal infrastructure and vineyard support structures sustain copper azole uptake. ECHA implements REACH authorization requirements that compel migration toward copper-only or alternative biocide systems. Wood preservation facilities in the Provence-Alpes-Côte d'Azur region specialize in marine-grade formulation testing.
China
Coastal piling replacement cycles and utility pole expansion programs absorb copper azole volumes for dual-decay protection. The Ministry of Ecology and Environment enforces discharge standards that affect wood treatment facility operations. Yangtze River Delta manufacturing clusters integrate preservative chemistry into construction materials supply chains.
Australia
Salt-tolerant fungal decay in marine environments drives specification of specialized copper azole variants for dock and wharf reconstruction. The national pesticide regulator administers re-registration reviews that align with OECD biocide standards. Queensland coastal infrastructure projects concentrate demand for ground-contact preservative systems.
Copper Azoles Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in copper azole supply. Integrated active ingredient manufacturers secure raw material continuity through captive copper and azole synthesis capacity. Specialist wood preservation service providers anchor regional distribution through treatment facility networks. The dominant competitive moves involve portfolio diversification across micronized and soluble copper systems and geographic expansion through technical service agreements.
Within the integrated manufacturing tier, Lonza and Koppers Inc. exemplify divergent strategic positioning. Lonza represents the chemistry-forward archetype with integrated azole synthesis capabilities. Koppers Inc. anchors the service-integrated model through its treated wood facility network and rail-tie preservation contracts. Viance LLC occupies a specialized position with EPA-registered micronized copper systems that extend preservative penetration specifications.
| Leading Market Players |
|---|
| Koppers Inc. |
| Lonza |
| UFP Industries, Inc. |
| ACURO ORGANICS LIMITED |
| COX STUD WELDING |
| Conrad Forest Products |
| North Sawn Lumber |
| Wilson Timbers Pty Ltd |
| Viance LLC |
| Others |
Value Chain & Pricing Dynamics
EPA FIFRA registration tiers gate both supplier qualification and price differentiation in copper azole markets, as treaters lacking accelerated testing capabilities cannot access modified label rates that command formulation premiums. This regulatory filtering concentrates pricing power among legacy laboratories with established EPA relationships while compressing margins for commodity bulk suppliers.
Pricing Analysis
Long-term offtake contracts dominate copper azole procurement between integrated manufacturers and pressure-treatment facilities, insulating volume buyers from electrolytic copper cathode spot volatility. Price differentiation rests on EPA label tier and third-party certification depth, with ground-contact rated formulations commanding premiums over above-ground alternatives. Cost compression in standard-grade soluble copper systems is intensifying because micronized copper carbonate alternatives capture share in residential decking. DIY retail channels exhibit the highest price sensitivity, while multi-family housing developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Inventory lead times for azole active ingredients stretch disproportionately against copper concentrate availability, reflecting single-source dependencies in triazole synthesis clusters. Supply concentrates in the United States, Germany, and China, with azole manufacturing anchored in specialized chemical corridors. Raw material flows draw from electrolytic copper cathode markets, tebuconazole synthesis facilities, and propiconazole precursor suppliers. Tariff exposure on Chinese azole intermediates presents structural vulnerability. Distribution runs through B2B direct supply relationships linking active ingredient manufacturers to pressure-treatment facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service agreements and reformulation support contracts represent the fastest-expanding recurring revenue layer in copper azole markets, outpacing hardware-centric preservative sales as ECHA REACH deadlines accelerate R&D outsourcing.
For Market Incumbents: Shield formulation margins by deepening backward integration into azole synthesis capacity and securing captive copper concentrate offtake ahead of price volatility. Micronized copper carbonate substitution threatens soluble copper azole volumes in above-ground segments; counter by expanding EPA-registered label tiers that commodity competitors cannot replicate. Prioritize certification investment in ground-contact performance guarantees for multi-family housing developers. For New Entrants and Emerging Players: Anchor in architectural metal coatings where copper azole chemistry for corrosion inhibition remains underpenetrated relative to wood preservation saturation. European reformulation timelines ahead of ECHA propiconazole sunset dates create immediate white-space demand for alternative azole certification services. Pursue technical service partnerships with mid-sized German and French wood treaters lacking in-house R&D capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across micronized copper system retrofitting as pressure-treatment facilities absorb retort upgrade cycles. Long-term viability favors integrated players with simultaneous active ingredient and treatment service capabilities. Acquisition targets should display dual EPA-ECHA regulatory navigation competence. The signal to watch is ECHA authorization timeline acceleration for remaining triazole chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Azole Synthesis | Captive tebuconazole production secures supply continuity against REACH-driven reformulation surges. |
| Micronized Copper System Certification | EPA-registered sub-micron penetration specifications differentiate above-ground formulations from soluble copper alternatives. |
| Technical Service Agreement Expansion | Reformulation support contracts capture recurring revenue as ECHA deadlines compress treater R&D timelines. |
| Ground-Contact Label Tier Investment | Modified application rate approvals unlock premium positioning in utility pole and marine piling procurement. |
| European Alternative Azole Portfolio | Propiconazole substitute certification ahead of REACH sunset dates secures continuity in German and French markets. |
Study Parameters
Cross-validation between formulation chemist interviews and regulatory filing analysis anchors the qualitative findings in this copper azole assessment. Primary fieldwork engaged wood preservation technicians, pressure-treatment facility procurement managers, EPA regulatory affairs consultants, and architectural coatings formulators. Secondary validation drew from EPA Office of Pesticide Programs registration databases, ECHA REACH authorization timelines, SEC filings of treated wood service providers, and American Wood Protection Association technical standards. Bottom-up volume estimates from individual treater capacity were triangulated against top-down construction sector lumber demand projections.
Sensitivity analysis around copper price volatility and ECHA authorization timeline scenarios frames the forecast uncertainty. The analytical framework segments by product type, application, and end-use across the projection horizon, with additional granularity on EPA label tier and certification depth. CAGRs were derived from segment-level volume trajectories weighted by copper-to-azole ratio shifts. Key inputs include housing start correlations for residential decking demand and utility pole replacement schedules from electric transmission infrastructure databases.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in EPA re-registration pacing or ECHA sunset date acceleration would warrant model refresh. Forecasts reflect construction sector cyclicality and biocide substitution dynamics without claiming predictive precision on copper commodity swings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Plates and Sheet Coils Market
Metals
Bearing Steel Market
Metals
Copper and Brass Flat Products Market
Metals
Qatar Metalworking Market
Metals
Europe Aluminium Powder Market
Metals
Stainless Steel Market
Metals
China Copper Market
Metals
Rhodium Market
Metals
Global Copper Cathode Market
Metals
Nickel Oxide Target Market
Metals
Global Brass Rods Market
Metals
Cold Drawn Wire Market
Metals
Steel Ingots Market
Metals
Global Galvanized Steel Wire Market
Metals
Tin Chloride Market
Metals
Powder Metallurgy Market