
 Ferrochrome Market | 2026-2036
Ferrochrome Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrochrome Market Intelligence
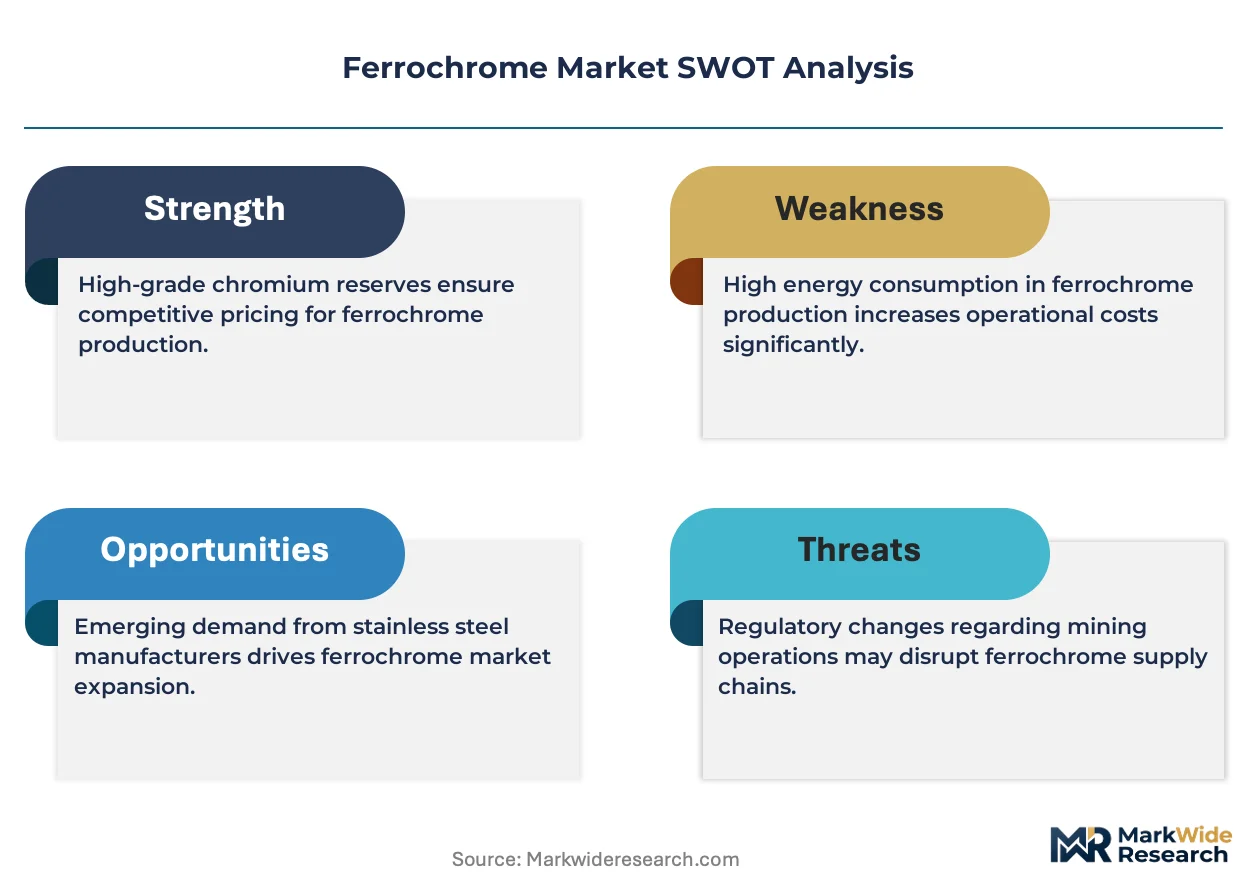
South African ferrochrome furnace capacity is decoupling from Chinese stainless steel expansion, creating a supply-demand geography mismatch. Glencore International AG leverages its integrated chromite-to-alloy footprint across southern Africa to sustain export volumes. Tata Steel Limited anchors Indian domestic ferrochrome consumption through captive stainless melt shops. Eurasian Resources Group competes on Kazakhstan-origin charge chrome shipments into European electric arc furnaces.
Ferrochrome is an iron-chromium alloy typically containing 50-70% chromium by weight, produced via carbothermic reduction of chromite ore in submerged arc furnaces at temperatures exceeding 1700°C, primarily to impart corrosion resistance and hardness in stainless steel formulations. High carbon ferrochrome dominates volume flows into austenitic stainless grades, while low carbon ferrochrome commands premium pricing from specialty steelmakers seeking precise carbon control. Charge chrome occupies the cost-sensitive bulk segment, with submerged arc furnace technology leading production economics across major smelter complexes.
South Africa's Department of Mineral Resources and Energy, China's Ministry of Ecology and Environment, and the EU's REACH framework collectively shape ore export licensing, emission intensity benchmarks, and chromium compound registration requirements for market access. South32 Limited and Samancor Chrome navigate these overlapping compliance layers through furnace upgrades and energy mix diversification. Stakeholders must monitor carbon border adjustment mechanisms and power purchase agreement structures to preserve margin visibility across the ferrochrome value chain.
Market Dynamics
China's dual carbon goals and emission caps at smelters are forcing a recalibration of ferrochrome procurement specifications, tightening feedstock requirements while South African furnace capacity struggles to align with Asian stainless steel mill demand patterns.
Growth Catalysts
- Stainless steel mill expansion:Asia-Pacific alloy procurement volumes continue rising as new melt shop capacity comes online in India and Southeast Asia, sustaining ferrochrome consumption growth.
- REACH framework compliance:European chromium compound registration requirements are standardizing quality benchmarks, creating preference premiums for certified alloy suppliers meeting ECHA specifications.
- Submerged arc furnace upgrades:Energy efficiency retrofits at Bushveld Complex smelters are lowering carbon intensity per ton of high carbon ferrochrome produced.
Market Restraints
- Chromite ore supply concentration:South Africa's Bushveld Complex hosts the bulk of economically viable reserves, exposing buyers to single- geography disruption risks from power grid instability or export licensing changes.
- Carbothermic reduction energy intensity:Furnace operations exceeding 1700°C require baseload power contracts that face escalating cost pressure from national utility tariff restructures.
- Scrap-based stainless production:Electric arc furnace operators in Europe and North America are raising stainless scrap charge ratios, compressing primary ferrochrome unit demand in mature markets.
Strategic Opportunities
- Indian stainless steel self-sufficiency:Domestic melt shop expansion under PLI scheme incentives is creating captive ferrochrome demand that local producers can serve with reduced logistics costs versus imports.
- Low carbon ferrochrome premium capture:Specialty steelmakers seeking precise carbon control in aerospace and medical grade formulations are paying substantial markups over high carbon grades.
- Renewable power purchase agreements:Smelters securing solar and wind PPAs are positioning alloy output for EU carbon border adjustment mechanism compliance ahead of full implementation.
Industry Challenges
- Pyrometallurgical engineering talent scarcity:Submerged arc furnace design and operation expertise is concentrating among retiring specialists, constraining new smelter commissioning timelines.
- Emission monitoring system integration:Retrofitting continuous emissions monitoring equipment at legacy furnace complexes requires extended shutdown windows that compress annual output volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrochrome Market |
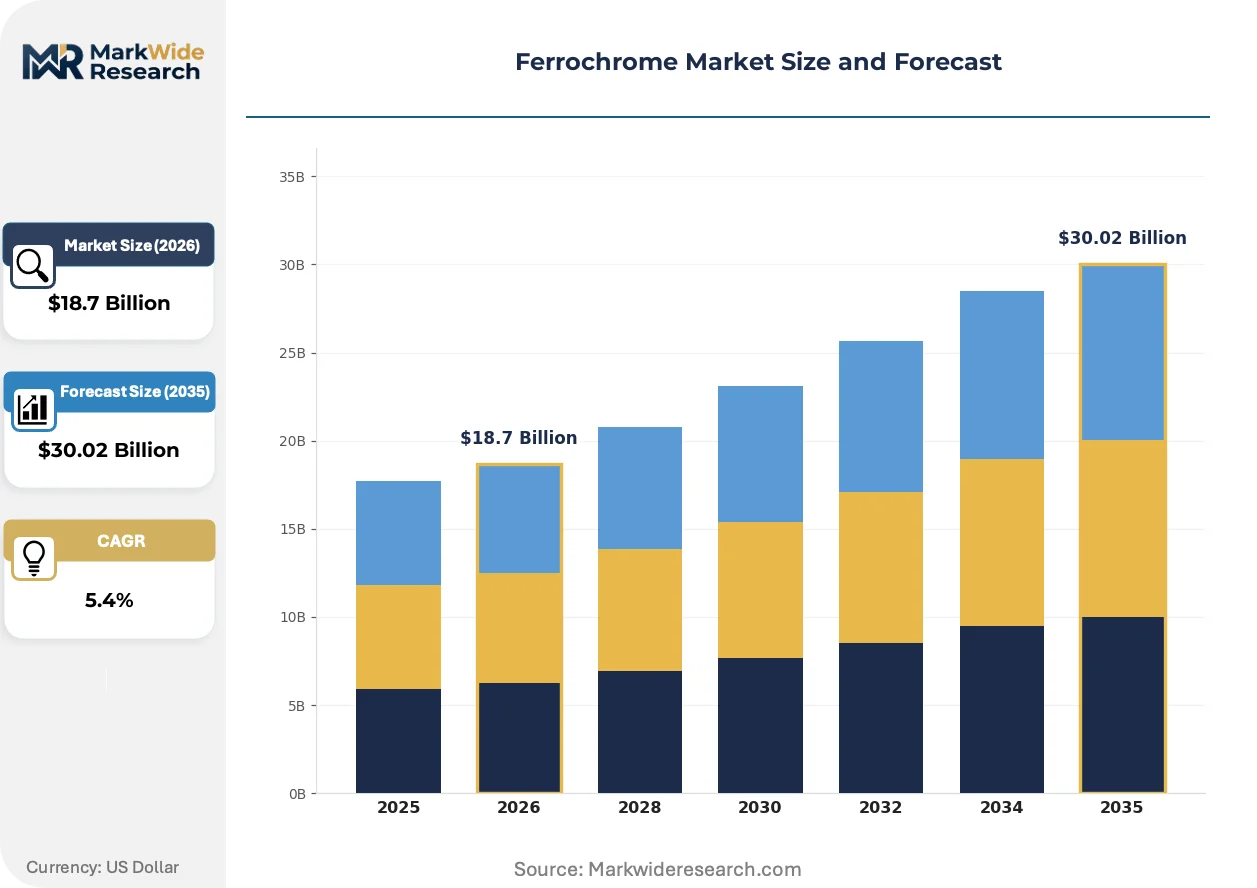
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Carbon Ferrochrome, Low Carbon Ferrochrome, Medium Carbon Ferrochrome, Charge Chrome Application: Stainless Steel, Carbon Steel, Ferroalloys Manufacturing, Foundry Castings End User Industry: Steel Producers, Metallurgical Plants, Foundries, Alloy Producers Technology: Electric Arc Furnace, Blast Furnace, Submerged Arc Furnace, Rotary Kiln |
| Companies Covered | South32 Limited, Tata Steel Limited, Glencore International AG, Assmang Proprietary Limited, Hernic Ferrochrome, Eurasian Resources Group, Outokumpu Oyj, Eramet SA, Samancor Chrome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrochrome Market Strategic Shifts & Innovations
Digital process control systems and alternative reduction technologies are reshaping ferrochrome production economics, while regulatory carbon accounting requirements are redefining competitive positioning across the alloy value chain.
Closed furnace gas cleaning and energy recovery systems are integrating waste heat capture into smelter operations. South African producers adopting these retrofits are reducing grid electricity draw per ton of alloy output. The technology is integrating carbon intensity reduction with operational cost compression, enabling suppliers to meet emerging buyer ESG screening criteria.
China's Ministry of Ecology and Environment emission caps are tightening particulate matter and sulfur dioxide limits at chromite processing facilities. Smelters in Inner Mongolia and Shanxi provinces face accelerated compliance deadlines. High carbon ferrochrome exports from non-compliant producers are encountering heightened inspection protocols at port customs.
Long-term offtake contracting is displacing spot market procurement for major stainless steel mills. Japanese and South Korean buyers are locking in multi-year alloy supply agreements with fixed volume floors. This pattern is most visible in austenitic grade production, where mills prioritize feedstock security over price arbitrage opportunities.
Ferrochrome Market Segmentation
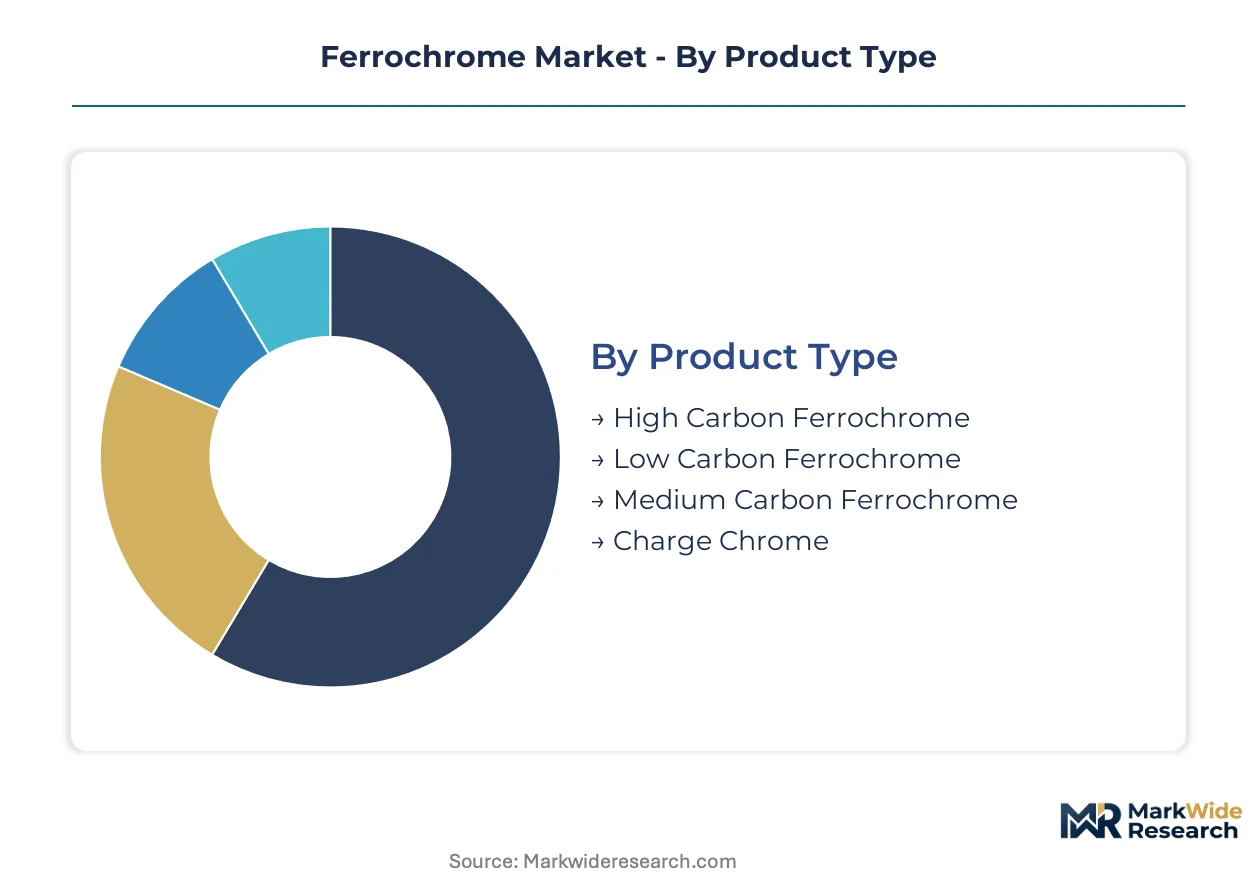
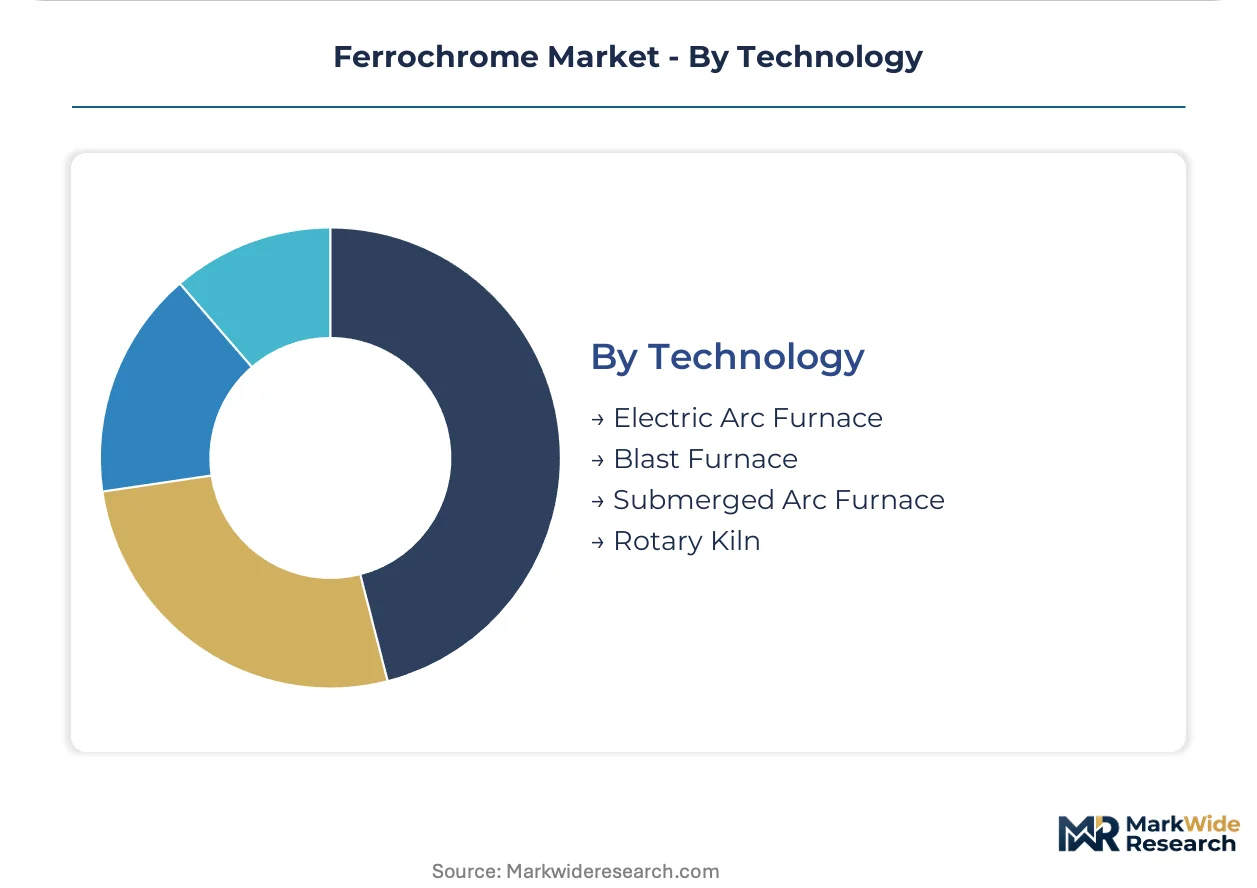
Ferrochrome segmentation reveals how alloy chemistry, steel grade requirements, and furnace technology interlock to determine procurement patterns. Stainless steel mills specify carbon content thresholds that cascade through product type selection and smelter technology choices.
Product Type:
Carbon control precision separates commodity-grade from specialty-grade ferrochrome offerings across this spectrum.
- High Carbon Ferrochrome:Contains 6-8% carbon by weight, produced via submerged arc furnace reduction of chromite ore with metallurgical coke. Demand concentrates in austenitic stainless steel mills across India and China, where cost efficiency outweighs carbon content flexibility. Eskom tariff volatility in South Africa directly compresses margins for high carbon producers dependent on grid power.
- Low Carbon Ferrochrome:Restricts carbon to 0.03-0.15% through silicon reduction or vacuum processing, commanding substantial premiums from aerospace and medical-grade stainless formulators. Japanese specialty steelmakers at Nippon Steel and JFE Steel specify ultra-low carbon grades for nuclear applications, with procurement locked in multi-year offtake agreements.
- Medium Carbon Ferrochrome:Bridges the gap at 1-4% carbon content, serving tool steel and high-strength alloy applications where moderate carbon tolerance exists.
- Charge Chrome:Lowest-purity bulk grade with 50-55% chromium, shipped primarily to European electric arc furnace operators seeking cost-optimized melt shop charge mixes.
Leading the category by volume: High Carbon Ferrochrome. Expanding most quickly: Low Carbon Ferrochrome.
Application:
End-use differentiation tracks corrosion resistance requirements against mechanical property specifications.
- Stainless Steel:Absorbs approximately 75% of global ferrochrome output, with austenitic grades (300-series) requiring 18-20% chromium content sourced primarily through high carbon ferrochrome addition. Indonesian integrated stainless complexes at Morowali and Weda Bay are accelerating melt shop commissioning, tightening regional alloy procurement competition.
- Carbon Steel:Incorporates ferrochrome for hardenability and wear resistance in automotive components and railway infrastructure, with specification tolerance for higher carbon grades reducing unit economics pressure.
- Ferroalloys Manufacturing:Intermediate blending operations in Kazakhstan and India combine ferrochrome with ferromanganese and ferrosilicon to produce complex master alloys for specialty foundries.
- Foundry Castings:Precision casting operations for pump housings and valve components specify low carbon ferrochrome to prevent carbide precipitation in critical service environments.
Dominant application: Stainless Steel. Steepest expansion trajectory: Foundry Castings for energy sector components.
End User Industry:
Procurement sophistication varies sharply between integrated steelmakers and merchant alloy consumers.
- Steel Producers:Integrated stainless mills from Baosteel to Outokumpu operate captive ferrochrome blending facilities or long-term supply contracts with Bushveld Complex smelters, prioritizing feedstock security over spot price arbitrage.
- Metallurgical Plants:Merchant processors in Turkey and Iran toll-convert chromite concentrate into ferrochrome for re-export, exposed to chromite ore price volatility and energy cost differentials.
- Foundries:Small-batch consumers in Italy and Germany source packaged ferrochrome through distributors, with REACH registration requirements filtering supplier eligibility.
- Alloy Producers:Master alloy specialists in Austria and the United States blend ferrochrome with nickel and molybdenum for superalloy feedstock serving aerospace turbine manufacturers.
Category leader by procurement volume: Steel Producers. Gaining share fastest: Alloy Producers for aerospace supply chains.
Technology:
Energy intensity and emission profiles differentiate furnace technologies under tightening environmental compliance.
- Submerged Arc Furnace:Dominates high carbon ferrochrome production through continuous operation at 1700-1800°C with direct current or alternating current electrode configurations. South African producers at Rustenburg and Lydenburg deploy closed furnace designs with gas cleaning systems to meet MEE-equivalent emission benchmarks for export eligibility.
- Electric Arc Furnace:Flexible batch processing enables low carbon ferrochrome production through exothermic reduction with silicon, with European installations prioritizing scrap-based charge mixes to reduce Scope 3 emissions.
- Blast Furnace:Limited legacy installations in China and Russia produce charge chrome at lower capital intensity but higher coke consumption rates, facing accelerated closure timelines under dual carbon compliance deadlines.
- Rotary Kiln:Pre-reduction technology for chromite pelletizing reduces submerged arc furnace power consumption, with pilot installations in Finland and South Africa testing renewable hydrogen integration.
Technology leader by installed capacity: Submerged Arc Furnace. Climbing the fastest: Rotary Kiln pre-reduction with alternative reductant trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bushveld Complex in South Africa anchors global chromite reserves, yet furnace capacity dispersion across multiple jurisdictions creates procurement complexity for stainless steel mills.
China
Inner Mongolia and Shanxi provinces host submerged arc furnace clusters serving Baosteel and Tsingshan stainless operations. The Ministry of Ecology and Environment emission caps are forcing smelter consolidation. Rizhao and Ningbo ports handle import inspections for South African high carbon ferrochrome shipments.
India
Odisha and Karnataka states concentrate domestic ferrochrome output under PLI scheme incentives for stainless steel self-sufficiency. The Bureau of Indian Standards certifies alloy grades for melt shop integration. Jajpur and Bhadrak industrial corridors attract captive smelter investments from integrated steelmakers.
South Africa
Rustenburg and Lydenburg smelter complexes in the Bushveld region export charge chrome and high carbon grades. The Department of Mineral Resources and Energy regulates ore export licensing and power purchase agreements. Eskom tariff restructures threaten furnace economics at Witbank and Middelburg operations.
Finland
Tornio harbor facilitates Outokumpu's integrated chromite-to-stainless production chain. The EU REACH framework mandates chromium compound registration for alloy market access. Kemi mine and ferrochrome works represent Europe's only significant primary production cluster.
Kazakhstan
Aktobe and Aksu smelters in the Eurasian Resources Group network ship charge chrome to European electric arc furnace operators. National utility tariff structures favor export-oriented production economics. Pavlodar region concentrates chromite mining and alloy processing capacity.
Ferrochrome Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue renewable power integration and carbon-certified alloy positioning. The vendor base concentrates among integrated mining-smelting groups and captive stainless steel suppliers. Three archetypes dominate: chromite-reserve-backed integrated operators, stainless-mill-captive ferrochrome producers, and merchant alloy specialists serving spot markets. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as mills prioritize feedstock security.
Among South Africa-based integrated operators, Glencore International AG and South32 Limited exemplify the reserve-backed archetype with Bushveld Complex chromite control. Samancor Chrome occupies a position within this tier through furnace concentration at Rustenburg and Lydenburg. Tata Steel Limited represents the captive-producer model, anchoring Indian domestic consumption through in-house melt shop integration. Eurasian Resources Group exemplifies the merchant-specialist vector with Kazakhstan-origin shipments into European markets.
| Leading Market Players |
|---|
| South32 Limited |
| Tata Steel Limited |
| Glencore International AG |
| Assmang Proprietary Limited |
| Hernic Ferrochrome |
| Eurasian Resources Group |
| Outokumpu Oyj |
| Eramet SA |
| Samancor Chrome |
| Others |
Cost & Logistics Intelligence
China's Ministry of Ecology and Environment emission caps gate qualified supply access for South African smelters seeking premium-tier entry into Asian stainless steel procurement channels. Furnace operators without continuous emissions monitoring retrofits face exclusion from long-term offtake negotiations with Japanese and South Korean mills, compressing margin visibility for non-compliant producers while certified suppliers capture contract premiums.
Pricing Analysis
Long-term offtake agreements bundle freight optimization and quality certification guarantees that spot market transactions exclude. Pricing stratifies across premium, standard, and economy tiers based on carbon content precision and REACH registration status. Cost compression in high carbon grades is intensifying because Eskom tariff restructures at Bushveld Complex smelters pass through to export quotations. Merchant alloy buyers in European electric arc furnace operations exhibit highest price sensitivity; aerospace-grade low carbon purchasers show lowest.
Supply Chain Analysis
Chromite ore supply rests on South African Bushveld Complex mining concessions, Kazakhstani deposits at Aktobe, and Finnish Kemi underground operations. Metallurgical coke for carbothermic reduction draws from Australian and Chinese coking coal conversion. Single-source vulnerability concentrates in South African furnace capacity exposed to national utility load-shedding events. Distribution runs through Rotterdam and Singapore bulk terminals to stainless steel melt shops at Ningbo, Jajpur, and Tornio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrochrome market structure favors consolidation plays as emission compliance costs force sub-scale smelter closures across Inner Mongolia and Shanxi provinces. Surviving producers will capture displaced volume through certified supply positioning.
For Market Incumbents: To counter pyrometallurgical engineering talent scarcity constraining furnace commissioning timelines, secure captive chromite reserves through lease extensions at Bushveld Complex deposits and accelerate submerged arc furnace closed-design retrofits ahead of EU carbon border adjustment mechanism full implementation. Backward integration into renewable power purchase agreements represents the critical margin defense lever against Eskom tariff volatility. For New Entrants and Emerging Players: Rotary kiln pre-reduction technology with hydrogen integration trials offers entry pathway into low-carbon ferrochrome segments where incumbent capital intensity creates white space. Target Indian domestic stainless steel self-sufficiency initiatives under PLI scheme incentives, where logistics cost advantages versus South African imports create penetrable demand. Pursue toll-smelting partnerships with Odisha-based chromite concentrate processors to bypass greenfield furnace construction barriers. For Investors and Strategic Acquirers: Multi-year offtake contracting volume floors at Japanese specialty steelmakers is the leading indicator that premium-tier low carbon ferrochrome supply will tighten against aerospace and medical-grade demand expansion. Position acquisition screening around Bushveld Complex smelters with existing closed furnace gas cleaning infrastructure and renewable power offtake arrangements. Watch Inner Mongolia smelter consolidation announcements as signal for Chinese import dependency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Closed Furnace Retrofit Program | Enables MEE-equivalent emission benchmarks for Chinese market access at Rustenburg and Lydenburg operations. |
| Renewable Power Purchase Agreement | Positions alloy output for EU carbon border adjustment mechanism compliance ahead of full implementation. |
| Chromite Reserve Lease Extension | Secures feedstock security for integrated mining-smelting groups against Bushveld Complex licensing competition. |
| Long-term Offtake Contracting | Locks volume floors with Baosteel and Tsingshan stainless operations displacing spot market procurement. |
| Low Carbon Grade Capacity Addition | Captures premium pricing from Nippon Steel and JFE Steel nuclear application specifications. |
Research Approach
Document review covered trade flow databases, ECHA REACH registration filings, and South African Department of Mineral Resources and Energy licensing records, complemented by interviews with submerged arc furnace operations managers, stainless steel procurement leads at integrated mills, chromite mining concession holders, and renewable power project developers. Secondary validation drew from customs export statistics, Eskom tariff restructuring announcements, and EU carbon border adjustment mechanism draft implementing acts. Bottom-up smelter capacity modeling and top-down stainless steel demand projection triangulated volume estimates.
Cross-referencing historical production data against expert panel input on furnace commissioning timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include carbon content tier, end-use application chemistry requirements, furnace technology type, and regional regulatory cluster. CAGRs were derived from alloy demand intensity coefficients applied to stainless steel melt shop capacity expansion pipelines, with chromite ore grade degradation curves and power cost trajectory assumptions as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Chinese dual carbon compliance deadlines or extended South African utility load-shedding duration. Projections reflect assumptions on submerged arc furnace energy efficiency improvement rates and REACH framework enforcement consistency. A small set of named triggers warrants ongoing watch: Bushveld Complex ore export licensing changes, Indonesian integrated stainless complex commissioning pace, and EU carbon border adjustment mechanism scope expansion to ferroalloys.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Shipbuilding Steel Plate Market
Metals
Metal Recycling Market
Metals
Steel Drums and Ibcs Market
Metals
US Metal Fabrication Market
Metals
Europe Aluminium Powder Market
Metals
Metal Coil Lamination Market
Metals
Hafnium Foil Market
Metals
Metallurgical Coal Market
Metals
Russia Metal Fabrication Market
Metals
Zirconium Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Steel Sheet for Home Appliances Market
Metals
Transition Metals Market
Metals
Heat-Treated Steel Plates Market
Metals
Aluminum Fluoride Market
Metals
Global Tool Steel Market