
 Global Ultra-Low Alpha Metal Market | 2026-2036
Global Ultra-Low Alpha Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra-Low Alpha Metal Market Foresight
Defense contractors are reorganizing procurement priorities for radiation-hardened electronic systems. Indium Corporation leverages its vertical integration from mining to refined metal products. Honeywell International Inc. anchors aerospace supply chains with certified ultra-low alpha titanium and nickel alloys. Mitsubishi Materials Corporation specializes in high-purity cobalt and aluminum for semiconductor packaging applications.
Ultra-low alpha metals are engineered materials with alpha particle emission rates below 0.002 counts per hour per square centimeter, typically achieved through electrorefining and zone melting purification. These metals prevent soft errors in integrated circuits by eliminating radioactive contaminants such as uranium and thorium. Semiconductor fabrication applications command the largest share of demand as foundries push below three-nanometer process nodes. Aerospace manufacturing represents the fastest-growing application segment as satellite constellations multiply and radiation tolerance requirements stiffen. Precision optics maintains stable demand with concentrated margin pools in EUV lithography mirror substrates.
FDA scrutiny of medical device radiation exposure intersects with EPA hazardous substance reporting for mined ores containing trace actinides. Japan's METI enforces JIS standards for electronic-grade materials that de facto govern Asian supply specifications. Stakeholders must monitor how EU Green Deal material traceability rules and China's dual carbon goals reshape smelter energy sourcing and purification cost structures.
Market Dynamics
Semiconductor foundries below three-nanometer nodes now mandate sub-0.002 cph/cm² alpha emission rates, forcing purification technology upgrades across the entire supply base. This technical threshold is concentrating procurement among electrorefining specialists capable of zone melting at industrial scale.
Growth Catalysts
- EU REACH and RoHS frameworks:Tightening purity disclosure requirements for critical materials are accelerating certification investments by European semiconductor packaging houses.
- Taiwan's Hsinchu Science Park cluster:Leading foundries operating in this concentrated geography are expanding procurement volumes for advanced packaging nodes.
- Radiation-hardened aerospace electronics:Satellite constellation multiplication is stiffening radiation tolerance requirements across defense and commercial spacecraft programs.
Market Restraints
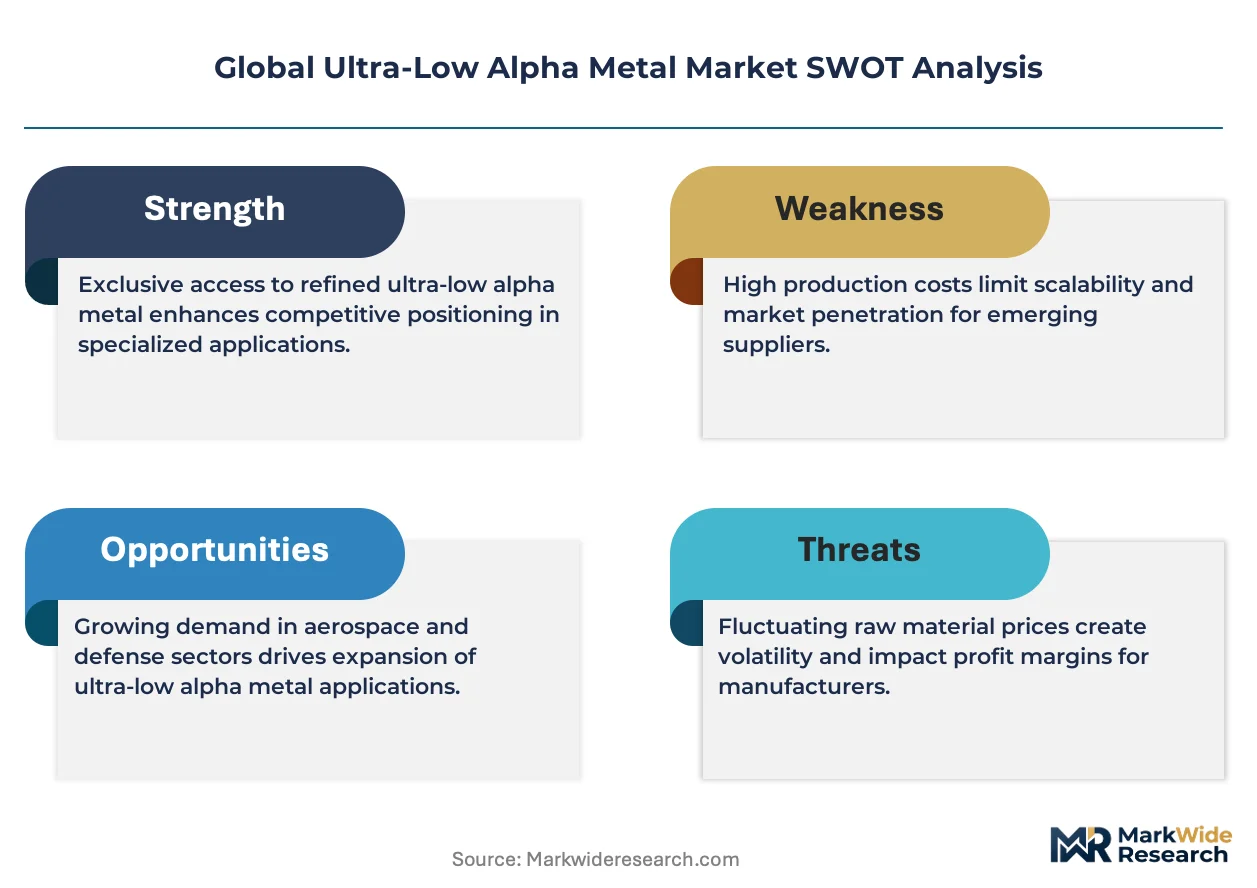
- Energy-intensive zone melting:Electrorefining purification consumes substantial electricity, exposing cost structures to volatile industrial power tariffs in smelter locations.
- Upstream ore concentration:Mined cobalt and indium deposits with naturally low uranium-thorium contamination are geographically concentrated, creating feedstock access bottlenecks.
- Substitution by synthetic substrates:Advanced ceramic interposers and carbon-based thermal management materials are capturing select packaging applications from metallic solutions.
Strategic Opportunities
- India's semiconductor fabrication incentives:The country's PLI scheme for electronic manufacturing is attracting greenfield investments in materials purification capacity.
- EUV lithography mirror substrates:Precision optics for next-generation lithography systems represents an emerging application with concentrated margin pools.
- Dual carbon goals in China:Smelter energy sourcing requirements are creating competitive openings for producers with verified low-carbon purification processes.
Industry Challenges
- Certification timeline compression:JIS standards enforcement by Japan's METI and emerging FDA medical device scrutiny are extending qualification cycles for new material grades.
- Specialized metallurgical talent scarcity:Zone melting process engineers and alpha spectroscopy technicians command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra-Low Alpha Metal Market |
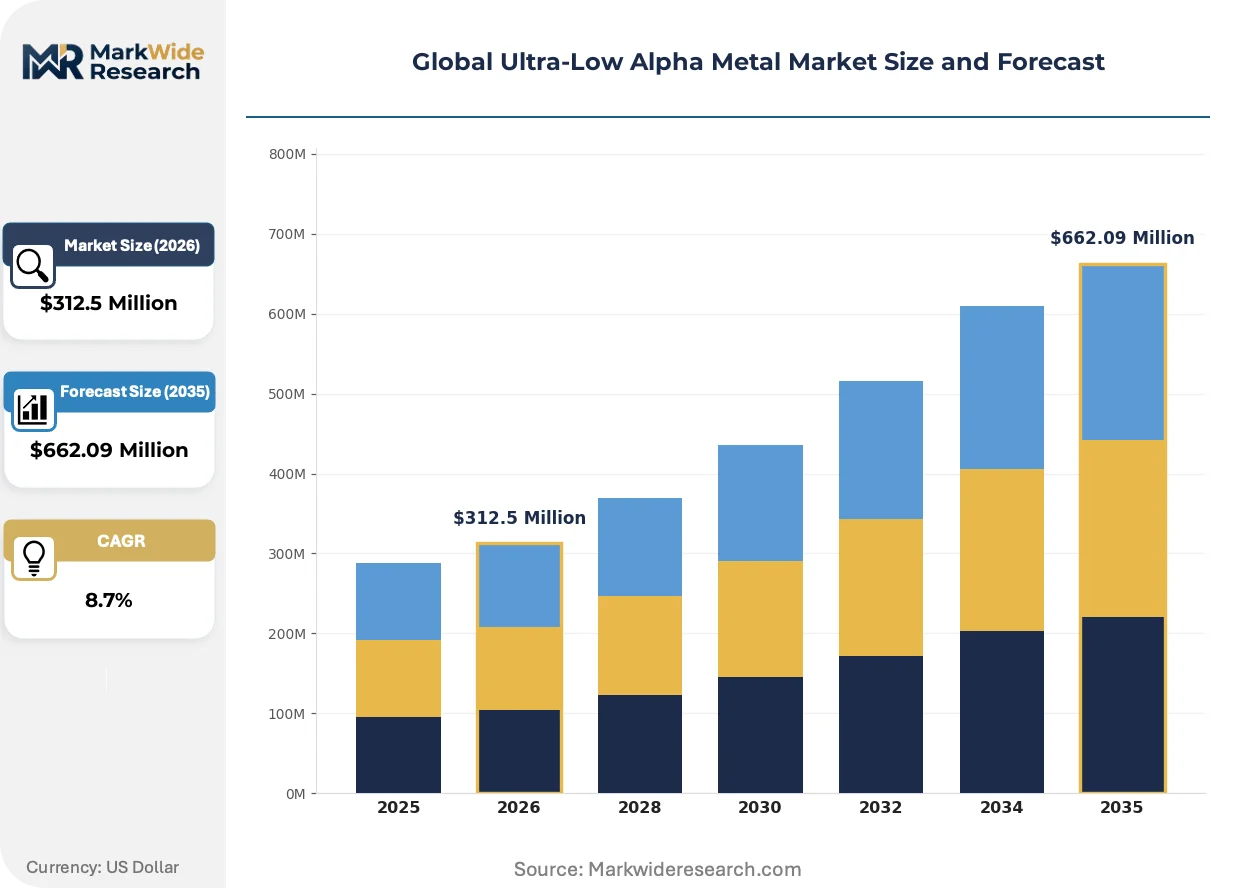
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Aluminum, Nickel, Cobalt, Stainless Steel, Titanium Application: Semiconductor Fabrication, Aerospace Manufacturing, Scientific Instrumentation, Defense Systems, Precision Optics End User: Microelectronics Manufacturers, Aerospace Engineers, Defense Contractors, Laboratory Equipment Firms, Optical Device Makers Form: Sheets, Plates, Foils, Bars, Rods |
| Companies Covered | Indium Corporation, Alpha Assembly Solutions, Honeywell International Inc., STANNOL GmbH, AIM Metals & Alloys LP, Teck Resources Limited, DUKSAN Hi-Metal Co, MacDermid Alpha Electronics Solutions, Mitsubishi Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra-Low Alpha Metal Market Shifts & Advancements
Purification technology and regulatory traceability requirements are converging to reshape competitive capabilities across the ultra-low alpha metal value chain. Three distinct movements are altering how producers defend position and how buyers evaluate supply security.
Multi-stage zone refining with in-situ alpha particle monitoring is decomposing traditional batch-based purification economics. Leading semiconductor foundries in Taiwan and South Korea are adopting continuous-zone systems that cut residence time by half while tightening emission consistency. This technology is compressing margin structures for electrorefining-only competitors unable to fund capital upgrades.
EU Green Deal material traceability rules are mandating blockchain-verified supply chain documentation from mine to refined product. German and French aerospace primes now require actinide-content certificates at every processing stage. Packaging houses serving European medical device OEMs are responding by consolidating supplier lists to vertically integrated miners with captive spectroscopy laboratories.
Defense contractors are unbundling after-sales inventory management from long-term purchase agreements. Radiation-hardened system builders now operate vendor-managed consignment programs at their subcontractor facilities. This pattern is most visible in US satellite manufacturing clusters, where prime contractors transfer alpha-certification liability downstream while retaining specification control.
Global Ultra-Low Alpha Metal Market Segmentation
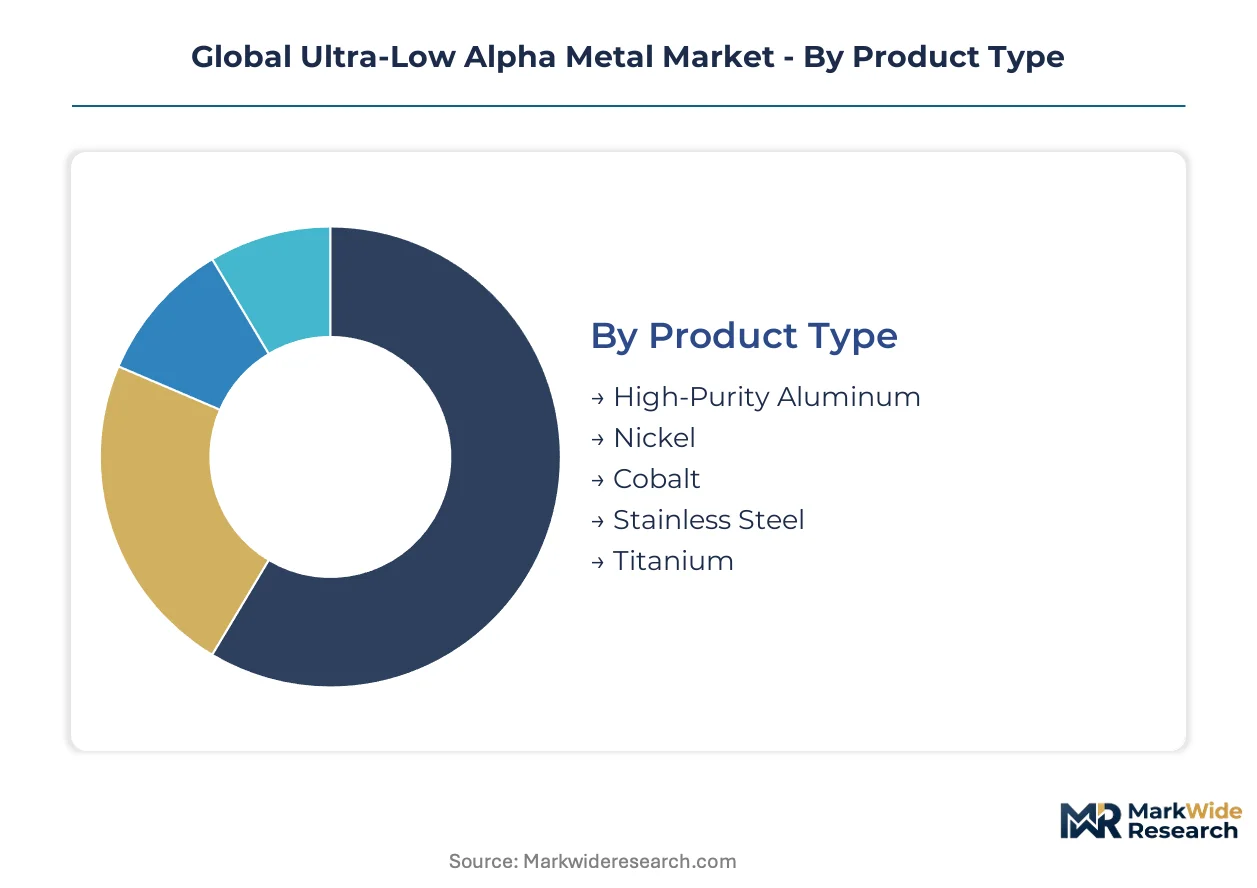
Ultra-low alpha metal procurement patterns diverge sharply across product grades and end-use specifications. Foundries prioritize alpha emission thresholds over base metal cost, while aerospace buyers weight mechanical properties against radiation tolerance.
Product Type:
Margin pools concentrate in cobalt and nickel purification where electrorefining complexity creates specialist moats.
- High-Purity Aluminum:Zone-refined grades achieve sub-0.002 cph/cm² emission rates through fractional crystallization. Taiwan packaging houses consume the majority of output for flip-chip interconnects as three-nanometer node ramp accelerates.
- Nickel:Electrorefined cathodes with actinide separation command premium pricing in EU medical device supply chains. German aerospace primes now require blockchain-verified contamination certificates for every processing stage.
- Cobalt:High-purity cathodes for solder bump metallization.
- Stainless Steel:Low-emission grades for vacuum chamber components.
- Titanium:Alpha-reduced sponge for satellite structural elements.
The dominant share belongs to High-Purity Aluminum, while Nickel is closing the gap fastest.
Application:
Application demand splits between process-node-driven semiconductor procurement and mission-specification aerospace programs.
- Semiconductor Fabrication:Advanced packaging nodes below three nanometers mandate ultra-low alpha solder alloys and interconnect metals. Hsinchu Science Park foundries anchor global consumption volume with concentrated procurement from electrorefining specialists.
- Aerospace Manufacturing:Satellite constellation multiplication stiffens radiation tolerance requirements across commercial and defense spacecraft. US prime contractors now operate vendor-managed consignment programs at subcontractor facilities.
- Scientific Instrumentation:Detector-grade materials for particle physics research.
- Defense Systems:Radiation-hardened electronics for strategic platforms.
- Precision Optics:EUV lithography mirror substrates represent an emerging niche with concentrated margin pools.
Semiconductor Fabrication retains volume leadership, though Aerospace Manufacturing is expanding most quickly.
End User:
Customer concentration varies by certification burden and inventory liability structures.
- Microelectronics Manufacturers:Foundries and OSATs with captive packaging operations. Taiwan and South Korea facilities drive specification tightening through continuous-zone refining adoption.
- Aerospace Engineers:Prime contractors transferring alpha-certification liability downstream while retaining specification control.
- Defense Contractors:Radiation-hardened system builders with long-term purchase agreements.
- Laboratory Equipment Firms:Scientific instrument OEMs with batch procurement patterns.
- Optical Device Makers:EUV lithography system suppliers with emerging material requirements.
Microelectronics Manufacturers command the dominant procurement volume, with Aerospace Engineers gaining share fastest.
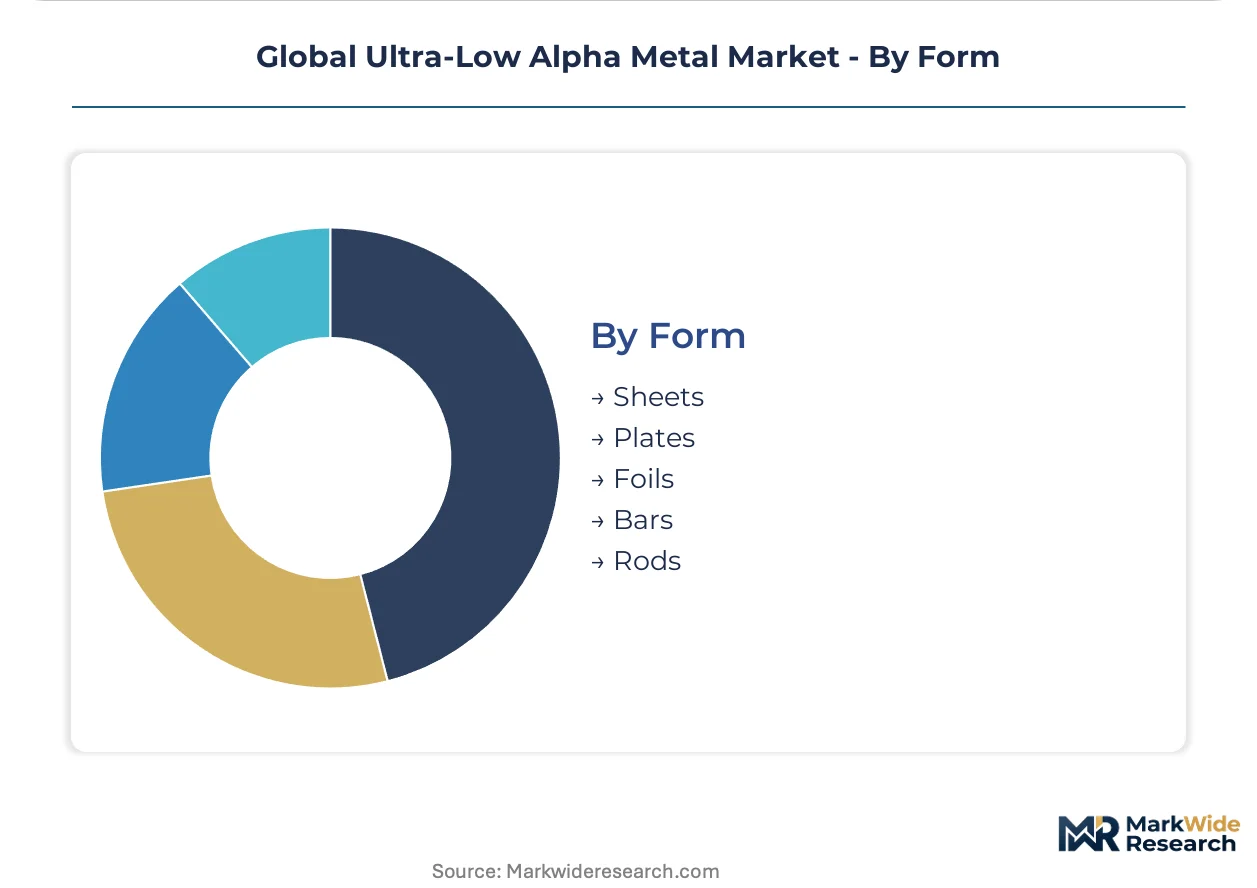
Form:
Form selection tracks downstream processing economics and scrap recovery rates.
- Sheets:Vacuum chamber liners and thermal management plates for semiconductor equipment. Japanese METI JIS standards govern thickness tolerances and surface alpha emission consistency.
- Foils:Ultra-thin gage for flip-chip underfill and precision shielding. South Korean packaging houses specify rolled products with verified grain structure for anisotropic thermal expansion matching.
- Plates:Structural substrates for optical bench assemblies.
- Bars:Feedstock for precision machining of connector components.
- Rods:Starting stock for wire drawing and fastener production.
Sheets hold the dominant position, while Foils are climbing the fastest on advanced packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports zone-refined cobalt and nickel to Taiwan's Hsinchu Science Park foundries, while German electrorefiners supply aerospace-grade titanium to US satellite manufacturers. This trade corridor concentrates procurement power in East Asian semiconductor clusters and North American defense supply chains.
United States
Defense contractors in Colorado and California drive radiation-hardened electronics procurement for satellite constellations. The FDA scrutinizes medical device radiation exposure alongside EPA hazardous substance reporting for mined ores. Prime contractors operate vendor-managed consignment programs at subcontractor facilities across the Southwest.
Germany
Aerospace primes in Bavaria and Baden-Württemberg mandate blockchain-verified actinide-content certificates at every processing stage. The EU Green Deal material traceability rules reshape smelter energy sourcing requirements. Stuttgart-based packaging houses consolidate supplier lists to vertically integrated miners with captive spectroscopy laboratories.
Japan
Tokyo and Osaka anchor electrorefining capacity for high-purity cobalt and aluminum solder alloys. METI enforces JIS standards for electronic-grade materials that de facto govern Asian supply specifications. Kyushu-based refiners supply continuous-zone systems to South Korean packaging houses.
Taiwan
Hsinchu Science Park foundries anchor global consumption volume for sub-0.002 cph/cm² alpha emission metals. The island's semiconductor fabrication incentives attract greenfield investments in materials purification capacity. Leading foundries adopt continuous-zone refining systems that cut residence time by half.
South Korea
Packaging houses in Suwon and Pyeongtaek specify rolled foil products with verified grain structure for anisotropic thermal expansion matching. The country's electronic manufacturing base tightens specification thresholds through direct equipment partnerships with Japanese refiners. Seoul-based OSATs drive adoption of in-situ alpha particle monitoring systems.
Global Ultra-Low Alpha Metal Market Competitive Landscape
Player mix skews toward vertically integrated mining-to-metal specialists and electrorefining-focused purification houses. The market structure concentrates procurement relationships among electrorefining specialists capable of zone melting at industrial scale. Three archetypes dominate: captive miners with spectroscopy laboratories, independent electrorefiners serving multiple foundries, and aerospace-certified alloy producers. Competitive moves center on backward integration into ore concentration assets and technology licensing for continuous-zone refining systems.
Within the vertically integrated tier, Indium Corporation and Mitsubishi Materials Corporation exemplify miners with captive purification capabilities spanning from ore concentration to refined metal products. Honeywell International Inc. occupies a position among aerospace-certified alloy producers serving radiation-hardened system builders. These three anchors represent distinct strategic postures: mining-backed supply security, semiconductor-focused electrorefining scale, and defense-aerospace certification depth.
| Leading Market Players |
|---|
| Indium Corporation |
| Alpha Assembly Solutions |
| Honeywell International Inc. |
| STANNOL GmbH |
| AIM Metals & Alloys LP |
| Teck Resources Limited |
| DUKSAN Hi-Metal Co |
| MacDermid Alpha Electronics Solutions |
| Mitsubishi Materials Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day qualification cycles for new ultra-low alpha metal grades compress inventory turns and amplify pricing power for electrorefining specialists with captive spectroscopy laboratories. This lead-time rigidity concentrates procurement leverage among zone-melting operators in Japan and Taiwan while forcing packaging houses to absorb premium pricing for certified supply security.
Pricing Analysis
Three-nanometer node certification premiums over legacy-node grades exceed prior-generation differentials by substantial multiples, reflecting zone-melting capital intensity and actinide-separation yield losses. Pricing stratifies across semiconductor-grade, aerospace-certified, and medical-device tiers, with JIS compliance and FDA material master file status commanding the widest spreads. Cost compression in standard-grade aluminum runs through energy tariff volatility at Japanese smelters. Foundries below three-nanometer nodes exhibit least price sensitivity; laboratory equipment firms with batch procurement patterns are most price-sensitive.
Supply Chain Analysis
Forty-five day consignment inventory positions at Taiwan packaging houses represent the tightest working-capital configuration in the value chain, with downstream satellite manufacturers holding ninety-day safety stocks against launch-schedule risk. Supply concentrates in Japan, Taiwan, and Germany, with ore feedstock drawing from Australian cobalt deposits and Canadian indium sources. Single-source vulnerability sits with zone-melting furnace operators; only three electrorefiners maintain continuous-zone systems at industrial scale. Distribution runs through vendor-managed consignment programs at US defense subcontractor facilities and direct mill relationships with Hsinchu Science Park foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zone-melting process engineers and alpha spectroscopy technicians command compensation premiums exceeding adjacent metallurgical specialties by wide margins, constraining purification capacity expansion regardless of capital availability. This human-asset scarcity defines competitive durability across the forecast horizon.
For Market Incumbents: Secure backward integration into low-uranium-thorium ore deposits in Australia and Canada to defend feedstock access against emerging Chinese electrorefiners. Lock continuous-zone refining equipment partnerships with Kyushu-based furnace builders before capacity installation backlogs extend beyond twenty-four months. Synthetic ceramic interposers threaten substitution in thermal-management applications; deepen certification relationships with FDA and EU medical device OEMs to anchor metallic solutions in regulated segments. For New Entrants and Emerging Players: JIS fast-track certification through METI-recognized laboratory partnerships opens procurement access to South Korean OSATs seeking supplier diversification beyond Japanese incumbents. India's semiconductor PLI scheme offers the most penetrable geography for greenfield electrorefining investment, with land and power cost advantages against Japanese and Taiwanese cost bases. Target EUV lithography mirror substrate qualification as the go-to-market angle; this emerging application lacks entrenched supplier relationships and rewards rapid certification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with captive ultra-low alpha metal divisions buried within broader materials portfolios. Long-term viability hinges on purification technology licensing revenue streams rather than commodity metal exposure. Watch for inflection when continuous-zone refining patent estates consolidate through equipment-maker acquisitions, signaling margin compression for electrorefining-only operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Concentration Assets | Captive supply of low-actinide cobalt and indium feedstock insulates Japanese electrorefiners from DRC and Chinese export restrictions. |
| Continuous-Zone Refining Technology Licensing | Equipment partnerships with Kyushu furnace builders transfer process expertise to South Korean packaging houses seeking in-house purification. |
| Blockchain-Verified Supply Chain Documentation | EU Green Deal traceability mandates force German aerospace primes to consolidate supplier lists to vertically integrated miners with captive laboratories. |
| Vendor-Managed Consignment Program Expansion | US defense contractors transfer alpha-certification liability downstream while retaining specification control over Southwest satellite manufacturing clusters. |
| EUV Lithography Mirror Substrate Qualification | Precision optics for next-generation lithography systems represents an emerging niche with concentrated margin pools and limited incumbent presence. |
Research Methodology
A spread of perspectives from zone-melting process engineers, semiconductor packaging procurement directors, aerospace prime contractor metallurgists, and defense subcontractor quality managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed mining conglomerates, METI JIS standard documentation, EU REACH substance database entries, and customs records of cobalt and indium concentrate trade flows. Bottom-up demand modeling from foundry capacity announcements triangulated against top-down metal consumption intensity benchmarks.
Segmentation dimensions modeled span product type, application, end user, and form factor across the projection horizon. Metal-specific emission thresholds, purification technology generation, and regional regulatory cluster variations shaped the analytical framework. CAGRs derived from intensity-of-use coefficients applied to semiconductor fabrication capacity expansion schedules and satellite constellation deployment manifests. Forecast inputs incorporated zone-melting electricity cost trajectories and JIS certification timeline observations.
The analysis sits within stated boundaries; outcomes outside continuous-zone refining adoption rates above baseline assumptions or EU Green Deal enforcement intensity below current trajectories would require recalibration. Forecasts reflect documented assumptions regarding ore grade degradation and spectroscopy technician labor market tightness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
US and Mexico Stainless Steel Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Global Oxygen-Free Copper Market
Metals
Weathering Steel Market
Metals
Heat-Treated Steel Plates Market
Metals
Silver Nitrate Market
Metals
North America Aluminium Powder Market
Metals
Global Stretch Spring Wire Market
Metals
High Purity Tungsten Market
Metals
Nickel Market
Metals
Aluminum Welding Market
Metals
Global Bronze Market
Metals
Beryllium Copper Plate Market
Metals
Platinum Compounds Market
Metals
Flat-Rolled Stainless Steel Market
Metals
High Purity Lead Market