
 Scandium Market | 2026-2036
Scandium Market Size, Share, and Industry Trends Forecast 2026-2036
Scandium Market Intelligence
Buyer concentration in aerospace supply chains is rebalancing as tier-one airframers consolidate qualified scandium suppliers while defense primes fragment procurement across emerging domestic sources. Rio Tinto leverages its integrated aluminum operations to trial scandium co-recovery from existing bauxite processing streams. RusAL sustains captive scandium output from its Urals aluminum smelters, anchoring supply for Russian aerospace programs. NioCorp Development Ltd positions its Elk Creek project in Nebraska as a vertically integrated rare earth and scandium alternative to Chinese supply dominance.
Scandium is a transition metal with atomic number 21 that forms high-strength, corrosion-resistant aluminum alloys when added at 0.1-0.5% by weight, typically produced through molten salt electrolysis or calcium reduction of scandium fluoride. Its primary commercial purpose centers on enabling lighter structural materials for aerospace and sporting applications without sacrificing fatigue resistance. Scandium oxide commands premium pricing as the principal feedstock for metal and alloy production, while the aerospace industry vertical absorbs the majority of high-purity metal offtake despite electronics emerging as a faster-growing demand pocket for sputtering targets and solid oxide fuel cell components.
EPA oversight of rare earth processing waste streams shapes US project economics, while REACH registration requirements in Europe constrain scandium chemical imports absent full toxicity dossiers. China's MEE enforces wastewater and tailings standards on ion-adsorption clay operations that indirectly govern scandium byproduct recovery economics. Stakeholders must monitor how critical minerals list designations across Washington, Brussels, and Canberra redirect public financing toward scandium separation technology rather than raw extraction alone.
Market Dynamics
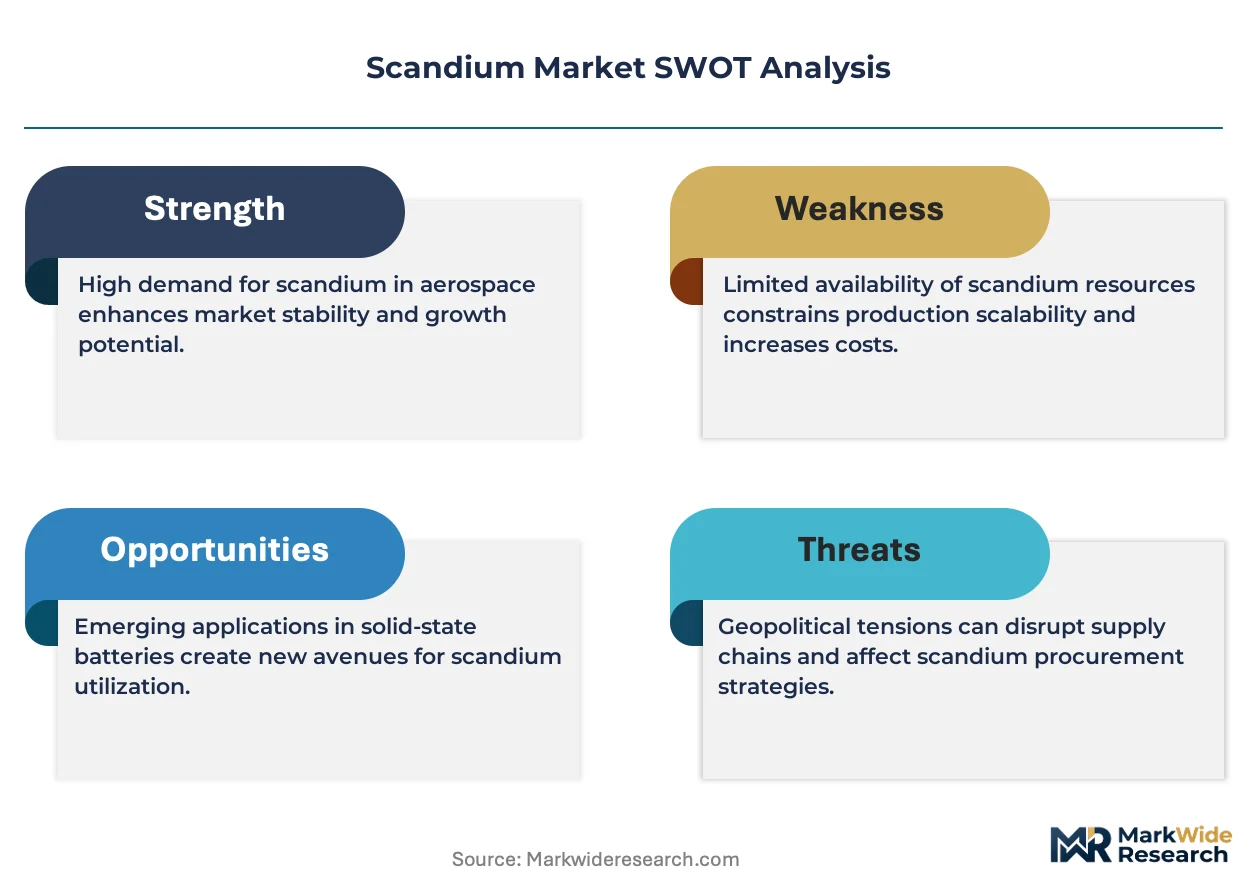
Aerospace manufacturers are consolidating scandium-aluminum alloy specifications for next-generation airframes, creating a qualification bottleneck that favors processors with existing metallurgical infrastructure over greenfield entrants.
Growth Catalysts
- GB Standard Tightening:China's evolving environmental standards for rare earth processing are accelerating investment in cleaner scandium co-recovery technologies from bauxite residue streams.
- Solid Oxide Fuel Cells:Stationary power applications for scandia-stabilized zirconia electrolytes are expanding beyond demonstration projects into commercial deployment.
- Australian Laterite Development:Capital commitments to Queensland and New South Wales resource projects are building independent supply chains outside Chinese dominance.
Market Restraints
- Scandium Fluoride Feedstock Concentration:Overreliance on Chinese refiners for high-purity scandium oxide creates supply vulnerability during export license reviews.
- Molten Salt Electrolysis Energy Intensity:The 900°C operating temperatures required for primary metal production expose processors to volatile electricity input costs.
- REACH Registration Barriers:Incomplete toxicity dossiers for scandium compounds block European chemical imports absent full ECHA compliance investment.
Strategic Opportunities
- Nebraska Vertically Integrated Development:The Elk Creek niobium-scandium-titanium resource offers North American defense-qualified supply independent of foreign processing.
- Sputtering Target Electronics:Semiconductor fabrication equipment manufacturers are qualifying scandium-aluminum targets for advanced interconnect metallization.
- IRA Critical Minerals Incentives:US domestic production tax credits are redirecting capital toward scandium separation technology development.
Industry Challenges
- Aerospace Qualification Timelines:OEM material specifications require 18-36 month certification cycles that lock out unproven suppliers regardless of purity metrics.
- Pyrometallurgical Skill Scarcity:The specialized expertise required for calcium reduction and electrolytic refining concentrates among a limited pool of rare earth metallurgists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandium Market |
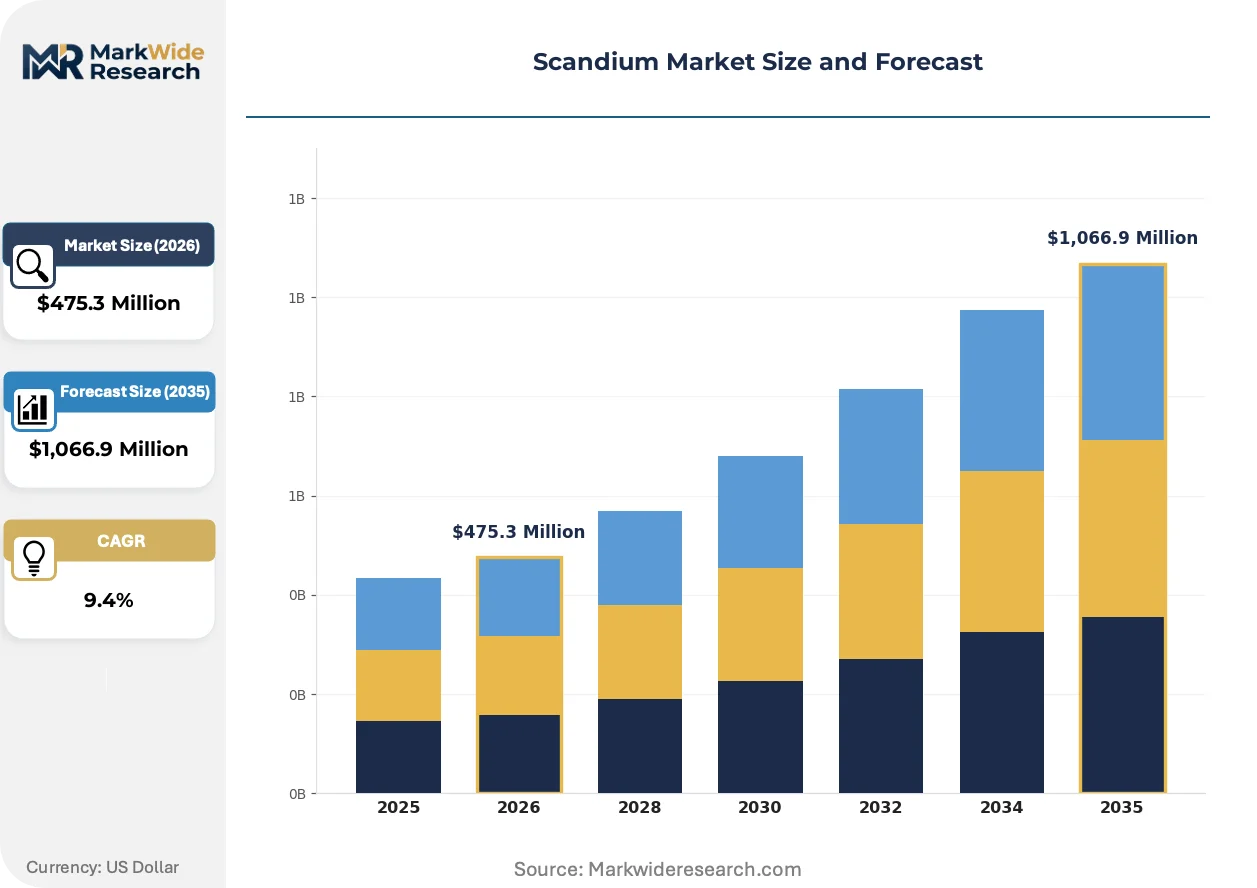
| Market Size in 2026 | $475.3 Million |
| Market Size in 2035 | $1,066.9 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scandium Oxide, Scandium Metal, Scandium Alloys, Scandium Nitrate Industry Vertical: Aerospace, Defense, Electronics, Energy Application: Automotive, Sports Equipment, Welding, Lighting End User: Manufacturers, Research Institutions, Retailers, Distributors |
| Companies Covered | Rio Tinto, RusAL, Scandium International Mining Corporation, NioCorp Development Ltd, Hunan Oriental Scandium Co Ltd, Stanford Advanced Materials, American Elements Inc, Sunrise Energy Metals, Platina Resources Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandium Market Strategic Shifts & Innovations
Scandium extraction technology is pivoting from dedicated mining toward industrial waste stream valorization, with bauxite residue and titanium pigment byproduct recovery overtaking traditional ion-adsorption clay sources.
Calcium reduction of scandium fluoride is overtaking legacy molten salt electrolysis for small-batch aerospace metal production. Specialty alloy foundries in France and Japan are adopting this route for 99.9% purity ingots. The shift is compressing capital requirements for entry-level producers while constraining output scale.
REACH registration deadlines for scandium oxide and chloride compounds are forcing importers to complete full toxicity dossiers or exit European markets. ECHA's extended one-year submission windows have delayed specialty chemical availability. Alloy processors are responding by qualifying US and Australian alternative feedstock sources.
Long-term offtake contracting is displacing spot market purchasing among tier-one airframers. Boeing and Airbus supply chain managers are securing 5-7 year scandium-aluminum billet agreements directly with integrated processors. This concentration is most visible in France and Germany, where qualified suppliers now number fewer than four per alloy specification.
Scandium Market Segmentation
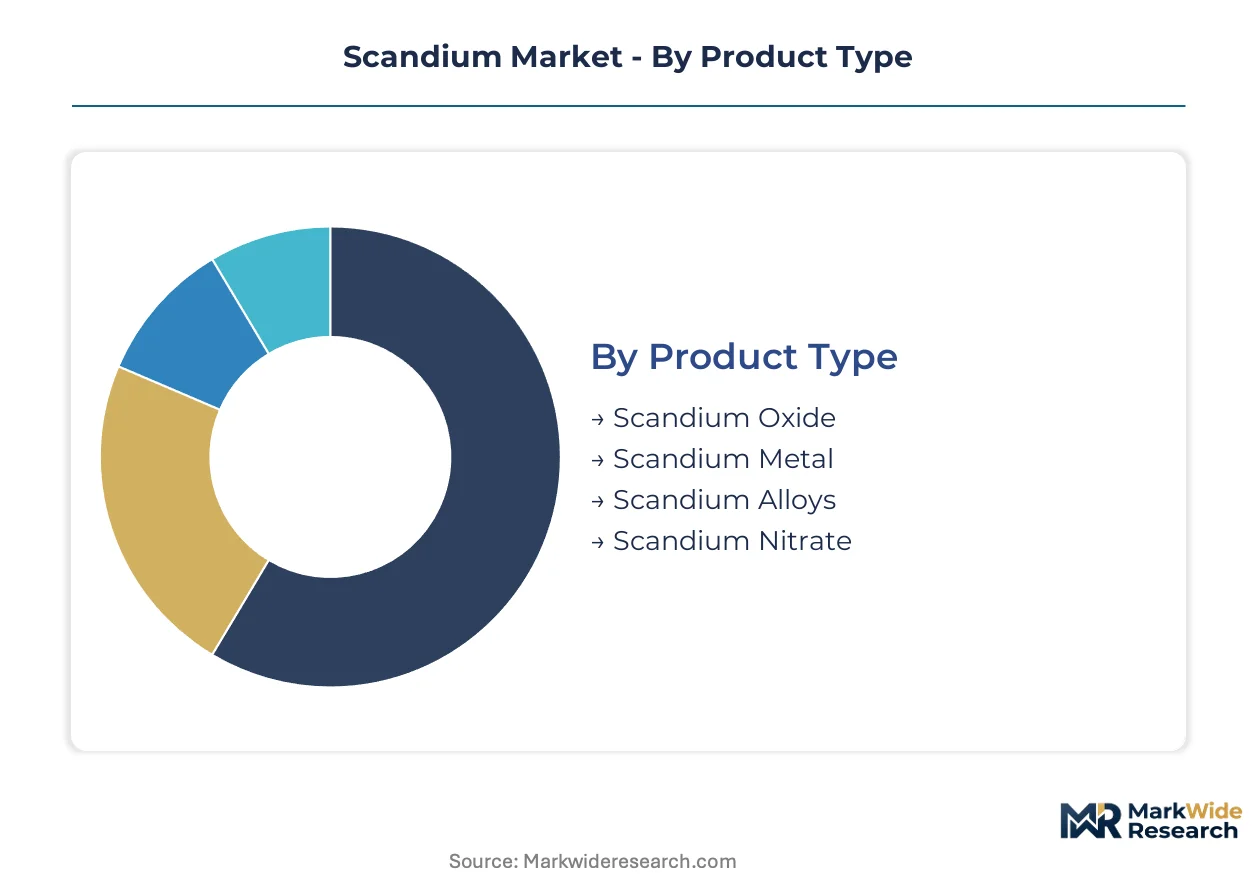
Scandium's commercial trajectory diverges sharply across product forms and end-use specifications. Aerospace qualification requirements and electronics purity standards create tiered demand patterns that reshape processor investment priorities.
Product Type:
Specification thresholds and metallurgical processing complexity differentiate commercial viability across scandium product categories.
- Scandium Oxide:The principal feedstock for downstream metal and alloy production, typically refined to 99.9% purity through solvent extraction and calcination. Demand concentrates in Chinese refiners supplying global aerospace billet manufacturers, constrained by MEE wastewater enforcement on ion-adsorption clay operations.
- Scandium Metal:Produced via molten salt electrolysis or calcium reduction of scandium fluoride at 900°C operating temperatures. Boeing and Airbus supply chain managers in France and Germany are consolidating 5-7 year offtake agreements directly with integrated processors for aerospace-grade ingots.
- Scandium Alloys:Aluminum-scandium master alloys containing 0.1-0.5% scandium by weight deliver high strength-to-weight ratios for airframe components.
- Scandium Nitrate:Specialty chemical precursor for catalytic applications and research quantities, subject to REACH registration barriers in European markets.
Mature deployment sits with Scandium Oxide. Newer deployment is concentrated in Scandium Metal.
Industry Vertical:
End-use qualification timelines and volume scales fragment scandium consumption across distinct industrial verticals.
- Aerospace:Tier-one airframers require 18-36 month certification cycles for scandium-aluminum billet specifications, locking procurement to qualified suppliers in France, Germany, and Japan.
- Defense:Nebraska's Elk Creek project targets defense-qualified supply independent of foreign processing, with US IRA critical minerals incentives redirecting capital toward domestic separation technology.
- Electronics:Semiconductor fabrication equipment manufacturers are qualifying scandium-aluminum sputtering targets for advanced interconnect metallization, climbing the fastest among verticals.
- Energy:Solid oxide fuel cell developers deploy scandia-stabilized zirconia electrolytes for stationary power applications beyond demonstration projects.
Procurement scale concentrates in Aerospace. Technology qualification is accelerating fastest in Electronics.
Application:
Performance requirements and substitution economics shape scandium penetration across downstream applications.
- Automotive:Lightweighting initiatives for electric vehicle structural components drive alloy specification development, though cost barriers limit mass-market adoption.
- Sports Equipment:Bicycle frames and baseball bats utilize scandium-aluminum alloys for fatigue resistance, with Japanese and US sporting goods manufacturers as primary offtakers.
- Welding:Scandium additions to aluminum welding wire reduce cracking susceptibility in high-strength joints.
- Lighting:Metal halide lamps employ scandium iodide for color rendering, a mature application with stable but declining volume.
Volume leadership rests with Sports Equipment. Emerging specification work is concentrated in Automotive.
End User:
Purchasing sophistication and technical capability stratify scandium demand across customer types.
- Manufacturers:Integrated aerospace and electronics producers with in-house metallurgical expertise negotiate long-term offtake contracts directly with processors.
- Research Institutions:Universities and national laboratories consume high-purity metal for materials science programs, typically sourcing through distributors.
- Retailers:Limited direct engagement due to specialty nature of scandium products and customer technical requirements.
- Distributors:Chemical and specialty metal distributors bridge qualified processors to smaller-scale end users in fragmented regional markets.
Contract sophistication sits with Manufacturers. Channel development is expanding fastest through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace demand concentrates in France and Germany where Airbus supply chains dominate qualified scandium-aluminum billet procurement. Chinese refiners control oxide feedstock supply. Australian laterite projects are attracting capital for independent processing capacity.
China
MIIT's evolving GB standards for rare earth processing are tightening wastewater discharge limits on ion-adsorption clay operations. The MEE enforces tailings management rules that indirectly govern scandium byproduct economics from bauxite residue streams. Jiangxi and Guangdong provinces host the principal refining clusters where environmental compliance investments are accelerating cleaner co-recovery technology deployment.
United States
Defense primes are fragmenting procurement across emerging domestic sources to reduce import dependency for aerospace-grade metal. The EPA oversees rare earth processing waste streams that shape project economics for Nebraska and Tennessee developments. The Elk Creek project in the Midwest is positioning as a vertically integrated alternative to Chinese supply dominance for defense-qualified material.
Australia
Laterite resource development in Queensland and New South Wales is drawing capital commitments from specialty metal processors seeking supply chain independence. The country's critical minerals strategy redirects public financing toward separation technology rather than raw extraction alone. Townsville and Gladstone are emerging as processing hubs where emerging refining capacity is consolidating regional output.
Russia
RusAL sustains captive scandium output from Urals aluminum smelters, anchoring supply for domestic aerospace programs. The country's metallurgical infrastructure supports molten salt electrolysis operations at industrial scale. The Sverdlovsk region concentration of aluminum processing capacity enables integrated scandium co-recovery without dedicated mining operations.
Japan
METI's critical minerals procurement initiatives are qualifying scandium-aluminum sputtering targets for semiconductor fabrication equipment. Specialty alloy foundries are adopting calcium reduction routes for small-batch aerospace metal production. Osaka and Nagoya industrial corridors concentrate the metallurgical expertise required for high-purity ingot manufacturing.
Scandium Market Key Industry Players
Australian producers anchor one tier; Chinese refiners hold feedstock dominance; North American developers occupy the emerging vertical integration vector. The vendor base stratifies across three tiers: integrated aluminum majors with co-recovery capabilities, dedicated scandium developers with laterite assets, and specialty chemical distributors bridging qualified processors to fragmented end users. Strategic archetypes include bauxite residue valorization specialists, ion-adsorption clay refiners, and defense-focused domestic supply builders. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as tier-one airframers consolidate supplier relationships.
Among integrated aluminum operators, Rio Tinto and RusAL exemplify the co-recovery archetype through existing bauxite processing infrastructure. NioCorp Development Ltd occupies a position within the North American vertical integration tier, representing the emerging domestic supply model for defense-qualified material independent of foreign processing chains.
| Leading Market Players |
|---|
| Rio Tinto |
| RusAL |
| Scandium International Mining Corporation |
| NioCorp Development Ltd |
| Hunan Oriental Scandium Co Ltd |
| Stanford Advanced Materials |
| American Elements Inc |
| Sunrise Energy Metals |
| Platina Resources Limited |
| Others |
Cost & Logistics Intelligence
Calcium reduction of scandium fluoride is displacing legacy molten salt electrolysis for aerospace-grade metal production, simultaneously compressing capital requirements for new entrants and concentrating pricing power among French and Japanese specialty foundries with established 99.9% purity capabilities. This production-method transition tightens feedstock competition for scandium oxide while amplifying cost advantages for processors with captive bauxite residue streams.
Pricing Analysis
High-volume oxide transactions trade at compressed margins against premium-capture aerospace metal sales. Contract-based long-term offtake dominates tier-one airframer procurement, with price differentiation driven by certification grade and volume scale. Cost compression in standard-grade oxide intensifies because Chinese MEE wastewater enforcement tightens ion-adsorption clay refinery output. Defense primes exhibit lowest price sensitivity; electronics distributors face highest pressure from REACH compliance investment requirements.
Supply Chain Analysis
Scandium metal scrap and spent sputtering target collection flows remain nascent, with reverse-logistics infrastructure concentrated in Japanese electronics corridors and French aerospace clusters. Primary supply draws from China, Russia, and Australia, with scandium fluoride, bauxite residue, and laterite ore as critical feedstocks. Single-source vulnerability concentrates in Chinese oxide refining capacity subject to export license reviews. Distribution runs through integrated aluminum majors and specialty chemical distributors to qualified aerospace billet manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scandium market functions as a vertical-integration race where control over bauxite residue processing technology determines long-term cost positioning and supply security.
For Market Incumbents: Cement long-term offtake relationships with Boeing and Airbus supply chain managers before Nebraska and Australian projects achieve qualification status. Expand molten salt electrolysis capacity in France and Germany to capture aerospace metal premiums while Chinese environmental compliance investments constrain rival oxide output. Backward integration into bauxite residue valorization technology insulates feedstock costs from ion-adsorption clay supply volatility. For New Entrants and Emerging Players: Launch via direct qualification with US defense primes seeking domestic supply alternatives to Chinese processing chains. Target electronics sputtering target specifications where semiconductor fabrication equipment manufacturers accelerate scandium-aluminum adoption faster than aerospace certification timelines permit. Penetrate Australian laterite development partnerships where critical minerals financing redirects toward separation technology rather than raw extraction alone. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated aluminum majors seeking co-recovery capabilities from existing bauxite processing infrastructure. Five-to-ten year viability hinges on defense procurement fragmentation and solid oxide fuel cell commercial deployment scale. Watch for EPA rare earth processing waste stream enforcement tightening as the signal indicating US project economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Residue Processing | Rio Tinto trials co-recovery from existing aluminum operations to secure captive oxide feedstock. |
| Long-term Supply Agreement with Tier-One Airframers | Boeing and Airbus procurement managers consolidate 5-7 year billet contracts with qualified French and German processors. |
| Defense-Qualified Domestic Supply Buildout | Nebraska's Elk Creek project targets US defense prime procurement independent of Chinese refining chains. |
| Electronics Sputtering Target Qualification | Japanese METI initiatives accelerate semiconductor fabrication equipment manufacturer adoption for advanced interconnect metallization. |
| Green Manufacturing Transition via Waste Stream Valorization | Chinese MIIT GB standard tightening accelerates investment in cleaner scandium co-recovery from bauxite residue streams. |
Research Approach
Document review covered SEC filings from specialty metal processors, ECHA REACH registration databases, and Chinese MIIT environmental compliance disclosures, complemented by interviews with rare earth metallurgists, aerospace procurement directors, and bauxite processing plant managers. Primary fieldwork included discussions with solid oxide fuel cell developers and defense prime supply chain strategists. Secondary validation drew from customs trade data, Australian critical minerals strategy documents, and EPA rare earth processing oversight records. Bottom-up capacity assessments triangulated against top-down demand projections from end-use verticals.
Cross-referencing historical pricing patterns from Chinese oxide export data against panel input from alloy foundry operators shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product form, industry vertical, application, and regional regulatory cluster. CAGRs were derived through slope analysis of annual growth trajectories adjusted for aerospace qualification timeline constraints and electronics adoption acceleration curves. Forecast inputs incorporated MEE wastewater enforcement intensity and IRA critical minerals incentive allocation patterns.
Export license review disruptions, REACH registration deadline extensions, and aerospace OEM certification timeline compression are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around bauxite residue valorization technology maturation and defense procurement fragmentation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Wear Steel Plate Market
Metals
Platinum Compounds Market
Metals
Brazil Aluminum Market
Metals
Grain Oriented Electrical Steel Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Europe Metal Service Centers Market
Metals
Tantalum and Niobium Material Market
Metals
GCC Metal Forging Market
Metals
Global Duplex Stainless Steel Market
Metals
Colloidal Metal Particles Market
Metals
Bismuth Market
Metals
United States Metal Casting Market
Metals
Molybdenum Market
Metals
Zinc Dust Market
Metals
Zirconium Market