
 Caribbean Islands Bunker Fuel Market | 2026-2036
Caribbean Islands Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Caribbean Islands Bunker Fuel Market Insights
Refinery upgrades across Trinidad and Tobago are recalibrating regional low-sulfur fuel availability. Royal Dutch Shell leverages its integrated supply chain to dominate bunkering operations at key Caribbean ports. BP competes through strategic storage investments that anchor its position in high-traffic shipping lanes. Bunker Holding A/S sustains a diversified barge fleet that navigates fragmented port infrastructure across multiple island jurisdictions.
Caribbean Islands Bunker Fuel encompasses marine-grade hydrocarbon products—specifically residual fuel oils with maximum sulfur content capped at 0.50% mass under IMO 2020, alongside marine gas oil and intermediate fuel oils—formulated to power main and auxiliary engines aboard oceangoing vessels. These fuels serve the essential commercial purpose of enabling maritime transport and cruise tourism across archipelagic trade routes where port-to-port distances demand reliable onboard energy storage. Marine gas oil commands premium positioning as the fastest-growing fuel type segment, driven by scrubber-equipped vessels seeking operational flexibility and cruise lines prioritizing emissions compliance. Barge delivery mode leads volume throughput due to port infrastructure constraints that preclude pipeline alternatives across most island terminals.
The International Maritime Organization enforces MARPOL Annex VI sulfur regulations that shape product formulation requirements across Caribbean bunkering hubs. The US EPA coordinates enforcement through its Caribbean Environmental Protection Division, affecting vessels calling at US Virgin Islands and Puerto Rico. IMO 2020 compliance deadlines have permanently altered supplier procurement patterns toward low-sulfur blending components. Stakeholders must monitor scrubber retrofit rates and alternative fuel pilot programs to anticipate shifts in fuel-type demand across the archipelago.
Market Dynamics
IMO 2020 sulfur regulations have permanently restructured Caribbean bunker fuel procurement, forcing suppliers to reconfigure blending operations and storage infrastructure while cruise operators accelerate scrubber retrofits to maintain fuel flexibility across archipelagic routes.
Growth Catalysts
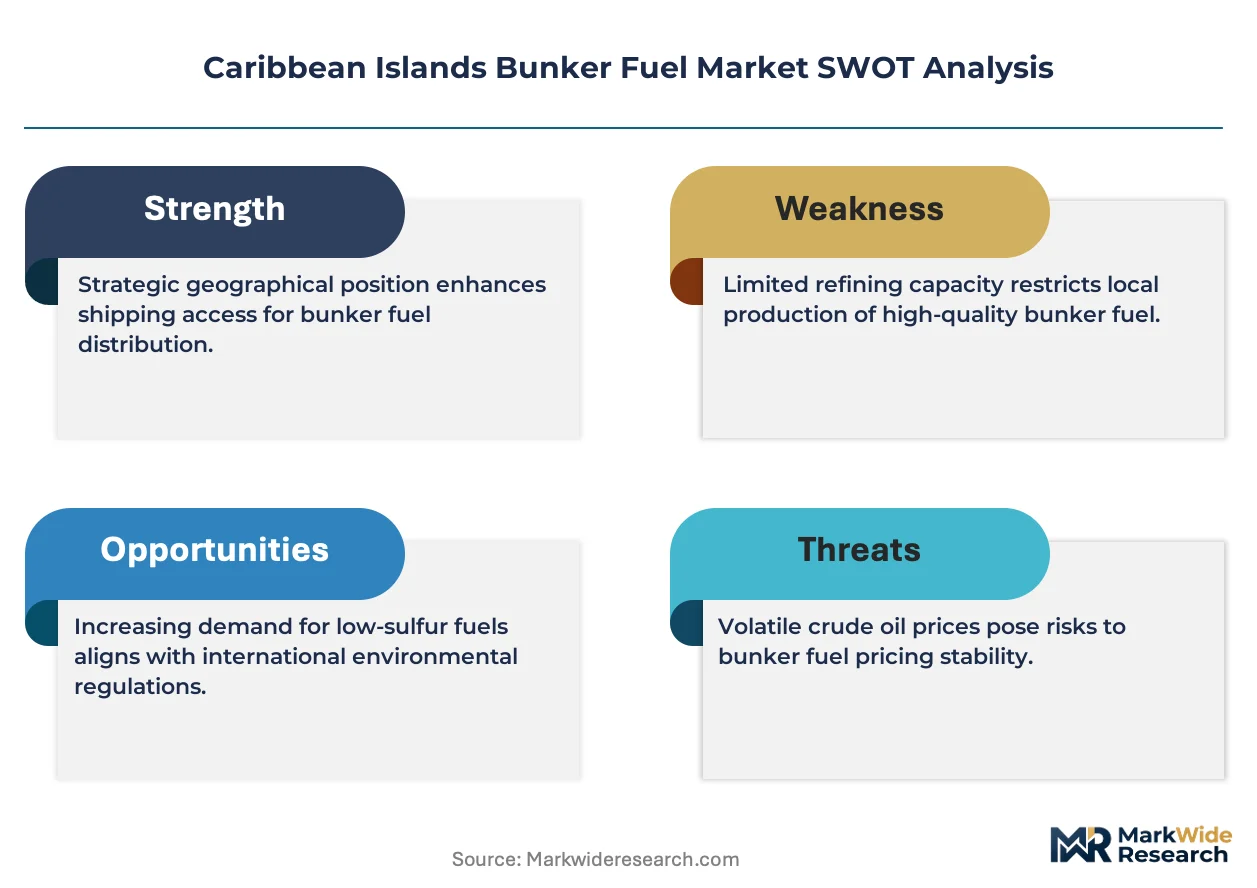
- Post-pandemic cruise tourism rebound:Cruise lines operating in the Bahamas-Florida Straits corridor are expanding fleet deployments and terminal capacity, directly lifting marine gas oil offtake volumes at key bunkering hubs.
- MARPOL Annex VI enforcement tightening:The US EPA Caribbean Environmental Protection Division has intensified port-state control inspections, compelling vessel operators to source certified low-sulfur fuels from compliant Caribbean suppliers.
- Scrubber technology maturation:Open-loop and hybrid scrubber installations aboard Panamax and post-Panamax vessels are enabling continued residual fuel oil consumption despite sulfur caps, preserving demand for intermediate fuel oils.
Market Restraints
- Crude oil price volatility:Brent crude fluctuations transmit directly into marine gas oil and low-sulfur fuel oil pricing, compressing supplier margins and destabilizing procurement budgets for shipping operators.
- Trinidad and Tobago refinery concentration:Regional low-sulfur fuel availability depends heavily on upgrades at Pointe-à-Pierre and Point Fortin facilities, creating single-source vulnerability for Caribbean blending components.
- LNG bunkering infrastructure gap:Liquefied natural gas remains unavailable at scale across most Caribbean terminals, blocking vessel operators from pursuing IMO 2050-aligned fuel switching strategies.
Strategic Opportunities
- Jamaica transshipment expansion:Kingston Freeport Terminal upgrades and Panama Canal route optimization are positioning the port as a secondary bunkering alternative to Bahamas-Florida corridor concentration.
- Biofuel blending pilot programs:B24 and B30 marine biofuel trials by cruise operators create regulatory-compliant pathways for suppliers to differentiate product offerings beyond conventional hydrocarbons.
- Digitized barge scheduling platforms:Real-time inventory tracking and automated berth allocation systems are reducing demurrage costs and vessel waiting times at fragmented island port infrastructure.
Industry Challenges
- Marine fuel chemist scarcity:Specialized expertise in low-sulfur fuel stability, compatibility testing, and cold-flow property management remains concentrated among aging workforces at major trading houses.
- IMO 2024 carbon intensity indicator compliance:Ship operators must now document operational carbon intensity ratings, requiring bunker suppliers to provide verified well-to-wake emissions data that many lack systems to generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caribbean Islands Bunker Fuel Market |
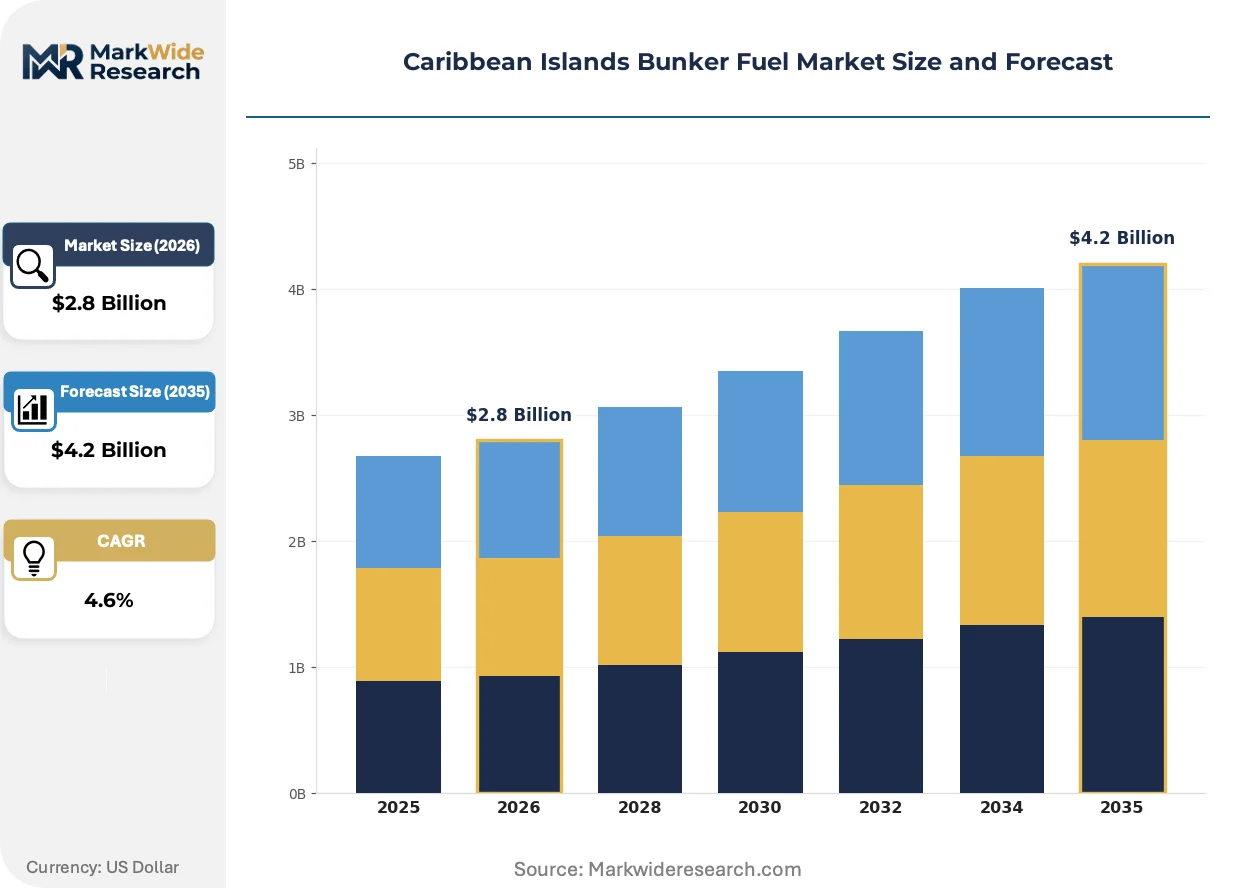
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Fuels Oil, Marine Diesel, Marine Gas Oil, IFO Delivery Mode: Barge, Pipeline, Truck, Ship End User: Shipping Lines, Cargo Vessels, Cruise Ships, Fishing Fleet Regulatory Compliance: IMO 2020, MARPOL, EPA Standards, Local Regulations |
| Companies Covered | Royal Dutch Shell, Gazprom Neft, Bunker One, Bomin Bunker Oil, GAC Bunker Fuels, BP, Bunker Holding A/S, Aegean Marine Petroleum Network, Exxon Mobil, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caribbean Islands Bunker Fuel Market Trends and Innovations
Digital fuel management systems and alternative fuel pilot programs are converging to reshape how Caribbean suppliers interact with vessel operators, compressing transaction cycles and elevating emissions transparency requirements.
Bunker delivery note digitization via blockchain-verified platforms is decentralizing fuel quality documentation across the Caribbean archipelago. Cruise operators and container lines are adopting these systems fastest, eliminating paper-based custody transfer delays. The technology is decentralizing trust mechanisms previously concentrated among major oil company laboratories, enabling independent barge operators to compete on verification speed.
The US EPA Caribbean Environmental Protection Division has harmonized enforcement protocols with MARPOL Annex VI port-state control procedures, creating unified inspection standards across US Virgin Islands and Puerto Rico. This regulatory convergence reduces compliance ambiguity for vessels on multi-port itineraries. Container shipping segments calling San Juan and Charlotte Amalie are responding by pre-positioning compliant fuel inventories to avoid detention risk.
Cruise line procurement departments are consolidating supplier relationships around integrated service contracts bundling fuel, lubricants, and technical advisory. This behavior compresses the vendor base at key Caribbean hubs, displacing spot-market transactions. The shift is most visible in the Bahamas-Florida Straits corridor, where Carnival Corporation and Royal Caribbean Group have reduced approved supplier lists by over half since 2022.
Caribbean Islands Bunker Fuel Market Segmentation
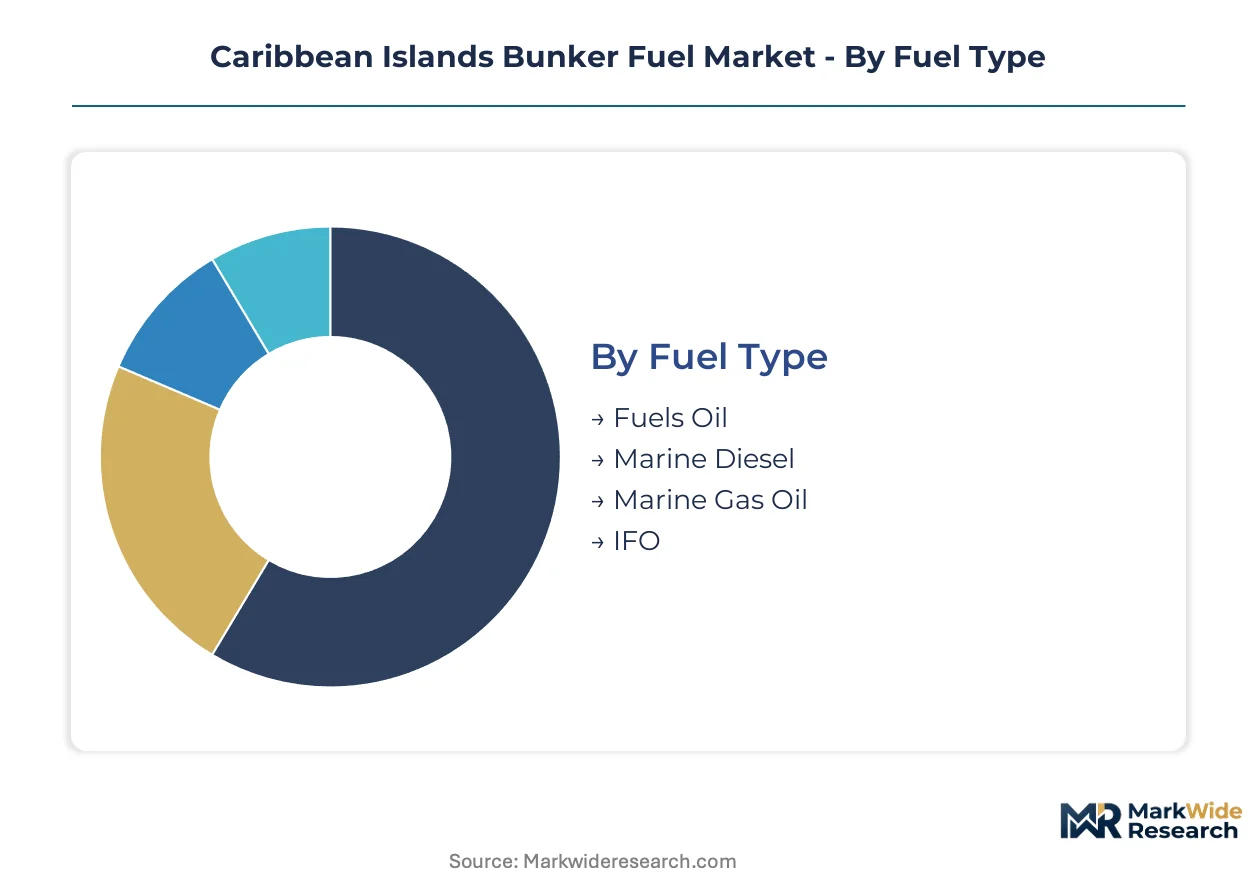
Caribbean bunker fuel procurement patterns diverge sharply across fuel specifications, delivery infrastructure, and vessel operator profiles. Each segmentation axis reveals distinct margin structures and compliance burdens that suppliers must navigate across fragmented island port networks.
Fuel Type:
Marine fuel chemistry and sulfur content specifications determine blending complexity, storage segregation requirements, and premium capture potential across Caribbean supply chains.
- Marine Gas Oil:Distillate-grade fuel with maximum 0.10% sulfur content serves scrubber-equipped vessels and cruise operators prioritizing emissions compliance. Demand concentrates in the Bahamas-Florida Straits corridor where Carnival Corporation and Royal Caribbean Group bunker their expanding post-pandemic fleets.
- IFO (Intermediate Fuel Oil):Blended residual-distillate formulations with 0.50% sulfur ceiling enable cost-efficient operations for container vessels transiting Panama Canal routes. Trinidad and Tobago refinery upgrades at Pointe-à-Pierre supply the primary blending components.
- Fuels Oil:Residual-based marine fuels remain in limited circulation for vessels with exhaust gas cleaning systems installed.
- Marine Diesel:Higher-cetane distillate variants serve auxiliary engines and cold-start requirements across smaller cargo fleets.
Marine Gas Oil leads on scale; IFO leads on momentum as scrubber retrofits preserve residual fuel compatibility.
Delivery Mode:
Physical distribution constraints across archipelagic geography dictate which delivery mechanisms dominate throughput at specific Caribbean terminals.
- Barge:Flat-bottomed tanker vessels navigate shallow-draft island ports where fixed infrastructure cannot reach. Real-time berth allocation systems at Kingston Freeport Terminal are reducing demurrage costs for this delivery mode.
- Pipeline:Direct fuel transfer from storage to vessel exists only at select industrialized terminals with dedicated marine loading arms.
- Truck:Road tanker delivery serves fishing fleets and smaller coastal vessels at secondary ports lacking deepwater access.
- Ship:Ocean-going bunker tankers conduct offshore ship-to-ship transfers for very large crude carriers and post-Panamax container vessels.
Barge delivery commands volume leadership; digitized scheduling platforms are accelerating its efficiency gains fastest.
End User:
Vessel operator categories present diverging procurement behaviors, contract structures, and technical service requirements that reshape supplier competitive positioning.
- Cruise Ships:Integrated service contracts bundling fuel, lubricants, and technical advisory are compressing approved supplier lists by over half since 2022 in the Bahamas-Florida corridor.
- Shipping Lines:Container operators prioritize MARPOL Annex VI compliance documentation to avoid US EPA Caribbean Environmental Protection Division detention risk at San Juan and Charlotte Amalie.
- Cargo Vessels:Bulk and breakbulk operators balance fuel cost against inventory carrying costs across multi-port Caribbean itineraries.
- Fishing Fleet:Artisanal and commercial fishing vessels source smaller volumes through fragmented distributor networks at secondary island ports.
Cruise Ships dominate contract value concentration; Shipping Lines are expanding compliance-driven procurement fastest.
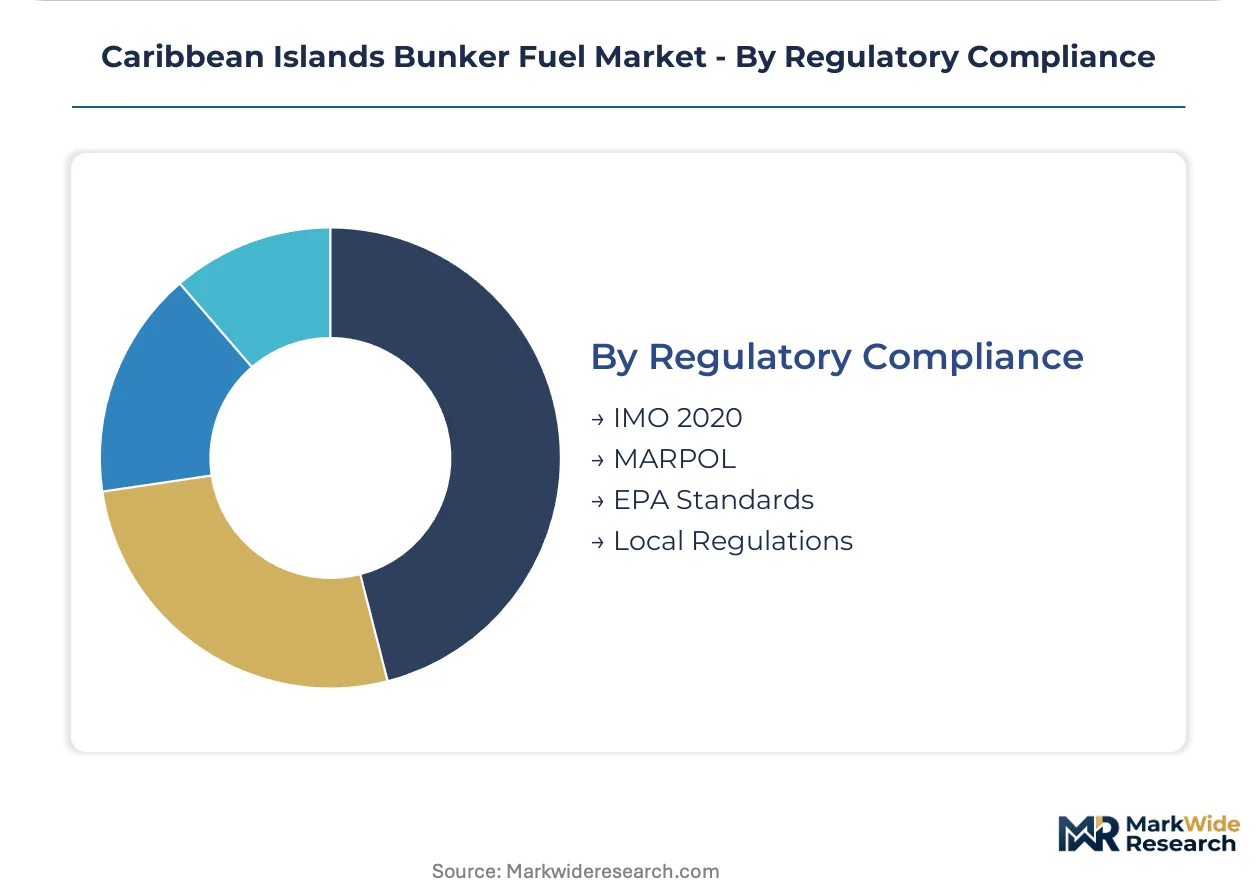
Regulatory Compliance:
Certification requirements fragment supplier qualification pathways and create documentation burdens that favor integrated trading houses over independent operators.
- IMO 2020:Global sulfur cap mandates 0.50% mass maximum for residual fuels, forcing Caribbean blenders to reconfigure component sourcing away from high-sulfur crudes.
- MARPOL:Annex VI port-state control procedures harmonized with US EPA enforcement create unified inspection standards across US Virgin Islands and Puerto Rico.
- EPA Standards:US EPA Caribbean Environmental Protection Division coordinates fuel quality verification affecting vessels on US-flagged itineraries.
- Local Regulations:Individual island nation environmental agencies impose additional storage, spill response, and emissions monitoring requirements.
IMO 2020 anchors global compliance architecture; MARPOL enforcement harmonization is tightening fastest across US-affiliated territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bahamas commands transshipment volumes that dwarf bunkering activity in Trinidad and Tobago, where refinery infrastructure instead anchors regional fuel blending. Jamaica leverages Panama Canal route optimization to capture secondary demand. Puerto Rico and the Dominican Republic split enforcement exposure between US EPA jurisdiction and independent port authorities.
Bahamas
Cruise terminal expansions at Freeport and Nassau drive marine gas oil offtake volumes for Carnival Corporation and Royal Caribbean Group fleets. The Bahamas Maritime Authority enforces MARPOL Annex VI compliance through flag-state inspections. The Freeport Harbour corridor concentrates bunkering infrastructure where scrubber-equipped vessels conduct simultaneous cargo and fuel operations.
Trinidad and Tobago
Pointe-à-Pierre and Point Fortin refinery upgrades supply low-sulfur blending components across the Eastern Caribbean. The country's national environmental regulator coordinates spill response protocols with IMO guidelines. The Point Lisas industrial estate anchors storage and blending operations that feed barge distribution networks to Barbados and Grenada.
Jamaica
Kingston Freeport Terminal upgrades position the port as an alternative to Bahamas-Florida corridor concentration for container vessels. The Port Authority of Jamaica implements digitized berth allocation systems reducing demurrage costs. The Kingston Harbour zone attracts ship-to-ship transfers for post-Panamax vessels optimizing Panama Canal routing.
Puerto Rico
San Juan terminals face intensified US EPA Caribbean Environmental Protection Division port-state control inspections. The EPA harmonizes enforcement with MARPOL Annex VI procedures creating unified compliance standards. The San Juan Bay industrial zone pre-positions certified low-sulfur inventories to avoid vessel detention risk on multi-port itineraries.
Dominican Republic
Caucedo Multimodal Terminal expansion targets transshipment volumes from expanding Panama Canal traffic. The national maritime authority maintains independent environmental compliance frameworks outside US EPA jurisdiction. The Santo Domingo-Caucedo corridor develops barge fleet capacity to serve container lines avoiding Puerto Rico enforcement exposure.
Caribbean Islands Bunker Fuel Market Competitive Landscape
European integrated oil majors anchor one tier; specialized bunkering operators and regional distributors hold fragmented positions across island port networks. The market structure concentrates around trading houses with captive storage infrastructure and integrated supply chains. Three archetypes dominate: integrated oil companies with refining assets, independent bunker suppliers with barge fleets, and port-focused distributors serving cruise line consolidation. Capacity expansion into low-sulfur blending infrastructure and strategic storage investments represent the dominant competitive moves reshaping supplier positioning.
Among integrated oil majors, Royal Dutch Shell and BP exemplify the trading house archetype through Caribbean storage and supply chain control. Bunker Holding A/S represents the independent specialist tier with diversified barge operations across fragmented island jurisdictions. These three companies occupy positions that illustrate how scale and infrastructure concentration separate tier-one suppliers from regional competitors dependent on third-party storage.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| Gazprom Neft |
| Bunker One |
| Bomin Bunker Oil |
| GAC Bunker Fuels |
| BP |
| Bunker Holding A/S |
| Aegean Marine Petroleum Network |
| Exxon Mobil |
| Others |
Pricing and Supply Chain Analysis
Marine Gas Oil premiums against Intermediate Fuel Oil spreads widen or compress based on scrubber installation rates and Trinidad refinery output volumes. This fuel-grade divergence manifests in barge delivery pricing that fluctuates with berth congestion at Freeport and Kingston terminals, while integrated suppliers with captive storage capture margin that independent operators forfeit to third-party tankage fees.
Pricing Analysis
Distributor margins at Caribbean island terminals absorb the cost premium for IMO 2020 compliant blending components sourced from Pointe-à-Pierre upgrades. Pricing stratifies across marine gas oil, intermediate fuel oil, and residual-based fuels based on sulfur certification tier and vessel scrubber status. Cost compression in the IFO segment is intensifying because Trinidad refinery reliability issues periodically constrain low-sulfur component availability. Container shipping lines exhibit highest price sensitivity due to thin operating margins on Panama Canal routes, while cruise operators prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers at Point Lisas industrial estate and San Juan Bay feed hub-and-spoke barge networks across the Eastern Caribbean archipelago. Supply concentrates in Trinidad and Tobago, the Bahamas, and Puerto Rico as the primary storage and blending nodes. Raw material dependencies draw from Venezuelan heavy crude feedstocks, US Gulf Coast distillate imports, and regional refinery upgrading capacity. Single-source vulnerability runs through Pointe-à-Pierre operational reliability. Distribution runs through chartered barge fleets with real-time berth allocation systems reducing demurrage at Kingston and Freeport terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MARPOL Annex VI enforcement tightening and IMO 2024 carbon intensity indicators continuously restructure procurement requirements and supplier qualification barriers.
For Market Incumbents: Lock in integrated service contracts bundling fuel, lubricants, and technical advisory to preempt cruise line supplier consolidation. Expand captive storage capacity at Kingston Freeport Terminal to capture transshipment volume shifting from Bahamas-Florida corridor concentration. Biofuel blending certification investments defend position against emerging marine biofuel specialists threatening hydrocarbon incumbency. For New Entrants and Emerging Players: Mid-tier price-point gaps between Shell-BP integrated premiums and fragmented independent spot pricing create entry space for digitized barge operators with blockchain-verified delivery documentation. Target Jamaica transshipment expansion as the most penetrable geography given Kingston Freeport Terminal upgrades and reduced incumbent storage lock-in. Lead with automated berth allocation platforms that compress vessel waiting times against legacy scheduling systems. For Investors and Strategic Acquirers: Asymmetric upside sits with independent barge fleet operators possessing digitized inventory tracking and multi-island port access rights. Five-to-ten year viability favors suppliers with backward integration into Trinidad blending component sourcing or forward integration into cruise line technical advisory contracts. The signal to watch is scrubber retrofit completion rates among Panamax container fleets, which determines residual fuel demand persistence versus marine gas oil substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Sulfur Blending Capacity Expansion | Pointe-à-Pierre upgrades anchor regional IMO 2020 compliance fuel availability. |
| Blockchain-Verified Delivery Documentation | Digitized custody transfer displaces paper-based laboratory verification at independent barge operators. |
| Integrated Service Contract Bundling | Carnival and Royal Caribbean procurement consolidation favors full-service suppliers over spot-market traders. |
| Automated Berth Allocation Systems | Real-time scheduling at Kingston Freeport Terminal reduces demurrage costs for fragmented island infrastructure. |
| Biofuel Blending Certification Investment | B24 and B30 marine biofuel trials create regulatory-compliant differentiation beyond conventional hydrocarbons. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volumetric flows and procurement behavioral shifts. Primary discussions with bunker fuel traders, refinery operations managers, cruise line procurement directors, and port authority officials informed demand segmentation assumptions. Secondary validation drew from IMO MARPOL enforcement reports, US EPA Caribbean Environmental Protection Division inspection data, customs trade records, and SEC filings from integrated oil majors. Bottom-up vessel call data and top-down regional fuel consumption estimates were triangulated against refinery output disclosures.
Segment-weighting approaches applied differential growth assumptions across fuel type, delivery mode, and end-user categories. The analytical framework modeled marine gas oil, intermediate fuel oil, and residual fuel demand separately across the projection horizon, with scrubber retrofit rates and cruise fleet deployment schedules as key demand drivers. CAGRs were derived from regression analysis against historical bunker sales volumes, Panama Canal transit data, and cruise passenger capacity additions. Forecast inputs included Trinidad refinery upgrade timelines and US EPA enforcement intensity indices.
Caveats apply where Brent crude volatility, Pointe-à-Pierre operational disruptions, or accelerated LNG bunkering infrastructure development could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Coal Gasification Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
No.4 Fuel Oil Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Brazil Bunker Fuel Market
Fuels
Fuel Grinder Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Palm Methyl Ester Market
Fuels
Storage Tank Market
Fuels
Italy Chemical Logistics Market
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Japan Bunker Fuel Market
Fuels
Electric Fuel Heater Market