
 South America Bunker Fuel Market | 2026-2036
South America Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
South America Bunker Fuel Market Analytics
The split between premium very low sulfur fuel oil and commodity-grade high-sulfur residual products is realigning procurement patterns across South American ports. Bunker Holding A/S leverages its multi-port supply network to sustain coverage across Brazilian and Argentine terminals. Petrobras anchors domestic production through its integrated refining system, while Vitol Holding BV competes by positioning traded cargoes into import-dependent markets like Chile and Peru.
South America bunker fuel denotes marine-grade hydrocarbons burned in vessel main engines and auxiliary power units, with viscosity grades spanning IFO380 centistokes residual fuel through 0.10% sulfur maximum marine gasoil for emission control areas. The product serves commercial shipping fleets, fishing operators, and offshore energy platforms requiring reliable propulsion energy across extended ocean transits. VLSFO commands expanding share as vessel operators phase out non-compliant high-sulfur stocks, while MGO retains premium positioning in coastal trades where sulfur limits are most stringent. Commercial shipping dominates end-user demand, with offshore platforms representing a concentrated but higher-margin segment tied to Brazilian pre-salt development.
ANVISA and the Brazilian Navy's maritime authority shape product quality enforcement through port state control inspections, while Chile's environmental regulator tightens sulfur emission standards in Valparaíso and San Antonio anchorage zones. IMO 2020 compliance mechanisms continue redirecting supply source preferences toward blending facilities and import terminals capable of certifying sub-0.50% sulfur content. Stakeholders must monitor how Panama Canal transit patterns and emerging Pacific coast hub development redistribute bunkering demand between Atlantic and Pacific port systems.
Market Dynamics
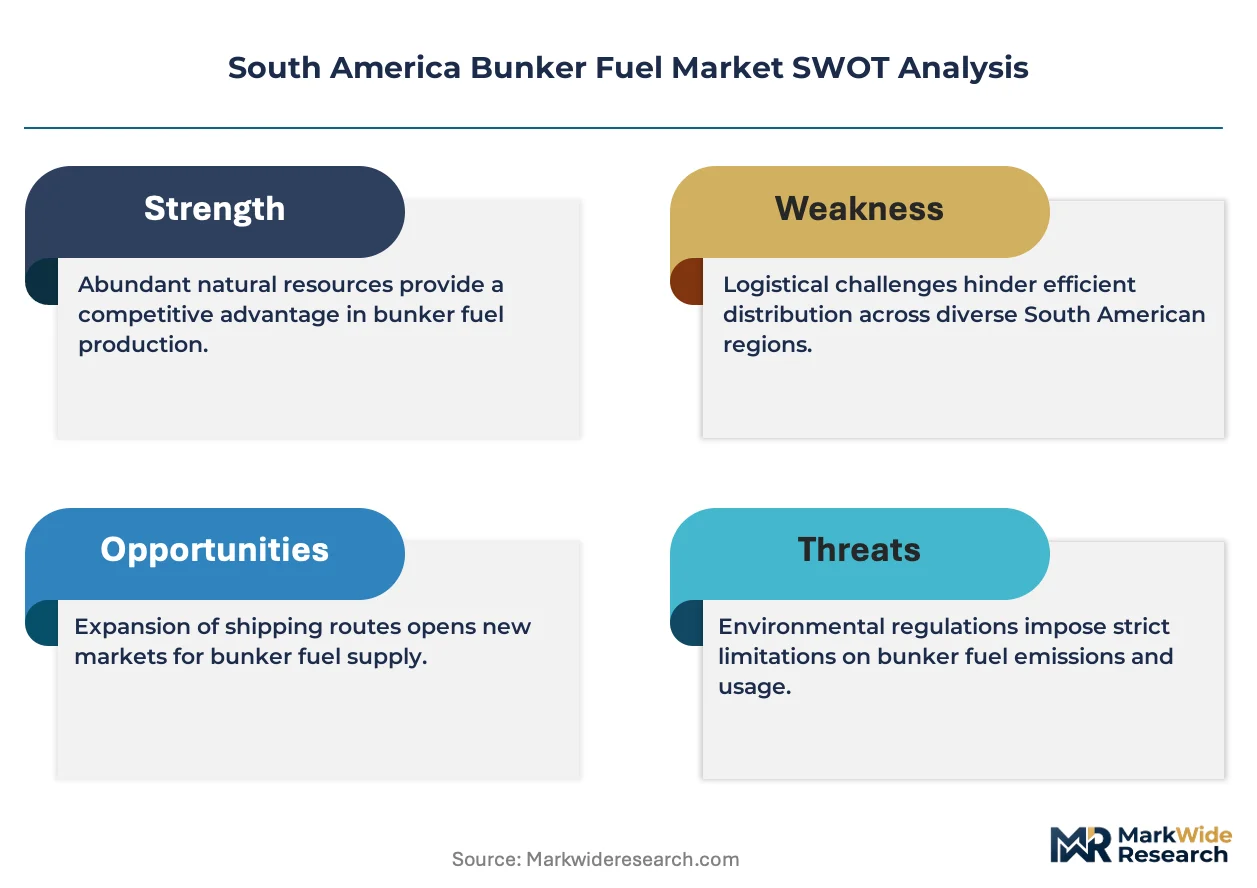
IMO 2020 sulfur cap enforcement is compressing residual fuel demand while forcing Brazilian refiners to reconfigure blending infrastructure for compliant very low sulfur fuel oil production.
Growth Catalysts
- Container fleet renewal:Brazilian and Chilean ports are receiving expanded calls from newer vessels designed exclusively for 0.50% sulfur maximum fuels, pulling compliant bunker volumes upward.
- ANVISA quality enforcement:Brazil's health and maritime regulator tightened port state control inspections, eliminating off-spec fuel arbitrage and rewarding certified suppliers with volume concentration.
- Pre-salt offshore development:Floating production units and drilling rigs off Brazil's southeastern coast generate concentrated demand for marine gasoil in coastal emission control zones.
Market Restraints
- Crude sulfur content mismatch:Domestic Brazilian crude slate runs heavy and sour, forcing Petrobras to import lighter sweet barrels or invest in hydrodesulfurization capacity to produce compliant bunker blends.
- Atlantic supply concentration:Santos and Rio de Janeiro terminals handle the majority of South American bunkering, creating congestion risk and limiting buyer leverage during peak vessel queues.
- Alternative fuel uncertainty:Methanol and ammonia pilot projects among European-flagged carriers are freezing long-term residual fuel infrastructure commitments at Chilean and Peruvian ports.
Strategic Opportunities
- Peruvian Pacific hub development:Callao and Matarani terminals remain underdeveloped relative to throughput potential, offering first-mover positioning for VLSFO storage and blending investments.
- Argentine riverine trade:Paraná-Paraguay waterway barge fleets currently rely on high-sulfur residual fuels, presenting conversion opportunity as IMO standards extend to inland shipping.
- Chilean green hydrogen corridor:Antofagasta and Valparaíso port authorities are designating zones for future ammonia bunkering, allowing early infrastructure positioning ahead of regulatory mandates.
Industry Challenges
- Blending technician scarcity:VLSFO production requires precise viscosity and stability control that legacy fuel oil blenders lack, forcing retraining programs at Brazilian coastal refineries.
- Storage tank segregation:Terminal operators must maintain parallel high-sulfur and low-sulfur inventories without cross-contamination, doubling working capital requirements at constrained port real estate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Bunker Fuel Market |
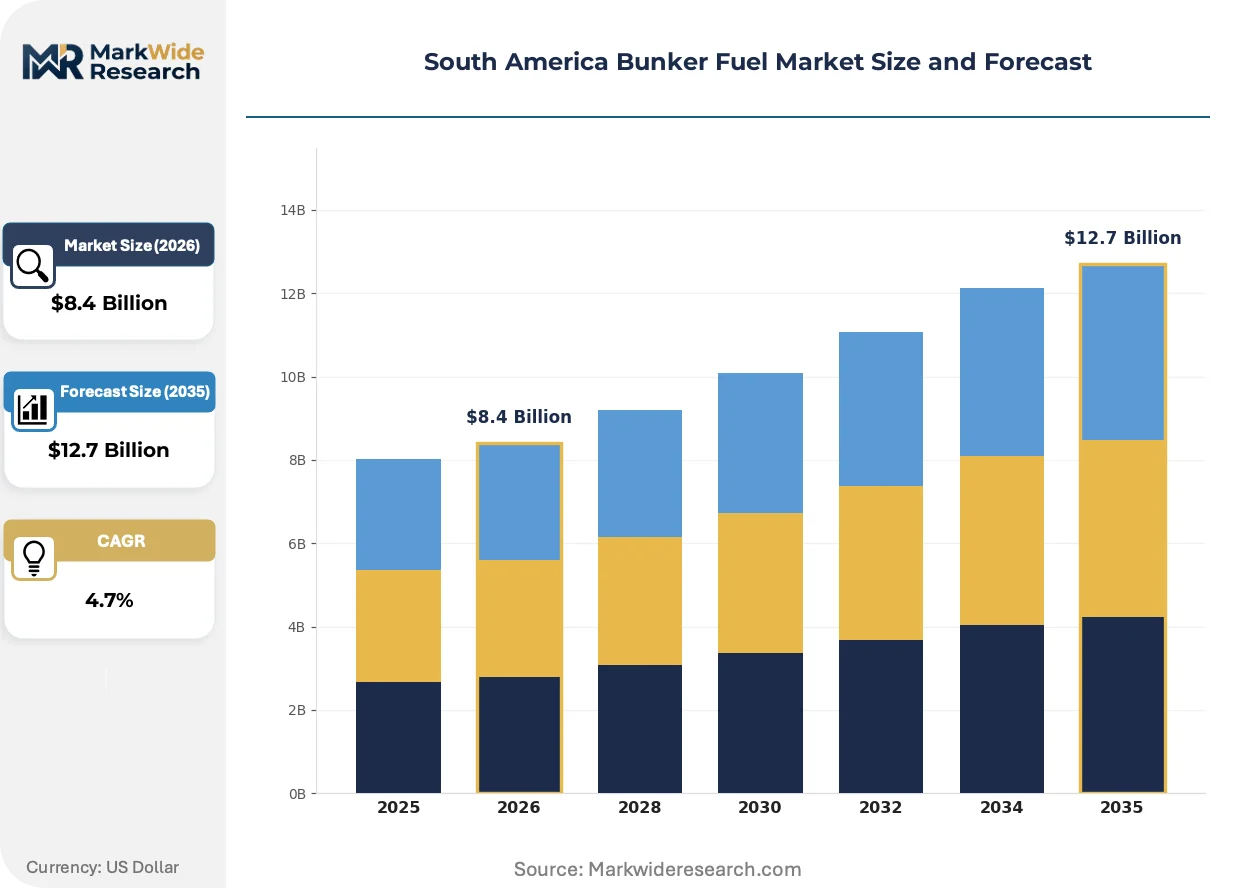
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: IFO380, IFO180, MGO, VLSFO End User: Commercial Shipping, Fishing Vessels, Recreational Boats, Offshore Platform Delivery Mode: Truck, Barge, Pipeline, Vessel Supply Source: Refineries, Import Terminals, Blending Facilities, Others |
| Companies Covered | Bunker Holding A/S, Peninsula Petroleum Ltd, Petrobras, TotalEnergies SA, Chevron Corporation, Vitol Holding BV, World Fuel Services Corp, AP Moeller Maersk A/S, Monjasa Holding A/S, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Bunker Fuel Market Evolving Landscape
Bunker supply chains are fragmenting from centralized refinery-direct models toward distributed blending hubs and import-reliant port terminals. Technology and regulatory pressure are accelerating this structural reconfiguration.
Hybrid digital fuel management systems are modularizing vessel procurement workflows. Container lines operating Brazilian routes are adopting cloud-based bunker planning platforms that integrate real-time port pricing, sulfur certification tracking, and voyage optimization. This technology is modularizing what had been siloed chartering, operations, and procurement functions into unified decision architectures.
Chile's environmental regulator is tightening sulfur emission standards in Valparaíso and San Antonio anchorage zones, compressing the window for non-compliant fuel combustion near population centers. Coastal trades and cruise itineraries are most affected, with operators accelerating marine gasoil substitution or cold-ironing investments to maintain port access.
Spot purchasing is displacing term contracts among midsize bulk carriers calling South American ports. Traders are responding by fragmenting cargo sizes and compressing delivery windows to match vessel scheduling volatility. Argentine grain export seasons and Brazilian iron ore loading cycles concentrate this behavioral shift in commodity shipping corridors.
South America Bunker Fuel Market Segmentation
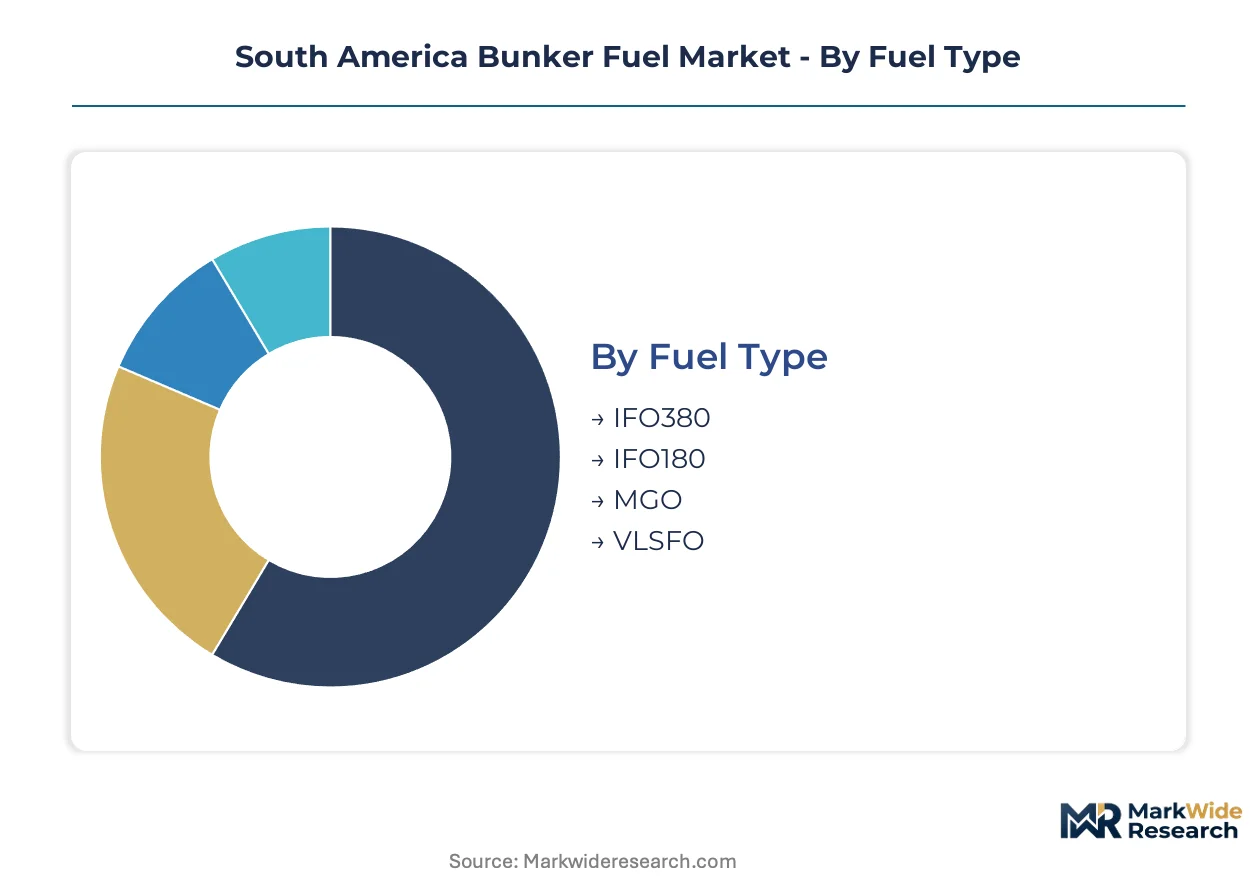
Marine fuel procurement in South America fragments across sulfur compliance tiers, vessel categories, and delivery logistics. Buyers optimize against port congestion, regulatory enforcement intensity, and inventory carrying costs at specific terminals.
Fuel Type:
Product differentiation spans the sulfur-content spectrum from legacy residual fuels to IMO-compliant blends, with viscosity grades determining engine compatibility and emission control area access.
- VLSFO:A 0.50% sulfur maximum residual blend formulated through hydrodesulfurization or sweet crude blending. Demand concentrates at Santos and Rio de Janeiro terminals where container lines with fleet renewal programs require compliant bunkers for trans-Atlantic and Asia-Pacific routes. ANVISA enforcement of port state control inspections eliminates off-spec arbitrage, rewarding certified suppliers with volume concentration.
- MGO:Distillate marine gasoil capped at 0.10% sulfur for emission control areas and coastal trades. Brazilian pre-salt offshore platforms generate concentrated demand along the southeastern coastline where floating production units operate within strict coastal sulfur limits.
- IFO380:High-viscosity residual fuel oil at 380 centistokes, now restricted to vessels with installed scrubber systems. Consumption is compressing as IMO 2020 enforcement eliminates open-loop scrubber discharge in Brazilian waters.
- IFO180:Lower-viscosity residual variant with marginally better cold-flow properties than IFO380. Demand persists among older bulk carriers without scrubber retrofit economics, primarily at secondary Atlantic ports with less stringent enforcement.
Most installed capacity flows through VLSFO blending infrastructure. Expansion is steepest in MGO storage and distribution as coastal emission zones tighten.
End User:
Customer concentration varies by fuel margin, volume predictability, and contract structure, with offshore energy commanding premium pricing against volatile spot shipping markets.
- Commercial Shipping:Container lines, bulk carriers, and tankers operating scheduled liner services or tramp trades. Brazilian iron ore export corridors and Argentine grain loading seasons concentrate bunker demand at specific annual intervals, compressing delivery windows and fragmenting cargo sizes.
- Offshore Platform:Floating production units, drilling rigs, and supply vessels supporting Brazil's pre-salt development. This segment purchases marine gasoil at premium pricing for reliability in coastal emission control zones, with demand anchored to Petrobras exploration schedules.
- Fishing Vessels:Industrial trawlers and coastal fleet operators across Chilean and Peruvian Pacific waters. Fuel procurement remains price-sensitive with limited compliance infrastructure, though IMO standards are extending enforcement to this historically informal segment.
- Recreational Boats:Yachts and cruise operators with intermittent demand at marina facilities. Chile's tightened sulfur standards in Valparaíso and San Antonio anchorage zones accelerate marine gasoil substitution or cold-ironing investments.
Commercial shipping absorbs the largest volume tonnage. Offshore platforms deliver the highest margin per barrel.
Delivery Mode:
Logistics configuration reflects port infrastructure maturity, vessel size constraints, and real-time scheduling volatility across South American terminals.
- Barge:The dominant delivery mechanism at major bunkering hubs, enabling simultaneous cargo operations and fuel transfer. Santos and Rio de Janeiro terminals maintain dedicated barge fleets for container lines with tight port rotation schedules.
- Truck:Essential for secondary ports and inland waterway access, particularly along the Paraná-Paraguay system serving Argentine riverine barge fleets. Limited volumes and higher per-unit costs restrict this mode to smaller vessels and emergency resupply.
- Vessel:Direct ship-to-ship transfer for very large crude carriers and bulk vessels with dedicated bunker schedules. Requires anchorage availability and weather windows, concentrating at deepwater Atlantic terminals.
- Pipeline:Captive infrastructure linking Petrobras refineries to coastal storage terminals. Restricted to Brazilian domestic supply chains with limited third-party access.
Barge deliveries handle the majority of throughput. Truck deployment is climbing fastest as secondary Pacific ports develop VLSFO accessibility.
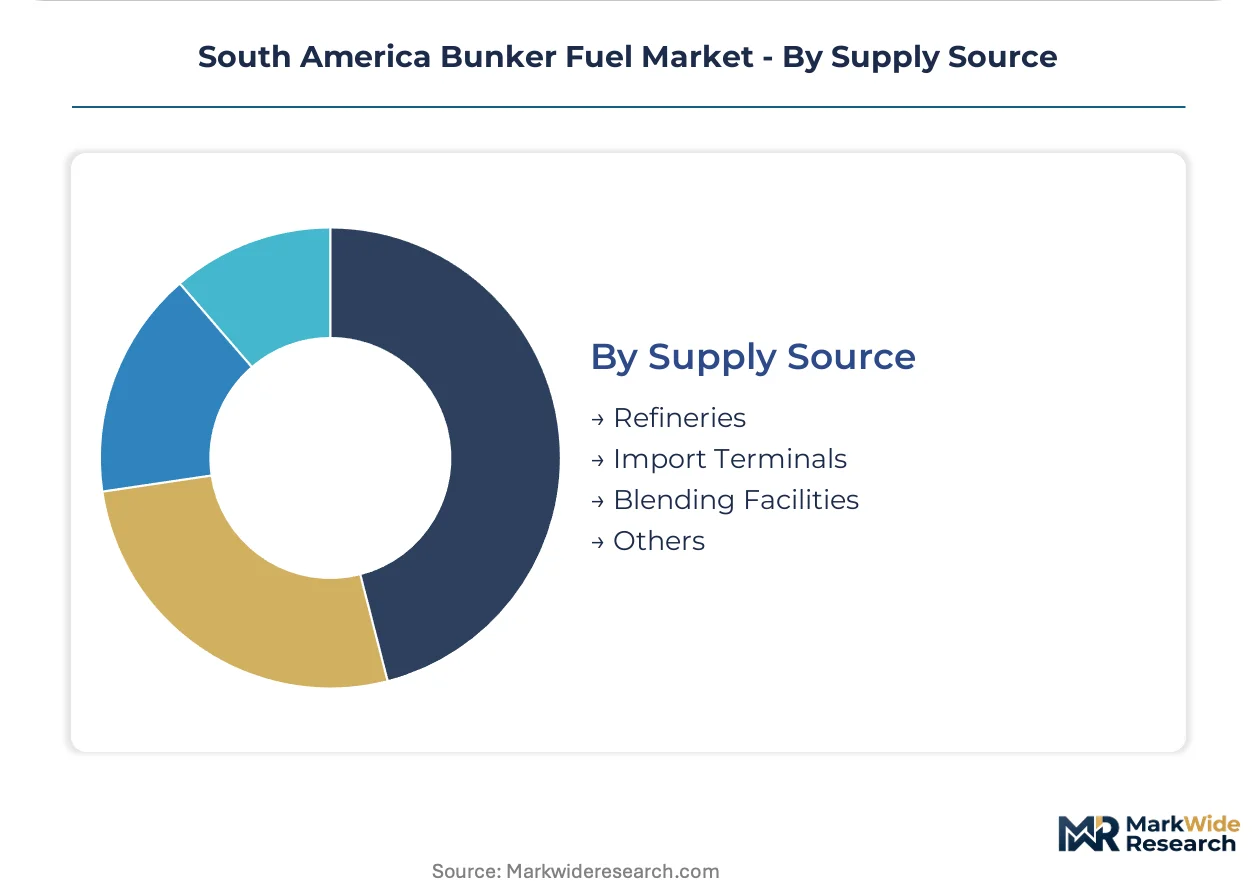
Supply Source:
Upstream configuration determines sulfur compliance certainty, inventory working capital requirements, and geographic coverage radius from production points.
- Refineries:Petrobras integrated coastal facilities anchor Brazilian domestic production, though heavy sour crude slate forces import dependency for sweet blending barrels or hydrodesulfurization investments.
- Blending Facilities:Distributed hubs combining low-sulfur components to achieve IMO-compliant specifications. These facilities are displacing direct refinery supply as traders fragment cargo sizes to match vessel scheduling volatility.
- Import Terminals:Critical for Chile, Peru, and secondary Brazilian ports lacking domestic refining capacity. Vitol and trading houses position traded cargoes through these terminals, concentrating VLSFO availability at Pacific coast hubs.
- Others:Spot market purchases and emergency supply arrangements for vessels diverting from scheduled routes. This residual category captures demand during peak congestion at Santos and Rio de Janeiro when primary terminals reach queue capacity.
Refinery-direct supply retains the largest installed base. Blending facilities are gaining share fastest as distributed hub models replace centralized production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized blending technicians and marine fuel chemists concentrate along Brazil's southeastern coastline, where Petrobras operates integrated refining complexes and independent traders maintain storage terminals. This workforce density supports the continent's largest bunkering infrastructure while creating regional capability gaps at Pacific ports lacking comparable technical depth.
Brazil
Container lines with fleet renewal programs drive VLSFO consumption at Santos and Rio de Janeiro terminals, where dedicated barge fleets serve tight port rotation schedules. ANVISA enforcement of port state control inspections eliminates off-spec fuel arbitrage and rewards certified suppliers with volume concentration. The pre-salt offshore development along the southeastern coast generates concentrated marine gasoil demand from floating production units operating within strict coastal sulfur limits.
Chile
Environmental regulators tighten sulfur emission standards in Valparaíso and San Antonio anchorage zones, accelerating marine gasoil substitution among cruise operators and coastal trades. The country's environmental regulator compresses windows for non-compliant fuel combustion near population centers. Antofagasta and Valparaíso port authorities designate zones for future ammonia bunkering, allowing early infrastructure positioning ahead of regulatory mandates.
Argentina
Paraná-Paraguay waterway barge fleets currently rely on high-sulfur residual fuels, presenting conversion opportunity as IMO standards extend to inland shipping. Argentine grain export seasons concentrate bunker demand at specific annual intervals, compressing delivery windows and fragmenting cargo sizes. Buenos Aires and Rosario terminals handle riverine trade volumes while secondary Atlantic ports absorb tramp shipping volatility.
Peru
Callao and Matarani terminals remain underdeveloped relative to throughput potential, offering first-mover positioning for VLSFO storage and blending investments. Import-dependent markets rely on trading houses positioning cargoes through Pacific coast hubs. Lima's commercial shipping corridors connect Andean mining exports to Asian markets, pulling compliant bunker volumes upward as vessel operators phase out non-compliant stocks.
South America Bunker Fuel Market Competitive Landscape
Top-tier vendors anchor integrated supply networks, while mid-tier traders compete through cargo fragmentation and delivery flexibility. The market structure reflects a bifurcation between refinery-direct producers with captive infrastructure and independent distributors relying on imported blending components. Two strategic archetypes dominate: integrated oil companies with coastal refining assets, and global trading houses with multi-port supply networks. Competitive moves concentrate on storage capacity expansion at underdeveloped Pacific terminals and strategic partnerships with container lines for term offtake agreements.
Within the integrated producer tier, Petrobras anchors Brazilian domestic production through its coastal refining system, while Bunker Holding A/S exemplifies the multi-port distributor archetype with coverage across Brazilian and Argentine terminals. Vitol Holding BV occupies a position among trading houses positioning imported cargoes into supply-constrained Pacific markets. These three companies represent the structural split between captive production, distributed blending, and traded supply that defines competitive positioning across South American bunkering corridors.
| Leading Market Players |
|---|
| Bunker Holding A/S |
| Peninsula Petroleum Ltd |
| Petrobras |
| TotalEnergies SA |
| Chevron Corporation |
| Vitol Holding BV |
| World Fuel Services Corp |
| AP Moeller Maersk A/S |
| Monjasa Holding A/S |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers like Petrobras anchor Brazilian supply through captive coastal refining, translating vertical integration into pricing discipline that resists spot-market volatility at Santos and Rio de Janeiro terminals. This ownership pattern compresses margin leakage while concentrating procurement leverage among certified suppliers rewarded by ANVISA enforcement.
Pricing Analysis
Bundled barge delivery with sulfur certification commands premium positioning against unbundled truck-delivered volumes at secondary Pacific ports. Three-tier pricing structure across premium VLSFO, standard marine gasoil, and residual IFO grades reflects sulfur compliance certainty and delivery reliability. Pricing pressure stems from crude sulfur content mismatch forcing sweet barrel imports. Container lines show lowest price sensitivity; fishing fleets exhibit highest.
Supply Chain Analysis
Reverse-logistics flows for off-spec fuel returns and tank cleaning residues concentrate at Brazilian blending facilities requiring reprocessing. Supply draws from Brazil, Singapore, and US Gulf Coast refining hubs. Feedstock dependencies include low-sulfur crude, vacuum gasoil, and marine diesel blendstocks. Single-source vulnerability runs through Petrobras pipeline infrastructure. Distribution runs through dedicated barge fleets at major hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America bunker fuel market functions as a stable compounder anchored by IMO regulatory ratchets that guarantee compliant fuel demand expansion regardless of shipping cycle volatility.
For Market Incumbents: Deepen hydrodesulfurization investments at Brazilian coastal refineries to capture VLSFO margin expansion as ANVISA enforcement eliminates off-spec arbitrage. Expand storage tank segregation capacity to maintain parallel high-sulfur and low-sulfur inventories without cross-contamination risk. For New Entrants and Emerging Players: ANVISA quality enforcement in Brazil opens a window for certified blending specialists to capture volume concentration from disqualified competitors. Target Peruvian Pacific hub development at Callao and Matarani terminals for first-mover VLSFO infrastructure positioning. Lead with digital fuel management platform partnerships to differentiate procurement workflow integration. For Investors and Strategic Acquirers: Valuations sit cheapest among import-terminal operators in supply-constrained Chilean and Peruvian markets. Long-term viability rests on contracted offtake structures with container lines facing fleet renewal mandates. Monitor ammonia bunkering pilot project announcements at Antofagasta and Valparaíso as inflection signal for residual fuel demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| VLSFO Blending Capacity Expansion | Captures IMO 2020 compliance premium at Santos and Rio de Janeiro terminals. |
| Digital Fuel Management Platform Deployment | Integrates real-time ANVISA certification tracking for container line procurement workflows. |
| Pacific Coast Storage Terminal Development | Positions imported cargoes into supply-constrained Chilean and Peruvian markets. |
| Marine Gasoil Distribution Network Buildout | Serves Brazilian pre-salt offshore platforms operating within strict coastal sulfur limits. |
| Ammonia Bunkering Infrastructure Zoning | Antofagasta and Valparaíso port authorities designate future-compatible terminal real estate. |
Research Methodology
Coverage spans Brazil, Chile, Argentina, and Peru, with primary inputs from each territory's bunkering corridor. The analysis combines structured interviews with refinery operations directors, marine fuel traders, port authority planners, and container line procurement officers with secondary validation through customs trade data, ANVISA enforcement records, and IMO compliance filings. Bottom-up volume triangulation against top-down macroeconomic drivers ensures forecast robustness.
Granularity-level modeling disaggregates projections across fuel type, end-user segment, delivery mode, and supply source dimensions throughout the forecast period. CAGRs derive from regression analysis against vessel fleet renewal schedules and pre-salt offshore development timelines. Industry-specific inputs include scrubber installation rates and Panama Canal transit pattern shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alternative fuel breakthroughs or sulfur cap enforcement relaxation. Practitioners should monitor methanol and ammonia pilot project scale-up rates for early demand displacement signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Oil & Gas Lubricants Market
Fuels
Diesel As Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Europe Gas Market
Fuels
Palm Methyl Ester Market
Fuels
LNG As a Fuel Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
India Petrol Station Market
Fuels
Anthracite Coal Mining Market
Fuels
Underground Coal Gasification Market
Fuels
Aviation Fuel Additives Market
Fuels
LPG Gas Cylinder Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
LPG Tanker Market