
 Global Fuel Ethanol Market | 2026-2036
Global Fuel Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel Ethanol Market Analysis
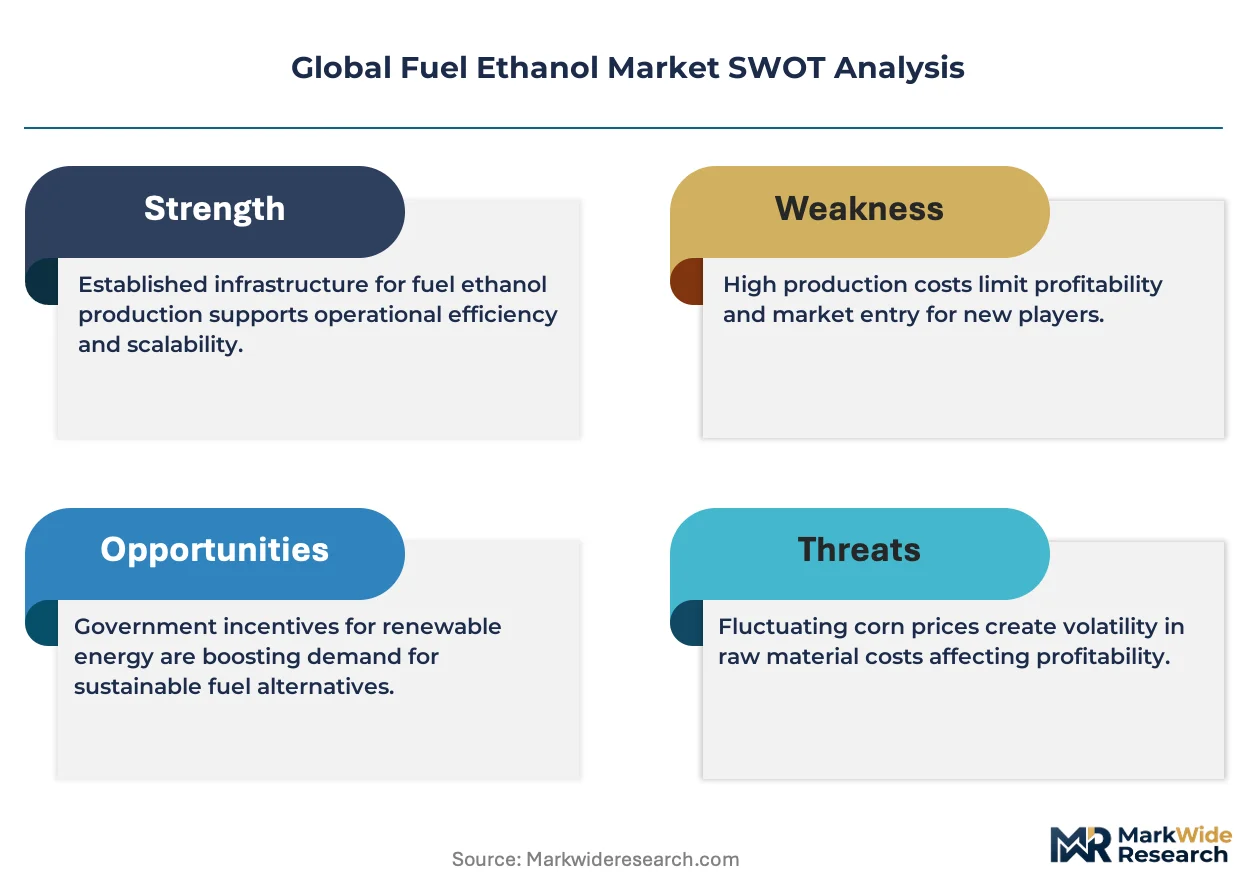
The US Renewable Fuel Standard is broadening the cost-of-entry calculus for new market participants by escalating renewable volume obligations and tightening compliance credit markets. POET LLC leverages its vertical integration across corn procurement, fermentation, and distribution to sustain margin capture across the Midwest. Raízen Energia S.A. anchors its position through sugarcane-to-ethanol integration in Brazil, while Valero Energy Corporation competes via refinery-adjacent production assets that optimize logistics and offtake.
Fuel ethanol denotes hydrous or anhydrous ethyl alcohol blended with gasoline at ratios from E10 to E100, produced primarily through yeast fermentation of starch or sucrose feedstocks with distillation and dehydration to meet fuel-grade specifications. Its primary commercial purpose centers on octane enhancement and tailpipe emissions reduction in spark-ignition engines. Cellulosic ethanol remains the fastest-growing production method as second-generation pathways mature, though fermentation from corn and sugarcane still dominates installed capacity and margin pools. Fuel-grade ethanol captures the largest volume share, while bioethanol certification tiers command premium positioning in regulated jurisdictions.
The US EPA administers renewable fuel mandates that directly shape annual blending obligations and compliance credit pricing. Brazil's ANP governs ethanol-gasoline blending ratios and flex-fuel vehicle specifications, while the EU Green Deal and F-Gas Regulation are redirecting European demand toward lower-carbon biofuel pathways. Stakeholders must monitor feedstock cost volatility, policy continuity across electoral cycles, and cellulosic technology scale-up as the central variables determining competitive positioning.
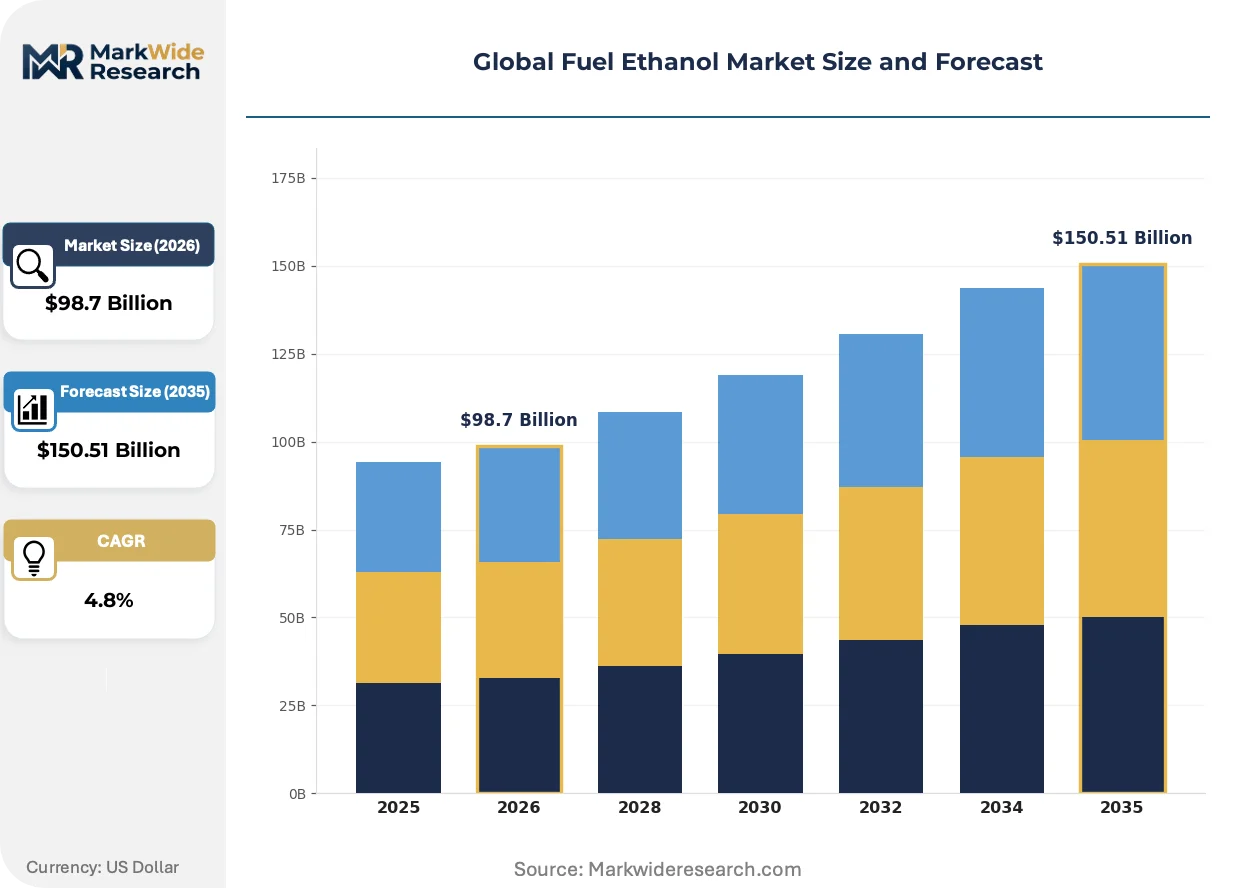
Market Dynamics
Cellulosic ethanol scale-up is compressing the cost premium against first-generation pathways while Brazil's flex-fuel fleet expansion and the US EPA's tightening renewable volume obligations create divergent regional demand pulls.
Growth Catalysts
- US EPA Renewable Fuel Standard:Escalating annual volume obligations and constrained compliance credit markets tighten the supply-demand balance for conventional and advanced biofuels alike.
- Brazil flex-fuel vehicle penetration:Sugar-based ethanol economics and ANP-mandated blending floors sustain structural offtake even during gasoline price volatility.
- Cellulosic enzyme cost reduction:Second-generation hydrolysis technology is narrowing the production cost gap against corn and sugarcane fermentation.
Market Restraints
- Corn price volatility:Feedstock cost swings in the US Midwest directly compress producer margins without long-term procurement hedges.
- Blending wall constraints:Legacy vehicle fleet compatibility limits gasoline-ethanol ratios below infrastructure and engine tolerance thresholds.
- Electrification substitution:Battery electric vehicle sales growth in the EU and China erodes addressable fuel pool for spark-ignition ethanol blends.
Strategic Opportunities
- India ethanol blending program:The country's 20% blending target by 2025 and sugarcane surplus create import substitution potential for domestic producers.
- Sustainable aviation fuel pathway:Alcohol-to-jet technology convergence opens ethanol-to-SAF conversion for aviation decarbonization mandates.
- Carbon intensity scoring:California's LCFS and EU RED III certification tiers reward low-CI ethanol with premium credit values.
Industry Challenges
- Cellulosic scale-up engineering:Pretreatment reactor reliability and enzyme dosing optimization require specialized biochemical process talent scarce outside pilot facilities.
- Feedstock logistics integration:Seasonal harvest windows and perishable biomass storage complicate year-round production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel Ethanol Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Denatured Ethanol, Undenatured Ethanol, Fuel-grade Ethanol, Bioethanol End Use: Automotive, Aviation, Industrial, Chemical Manufacturing Distribution Channel: Direct Sales, Retail, Online, Wholesale Production Method: Fermentation, Synthetic, Aqueous Ethanol, Cellulosic Ethanol |
| Companies Covered | POET LLC, Archer Daniels Midland Company, Raízen Energia S.A., Cargill Incorporated, ADM, Tereos S.A., Valero Energy Corporation, DuPont, CropEnergies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel Ethanol Market Emerging Trajectories
Yeast strain engineering and consolidated bioprocessing are collapsing unit capital requirements while regulatory carbon accounting rules reshape which production pathways capture premium credit markets.
Consolidated bioprocessing is electrifying the cellulosic ethanol economics by combining enzyme production, biomass hydrolysis, and fermentation in a single reactor vessel. POET-DSM and Clariant are deploying CBP configurations at commercial scale in Iowa and Romania respectively. This integration is compressing both operating expenditure and capital intensity for second-generation facilities.
The EU F-Gas Regulation and RED III sustainability criteria are redirecting European biofuel procurement toward certified low-carbon intensity supply chains. Fuel suppliers must now document greenhouse gas savings across cultivation, processing, and transport. This compliance burden favors Brazilian sugarcane ethanol and EU-waste-based pathways over US corn ethanol in Northwest European ports.
Fleet operators and fuel retailers are consolidating procurement through long-term offtake agreements indexed to carbon credit values rather than commodity ethanol spot markets. Major logistics companies in California and the Netherlands are locking in decade-long supply contracts with fixed carbon intensity guarantees. This shift is visible most acutely in the heavy-duty trucking corridors connecting Rotterdam to the German Ruhr and Los Angeles to Phoenix.
Global Fuel Ethanol Market Segmentation
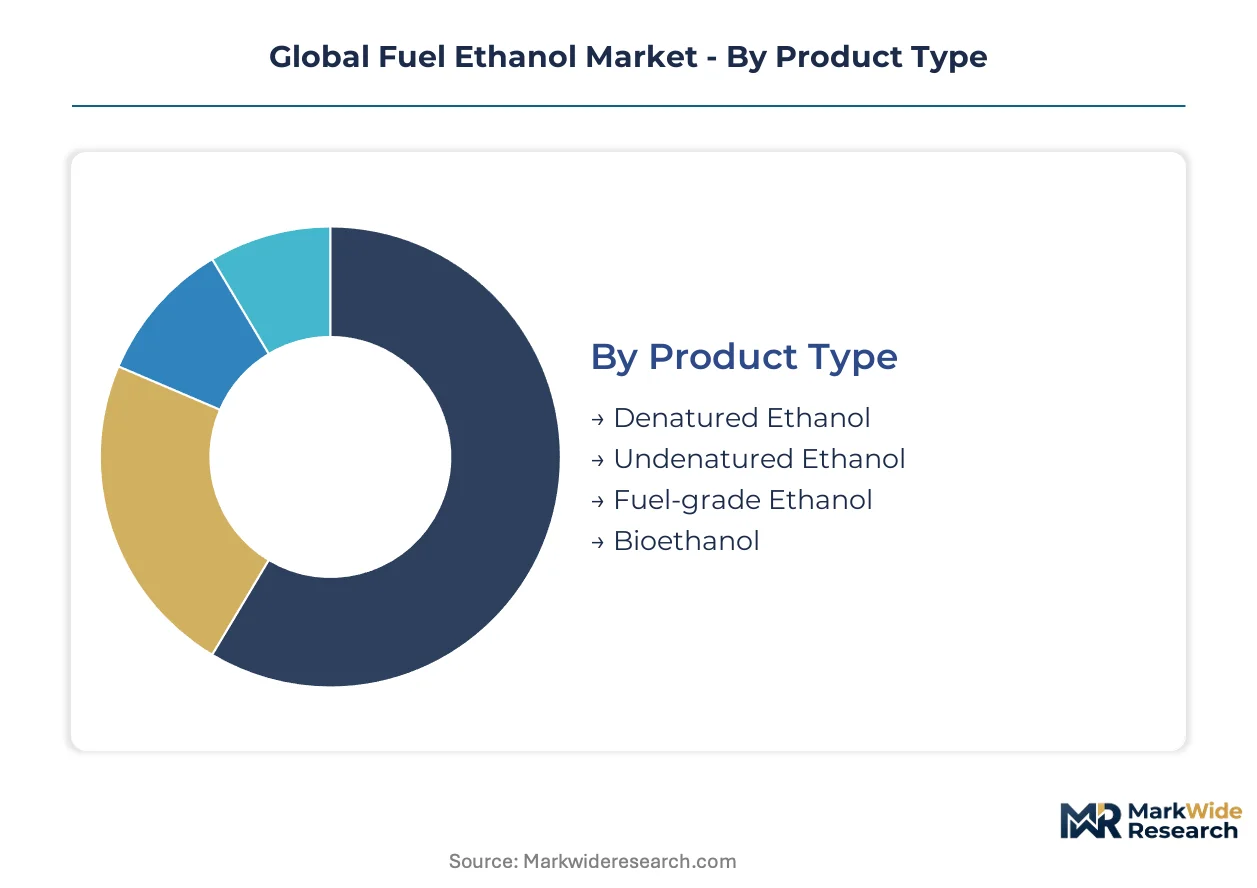
Fuel ethanol markets fragment across product specifications, end-use applications, and production technologies that each carry distinct margin profiles and regulatory requirements. Understanding these segment boundaries reveals where capital deployment captures premium returns versus commodity exposure.
Product Type:
Standardization dominates fuel-grade categories while specialty denatured formulations command specification premiums in industrial offtake.
- Fuel-grade Ethanol:Anhydrous ethanol meeting ASTM D4806 or EN 15376 specifications for gasoline blending at E10 through E85 ratios. Demand concentrates in Brazil's flex-fuel fleet and US Midwest retail terminals where EPA Renewable Fuel Standard compliance obligations sustain structural offtake.
- Bioethanol:Certified low-carbon intensity ethanol produced under EU RED III or California LCFS sustainability criteria, commanding credit-linked premiums in Rotterdam and Los Angeles fuel terminals. Certification tiers separate Brazilian sugarcane pathways from US corn ethanol in Northwest European procurement.
- Denatured Ethanol:Ethanol rendered unfit for consumption through denaturant addition, primarily serving industrial solvent and chemical feedstock applications.
- Undenatured Ethanol:Potable-grade ethanol diverted to fuel use in specific regulatory jurisdictions with distinct tax treatment.
Leading the category by volume: Fuel-grade Ethanol. Growing fastest: Bioethanol.
End Use:
Application maturity separates established automotive blending from emerging aviation pathways with divergent certification timelines.
- Automotive:Spark-ignition engine fuel blending from E10 to E100, anchored by Brazil's flex-fuel vehicle fleet exceeding 80% of new car sales and US EPA-mandated renewable volume obligations. ANP blending floors and RFS compliance credits sustain demand through gasoline price cycles.
- Aviation:Alcohol-to-jet conversion pathways for sustainable aviation fuel, currently scaling through ASTM D7566 annex certification with offtake commitments from EU and US carriers facing ICAO CORSIA compliance deadlines.
- Industrial:Solvent, disinfectant, and extraction applications with lower volume but higher margin stability.
- Chemical Manufacturing:Ethylene and derivative production feedstock competing with naphtha economics.
Automotive absorbs the dominant share. Aviation represents the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect bulk logistics density versus fragmented retail terminal access.
- Direct Sales:Long-term offtake agreements between producers and integrated oil companies, refiners, or fleet operators. California and Netherlands logistics corridors increasingly index contracts to carbon credit values rather than spot ethanol pricing.
- Wholesale:Terminal rack sales to independent fuel distributors and jobbers across US PADD regions and Brazilian state fuel networks.
- Retail:Branded E85 and flex-fuel pump installations at service stations.
- Online:Digital procurement platforms for industrial and specialty chemical buyers.
Direct Sales leads by contract value. Wholesale moves the largest physical volumes.
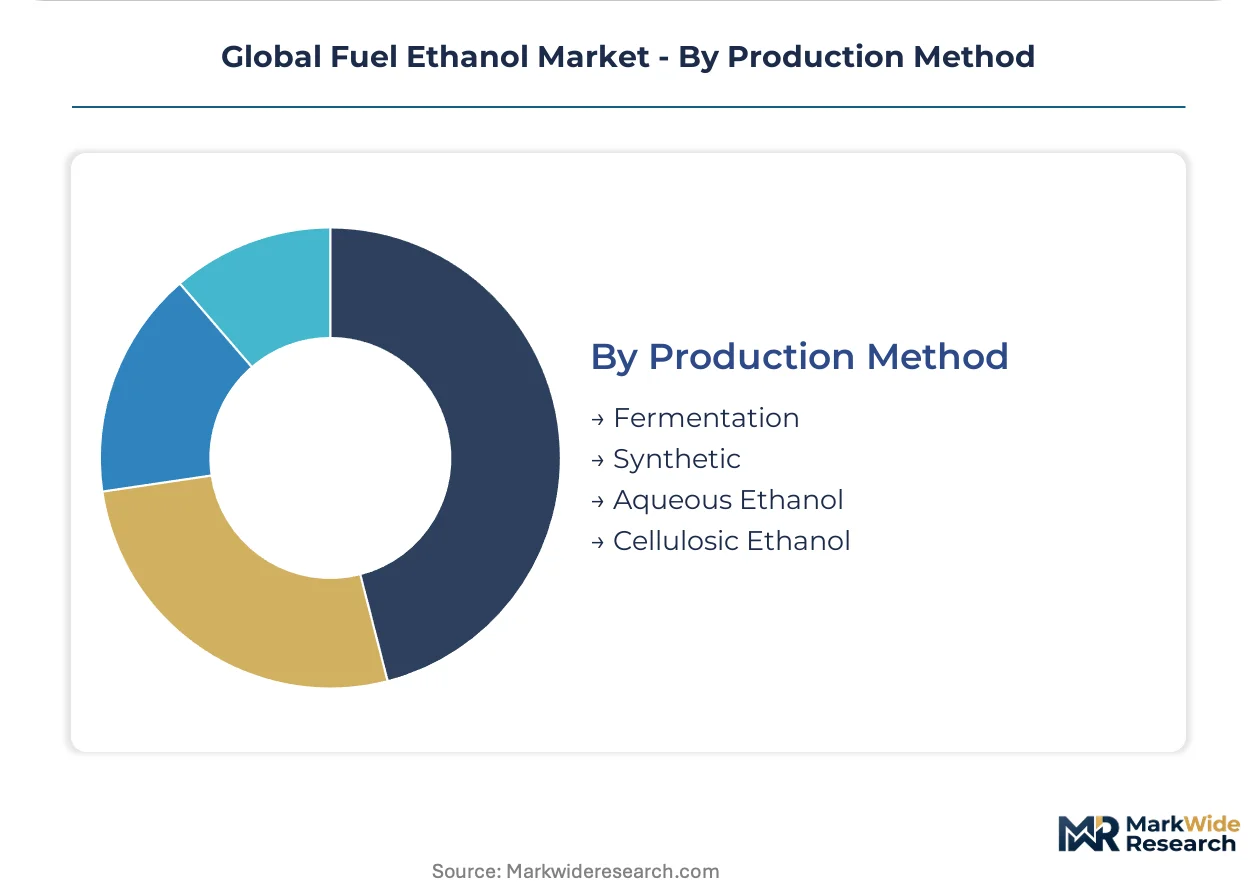
Production Method:
Technology maturity creates a cost curve from first-generation fermentation to second-generation cellulosic pathways still scaling commercial reliability.
- Cellulosic Ethanol:Enzymatic hydrolysis of lignocellulosic feedstocks followed by fermentation, with consolidated bioprocessing configurations deploying in Iowa and Romania. Enzyme cost reduction and pretreatment reactor optimization are narrowing the production cost gap against starch-based pathways.
- Fermentation:Yeast-based conversion of corn starch or sugarcane sucrose, dominating installed global capacity through POET's Midwest network and Raízen's Brazilian sugarcane integration.
- Synthetic:Catalytic conversion of syngas or captured CO2, currently at pilot scale.
- Aqueous Ethanol:Hydrous ethanol for E100 direct combustion in Brazilian flex-fuel engines.
Fermentation leads by installed capacity. Cellulosic Ethanol is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's ethanol-producing zones in São Paulo state and the US Midwest corn belt function as the primary tax-advantaged production corridors, concentrating capacity near feedstock sources and blending infrastructure.
United States
Iowa and Illinois ethanol plants process over half of US corn ethanol output, supplying E10 blending mandates across PADD II and PADD III terminals. The EPA's Renewable Fuel Standard escalates annual volume obligations through 2025, tightening compliance credit markets. POET operates the world's largest biorefinery complex in Sioux Falls, South Dakota, consolidating fermentation capacity and rail distribution.
Brazil
São Paulo state's sugarcane belt generates approximately 60% of national ethanol production, feeding flex-fuel vehicle demand exceeding 80% of new car sales. ANP blending floors mandate minimum ethanol ratios regardless of gasoline price cycles. Raízen Energia S.A. anchors the Paulínia-Santos corridor, integrating sugarcane crushing with coastal export terminals.
India
Maharashtra and Uttar Pradesh sugar mills divert molasses and cane juice to ethanol under the 20% blending target by 2025. The central government's Ethanol Blended Petrol program offers guaranteed offtake pricing through Oil Marketing Companies. Reliance Industries and Indian Oil Corporation are contracting dedicated ethanol storage at Jawaharlal Nehru Port Trust near Mumbai.
Germany
Lower Saxony and Saxony-Anhalt host the EU's largest grain ethanol cluster, supplying RED III-compliant biofuel to Rotterdam-Amsterdam-Rhine corridor terminals. The EU F-Gas Regulation and delegated acts on renewable energy sustainability criteria restrict US corn ethanol access. CropEnergies AG operates the Zeitz biorefinery, converting wheat and corn to fuel-grade ethanol with integrated CO2 capture.
China
Heilongjiang and Jilin provinces in Northeast China concentrate cassava and corn ethanol capacity for E10 blending in coastal demand centers. The National Energy Administration's biofuel development plan targets 10 million tonnes ethanol consumption by 2025. COFCO Biochemical operates the Zhaodong facility, linking grain procurement to Harbin-Dalian rail distribution.
Global Fuel Ethanol Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three structural tiers. Integrated agribusiness-trading houses control upstream feedstock procurement and downstream distribution networks. Independent biorefinery operators concentrate on fermentation technology optimization and regional logistics efficiency. Petroleum refiners leverage existing fuel terminal access for blending infrastructure. Dominant competitive moves include backward integration into captive grain and sugarcane supply, plus strategic partnerships with automotive OEMs for flex-fuel vehicle certification.
Among US-based agribusiness conglomerates, Archer Daniels Midland Company and Cargill Incorporated occupy positions spanning grain origination, ethanol production, and fuel distribution. POET LLC exemplifies the pure-play biorefinery archetype with concentrated Midwest capacity. Raízen Energia S.A. anchors the Brazilian sugarcane-ethanol integration model. Valero Energy Corporation represents petroleum refiner participation through refinery-adjacent production assets.
| Leading Market Players |
|---|
| POET LLC |
| Archer Daniels Midland Company |
| Raízen Energia S.A. |
| Cargill Incorporated |
| ADM |
| Tereos S.A. |
| Valero Energy Corporation |
| DuPont |
| CropEnergies AG |
| Others |
Supply Flow & Price Mechanics
Corn futures on the Chicago Board of Trade cascade through Midwest ethanol plant economics into three distinct pricing tiers: contract-indexed supply for RFS-compliant blenders, spot terminal rack sales, and carbon-credit-linked offtake for California LCFS and EU RED III markets. Feedstock cost volatility compresses margins at starch-based facilities while sugarcane ethanol from Brazil commands premiums in Rotterdam based on certified greenhouse gas savings.
Pricing Analysis
Short lead-time premiums attach to certified low-carbon intensity ethanol with documented RED III or LCFS compliance, while spot inventory at US Gulf Coast terminals trades at discounts due to RIN price volatility. Contract-based long-term offtake dominates, with price differentiation driven by carbon intensity scores and volume scale commitments. Cost compression in conventional corn ethanol is intensifying because enzyme and natural gas inputs face sustained inflation. Fleet operators with decarbonization mandates show least price sensitivity; independent fuel distributors in fragmented state markets exhibit highest.
Supply Chain Analysis
EU RED III and California LCFS certification gating restricts eligible supply to Brazilian sugarcane ethanol, US corn ethanol with documented cultivation emissions, and EU waste-based pathways. Geographic supply concentrates in Brazil, the United States, and India. Raw material dependencies center on corn starch, sugarcane sucrose, and cellulosic biomass feedstocks. Single-source vulnerability runs through enzyme suppliers for second-generation hydrolysis. Distribution runs through coastal export terminals, rail-fed inland blending facilities, and barge networks along the Mississippi and Rhine corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US EPA's escalating Renewable Fuel Standard volume obligations construct a compliance-cost barrier that entrenches incumbent producers with established RIN generation infrastructure and long-term offtake relationships.
For Market Incumbents:Cement market position through backward integration into captive corn and sugarcane supply basins, locking in feedstock cost stability against Midwest price swings. Expand cellulosic capacity in Iowa and Romania to capture premium credit markets as enzyme costs decline. Electrification of the automotive fleet poses the central demand threat to E10 blending volumes.
For New Entrants and Emerging Players:India's Ethanol Blended Petrol program opens a window for domestic producers to capture import substitution value under guaranteed offtake pricing through Oil Marketing Companies. Target Maharashtra and Uttar Pradesh sugar mill retrofits for molasses-to-ethanol conversion. Pursue alcohol-to-jet certification for sustainable aviation fuel as the most penetrable end-use expansion. Lead with carbon intensity scoring expertise to differentiate in European procurement.
For Investors and Strategic Acquirers:The window for entry favors cellulosic technology specialists with consolidated bioprocessing capabilities and proven pretreatment reactor reliability. Mid-term viability hinges on ethanol-to-SAF conversion technology maturation and aviation offtake contract visibility. Watch ASTM D7566 annex certification timelines for alcohol-to-jet pathways as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn procurement hedges at POET's Sioux Falls complex insulate margin capture against CBOT volatility. |
| Cellulosic Capacity Scale-Up | Consolidated bioprocessing deployments in Iowa and Romania compress unit capital requirements for second-generation ethanol. |
| Carbon Certification Investment | RED III and LCFS compliance documentation unlocks premium pricing in Rotterdam and Los Angeles fuel terminals. |
| Alcohol-to-Jet Technology Licensing | ASTM D7566 pathway certification positions ethanol producers for aviation decarbonization mandates under CORSIA. |
| Long-Term Offtake Agreement | Decade-long contracts indexed to carbon credit values rather than spot ethanol pricing secure revenue visibility. |
Methodological Framework
Multi-period observation of EPA renewable volume obligation trajectories, ANP blending ratio mandates, and EU RED III delegated acts anchored the trend analysis, supplemented by interviews with biorefinery operations managers, fuel supply procurement leads at integrated oil companies, agricultural commodity traders, and regulatory compliance officers at fuel terminals. Secondary validation drew from EIA fuel ethanol production data, EPA RIN transaction reports, ANP statistical bulletins, and EU renewable energy progress databases. Bottom-up plant-level capacity assessments triangulated against top-down regional demand modeling.
Segment-weighting across production method, end-use application, and geographic regulatory cluster shaped volume and value projections across the analysis window. The analytical framework modeled fuel-grade versus bioethanol certification tiers, automotive versus aviation demand splits, and direct sales versus wholesale channel economics. CAGRs were derived from feedstock cost curve trajectories, policy mandate enforcement timelines, and cellulosic technology adoption rates. Forecast inputs incorporated flex-fuel vehicle sales penetration in Brazil and ethanol blending target compliance in India.
The model assumes a particular technology adoption path; alternative pathways for consolidated bioprocessing or synthetic ethanol catalysis would alter the outlook for second-generation cost competitiveness. Forecasts reflect assumptions regarding EPA rulemaking continuity, Brazilian sugarcane harvest yields, and cellulosic enzyme cost reduction trajectories. A model refresh is warranted upon material change in US renewable volume obligation stringency or EU carbon border adjustment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline Market
Fuels
Australia Coal Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Fuel Analyzer Market
Fuels
North America Wood Pellet Market
Fuels
City Gas Distribution Market
Fuels
Smart Gas Solutions Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
North America LNG Bunkering Market
Fuels
Industrial Fuel Filter Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Palm Methyl Ester Market
Fuels
Fuel Conditioning System Market
Fuels
Marine Fuel Filter Market