
 Saudi Arabia Fuel Station Market | 2026-2036
Saudi Arabia Fuel Station Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Fuel Station Market Analytics
Fleet procurement among logistics companies and government entities is consolidating around long-term supply agreements with major fuel station networks. Saudi Arabian Oil Company leverages its captive crude supply and downstream refining assets to dominate retail fuel distribution. Aldrees Petroleum and Transport Services Co. anchors its position through an extensive eastern province station network and integrated transport services. TotalEnergies competes by extending European fuel retail expertise into premium service center formats across urban Saudi markets.
A fuel station constitutes a fixed retail facility designed for the storage, dispensing, and sale of motor fuels to vehicles, typically incorporating underground storage tanks with 20,000-60,000 liter capacity, multi-product dispensers, vapor recovery systems, and integrated point-of-sale infrastructure. These facilities serve as critical nodes in petroleum product distribution chains, bridging bulk terminal supply with end-consumer demand for transportation energy. Full-service and self-service formats remain the revenue backbone, though electric charging infrastructure represents the fastest-growing segment as automakers accelerate battery-electric vehicle introductions. Conventional stations still occupy the majority of capital deployed, while express outlets gain traction along highway corridors serving commercial fleets with high-throughput, limited-amenity designs.
SFDA oversees fuel station safety standards and hazardous materials handling protocols, while SASO enforces fuel quality specifications and dispenser calibration accuracy across the Kingdom. MOHAP coordinates environmental compliance for station siting near populated areas, collectively raising capital requirements for new entrants. Stakeholders must monitor the pace of electric charging infrastructure mandates and assess whether hybrid fuel-retail models or dedicated energy transition formats offer superior returns under evolving regulatory frameworks.
Market Dynamics
Downstream integration by national oil companies and SASO fuel quality mandates are compressing margins for independent operators while accelerating infrastructure modernization across the Kingdom's retail fuel network.
Growth Catalysts
- Logistics Fleet Consolidation:Commercial transport operators along the Riyadh-Jeddah-Dammam corridor are signing multi-year fuel supply contracts with station networks, locking in volume commitments that stabilize revenue streams for major operators.
- SASO Quality Mandates:The Saudi Standards, Metrology and Quality Organization's dispenser calibration and fuel specification requirements are forcing infrastructure upgrades that improve operational efficiency and reduce evaporative losses.
- Jubail Industrial Expansion:Heavy freight traffic serving petrochemical and manufacturing complexes near Jubail Industrial City is generating sustained demand for high-throughput fueling facilities with commercial-grade throughput capacity.
Market Restraints
- Crude Supply Concentration:Saudi Aramco's captive control over domestic crude allocation and refined product supply limits independent retailers' bargaining power and sourcing flexibility.
- Underground Tank Replacement Cycles:SFDA-mandated safety inspections and corrosion-monitoring requirements for 20,000-60,000 liter storage systems impose recurring capital burdens on aging station portfolios.
- Electric Vehicle Substitution:Battery-electric vehicle introductions by regional distributors are compressing long-term demand projections for conventional gasoline and diesel retail volumes.
Strategic Opportunities
- Eastern Province Network Gaps:Secondary corridors connecting Dammam to smaller industrial zones remain underserved by premium-amenity fuel stations, creating white space for differentiated service formats.
- Hybrid Energy Retail Convergence:Co-located DC fast charging and conventional fuel dispensing infrastructure is attracting automaker partnership investments for pilot sites in Riyadh and Jeddah.
- SFDA Safety Compliance Services:Third-party hazardous materials handling certification and vapor recovery system auditing represents an emerging ancillary revenue stream for technical service providers.
Industry Challenges
- Skilled Technician Scarcity:SFDA-certified hazardous materials handling specialists and automated dispenser maintenance engineers command premium wages, constraining expansion timelines for new station builds.
- Legacy POS Integration Complexity:Petroleum product inventory management systems require costly middleware development to interface with modern payment platforms and fleet card networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Fuel Station Market |
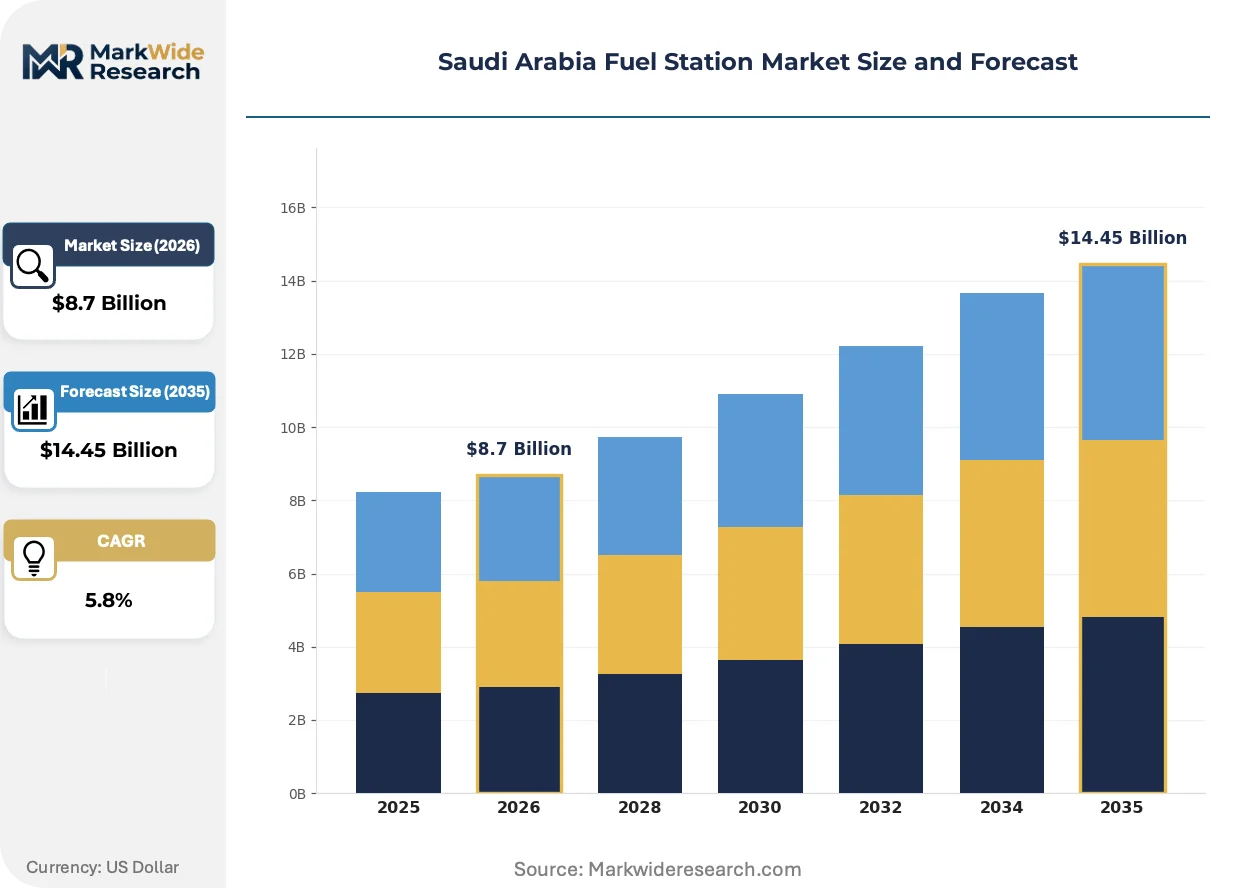
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service, Self-Service, Automated, Mobile Refueling Fuel Type: Petrol, Diesel, Compressed Natural Gas, Electric Charging Infrastructure: Conventional Stations, Express Outlets, Superstations, Service Centers Customer Type: Individual Consumers, Commercial Fleets, Logistics Companies, Government Entities |
| Companies Covered | Saudi Arabian Oil Company, Mazaya Fuel, Aldrees Petroleum and Transport Services Co., TotalEnergies, NAFT Services Company Limited, Saudi Automotive Services Co., J-Oil, ADNOC Distribution, Petromin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Fuel Station Market Evolving Landscape
Digital payment infrastructure and energy transition hardware are reconfiguring station design specifications, while regulatory pressure on fuel quality and safety systems accelerates capital deployment into monitoring technologies.
Advanced vapor recovery systems with real-time emission monitoring are integrating into new station builds across urban Saudi markets. SFDA is mandating Stage II recovery equipment for facilities near populated areas, compelling operators to retrofit existing sites. This technology is integrating environmental compliance with operational data streams, enabling predictive maintenance and reducing inspection failure rates.
SASO's updated fuel quality specifications and dispenser calibration accuracy standards are tightening measurement tolerances for retail fuel transactions. Non-compliant stations face operational suspension until corrective action verification. Retail networks in Riyadh and Jeddah are responding by deploying automated calibration scheduling systems and third-party audit contracts.
Commercial fleet operators are consolidating fuel purchasing through centralized procurement platforms that aggregate volume across multiple vehicle classes. Long-term supply agreements with fixed-price components are displacing spot-market purchasing for logistics companies serving Jubail Industrial City. This concentration is most visible among government entities and petrochemical transport contractors negotiating multi-year network access contracts.
Saudi Arabia Fuel Station Market Segmentation
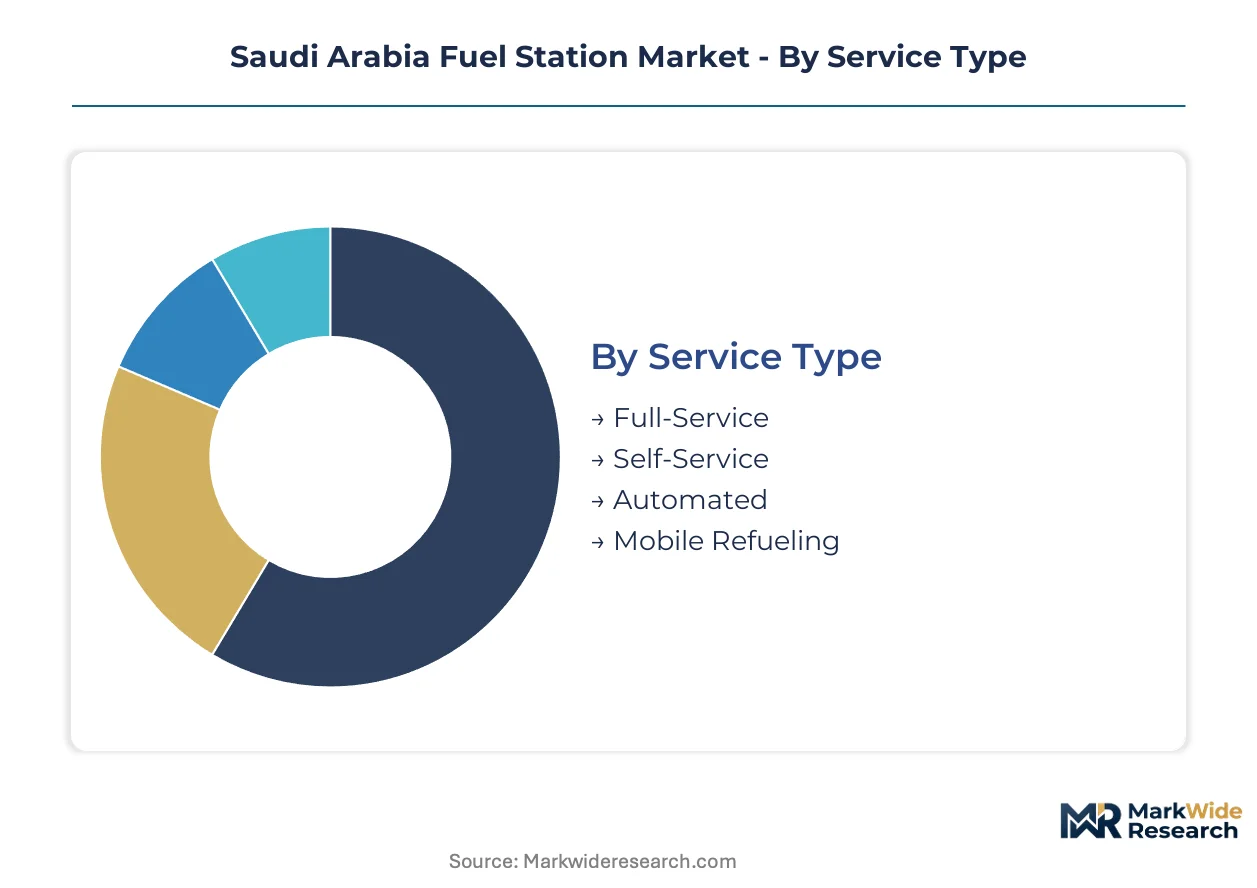
Segmentation reveals how capital allocation and regulatory pressure concentrate across distinct operational models in Saudi Arabia's fuel retail network. Service formats, fuel technologies, infrastructure scales, and customer categories each carry different compliance burdens and margin profiles that shape operator strategy.
Service Type:
Standalone full-service operations dominate urban corridors where labor costs remain manageable, while embedded automated and mobile formats integrate into broader logistics and fleet management systems.
- Full-Service:Attendant-operated dispensing with payment assistance and vehicle checks remains prevalent along the Riyadh-Jeddah-Dammam corridor where consumer preference for personal assistance persists. SFDA safety protocols require trained personnel for hazardous materials handling, reinforcing this format's regulatory alignment.
- Self-Service:Card-activated dispensers with minimal on-site staffing reduce operating costs at high-volume locations. Retail networks near Jubail Industrial City favor this format for 24-hour commercial fleet access with lower per-transaction overhead.
- Automated:Unmanned facilities with remote monitoring and automated payment reconciliation suit remote highway locations where staffing logistics prove prohibitive.
- Mobile Refueling:Tanker-delivered direct-to-vehicle service serves construction sites and mining operations with immobile or difficult-to-move equipment fleets.
Full-Service leads volumes today; Automated is gaining share fastest.
Fuel Type:
Cost tier differentiation separates mature commodity fuels from emerging alternatives requiring infrastructure retrofit and regulatory accommodation.
- Petrol:91 and 95 octane grades distributed through multi-product dispensers constitute the revenue foundation for retail networks across urban Saudi markets. SASO octane rating specifications and additive mandates require continuous quality testing at terminal and station levels.
- Diesel:Ultra-low sulfur diesel for commercial transport and industrial equipment generates concentrated demand near logistics hubs and Jubail Industrial City's freight corridors. Fleet procurement platforms negotiate diesel supply contracts with fixed-price mechanisms.
- Compressed Natural Gas:CNG dispensing infrastructure serves municipal bus fleets and selected heavy-duty transport operators with dedicated vehicle conversions.
- Electric Charging:DC fast charging and Level 2 AC infrastructure represents the steepest expansion trajectory as automaker partnerships pilot hybrid energy retail formats in Riyadh and Jeddah.
Petrol leads volumes today; Electric Charging is expanding most quickly.
Infrastructure:
Volume throughput and amenity depth determine capital intensity, with superstations and service centers commanding premium positioning against stripped-down express formats.
- Conventional Stations:Multi-bay facilities with 20,000-60,000 liter underground storage, convenience retail, and vehicle services anchor the installed base across Saudi Arabia's established urban and highway locations. SFDA tank integrity inspections and vapor recovery mandates impose recurring modernization costs.
- Express Outlets:Limited-amenity, high-throughput designs with minimal retail footprint target commercial fleets along highway corridors where speed and accessibility outweigh service breadth.
- Superstations:Large-format complexes with extensive retail, food service, and multiple fueling lanes concentrate near major intercity junctions and airport approaches.
- Service Centers:Integrated maintenance, lubrication, and diagnostic facilities attached to fuel retail operations capture ancillary revenue from individual consumers and light commercial operators.
Conventional Stations lead volumes today; Express Outlets are climbing the fastest.
Customer Type:
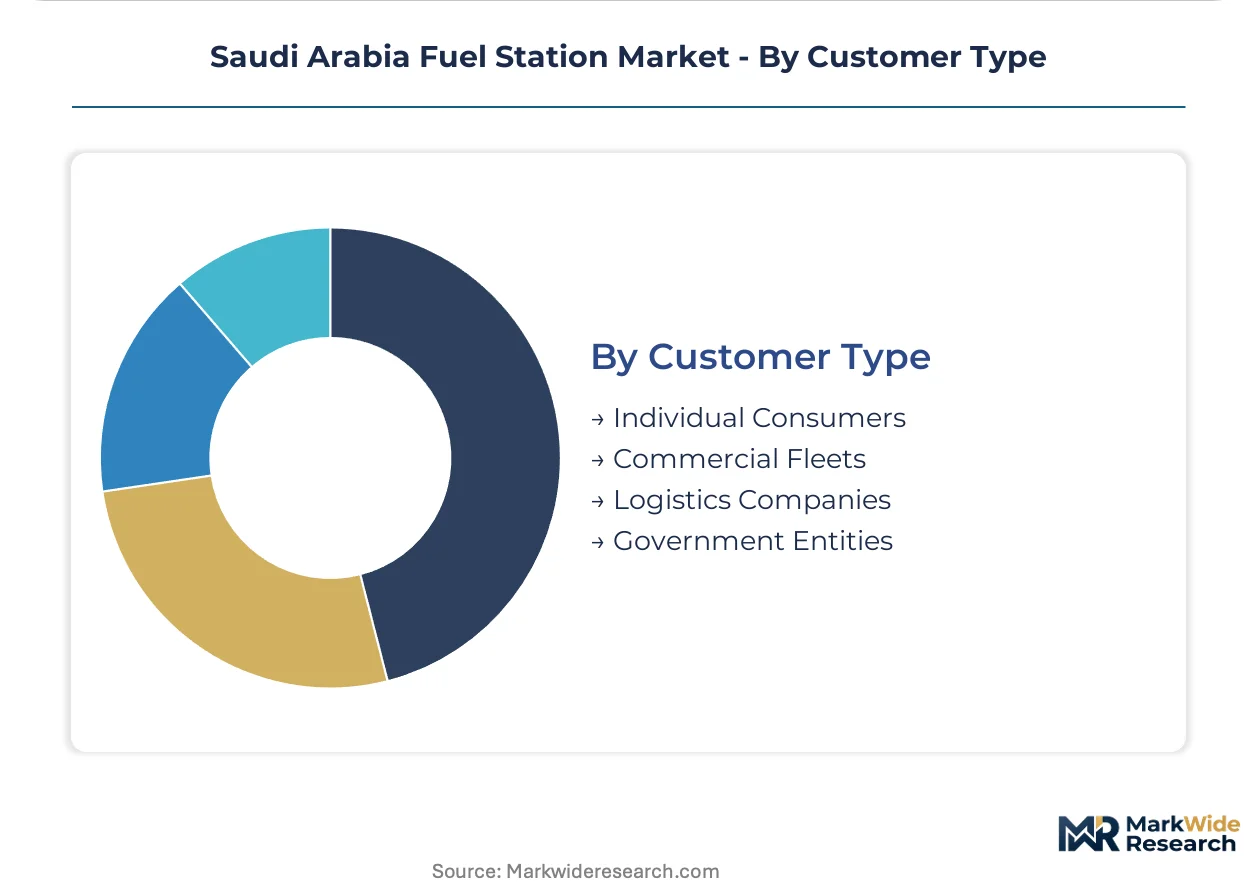
Maturity and procurement sophistication separate fragmented individual demand from consolidated institutional purchasing with multi-year contract structures.
- Commercial Fleets:Logistics companies and transport operators with centralized fuel management systems negotiate network access agreements with fixed-price components and volume commitments. Long-term contracts with major station networks stabilize revenue visibility for operators serving the Riyadh-Jeddah-Dammam triangle.
- Logistics Companies:Third-party freight and last-mile delivery specialists require high-throughput facilities with fleet card integration and consolidated billing across multiple vehicle classes.
- Individual Consumers:Price-sensitive retail purchasers with variable demand patterns and low loyalty concentration.
- Government Entities:Municipal and state vehicle fleets with mandated procurement transparency and public tender requirements.
Commercial Fleets lead volumes today; Logistics Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's fuel station density exceeds that of neighboring UAE, yet both markets face similar pressure from fleet electrification mandates and SASO fuel quality enforcement. The Kingdom's retail fuel network concentrates along three distinct geographic corridors with divergent demand profiles.
Riyadh
The capital region absorbs the highest individual consumer fuel volumes in Saudi Arabia, driven by commuter traffic and government fleet operations. SFDA safety inspections and vapor recovery mandates apply most stringently here due to population density. King Abdullah Financial District and Diriyah Gate developments are integrating hybrid energy retail pilots combining conventional fuel with DC fast charging infrastructure.
Eastern Province
Jubail Industrial City and Dammam's logistics corridors generate concentrated diesel demand from petrochemical transport and heavy freight operators. Aldrees Petroleum anchors its station network across this region, leveraging proximity to Saudi Aramco's refining complex at Ras Tanura. The King Fahd Industrial Port vicinity sees sustained investment in high-throughput express outlets serving commercial fleets.
Western Region
Jeddah's commercial port activity and Umrah pilgrimage traffic create seasonal demand spikes for retail fuel networks. TotalEnergies has extended its European service center format to urban locations here, targeting premium-amenity positioning. The Jeddah-Makkah highway corridor remains the Kingdom's most contested fuel retail battleground.
NEOM Northwest
The giga-project zone is mandating electric-first mobility infrastructure, limiting conventional fuel station permits to designated logistics corridors. NEOM's regulatory framework exempts certain zones from standard SASO dispenser calibration requirements as pilot programs test alternative energy retail models. The Oxagon industrial zone will require specialized mobile refueling services for construction equipment fleets.
Saudi Arabia Fuel Station Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's fuel retail network. Saudi Aramco's downstream integration creates a tiered structure where national oil companies control supply while independent operators battle for retail positioning. Three archetypes dominate: captive crude suppliers with terminal-to-pump control, regional station network specialists with integrated logistics arms, and international oil companies importing European service formats. Competitive moves center on hybrid energy retail partnerships and long-term fleet supply contract capture.
Within the national oil company tier, Saudi Arabian Oil Company exemplifies captive supply chain control from refining through retail. Aldrees Petroleum and Transport Services Co. represents the regional network specialist archetype, anchoring position through eastern province density and bundled transport services. TotalEnergies occupies the international format importer position, adapting European premium service center designs to Saudi urban markets.
| Leading Market Players |
|---|
| Saudi Arabian Oil Company |
| Mazaya Fuel |
| Aldrees Petroleum and Transport Services Co. |
| TotalEnergies |
| NAFT Services Company Limited |
| Saudi Automotive Services Co. |
| J-Oil |
| ADNOC Distribution |
| Petromin Corporation |
| Others |
Value Network & Pricing Analysis
Service format bifurcation between premium-amenity superstations and stripped-down express outlets manifests in divergent margin structures and procurement strategies across Saudi Arabia's fuel retail network. Full-service operations with attendant-staffed bays command higher per-liter premiums in Riyadh and Jeddah urban cores, while automated express formats near Jubail Industrial City compete on throughput velocity and fleet contract pricing.
Pricing Analysis
Capacity additions in the Eastern Province are reshaping price floors for diesel supply contracts serving petrochemical transport corridors. Three-tier pricing structure across premium superstations, standard conventional outlets, and economy express formats reflects amenity depth and throughput efficiency rather than fuel quality differentiation alone. Price compression runs through the express tier as Aldrees Petroleum and Saudi Aramco deploy high-volume automated facilities to capture fleet procurement volume. Logistics companies with centralized fuel management systems exhibit lowest price sensitivity, while individual consumers in Riyadh commuter corridors show highest responsiveness to promotional fuel card discounts.
Supply Chain Analysis
Direct-to-fleet channels handle commercial buyer demand through long-term supply agreements with fixed-price components and volume commitments. Refined product supply concentrates at Saudi Aramco's Ras Tanura and Yanbu terminals, with secondary distribution feeding into Dammam and Jeddah bulk storage facilities. Underground storage tank fabrication draws from South Korean and Chinese steel suppliers, while vapor recovery system components source from German and Japanese engineering specialists. Single-source vulnerability sits with Saudi Aramco's captive control over domestic crude allocation, limiting independent retailers' sourcing flexibility and bargaining leverage in supply negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid energy retail formats where DC fast charging infrastructure commands premium positioning alongside conventional fuel dispensing. SASO compliance automation and fleet contract consolidation represent the primary cost-down drivers reshaping operator economics.
For Market Incumbents: Deploy captive supply chain integration to defend against electric vehicle substitution pressure. Saudi Aramco should accelerate downstream retail network densification along the Riyadh-Jeddah-Dammam corridor before independent operators secure secondary corridor positions. Aldrees Petroleum must invest in SFDA-certified hazardous materials handling automation to reduce skilled technician wage pressure and accelerate new station build timelines.
For New Entrants and Emerging Players: The mid-tier pricing gap between TotalEnergies premium service centers and economy express outlets creates entry space for differentiated hybrid formats. White space exists in secondary corridors connecting Dammam to smaller industrial zones lacking premium-amenity stations. Mobile refueling services for NEOM construction equipment fleets offer the most penetrable segment, with automaker partnership pilots in Riyadh and Jeddah providing proven go-to-market templates.
For Investors and Strategic Acquirers: Consolidation pressure builds where aging station portfolios face simultaneous SFDA tank replacement cycles and electric charging retrofit capital demands. Long-term viability favors operators with hybrid energy retail capabilities and established fleet contract backlogs. Acquisition targets should demonstrate eastern province network density or integrated transport service bundling. Watch the pace of SASO electric charging infrastructure mandates as the critical inflection signal for conventional fuel demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Energy Retail Pilot | Co-located DC fast charging and conventional fuel dispensing attracts automaker partnership investments in Riyadh and Jeddah. |
| Fleet Contract Consolidation | Long-term supply agreements with fixed-price components stabilize revenue visibility for operators serving logistics corridors. |
| SFDA Compliance Automation | Automated calibration scheduling systems reduce inspection failure rates and operational suspension risk across retail networks. |
| Express Outlet Densification | High-throughput limited-amenity designs capture commercial fleet volume along highway corridors with lower per-transaction overhead. |
| Third-Party Safety Certification | Hazardous materials handling auditing creates ancillary revenue streams for technical service providers serving station operators. |
Research Methodology
Multiple input streams — structured interviews with fuel retail network executives, regulatory compliance officers at SFDA and SASO, fleet procurement managers at logistics companies, and petroleum product supply specialists — were reconciled against secondary validation from customs records, Saudi Aramco downstream disclosures, and infrastructure project databases. Bottom-up station count modeling and top-down fuel consumption triangulation anchored volume estimates across the analysis window.
Historical throughput patterns were cross-referenced against panel input from station operators and fleet managers to construct the analytical framework. Segmentation dimensions modeled include service format type, fuel technology category, infrastructure scale tier, and customer procurement sophistication. CAGRs were derived from trend extrapolation moderated by regulatory inflection assumptions, with electric charging infrastructure deployment schedules and SASO quality mandate compliance timelines serving as key industry-specific forecast inputs.
Caveats apply where electric vehicle adoption acceleration or crude supply allocation policy shifts could materially shift the outlook. Forecasts reflect assumptions about fleet electrification pacing and regulatory enforcement consistency that warrant ongoing monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Mobile Gas Pumping System Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
No.2 Diesel Fuel Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Aboveground Fuel Storage Market
Fuels
Hydrogen Cylinder Market
Fuels
Canada Coal Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Liquefied Helium Tanks Market
Fuels
Italy Automotive Engine Oils Market
Fuels
South America Aviation Fuel Market
Fuels
Solid Fuel Tablet Market
Fuels
Brazil LNG Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
North America Commercial Aircraft Aviation Fuel Market