
 Collapsible Fuel Tank Market | 2026-2036
Collapsible Fuel Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Fuel Tank Market Intelligence
The European Union's REACH regulation is recalibrating the cost-of-entry calculus for material suppliers. This framework governs the chemical substances used in tank fabrics, favoring producers with advanced research capabilities. Aero Tec Laboratories Ltd. specializes in high-performance, compliant materials. Amfuel Co. leverages its established position within the defense sector to navigate these complex requirements, while Simtech competes on custom engineering for specialized industrial uses.
A collapsible fuel tank is a portable, flexible container engineered for temporary storage and transportation of hydrocarbons. These products are typically constructed from durable, polymer-coated fabrics using high-frequency welding to ensure seam integrity. Pillow tanks are a leading product type for their stability in emergency response scenarios. The military end-user segment drives demand for specialized bladder tanks that conform to rigorous mil-spec standards for aviation and ground vehicle applications.
The market operates under strict regulatory oversight from bodies like the US Environmental Protection Agency and its SPCC rule. Military procurement requires adherence to specific defense logistics standards, such as MIL-DTL specifications for fuel handling equipment. These frameworks mandate specific material properties and performance testing. Success hinges on a manufacturer's ability to innovate materials that improve deployment speed and reduce environmental risk.
Market Dynamics
The market's primary structural force is the tension between military demand for rapid, expeditionary fuel logistics and tightening environmental regulations. This dual pressure accelerates material science innovation while simultaneously raising compliance barriers for manufacturers globally, from the US to the European Union.
Growth Catalysts
- Military Modernization Programs:Increased defense spending in NATO countries and Japan on expeditionary force capabilities directly stimulates procurement of MIL-DTL compliant bladder tanks for forward operating bases and aviation support.
- Climate-Driven Disaster Response:A higher frequency of extreme weather events necessitates expanded investment by agencies like FEMA in the United States and state emergency services in Australia for prepositioned fuel caches.
- Environmental Regulation:The US Environmental Protection Agency's SPCC rule and similar mandates in Canada create demand for tanks with superior spill prevention features and secondary containment compatibility.
Market Restraints
- Input Material Volatility:The cost of specialized polyurethane and PVC-coated fabrics, which are essential for durability and chemical resistance, is subject to fluctuations in petrochemical feedstock prices.
- Stringent Certification Cycles:Achieving compliance with military specifications like MIL-DTL or aviation-grade standards is a lengthy and capital-intensive process, limiting the number of qualified suppliers for high-value contracts.
- Substitution from Rigid Tanks:In non-critical, static storage applications, lower-cost rigid polyethylene or steel drums and intermediate bulk containers (IBCs) present a persistent alternative for price-sensitive buyers.
Strategic Opportunities
- Humanitarian Aid Sector:Non-governmental organizations and United Nations agencies require mobile fuel solutions for infrastructure projects and relief efforts in underpenetrated regions of Africa and Southeast Asia.
- Unmanned Systems Support:The expanding use of drones and unmanned ground vehicles in agriculture and remote surveillance opens a new application for small-capacity, highly portable refueling tanks.
- Recyclable Material Development:Innovating tank fabrics that are fully recyclable at end-of-life offers a path to meet corporate sustainability mandates and future circular economy regulations.
Industry Challenges
- Specialized Labor Scarcity:A shortage of technicians with expertise in high-frequency and radio-frequency welding of high-performance polymer fabrics creates a significant production bottleneck for manufacturers.
- Lifecycle Management Logistics:Establishing efficient reverse logistics for the inspection, cleaning, repair, and recertification of returned tanks is an operationally complex and costly challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Fuel Tank Market |
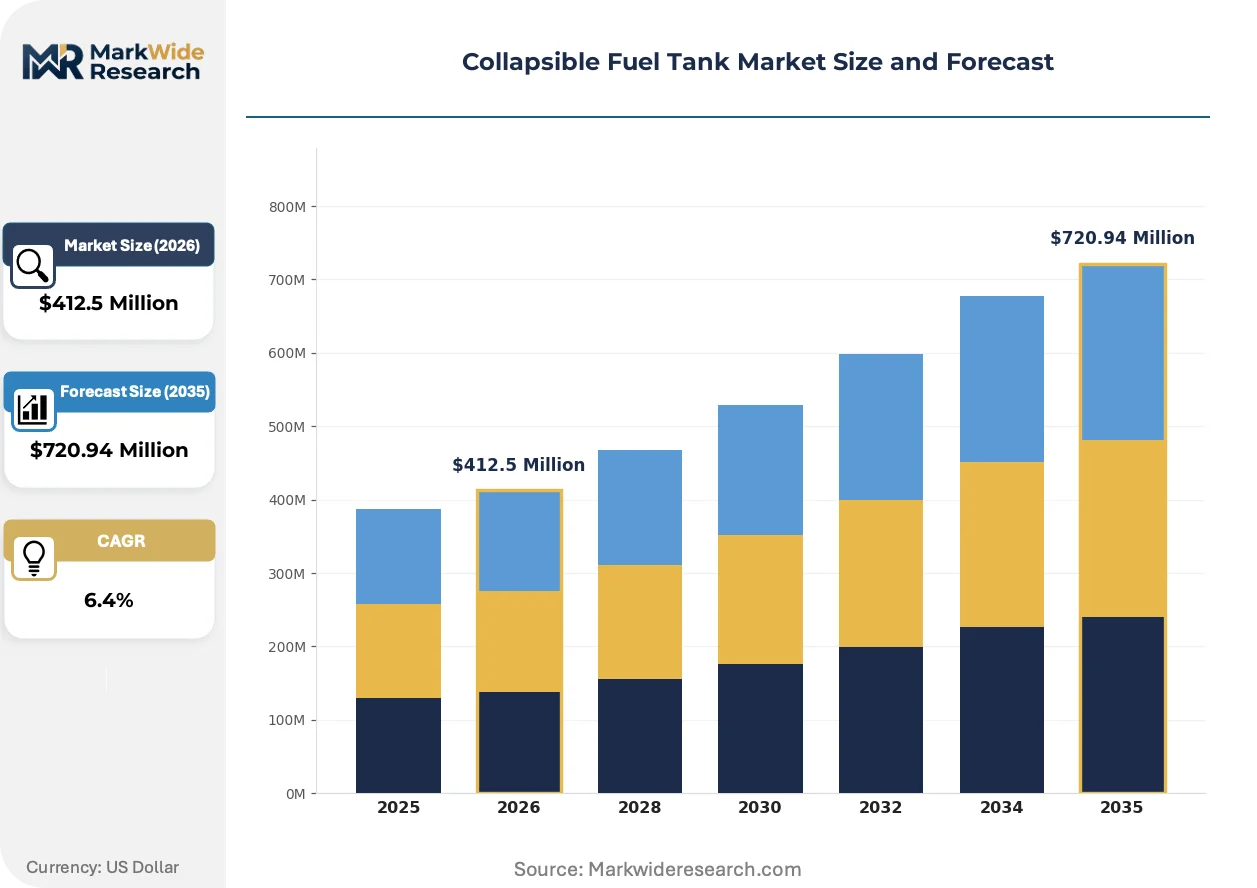
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bladder Tanks, Pillow Tanks, Flex Tanks, Tank Bags Material: Polyethylene, PVC, Nylon, Rubber Use Case: Emergency Response, Military Logistics, Fuel Storage, Water Transport End User: Military, Aerospace, Construction, Transportation |
| Companies Covered | Amfuel Co., Simtech, Texas Boom Company, Aero Tec Laboratories Ltd., Ready Containment, Interstate Products, Inc., GTA Containers, Inc., MPC Containment International LLC, ContiTech North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Fuel Tank Market Strategic Shifts & Innovations
Material science advancements are converging with operational demands for enhanced safety and deployment speed. The evolution is shifting product focus from simple containment to integrated systems that offer improved environmental security and logistical efficiency across diverse operating theaters.
Self-sealing polymer composites and fabrics with embedded health-monitoring sensors represent a significant product evolution. Military logistics commands and aviation ground support crews are the primary adopters, seeking to minimize fuel loss and environmental contamination in austere environments. This technology is consolidating the high-end market around manufacturers with deep materials science expertise, creating a performance gap that generic fabricators cannot easily bridge.
The European Union's REACH regulation directly influences material composition and supply chain transparency for tank manufacturers. This framework requires extensive testing and registration for chemical substances used in polymer coatings, increasing compliance overhead and favoring suppliers with robust R&D infrastructure. The defense sector is most affected, as it must ensure that all components in the supply chain, from fabrics to fittings, meet these stringent European standards.
A notable shift in acquisition strategy is moving from direct capital purchase to comprehensive leasing and service-based contracts. This model disrupts traditional equipment sales channels, especially in the disaster response and remote mining sectors. Organizations prefer this approach to convert capital expenditures into predictable operational costs, a trend most visible in contracts with large NGOs and government emergency management agencies in North America.
Collapsible Fuel Tank Market Segmentation
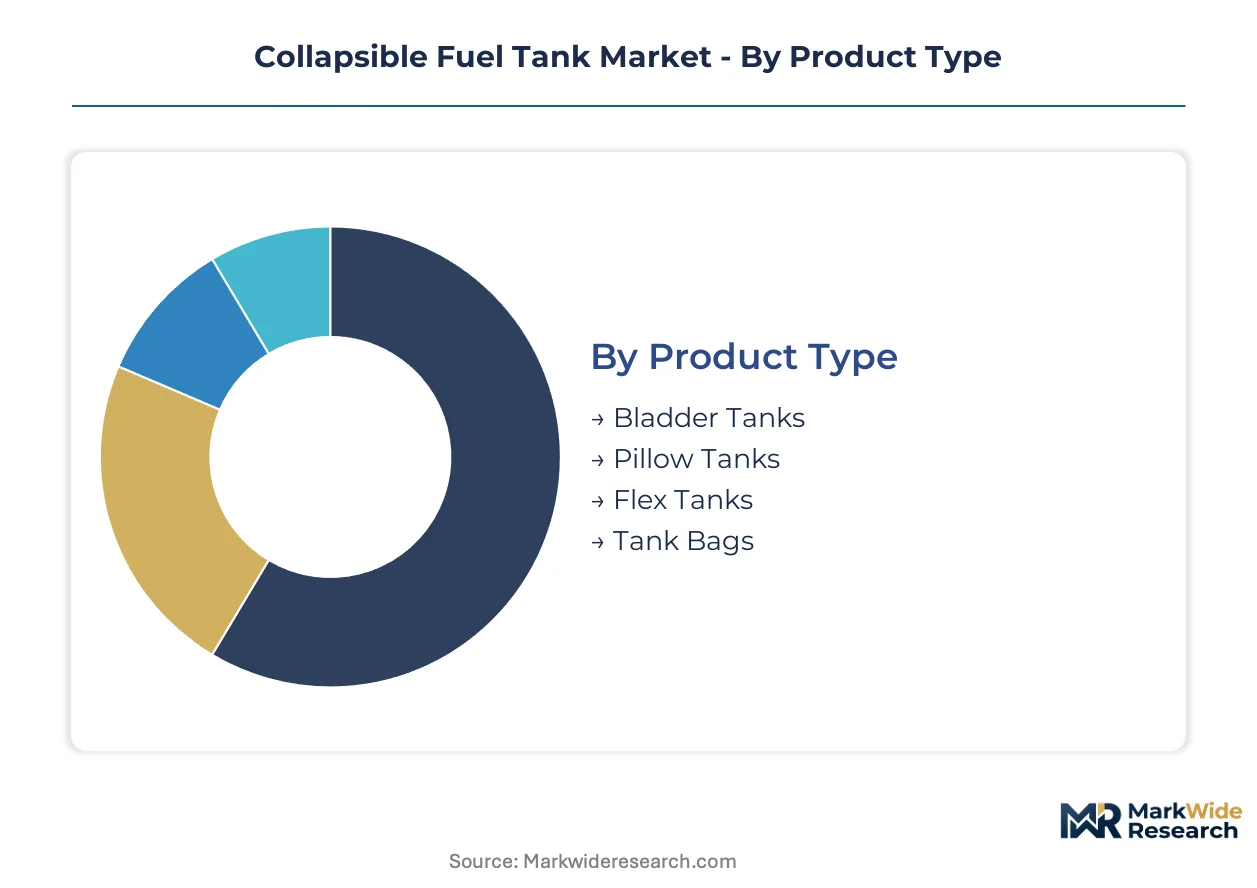
The collapsible fuel tank market's intricate structure reflects diverse operational requirements and material science advancements. Understanding these segments clarifies where specialized manufacturing capabilities are concentrating and where future demand will emerge. Market segmentation provides critical insights into product development priorities and strategic investment areas for suppliers.
Product Type:
Supply concentration within the collapsible fuel tank market often correlates with specific product types that meet rigorous performance standards.
- Bladder Tanks:These highly flexible, robust containers are engineered for military and aviation applications, often conforming to MIL-DTL specifications. Demand is concentrating within NATO countries' defense procurement agencies for expeditionary fuel logistics and forward operating bases.
- Pillow Tanks:Characterized by their flat, low-profile design, pillow tanks offer exceptional stability for static storage and emergency fuel caches. Demand is concentrating within US federal agencies like FEMA and Australian state emergency services for rapid disaster response.
- Flex Tanks:These tanks are typically large-capacity, fabric-based containers used for bulk storage in remote industrial or humanitarian aid settings.
- Tank Bags:Smaller, more portable variants suitable for short-term fuel transfer or support for unmanned systems in agricultural operations.
Bladder Tanks absorb the bulk of installed capacity; Pillow Tanks are expanding most quickly.
Material:
Material selection directly influences a collapsible fuel tank's application suitability, dictating chemical resistance, durability, and weight characteristics.
- PVC:Polyvinyl chloride fabrics, often coated, offer a balance of cost-effectiveness and chemical resistance for general fuel storage and water transport. Demand is concentrating in the construction and humanitarian aid sectors for versatile, temporary containment solutions.
- Polyethylene:High-density polyethylene (HDPE) and linear low-density polyethylene (LLDPE) provide excellent chemical inertness and puncture resistance for demanding industrial applications. Demand is concentrating in the remote mining sector and environmental remediation projects due to stringent spill prevention requirements.
- Nylon:Nylon-based fabrics provide superior strength-to-weight ratios, making them suitable for lightweight, high-performance applications like aerospace ground support equipment.
- Rubber:Synthetic rubber compounds offer high elasticity and temperature resistance, primarily used in specialized military applications requiring extreme durability.
The selection of specific materials directly influences performance metrics and regulatory compliance across diverse operational environments.
Use Case:
Understanding the primary customer type for each use case reveals distinct procurement patterns and specific product feature requirements.
- Military Logistics:This segment involves rapid deployment and storage of fuel for ground vehicles and aviation assets in austere environments. Military end-users prioritize MIL-DTL compliant bladder tanks that withstand extreme conditions and offer quick setup times.
- Emergency Response:This use case focuses on providing temporary fuel and water storage during natural disasters or humanitarian crises. Agencies like FEMA and UN bodies require stable pillow tanks that can be quickly deployed and retrieved.
- Fuel Storage:This general category encompasses static, temporary storage solutions for various industries, including construction sites and agricultural operations.
- Water Transport:These tanks are designed for potable or non-potable water movement, often used in remote areas or disaster-stricken regions by NGOs.
These applications collectively define the operational demands placed on collapsible fuel tank designs and material specifications.
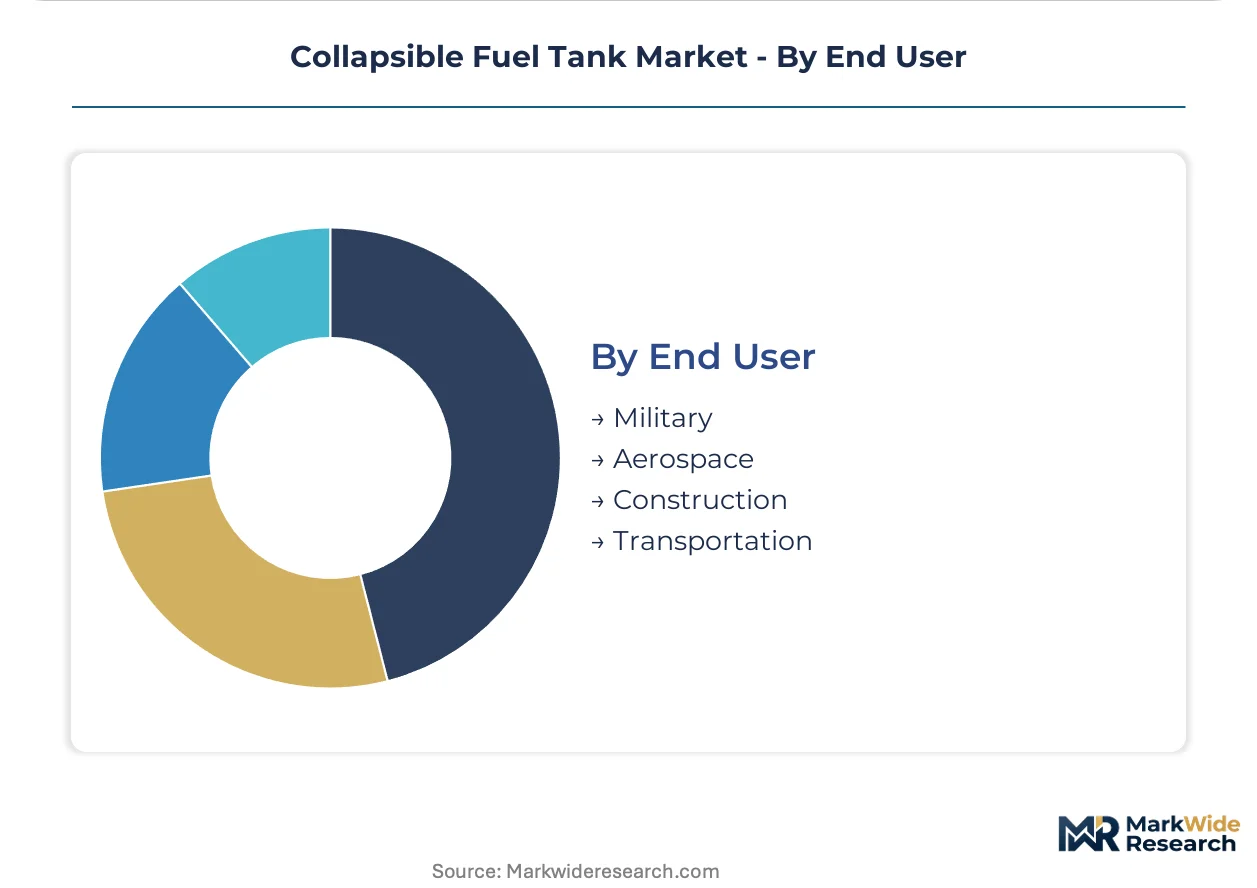
End User:
Regulatory oversight and specific defense logistics standards significantly shape product requirements and market access for various end-user segments.
- Military:This segment demands highly specialized bladder tanks and flex tanks adhering to stringent MIL-DTL specifications for aviation and ground support. US Department of Defense procurement emphasizes rapid deployability and extreme durability in combat zones.
- Aerospace:Aerospace operations require precise fuel handling equipment for aircraft ground support and remote refueling, often utilizing lightweight, high-performance materials. European aviation authorities mandate specific safety certifications for all ground support equipment.
- Construction:Construction companies utilize collapsible tanks for temporary fuel storage on job sites, prioritizing durability and ease of transport for diesel and gasoline.
- Transportation:This segment includes commercial trucking and rail operations that require mobile fuel solutions for remote depots or emergency roadside assistance.
Each end-user segment presents distinct procurement processes and performance requirements, influencing product development and market entry strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in the United States, designed to foster military innovation, significantly influence the global collapsible fuel tank market. These zones attract specialized manufacturers developing advanced materials for expeditionary logistics. Strict regulatory frameworks and high-performance demands define regional market dynamics.
United States
United States military modernization programs and FEMA's disaster preparedness initiatives drive substantial demand for collapsible fuel tanks. The US Environmental Protection Agency's SPCC rule mandates superior spill prevention features for fuel storage. Manufacturers in Texas and California actively develop MIL-DTL compliant bladder tanks for defense and rapid emergency deployment.
Germany
Germany's commitment to NATO defense spending and its role in international humanitarian aid efforts generate demand for flexible fuel storage. The European Union's REACH regulation dictates stringent material compliance for tank fabrics. Companies in Bavaria and North Rhine-Westphalia focus on developing high-performance, compliant materials for diverse applications.
Japan
Japanese defense spending on expeditionary force capabilities and national disaster response efforts stimulate procurement of specialized collapsible tanks. METI guidelines ensure industrial safety standards are met for fuel handling equipment. Manufacturers in the Tokyo and Osaka regions are innovating lightweight, high-performance tanks for aviation and emergency use.
Australia
Australia's frequent extreme weather events necessitate expanded investment in prepositioned fuel caches by state emergency services. TGA regulations influence material properties for safe fuel and water storage. Suppliers in Queensland and New South Wales focus on stable pillow tanks and robust solutions for remote mining sectors.
Collapsible Fuel Tank Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the collapsible fuel tank market, which exhibits a tiered structure. This market segments into high-performance military suppliers, general industrial and emergency response providers, and custom engineering specialists. Material innovation for regulatory compliance and strategic partnerships with defense agencies represent dominant competitive moves among manufacturers.
Specialists in high-performance materials and custom engineering define critical competitive segments. Amfuel Co. exemplifies a player with an established position within the defense sector, navigating complex regulatory requirements for military applications. Aero Tec Laboratories Ltd. represents a manufacturer concentrating on high-performance, compliant materials that meet stringent industry standards. Simtech occupies a position focused on custom engineering solutions for specialized industrial uses, catering to niche market demands.
| Leading Market Players |
|---|
| Amfuel Co. |
| Simtech |
| Texas Boom Company |
| Aero Tec Laboratories Ltd. |
| Ready Containment |
| Interstate Products, Inc. |
| GTA Containers, Inc. |
| MPC Containment International LLC |
| ContiTech North America, Inc. |
| Others |
Cost & Logistics Intelligence
Outsourced manufacturing of specialized polymer fabrics anchors supply positions for many market participants, directly influencing their pricing power in niche segments. This integration choice allows flexibility but also ties pricing to input material costs.
Pricing Analysis
Premium pricing for short lead times characterizes high-performance collapsible fuel tanks, especially those meeting MIL-DTL specifications. Contract-based long-term offtake agreements dominate military procurement, ensuring stable pricing for certified suppliers. Certification level, particularly MIL-DTL compliance, and customization capabilities drive significant price differentiation. Pricing pressure stems from input material volatility, impacting general industrial and humanitarian aid segments. Military and aerospace end-users demonstrate the least price sensitivity, while construction and agricultural operations are the most price-sensitive.
Supply Chain Analysis
Certification and qualification gating for materials and manufacturing processes restrict market entry, concentrating the supply chain among a few specialized producers. Geographic supply concentrates in the United States for defense-grade materials, Germany for REACH-compliant fabrics, and Japan for lightweight aerospace components. Raw material dependencies include specialized polyurethane and PVC-coated fabrics, along with advanced high-frequency welding equipment. Input material volatility presents a structural risk to overall supply stability. Distribution runs through direct sales channels to military and government agencies, complemented by specialized distributors for industrial and humanitarian aid sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
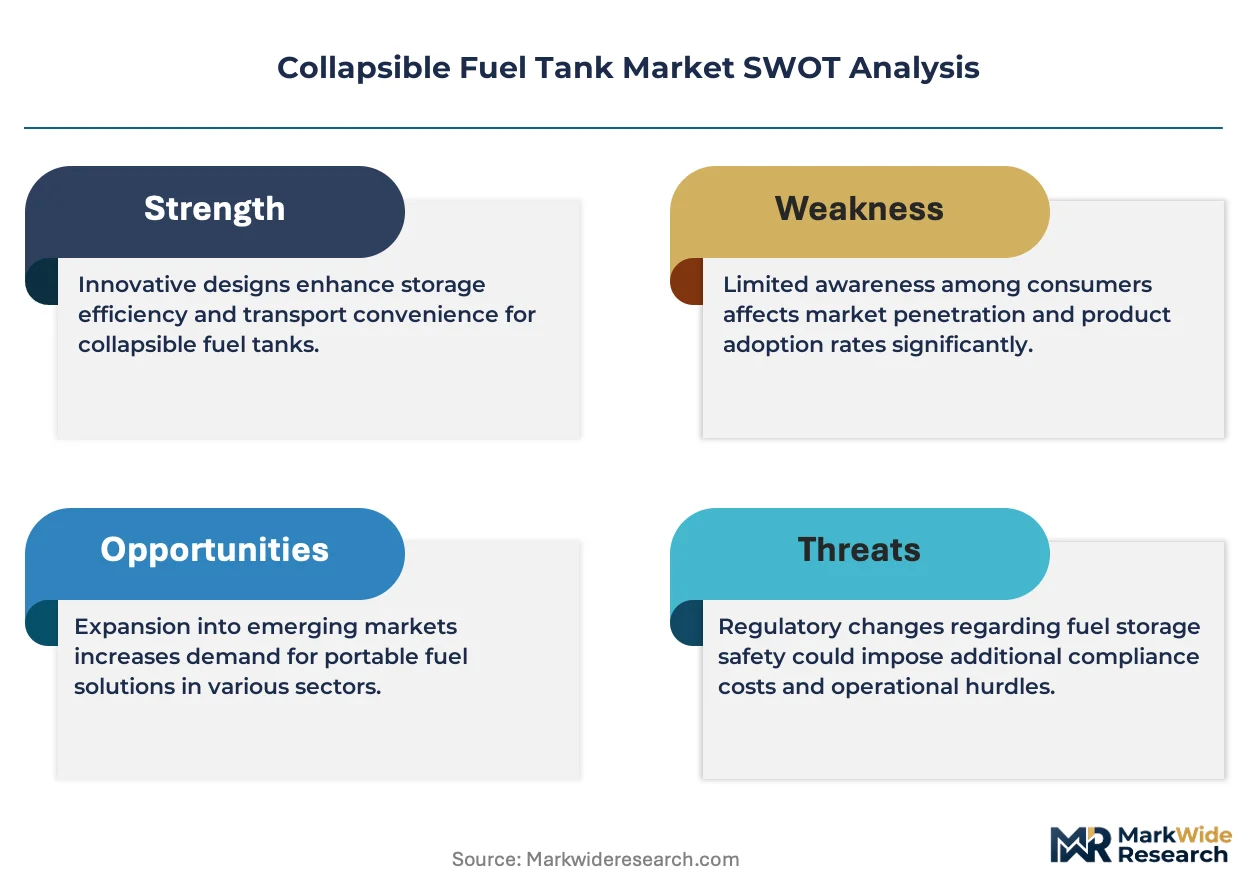
This market functions as a supply-constrained story, with specialized labor scarcity for high-frequency welding acting as a primary bottleneck propping up pricing for complex products.
For Market Incumbents:Anticipate continued demand for MIL-DTL compliant bladder tanks by investing in advanced material science R&D for self-sealing composites. Deepen vertical integration into specialized fabric coating processes to mitigate input material volatility. Focus on expanding certified production capacity in strategic defense industrial zones to counter specialized labor scarcity. The persistent threat of rigid tank substitution in non-critical applications requires continuous product innovation.
For New Entrants and Emerging Players:Recyclable material development presents a technology-first wedge into the market, appealing to corporate sustainability mandates and future circular economy regulations. Target the humanitarian aid sector and unmanned systems support for underpenetrated regions of Africa and Southeast Asia. Focus on developing small-capacity, highly portable refueling tanks for agricultural drones. A leasing and service-based contract model offers a compelling go-to-market angle, converting capital expenditures into predictable operational costs for NGOs.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialists possessing unique material science intellectual property or robust MIL-DTL certification portfolios. Long-term viability hinges on companies that can consistently meet stringent environmental regulations and defense logistics standards. Target acquisition candidates with established positions in high-growth segments like disaster response or unmanned systems. A signal to watch is the widespread adoption of new mil-spec standards for advanced composites, indicating a shift in procurement priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Material R&D | Manufacturers gain a competitive edge by developing self-sealing polymers and health-monitoring sensors for military logistics. |
| Expand Certified Production Capacity | Companies meet growing demand for MIL-DTL compliant bladder tanks in NATO countries and Japan's defense programs. |
| Develop Recyclable Tank Fabrics | Suppliers align with corporate sustainability mandates and future circular economy regulations, opening new market opportunities. |
| Offer Leasing and Service Contracts | Providers convert capital expenditures into predictable operational costs for government emergency management agencies and NGOs. |
| Target Unmanned Systems Support | Companies tap into expanding applications for small-capacity, highly portable refueling tanks in agriculture and remote surveillance. |
Research Approach
Document review covered EPA SPCC rules, MIL-DTL specifications, REACH regulations, and FEMA guidelines, complemented by interviews with defense procurement officers, material scientists, emergency management leads, and logistics managers. This approach combined primary insights with secondary validation. Bottom-up data collection from manufacturers was triangulated with top-down market sizing estimates.
Historical market performance was cross-referenced with expert panel input to construct the forecast framework across the analysis window. The analytical model segmented the market by product type, material, end-user, use case, and regulatory compliance tier. Compound annual growth rates were derived from projected shifts in defense spending and climate-driven disaster response. Key forecast inputs included defense spending trends in NATO countries and the frequency of extreme weather events.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid, disruptive material science breakthroughs. Forecasts reflect assumptions regarding stable regulatory frameworks and consistent procurement patterns over the projection horizon. A model refresh is warranted upon material change in global defense budgets or the severity of climate-related disasters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
China Bunker Fuel Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Wood Charcoal Market
Fuels
India Retail Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Canada Bunker Fuel Market
Fuels
Global Gas Treatment Market
Fuels
Pyrolysis Gas Market
Fuels
Coal Briquettes Market
Fuels
Global Wood Gas Generator Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Canada Coal Market
Fuels
Compressed Natural Gas Market
Fuels
Diesel Fuel Water Separator Market