
 India Thermal Power Plant Market | 2026-2036
India Thermal Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
India Thermal Power Plant Market Foresight
Modular supercritical boiler packages is expanding as the preferred procurement format among state gencos seeking faster commissioning timelines. NTPC Limited leverages its pan-India project pipeline to sustain engineering dominance across ultra-mega power plant sites. Adani Power Limited anchors its position through captive coal logistics and port-linked generation clusters. Tata Power Company Ltd differentiates via integrated transmission access and distribution footprint in Mumbai.
An India thermal power plant converts fossil or biomass fuel into electricity through steam-driven turbine generators, typically operating at supercritical steam conditions above 22.1 MPa pressure to achieve thermal efficiencies near 38-42 percent. Coal-fired technology dominates installed capacity but faces margin compression from fuel cost volatility and environmental compliance burdens. Independent power producers represent the fastest-growing end user category as merchant power frameworks attract private capital into brownfield expansion projects. Retrofit and upgrade installations command premium service margins as aging subcritical units require flue-gas desulfurization and selective catalytic reduction retrofits to meet new emission standards.
Central Electricity Authority (CEA) technical standards govern plant design and grid connectivity, while Central Pollution Control Board (CPCB) emission norms mandate particulate matter and sulfur dioxide limits that reshape capital expenditure priorities. State-level regulators such as Maharashtra Electricity Regulatory Commission and Gujarat Electricity Regulatory Commission determine tariff structures that influence investor returns across the project lifecycle. Stakeholders must monitor the pace of renewable energy integration mandates and their impact on thermal plant capacity utilization trajectories.
Market Dynamics
Supercritical steam technology is consolidating procurement preferences among Indian state gencos seeking thermal efficiency gains above 38 percent, while Central Pollution Control Board emission norms force simultaneous retrofits on aging subcritical units.
Growth Catalysts
- Ultra-mega power plant frameworks:These centralized procurement mechanisms aggregate demand across multiple state utilities, reducing transaction costs and accelerating project financial closure timelines.
- Flue-gas desulfurization mandates:CPCB's sulfur dioxide limits for thermal plants above 500 MW create recurring retrofit demand and premium service margins for engineering contractors.
- Captive coal block allocations:Domestic fuel security through allocated mining rights reduces import dependency and stabilizes generation economics for integrated operators.
Market Restraints
- Imported coal price volatility:Indonesian and South African thermal coal indices expose merchant power producers to margin compression when rupee depreciation coincides with seaborne fuel spikes.
- Transmission congestion:Inter-regional grid bottlenecks between coal-rich eastern states and western load centers limit offtake from new generation assets.
- Renewable energy obligation norms:State-level solar and wind purchase mandates reduce plant load factors for thermal baseload capacity.
Strategic Opportunities
- Industrial cogeneration clusters:Gujarat's petrochemical and textile belts offer captive power expansion potential with waste heat recovery integration.
- Selective catalytic reduction retrofits:Nitrogen oxide compliance deadlines for plants commissioned before 2017 create equipment upgrade cycles across Maharashtra and Tamil Nadu.
- Biomass co-firing mandates:Ministry of Power directives for 5-10 percent agricultural residue blending open fuel diversification pathways for pulverized coal units.
Industry Challenges
- Supercritical welding certification:Qualified pressure vessel fabricators remain concentrated among a handful of domestic and Korean contractors, extending commissioning schedules.
- Legacy control system integration:Digital turbine governor upgrades require specialized protocol translation between 1990s-era DCS architectures and modern IoT monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Thermal Power Plant Market |
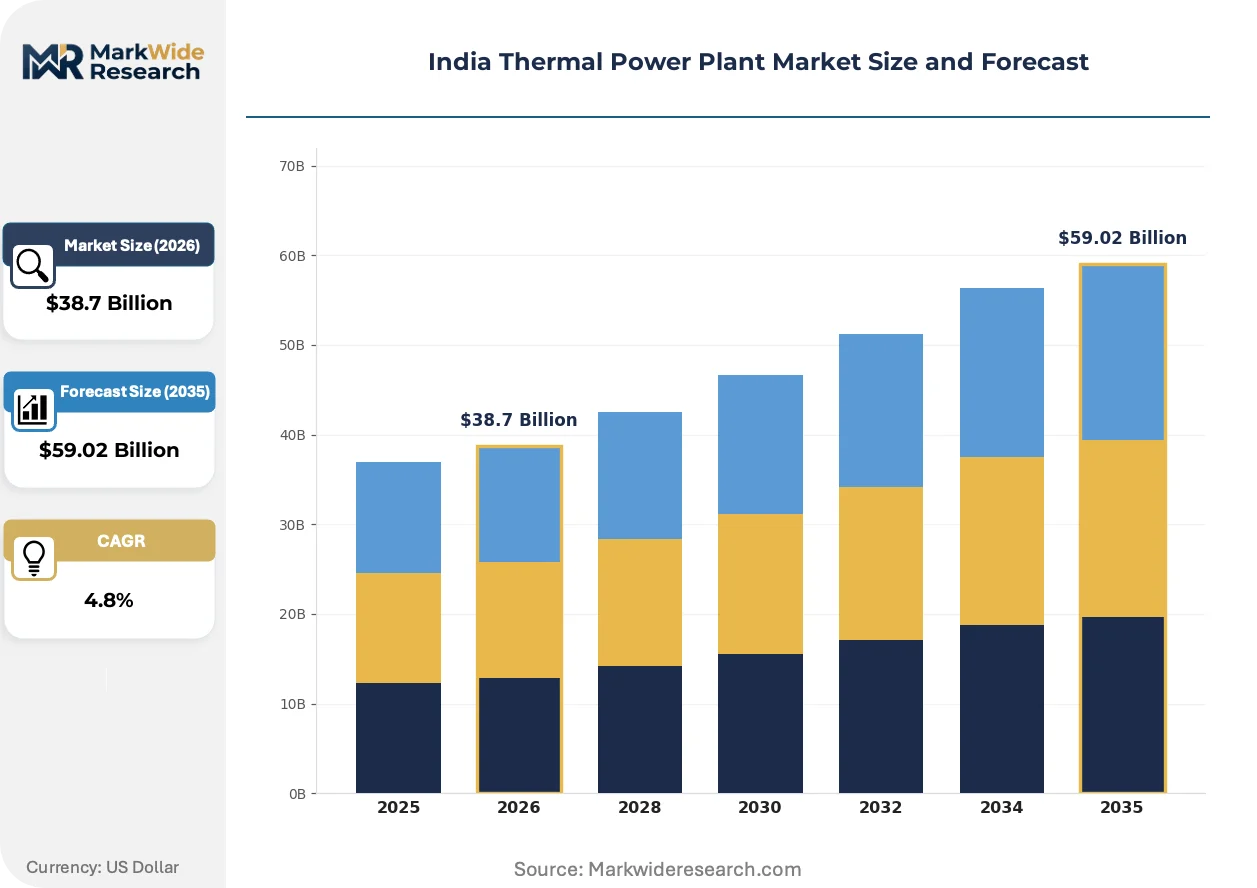
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
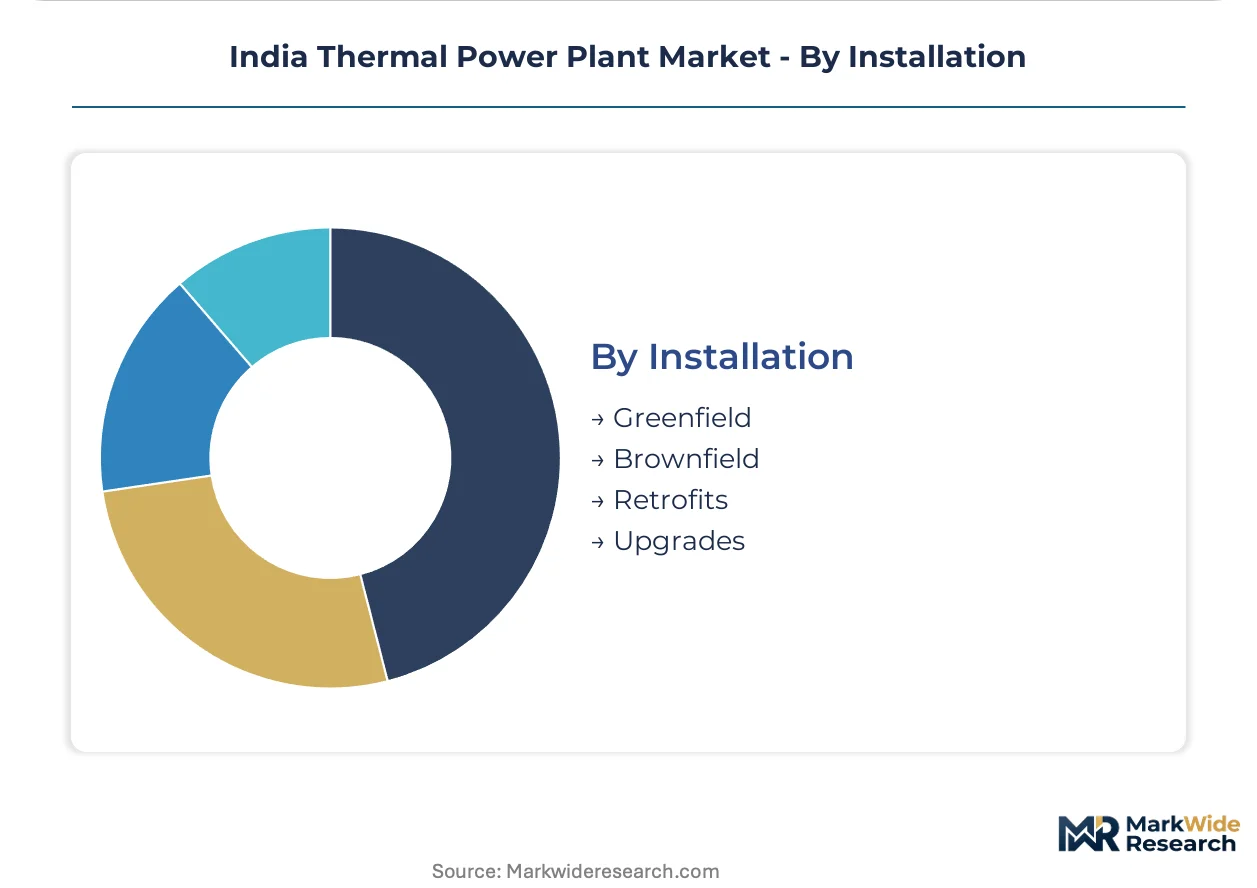
| Segmentation | Technology: Coal-Fired, Gas-Fired, Oil-Fired, Biomass End User: Utilities, Industrial Sector, Independent Power Producers, Government Service Type: Maintenance, Operations, Consulting, Engineering Installation: Greenfield, Brownfield, Retrofits, Upgrades |
| Companies Covered | Reliance Power Limited, Torrent Power Limited, NTPC Limited, APGENCO, JSW Energy, Adani Power Limited, MAHAGENCO, Haryana Power Generation Corporation Ltd, Tata Power Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Thermal Power Plant Market Shifts & Advancements
Steam cycle efficiency improvements and emission control retrofits are converging to reshape capital allocation priorities across Indian thermal generation, with technology choices increasingly constrained by compliance timelines rather than pure thermodynamic optimization.
Advanced ultra-supercritical boiler designs operating above 600°C and 30 MPa are consolidating engineering procurement patterns among NTPC and state gencos seeking 42 percent-plus thermal efficiency. These high-alloy steel configurations reduce coal consumption per megawatt-hour but require specialized welding protocols and extended commissioning periods. The technology is compressing competitive differentiation between domestic boiler fabricators and Korean-Japanese licensors.
Central Electricity Authority technical standards for grid connectivity and fault ride-through capability are tightening synchronization requirements for new thermal units. These mandates force generator OEMs to upgrade excitation systems and power electronics packages. Maharashtra and Gujarat utilities face the steepest compliance curves due to high renewable penetration requiring greater grid stability contributions from thermal assets.
Merchant power offtake agreements are displacing traditional cost-plus tariffs as the dominant revenue model for private independent power producers. These contracts expose generators to day-ahead market price volatility while offering higher returns during peak demand periods. Tamil Nadu's industrial corridor exhibits the most pronounced shift toward flexible bilateral contracts with aluminum smelters and cement manufacturers.
India Thermal Power Plant Market Segmentation
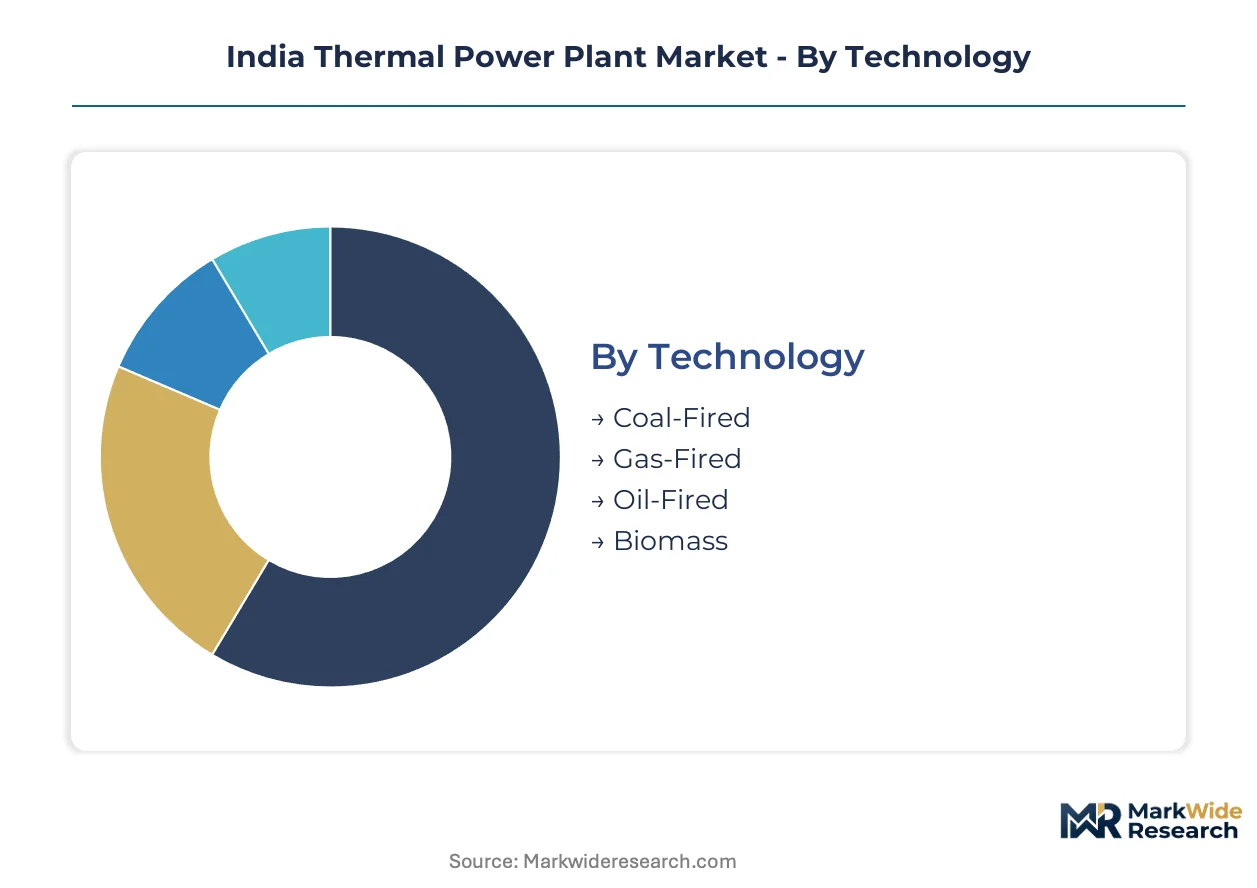
Segmentation in India's thermal power sector reveals how procurement priorities split between efficiency-driven technology choices and compliance-mandated service investments. Plant operators navigate competing pressures from CEA grid standards, CPCB emission deadlines, and state-level renewable integration mandates.
Technology:
The customization-vs-standardization spectrum spans from mature subcritical units requiring extensive retrofits to advanced ultra-supercritical designs demanding specialized fabrication protocols.
- Coal-Fired:Pulverized coal combustion dominates installed base with supercritical steam conditions above 22.1 MPa delivering thermal efficiencies near 38-42 percent. Maharashtra and Gujarat utilities concentrate procurement for ultra-mega power plant sites where domestic coal block allocations stabilize fuel economics against import price volatility.
- Gas-Fired:Combined cycle configurations using natural gas or regasified LNG offer faster ramp rates for grid balancing amid rising renewable penetration. Tamil Nadu's industrial corridor anchors demand where stranded gas assets seek revival through imported LNG contracts and pipeline infrastructure expansions.
- Oil-Fired:Diesel and heavy fuel oil units serve peaking and emergency backup roles in islanded grids and remote locations.
- Biomass:Agricultural residue combustion and co-firing configurations align with Ministry of Power blending mandates for 5-10 percent renewable fuel integration.
Leading the category by volume: Coal-Fired. Expanding most quickly: Biomass co-firing configurations.
End User:
Volume concentration tracks state procurement centralization against decentralized private capital deployment across merchant power frameworks.
- Utilities:State gencos and NTPC Limited anchor procurement through centralized tendering for supercritical boiler packages and emission control retrofits. Maharashtra State Power Generation Company and Gujarat State Electricity Corporation concentrate greenfield investments where transmission access constraints shape site selection.
- Independent Power Producers:Private developers pursue brownfield expansions and merchant power offtake agreements exposing returns to day-ahead market volatility. Adani Power and Tata Power leverage captive coal logistics and port-linked generation clusters to defend margin positions.
- Industrial Sector:Captive power plants for aluminum smelters, cement manufacturers, and petrochemical complexes in Gujarat's chemical belt.
- Government:Defense installations, railway electrification, and strategic reserve capacity under central ministry oversight.
Dominant by procurement value: Utilities. Steepest expansion trajectory: Independent Power Producers.
Service Type:
Margin profiles diverge between commoditized maintenance contracts and premium engineering services tied to compliance deadlines.
- Maintenance:Scheduled overhauls, boiler tube replacements, and turbine blade inspections form recurring revenue streams for OEM service arms. Aging subcritical units across Uttar Pradesh and Madhya Pradesh drive demand for life extension assessments.
- Engineering:Supercritical welding certification, DCS architecture upgrades, and IoT integration protocols command premium pricing from Korean-Japanese licensors and qualified domestic fabricators. NTPC's pan-India pipeline sustains engineering dominance through proprietary specifications.
- Operations:Third-party O&M contracts for state gencos seeking cost optimization.
- Consulting:Environmental compliance advisory and tariff restructuring support before regulatory commissions.
Highest revenue concentration: Maintenance. Fastest margin expansion: Engineering.
Installation:
Capital deployment timing splits between new capacity additions and regulatory-forced asset modifications.
- Greenfield:New ultra-mega power plant developments face extended commissioning schedules due to land acquisition complexities and supercritical welding certification bottlenecks. Central Electricity Authority grid synchronization standards tighten excitation system requirements for fresh connections.
- Retrofits:Flue-gas desulfurization and selective catalytic reduction installations on pre-2017 units dominate service demand as CPCB emission deadlines approach. Plants above 500 MW in Maharashtra and Tamil Nadu face the steepest compliance curves.
- Brownfield:Capacity expansions at existing sites leveraging established coal linkages and water allocations.
- Upgrades:Digital turbine governor replacements and efficiency enhancement packages for mid-life assets.
Current investment priority: Retrofits. Longest project timelines: Greenfield.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and industrial corridors concentrate thermal generation demand across Indian states. Central Electricity Authority standards and state regulatory commissions shape investment flows. Coastal manufacturing belts and inland mining regions anchor divergent procurement priorities.
Maharashtra
Western Maharashtra's Mumbai-Pune industrial corridor drives baseload demand from automotive and pharmaceutical clusters. Maharashtra Electricity Regulatory Commission tariff orders influence merchant power contract structures. Ultra-mega power plant sites in Chandrapur and Nagpur leverage domestic coal linkages from nearby mines.
Gujarat
Petrochemical complexes in Hazira and Mundra anchor captive power expansion alongside port-linked generation clusters. Gujarat Electricity Regulatory Commission's renewable purchase obligations compress thermal plant load factors. Dahej and Sikka industrial zones drive demand for combined cycle configurations serving fluctuating process loads.
Tamil Nadu
Sriperumbudur-Oragadam automotive belt and cement manufacturers in Ariyalur district sustain thermal baseload requirements. Tamil Nadu Generation and Distribution Corporation's long-term power purchase agreements stabilize revenue visibility for independent producers. Ennore and Tuticorin coastal clusters integrate imported coal logistics with generation assets.
Andhra Pradesh
Krishna-Godavari delta agro-processing and Visakhapatnam steel corridor create distributed demand for mid-size thermal units. Andhra Pradesh Electricity Regulatory Commission's competitive bidding guidelines reshape procurement for new capacity. Kakinada and Krishnapatnam port zones enable cost-competitive fuel sourcing for coastal plants.
West Bengal
Asansol-Durgapur mining and manufacturing belt sustains demand for pithead generation leveraging Raniganj coal reserves. West Bengal State Electricity Distribution Company Limited's rural electrification mandates extend grid infrastructure toward thermal assets. Haldia petrochemical complex drives captive power requirements with waste heat recovery integration potential.
India Thermal Power Plant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across generation, equipment supply, and service verticals. State-owned NTPC Limited and regional gencos anchor centralized procurement through tender-based frameworks. Private independent power producers pursue merchant power exposure and captive fuel security. Strategic moves concentrate on backward integration into coal mining, transmission access rights, and emission control retrofit capabilities.
Within the state-owned tier, NTPC Limited exemplifies scale-driven engineering dominance across ultra-mega power plant developments. Among private operators, Adani Power Limited and Tata Power Company Ltd occupy positions defined by port-linked generation clusters and integrated Mumbai distribution footprints. These three anchors represent divergent strategic archetypes: centralized procurement leverage, captive fuel logistics, and end-to-end grid presence.
| Leading Market Players |
|---|
| Reliance Power Limited |
| Torrent Power Limited |
| NTPC Limited |
| APGENCO |
| JSW Energy |
| Adani Power Limited |
| MAHAGENCO |
| Haryana Power Generation Corporation Ltd |
| Tata Power Company Ltd |
| Others |
Supply & Pricing Matrix
Supercritical welding specialists concentrated in Gujarat and Tamil Nadu command 15-25 percent labor-cost premiums over standard pressure-vessel fabricators, compressing pricing spreads between premium Korean-Japanese boiler packages and domestic standard-tier alternatives. This workforce scarcity differential forces state gencos into longer lead-time commitments for advanced ultra-supercritical units while opening spot-market opportunities for refurbished subcritical equipment.
Pricing Analysis
Short lead-time premiums for supercritical boiler packages run 12-18 percent above standard-schedule contracts as NTPC and state gencos compete for qualified Korean-Japanese licensors. Project-based long-term offtake agreements dominate procurement, with price differentiation hinging on welding certification grade and bundled O&M service scope. Cost compression in the standard tier is intensifying because domestic fabricators absorb margin erosion to maintain volume against import competition. Merchant power producers exhibit highest price sensitivity due to exposure to day-ahead market volatility, while captive industrial buyers prioritize fuel security over unit cost.
Supply Chain Analysis
Welding certification bottlenecks in Gujarat, Tamil Nadu, and Korean fabrication hubs constrain supercritical component throughput, extending project timelines for advanced ultra-supercritical designs. Raw material dependencies center on high-alloy steel from South Korea and Japan, specialized turbine blades from German and Czech OEMs, and domestic coal linkages from allocated mining blocks. Single-source vulnerability in Korean-Japanese boiler licensing creates procurement risk for state gencos pursuing 42 percent-plus thermal efficiency targets. Distribution runs through EPC contractor-led project structures with NTPC and state gencos anchoring centralized tender volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Central Pollution Control Board emission deadlines for plants above 500 MW erect a compliance-cost barrier that favors incumbent operators with retrofit execution experience and existing environmental permits. This regulatory moat compresses viable entry pathways to acquisition rather than greenfield development.
For Market Incumbents: Deploy captive coal logistics integration to insulate generation economics from Indonesian and South African thermal coal price volatility. State gencos should consolidate engineering procurement through pan-India tender frameworks, leveraging NTPC's specification standards to compress Korean-Japanese licensor premiums. Threat substitution from solar-wind hybrid projects demands accelerated biomass co-firing pilot programs to preserve plant load factors under renewable purchase obligation norms. For New Entrants and Emerging Players: Launch via selective catalytic reduction retrofit specialization targeting Maharashtra and Tamil Nadu plants commissioned before 2017. White-space concentration sits with flue-gas desulfurization engineering services for subcritical units facing CPCB sulfur dioxide deadlines. Industrial cogeneration clusters in Gujarat's petrochemical belt offer the most penetrable captive power segment, with waste heat recovery integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with engineering contractors holding supercritical welding certification given NTPC's pan-India pipeline expansion and state genco procurement centralization. Long-term viability over the next decade hinges on emission control retrofit capabilities rather than pure generation capacity. Acquisition target archetype: domestic fabricators with Korean-Japanese technology licensing relationships. Signal to watch: Ministry of Power biomass co-firing mandate enforcement pace as indicator of fuel diversification optionality value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal Mining | Allocated mining rights from Ministry of Coal stabilize fuel costs against import price volatility for integrated operators. |
| Flue-Gas Desulfurization Retrofit Deployment | CPCB compliance deadlines for plants above 500 MW create premium service margins for qualified engineering contractors. |
| Supercritical Welding Certification Investment | Specialized fabrication protocols from Korean-Japanese licensors compress commissioning schedules for ultra-mega power plant sites. |
| Biomass Co-Firing Pilot Programs | Ministry of Power blending mandates open fuel diversification pathways for pulverized coal units facing renewable penetration. |
| Merchant Power Offtake Agreement Structuring | Flexible bilateral contracts with aluminum smelters and cement manufacturers capture peak demand pricing premiums. |
Research Methodology
Multi-period observation of supercritical boiler procurement volumes, emission control retrofit installation rates, and state genco tender award patterns anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and Central Electricity Authority technical staff. Secondary validation drew from CEA generation capacity databases, Central Pollution Control Board compliance filings, state electricity regulatory commission tariff orders, and Ministry of Power policy directives. Bottom-up project pipeline tracking triangulated against top-down capacity addition forecasts to reconcile volume estimates.
Input-output matrices mapped fuel source, generation capacity tier, regulatory framework, and regional grid type against procurement value flows across the projection horizon. CAGRs were derived from segmented growth trajectory modeling with cross-validation against historical capacity commissioning patterns. Forecast inputs incorporated coal price index volatility assumptions, renewable purchase obligation enforcement trajectories, and supercritical technology adoption curves by state utility.
Regulatory enforcement delays, imported coal price spikes, and renewable integration mandate acceleration are the dominant revision risks for thermal capacity utilization assumptions. Forecasts reflect documented assumptions on emission compliance timelines and transmission infrastructure expansion schedules. Material deviation in CPCB deadline adherence or inter-regional grid bottleneck resolution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Algeria Power Market
Power Generation
Commercial Gensets Market
Power Generation
Retail Electricity Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Global Turbines Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Residential Solar Generator Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Gas Gensets Market
Power Generation
Global Power Grid System Market
Power Generation
Indonesia Power Market
Power Generation
Global Power Generation Market