
 South America Consumer Battery Market | 2026-2036
South America Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Consumer Battery Market Analytics
The gap between premium lithium-ion packs and commodity alkaline cells is shifting as power density expectations diverge across consumer segments. Duracell Inc. anchors the alkaline mass market through retail channel control in Brazil and Argentina. Samsung SDI Co. Ltd leverages its cylindrical cell expertise to dominate power tool and laptop OEM supply. BYD Co Ltd competes on blade-cell cost structures for emerging residential energy storage applications.
Consumer batteries are electrochemical energy storage devices ranging from 1.5V primary cells to 48V lithium-ion packs, manufactured through electrode coating, winding or stacking, electrolyte filling, and formation cycling to deliver portable power for electronic devices. Alkaline chemistry still occupies the largest volume share in residential flashlight and remote control applications across South America. Lithium-ion segments lead value generation due to higher unit economics in smartphone and laptop replacements. The automotive end user category is expanding fastest as Brazilian consumers adopt mild-hybrid vehicles requiring auxiliary battery systems.
Brazil's INMETRO certification requirements and Argentina's IRAM safety standards shape import compliance costs for foreign manufacturers seeking market access. ANVISA oversight of medical device batteries and Chile's SEC electrical safety protocols add further regulatory layers for specialized applications. Stakeholders must monitor how Mercosur harmonization efforts resolve testing standard fragmentation across the customs union.
Market Dynamics
Lithium-ion chemistry is compressing the addressable market for primary cells across Brazilian and Argentine households, while Mercosur regulatory fragmentation forces parallel certification tracks for importers.
Growth Catalysts
- INMETRO certification harmonization:Brazil's national metrology institute is streamlining testing protocols for lithium-ion packs, reducing time-to-market for regional suppliers.
- Mild-hybrid vehicle proliferation:Brazilian OEMs are integrating 48V auxiliary battery systems into passenger vehicles, creating fresh demand for cylindrical cell formats.
- Residential solar-plus-storage:Argentine households in grid-unreliable provinces are adopting blade-cell battery banks for nighttime load shifting.
Market Restraints
- Lithium carbonate price volatility:Argentine salares and Chilean brine operations dominate cathode material supply, exposing cell assemblers to input cost swings.
- IRAM safety standard stringency:Argentina's national standards body mandates destructive testing for all imported lithium chemistries, elevating compliance costs for foreign entrants.
- Alkaline format lock-in:Flashlight and remote control manufacturers in Paraguay and Uruguay continue specifying zinc-manganese dioxide cells due to established supply chains.
Strategic Opportunities
- Medical device battery specialization:ANVISA oversight of implantable and portable diagnostic equipment creates a premium segment for certified cell suppliers.
- Direct-to-installer distribution:Bypassing traditional electronics retail through electrical contractor channels captures residential energy storage growth in São Paulo's metropolitan zone.
- Recycling infrastructure gaps:Brazil lacks pyrometallurgical recovery capacity for end-of-life lithium-ion packs, inviting vertical investment in black mass processing.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell formation and electrolyte formulation expertise concentrates in São Paulo's research institutes, constraining plant expansion in secondary states.
- Dual certification timelines:Manufacturers must sequence INMETRO and IRAM approvals sequentially, extending product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Consumer Battery Market |
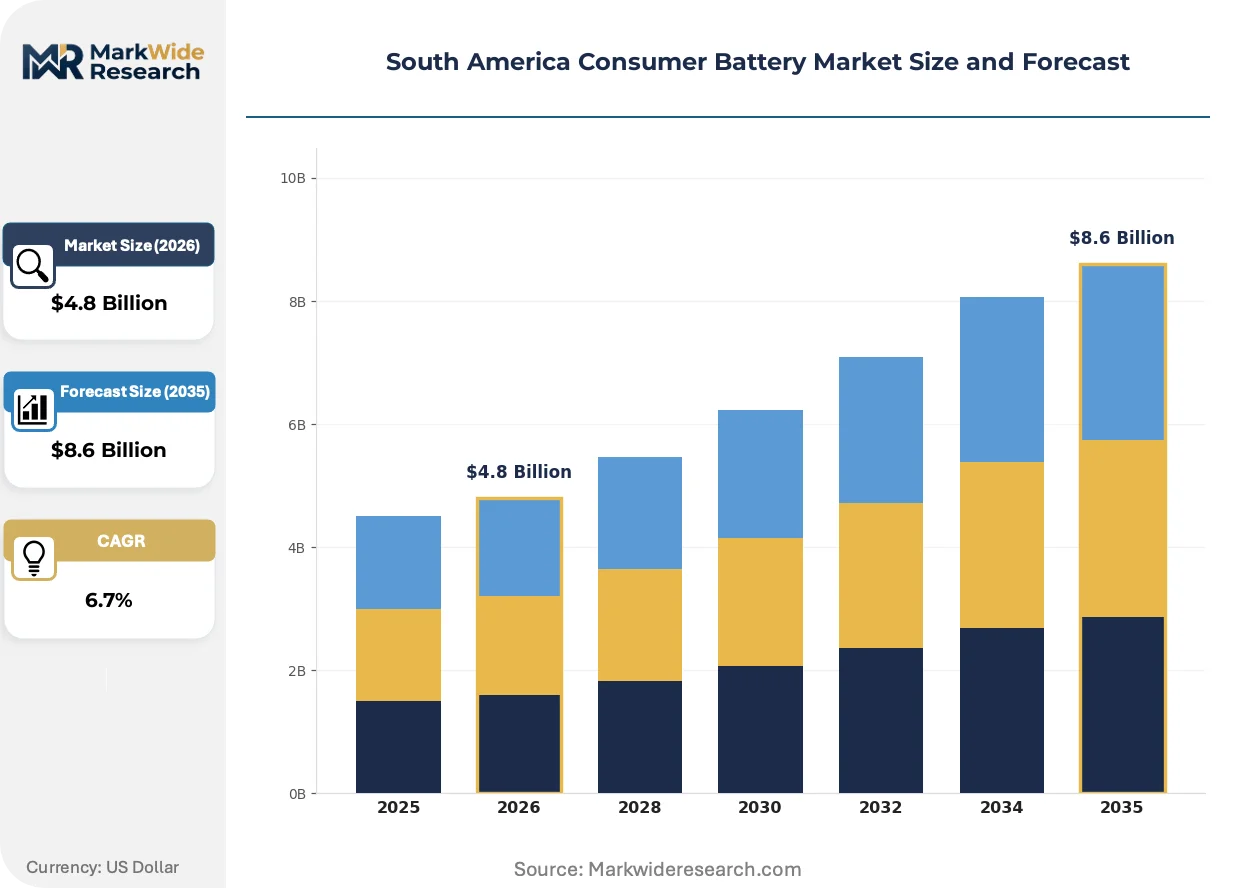
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, NiMH, Alkaline, Lead-Acid Application: Smartphones, Laptops, Power Tools, Electric Vehicles End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Wholesalers |
| Companies Covered | Duracell Inc., BYD Co Ltd, Samsung SDI Co. Ltd, LG Chem Ltd, Panasonic Corporation, Energizer Holdings Inc., EnerSys, Spectrum Brands Holdings Inc., Camelion Battery Co. Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Consumer Battery Market Evolving Landscape
Solid-state electrolyte research is advancing through Brazilian university partnerships, while regulatory pressure on thermal runaway risks accelerates safety system integration. Demand-side fragmentation is reshaping how cells reach end users.
Solid-state ceramic separators are unifying energy density and safety performance in next-generation pouch cells. Brazilian electronics OEMs are piloting these formats for premium laptop lines. The technology is unifying previously separate BMS architectures into single-chip protection solutions, compressing subsystem costs.
IRAM is tightening thermal propagation testing requirements for lithium-ion imports under updated electrical safety protocols. Cell assemblers must now submit full module-level abuse data rather than single-cell results. Medical device manufacturers in Buenos Aires are absorbing these costs fastest, passing premiums through to hospital procurement.
After-sales service unbundling is separating battery replacement from original device warranties across Argentine consumer electronics retail. Independent repair shops in Córdoba and Rosario are capturing smartphone cell swaps previously monopolized by authorized channels. Chilean SEC electrical safety protocols are accelerating this shift by legitimizing third-party technician certification.
South America Consumer Battery Market Segmentation
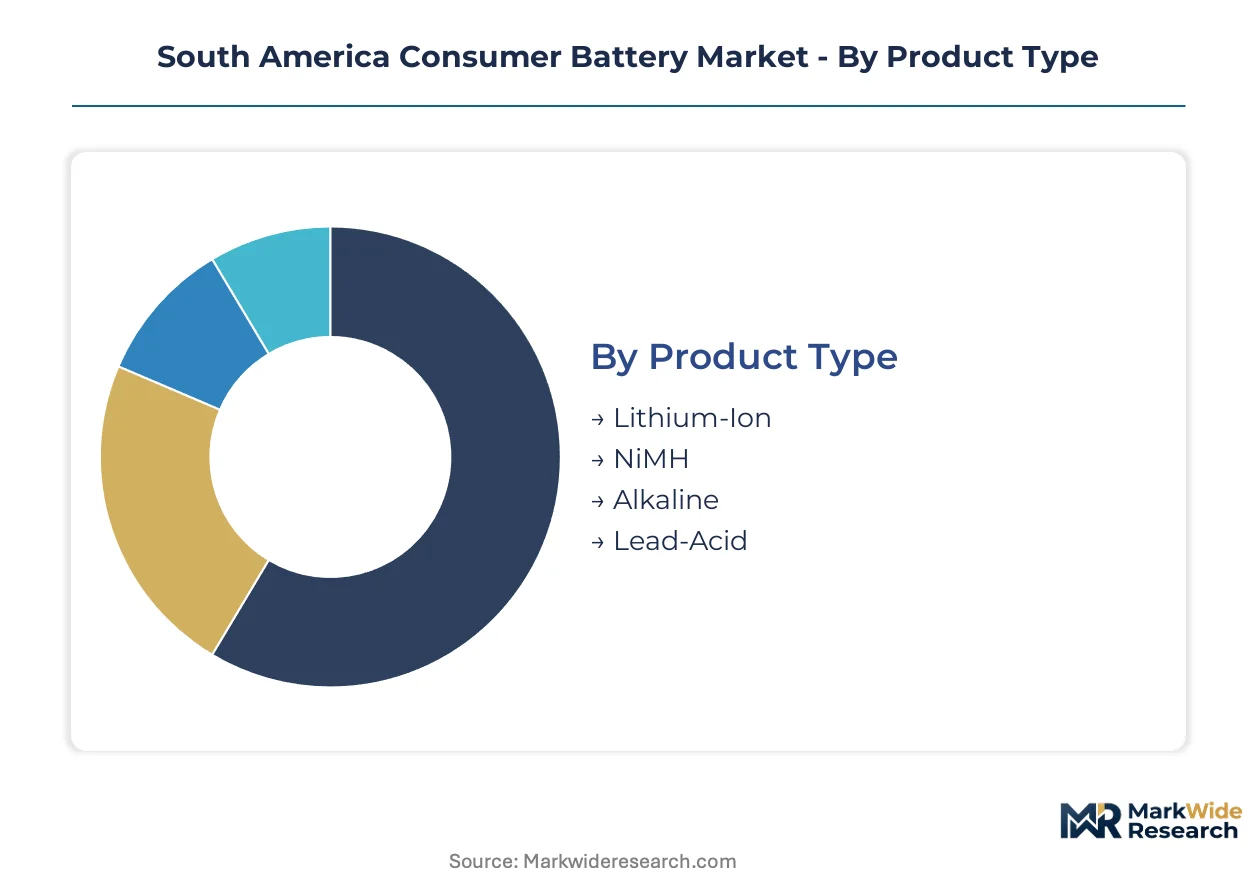
Battery chemistry and application fragmentation across South America demands granular segmentation. Brazilian INMETRO certification tiers and Argentine IRAM safety classifications create distinct commercial boundaries between product categories.
Product Type:
Supply concentration for cathode materials in Chilean brine operations and Argentine salares directly shapes cost structures across cell chemistries imported into Brazil and Argentina.
- Lithium-Ion:Rechargeable cells utilizing lithium cobalt oxide or lithium iron phosphate cathodes deliver energy densities exceeding 250 Wh/kg. Demand concentrates in São Paulo's electronics manufacturing corridor where smartphone OEMs specify high-cycle-life pouch formats. INMETRO certification timelines for lithium-ion packs now run 30% shorter than legacy protocols.
- Alkaline:Zinc-manganese dioxide primary cells with 1.5V nominal output dominate flashlight and remote control applications across Paraguayan and Uruguayan retail. Established supply chains from Brazilian coastal ports lock in alkaline procurement for mass-market distributors in Asunción and Montevideo.
- NiMH:Nickel-metal hydride cells serve legacy power tool bases and cordless phone replacements in Argentine provinces with slower lithium-ion adoption.
- Lead-Acid:Flooded and AGM formats persist in automotive starter applications and budget residential backup systems across Brazil's northeastern states.
Today's leader: Alkaline. Tomorrow's challenger: Lithium-Ion.
Application:
Volume tiers separate high-unit-value OEM supply from replacement market transactions across South American distribution networks.
- Smartphones:Compact lithium-ion pouch cells with integrated protection circuits power Brazil's 250 million active mobile connections. Replacement demand clusters in independent repair shops across Córdoba and Rosario where ANVISA oversight is lighter than hospital-grade equipment.
- Electric Vehicles:48V mild-hybrid auxiliary battery systems from Brazilian OEMs specify cylindrical NMC cells. IRAM's updated thermal propagation testing now mandates module-level abuse data submission, elevating compliance costs for foreign assemblers.
- Laptops:18650 and 21700 cylindrical formats supply notebook OEMs in São Paulo's industrial free zones.
- Power Tools:Brushless motor compatibility drives lithium-ion pack adoption among Brazilian construction contractors in Minas Gerais.
Smartphone replacement volumes anchor current revenue. Electric vehicle auxiliary systems claim the steepest expansion trajectory.
End User:
Customer procurement sophistication spans retail self-selection to engineered specification across South America's battery-consuming sectors.
- Residential:Grid-unreliable Argentine households in provinces like Mendoza adopt blade-cell battery banks for nighttime load shifting. Direct-to-installer distribution channels in São Paulo's metropolitan zone bypass traditional electronics retail markup structures.
- Automotive:Brazilian OEMs integrate auxiliary battery systems into mild-hybrid passenger vehicles, creating fresh demand for cylindrical cell formats with enhanced vibration tolerance.
- Commercial:Retail chains and office complexes across Santiago specify UPS battery replacements under Chile's SEC electrical safety protocols.
- Industrial:Mining operations in Chile's Atacama deploy ruggedized lithium-ion packs for remote sensor networks.
Residential demand scales through installer networks. Automotive procurement is consolidating around OEM qualification programs.
Distribution Channel:
Channel margins compress where certification burdens concentrate, favoring vertically integrated suppliers with in-house INMETRO and IRAM testing capabilities.
- Electronics Stores:Authorized retail chains in São Paulo and Buenos Aires stock certified lithium-ion packs with full warranty coverage. Samsung SDI and BYD maintain dedicated shelf space through direct vendor-managed inventory agreements.
- Wholesalers:Bulk alkaline and lead-acid distribution to Paraguayan and Uruguayan resellers runs through Brazilian port logistics hubs. Duracell anchors this channel through decades-long distributor relationships.
- Online Retail:Marketplace platforms face ANVISA scrutiny for medical device battery listings, segmenting compliance-capable sellers from gray-market operators.
- Supermarkets:Mass-market alkaline blister packs reach Brazilian household penetration through grocery retail in Rio de Janeiro and Belo Horizonte.
Electronics stores command premium positioning. Wholesalers capture volume throughput across Mercosur border trade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical engineering talent concentrates in São Paulo's research institutes, anchoring Brazil's cell formation and electrolyte formulation capabilities while constraining plant expansion in secondary states.
Brazil
INMETRO certification harmonization is streamlining lithium-ion pack testing protocols, reducing time-to-market for regional suppliers. ANVISA oversight of medical device batteries adds regulatory layers for specialized applications. São Paulo's industrial free zones host notebook OEMs specifying 18650 and 21700 cylindrical formats, while Minas Gerais construction contractors drive brushless motor-compatible lithium-ion pack adoption.
Argentina
Grid-unreliable households in Mendoza province adopt blade-cell battery banks for nighttime load shifting. IRAM mandates destructive testing for all imported lithium chemistries, elevating compliance costs for foreign entrants. Buenos Aires medical device manufacturers absorb updated thermal propagation testing costs fastest, passing premiums through to hospital procurement channels.
Chile
Mining operations in the Atacama deploy ruggedized lithium-ion packs for remote sensor networks. SEC electrical safety protocols accelerate after-sales service unbundling, legitimizing third-party technician certification for battery replacement. Santiago retail chains and office complexes specify UPS battery replacements under tightening electrical safety frameworks.
Paraguay
Flashlight and remote control manufacturers continue specifying zinc-manganese dioxide cells due to established supply chains from Brazilian coastal ports. Mass-market distributors in Asunción lock in alkaline procurement through decades-long wholesaler relationships. Grid stability in urban centers delays lithium-ion adoption for residential applications.
Uruguay
Montevideo retail channels mirror Paraguayan alkaline format lock-in for household electronics. Brazilian port logistics hubs dominate bulk battery distribution to Uruguayan resellers. Consumer electronics penetration rates trail regional peers, compressing addressable market scale for advanced cell chemistries.
South America Consumer Battery Market Competitive Landscape
Top-tier vendors anchor premium lithium-ion supply to OEM channels, while mass-market alkaline distributors control retail shelf space through vendor-managed inventory agreements. The vendor base stratifies across three functional tiers: chemistry specialists, format generalists, and private-label assemblers. Strategic archetypes include cylindrical cell experts, blade-cell cost optimizers, and primary cell incumbents. Competitive moves concentrate on direct-to-installer channel development and in-house certification testing capabilities.
Within the premium-tier vector, Samsung SDI Co. Ltd and LG Chem Ltd occupy positions as cylindrical cell specialists supplying power tool and laptop OEM segments. BYD Co Ltd exemplifies the blade-cell cost structure archetype targeting residential energy storage applications. Duracell Inc. anchors mass-market alkaline distribution through retail channel control in Brazil and Argentina, representing the incumbent primary cell position.
| Leading Market Players |
|---|
| Duracell Inc. |
| BYD Co Ltd |
| Samsung SDI Co. Ltd |
| LG Chem Ltd |
| Panasonic Corporation |
| Energizer Holdings Inc. |
| EnerSys |
| Spectrum Brands Holdings Inc. |
| Camelion Battery Co. Ltd |
| Others |
Value Network & Pricing Analysis
Captive sourcing of lithium carbonate from Chilean brine operations and Argentine salares anchors cell assembler supply positions while concentrating pricing power among cathode material suppliers. This upstream control cascades into downstream battery pack economics, where certification burdens and chemistry choices fragment pricing tiers across Brazilian and Argentine distribution channels.
Pricing Analysis
Bundled after-sales service packages are separating from core battery transactions across Argentine consumer electronics retail, while standalone cell pricing dominates Brazilian wholesale channels. Three-tier pricing structure across premium certified, standard compliant, and economy gray-market levels reflects INMETRO and IRAM certification investment differentials. Cost compression in economy-tier alkaline cells is intensifying because Brazilian port logistics hubs face container handling bottlenecks. Mass-market flashlight and remote control manufacturers in Paraguay and Uruguay exhibit highest price sensitivity, whereas Buenos Aires medical device OEMs absorb premium lithium-ion pricing with minimal procurement friction.
Supply Chain Analysis
Single-source vulnerability sits with Chilean brine operations supplying cathode precursor materials to Brazilian cell assemblers. Manufacturing capacity concentrates in China, South Korea, and Japan for finished lithium-ion cells, while electrode coating and formation cycling equipment draws from German and Japanese machinery suppliers. Supply chain risk centers on lithium carbonate price volatility from Atacama salares exposure. Distribution runs through São Paulo's electronics free zones for OEM supply and Brazilian coastal port logistics hubs for mass-market alkaline distribution to Mercosur neighbors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in South American consumer batteries rests on blade-cell cost-down curves displacing legacy formats and premium medical-device certification tiers capturing hospital procurement premiums. Electrochemical engineering scarcity and regulatory fragmentation create defendable positioning for early movers.
For Market Incumbents: Lock in electrolyte formulation talent through partnerships with São Paulo's research institutes before competitors exhaust the limited pool. Defend channel position by embedding vendor-managed inventory agreements with electronics retail chains in São Paulo and Buenos Aires. Certification investment in ANVISA medical-device pathways creates switching costs against emerging Asian suppliers.
For New Entrants and Emerging Players: Electrical contractor networks in São Paulo's metropolitan zone represent the most penetrable channel for residential energy storage blade-cell distribution. Target grid-unreliable Argentine provinces like Mendoza where nighttime load-shifting demand outpaces established supply. Bypass traditional retail markup through direct-to-installer pricing models.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cell assemblers with in-house INMETRO and IRAM testing capabilities because dual certification timelines extend product launch cycles and deter fragmented competition. Acquisition targets with captive pyrometallurgical recovery capacity will command scarcity premiums as Brazil's end-of-life lithium-ion waste stream expands. Watch for Mercosur harmonization announcements as inflection signals for compliance cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium carbonate sourcing from Chilean salares insulates Brazilian assemblers from input cost volatility. |
| Direct-to-Installer Channel Development | Bypassing electronics retail markup captures residential storage growth in São Paulo's metropolitan zone. |
| ANVISA Medical Device Certification Investment | Premium hospital procurement channels in Buenos Aires absorb certified cell premiums with minimal price resistance. |
| Pyrometallurgical Recovery Capacity Buildout | Brazil's black mass processing gap invites vertical investment ahead of end-of-life lithium-ion waste expansion. |
| Solid-State Electrolyte University Partnerships | Brazilian research institute collaborations advance ceramic separator formats for premium laptop OEM supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell formation engineers, electronics retail category managers, electrical contractor network heads, and ANVISA regulatory affairs specialists with secondary validation. Trade data from Brazilian customs authorities, INMETRO certification registries, Chilean SEC electrical safety filings, and Argentine IRAM testing records anchored supply-side sizing. Bottom-up cell shipment estimates and top-down electronics manufacturing value analysis were triangulated against OEM procurement disclosures.
Historical reference periods spanning five years anchored the projection horizon, with growth trajectories derived from chemistry-specific adoption curves and regulatory implementation timelines. Segmentation modeling spanned product chemistry, application device category, end-user procurement sophistication, and distribution channel margin structure. Cylindrical versus pouch format splits, INMETRO certification tier progression, and mild-hybrid vehicle auxiliary battery integration rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur regulatory harmonization progress and lithium carbonate supply disruptions from Chilean salares. Forecasts reflect documented assumptions about electrolyte cost curves and certification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Military Battery Market
Batteries
Atomic Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Alkaline Battery Market
Batteries
Rechargeable Battery Market
Batteries
South America Battery Cell Market
Batteries
Power-Sports Batteries Market
Batteries
Middle East Rechargeable Battery Market
Batteries
Portable Battery Station Market
Batteries
East Africa Battery Market
Batteries
Marine Low-Voltage Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
Molten Salt Battery Market
Batteries
South and Central America Battery Market
Batteries
West Europe Battery Market
Batteries
Aluminium-Sulfur Battery Market