
 Europe Aviation Fuel Market | 2026-2036
Europe Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aviation Fuel Market Foresight
SAF-grade fuel certification is rotating from niche pilot programs toward fleet-wide procurement protocols across European carriers. Shell plc leverages its Rotterdam biorefinery complex to anchor supply security for Amsterdam Schiphol and Frankfurt hub operations. BP plc sustains conventional Jet A-1 distribution dominance through its Antwerp refining network while competing on forward SAF offtake contracts with International Airlines Group and Air France-KLM.
Aviation fuel denotes refined petroleum products meeting strict energy density, flash point, and freeze point specifications for gas turbine propulsion, with Jet A-1 requiring a maximum freeze point of minus 47 degrees Celsius for high-altitude operations. Conventional refining still occupies the majority volume position, yet biorefining represents the fastest-expanding technology segment as hydroprocessed esters and fatty acids pathways achieve ASTM D7566 certification. Commercial airlines generate the largest end-user revenue pool, while business aviation channels command premium pricing through direct supply arrangements at dedicated FBO terminals.
ReFuelEU Aviation mandates progressively binding SAF blend rates, while ECHA oversees chemical safety assessments for novel biogenic feedstocks entering the supply chain. The EU Green Deal's broader decarbonization framework channels public financing toward synthetic fuel production demonstrations in Denmark and the Netherlands. Stakeholders must monitor ASTM certification timelines for alcohol-to-jet pathways and assess whether centralized fuel farm infrastructure at Paris Charles de Gaulle and Frankfurt can accommodate parallel conventional and biogenic logistics without operational disruption.
Market Dynamics
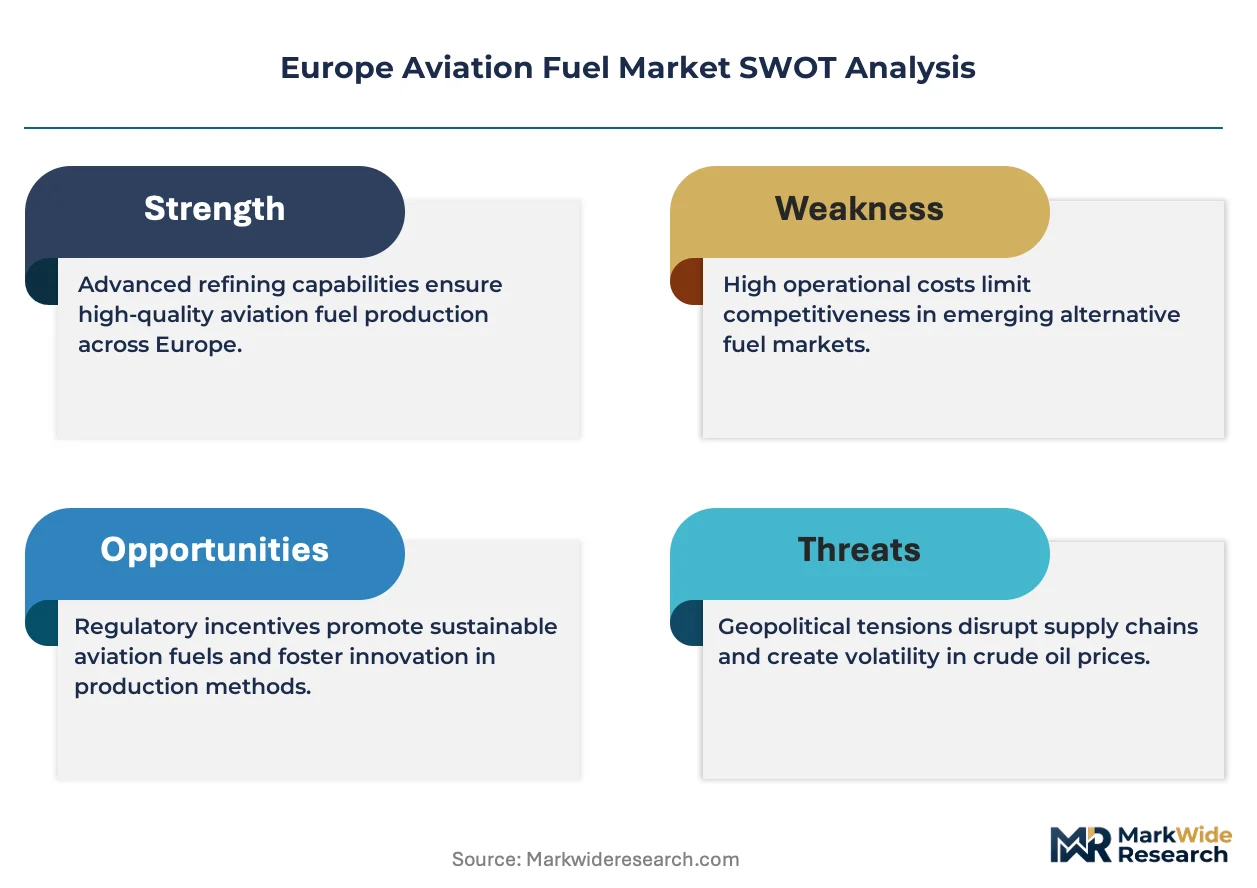
The EU Green Deal's ReFuelEU Aviation mandate is compressing the timeline for sustainable aviation fuel adoption, forcing fuel suppliers and airlines to reconfigure procurement contracts, storage infrastructure, and fleet certification pathways simultaneously.
Growth Catalysts
- ReFuelEU Aviation mandate:Binding SAF blend requirements escalate from 2025 through 2035, creating guaranteed demand pull for certified biogenic and synthetic pathways.
- Hydroprocessed esters and fatty acids technology:ASTM D7566 certification unlocks fleet-wide deployment without engine modifications, accelerating airline adoption.
- Rotterdam-Frankfurt-Amsterdam hub concentration:Co-located biorefinery investments and dedicated SAF fuel farms enable supply security at Europe's highest-volume airports.
Market Restraints
- Feedstock cost volatility:Used cooking oil and animal fat prices fluctuate with biodiesel competition, compressing SAF refining margins.
- Biorefinery supply concentration:Neste Oyj's Rotterdam facility and limited comparable scale projects create single-point vulnerability for Northwest European supply.
- Alcohol-to-jet pathway immaturity:ASTM certification timelines for ethanol and methanol conversion remain unresolved, blocking lignocellulosic feedstock commercialization.
Strategic Opportunities
- Power-to-liquid synthetic fuels:Denmark and the Netherlands host publicly financed demonstration plants for e-kerosene production using renewable hydrogen and captured carbon.
- Business aviation direct supply arrangements:Fixed-base operator terminals at London Biggin Hill and Geneva Cointrin enable premium SAF pricing outside hub congestion.
- CSRD disclosure requirements:Corporate sustainability reporting mandates push large enterprises toward SAF-booking programs for scope 3 emissions reduction.
Industry Challenges
- ASTM certification bottleneck:Novel biogenic feedstock approvals require multi-year ECHA safety assessments and engine manufacturer validation cycles.
- Parallel logistics infrastructure:Conventional Jet A-1 and SAF require segregated storage and handling systems at Charles de Gaulle and Frankfurt fuel farms.
- Biorefining talent scarcity:Hydroprocessing expertise concentrates in petroleum refining, creating recruitment gaps for lipid conversion and catalyst management roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aviation Fuel Market |
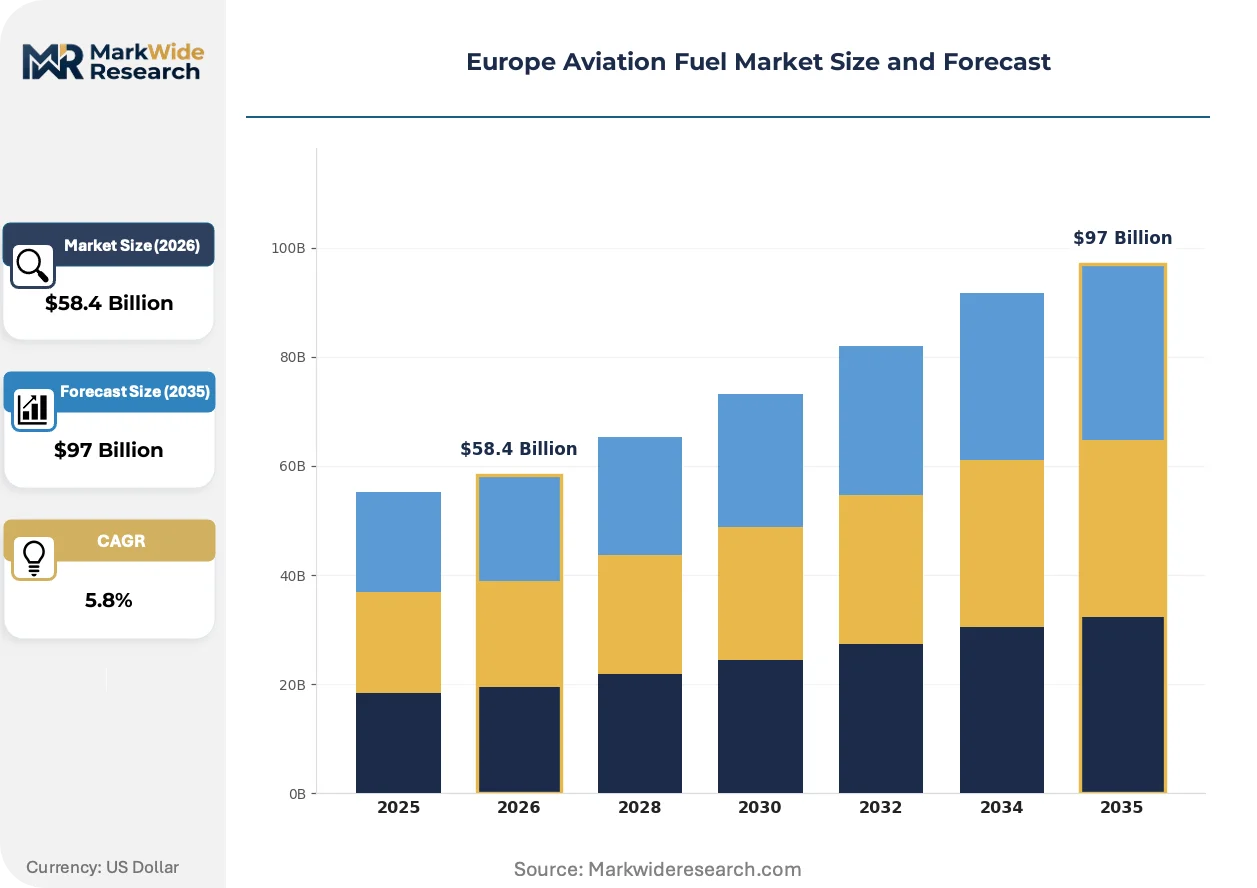
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Avgas End User: Commercial Airlines, Cargo Airlines, Business Aviation, Military Aviation Distribution Channel: Direct Supply, Resellers, Airports, Fuel Farms Technology: Conventional Refining, Biorefining, Synthetic Fuel Production, Additive Systems |
| Companies Covered | Repsol SA, Exxon Mobil Corporation, BP plc, Chevron Corporation, Gazprom Neft PJSC, Shell plc, Neste Oyj, Kuwait Petroleum Corporation, TotalEnergies SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aviation Fuel Market Shifts & Advancements
Aviation fuel supply chains are bifurcating into conventional petroleum refining and biogenic processing streams, with certification protocols, procurement contracts, and airport infrastructure evolving in parallel rather than sequentially.
Modular biorefinery units for hydroprocessed esters and fatty acids conversion are miniaturizing from 500,000-tonne annual capacities toward distributed 50,000-tonne installations. Regional airports in France and Sweden pilot these scaled systems to serve short-haul carrier networks. The compression enables feedstock sourcing from local agricultural and waste streams rather than global commodity markets.
REACH registration requirements for novel biogenic feedstocks are tightening purity and traceability documentation. ECHA's expanded chemical safety assessments extend approval timelines for algae-derived and forestry-residue pathways. Suppliers targeting synthetic fuel production in the Netherlands accelerate pre-submission data packages to secure conditional authorizations.
Long-term offtake contracting is displacing spot market purchasing for SAF volumes. International Airlines Group and Air France-KLM negotiate decade-long supply agreements directly with biorefinery developers, bypassing traditional fuel supplier intermediaries. This restructuring concentrates procurement leverage among large flag carriers while regional operators face allocation constraints.
Europe Aviation Fuel Market Segmentation
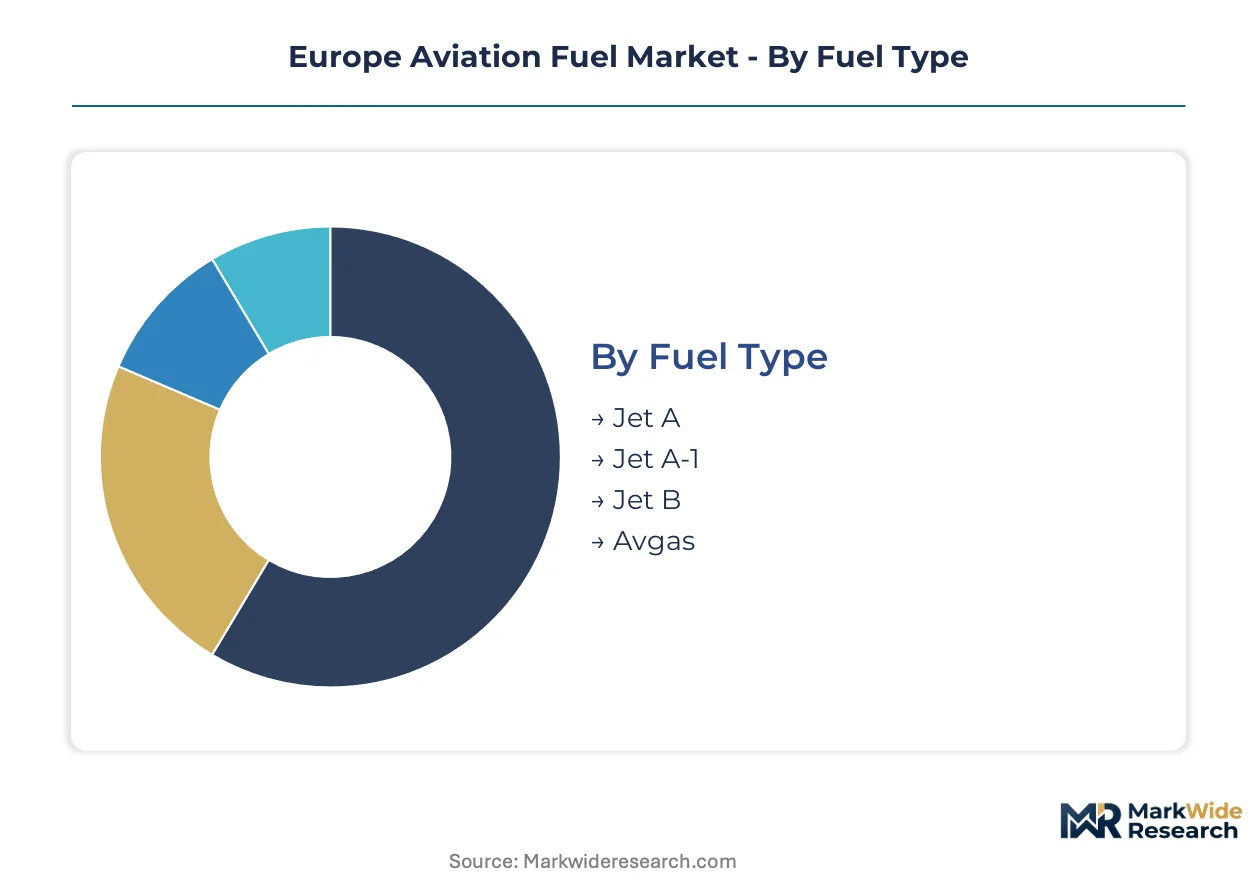
Europe's aviation fuel segmentation reflects divergent supply chain configurations across conventional petroleum refining and emerging biogenic pathways. Regulatory mandates under ReFuelEU Aviation are fragmenting procurement patterns by fuel type, end user, and technology maturity. Each segment carries distinct certification requirements, infrastructure dependencies, and geographic concentration profiles.
Fuel Type:
Jet A-1 dominates domestic European consumption for high-altitude operations, while Jet A retains transatlantic supply chain linkages. Jet B and Avgas serve specialized regional niches with limited cross-border trade.
- Jet A-1:Kerosene-based turbine fuel requiring maximum freeze point of minus 47 degrees Celsius per DEF STAN 91-91 specifications. Demand concentrates at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle where long-haul carriers face ReFuelEU Aviation blending mandates. Airlines at these hubs are retrofitting fuel farm infrastructure to accommodate segregated SAF storage.
- Jet A:Slightly higher freeze point specification than Jet A-1, predominantly supplied through Antwerp-Rotterdam refining corridor for North Atlantic routes. British Airways and Virgin Atlantic procurement contracts favor this grade for London Heathrow transatlantic departures, though SAF blending ratios are compressing conventional volume share.
- Jet B:Wide-cut gasoline-kerosene blend for extreme cold climate operations, limited to northern Scandinavian airports and Arctic route alternates.
- Avgas:High-octane aviation gasoline for piston-engine aircraft, concentrated at general aviation fields in France and Germany with declining volume trajectory.
Jet A-1 holds the largest share; momentum sits with SAF-certified variants of this grade.
End User:
Commercial carriers generate volume concentration at hub airports, while business aviation commands premium pricing through direct supply arrangements. Cargo operators and military buyers operate on separate procurement frameworks with limited SAF exposure.
- Commercial Airlines:Flag carriers including Air France-KLM, Lufthansa Group, and International Airlines Group negotiate decade-long SAF offtake contracts directly with biorefinery developers. Their fleet-wide certification for ASTM D7566 blends is redirecting capital toward Rotterdam and Neste Oyj supply commitments.
- Business Aviation:Fixed-base operator terminals at London Biggin Hill and Geneva Cointrin enable segregated SAF logistics for corporate jet operators. This segment purchases at 40-60 percent premiums over hub pricing due to dedicated handling and smaller batch requirements.
- Cargo Airlines:DHL Express and FedEx European hubs at Leipzig and Cologne Bonn prioritize conventional Jet A-1 for freighter fleet compatibility, with SAF adoption lagging passenger carriers.
- Military Aviation:NATO standard F-34 procurement through national defense fuel agencies operates outside EU blending mandates, maintaining petroleum-based supply security protocols.
Commercial airlines dominate volume; business aviation delivers the steepest margin expansion.
Distribution Channel:
Hub airport fuel farms are consolidating SAF segregation capabilities, while direct supply contracts are displacing reseller intermediaries for sustainable volumes. Channel selection correlates with carrier scale and certification timeline urgency.
- Direct Supply:Long-term agreements between airlines and biorefinery operators bypass traditional fuel suppliers, concentrating procurement leverage among International Airlines Group and Air France-KLM scale carriers.
- Resellers:Independent fuel traders retain relevance for spot market conventional Jet A-1 at secondary airports lacking dedicated SAF infrastructure.
- Airports:Charles de Gaulle and Frankfurt are retrofitting fuel farm hydrant systems for parallel conventional and biogenic logistics, requiring segregated storage tanks and quality testing protocols.
- Fuel Farms:Rotterdam port complex biorefinery co-location enables pipeline delivery to Amsterdam Schiphol, reducing trucking costs and contamination risk.
Airport fuel farms anchor volume throughput; direct supply channels are climbing fastest.
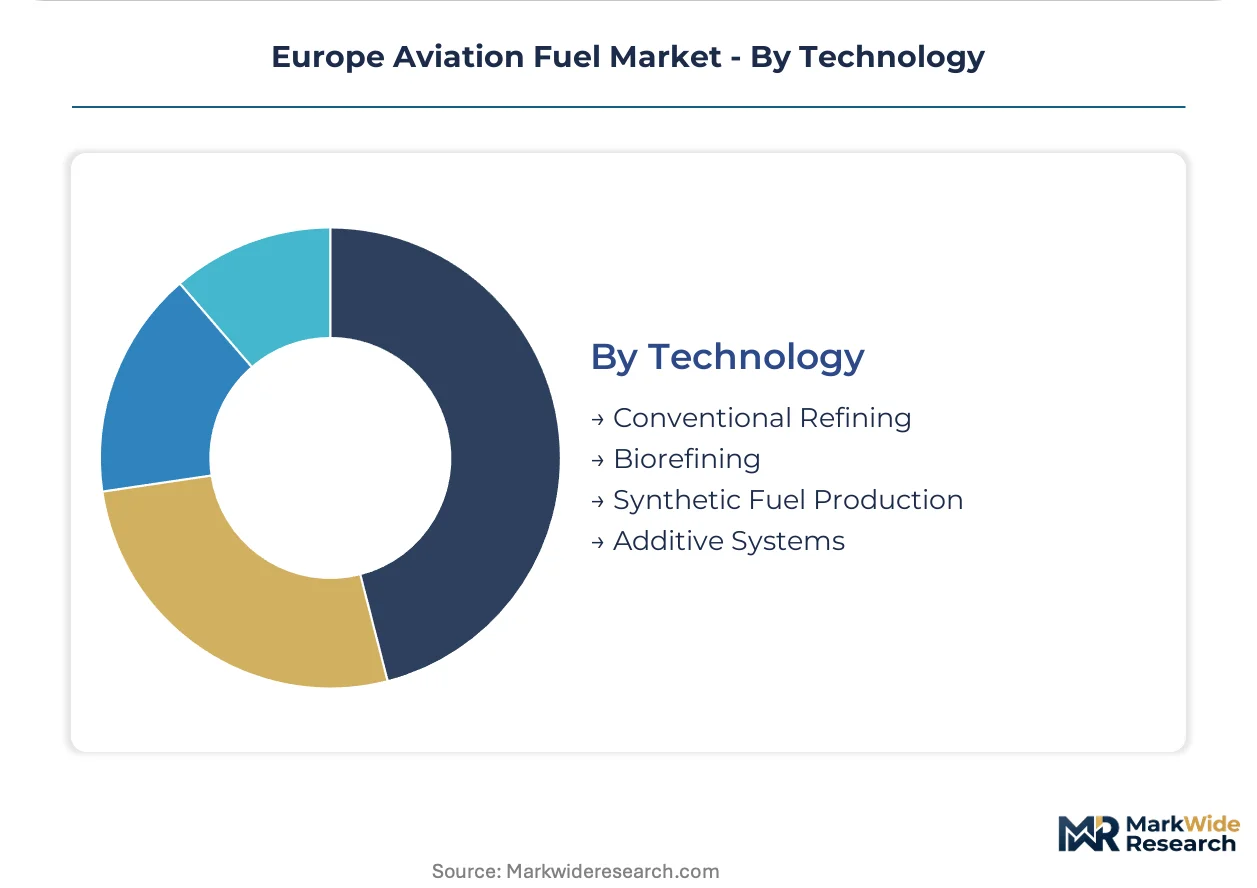
Technology:
Conventional refining retains capacity dominance at Antwerp and Rotterdam complexes, while biorefining attracts green financing and synthetic fuel demonstrations receive Dutch and Danish public funding.
- Conventional Refining:Fluid catalytic cracking and hydroprocessing units at BP's Antwerp complex and Shell's Pernis facility sustain Jet A-1 output for legacy fleet compatibility.
- Biorefining:Hydroprocessed esters and fatty acids pathways achieve ASTM D7566 certification without engine modifications, with Neste Oyj's Rotterdam facility supplying Amsterdam and Frankfurt hubs.
- Synthetic Fuel Production:Power-to-liquid e-kerosene demonstrations in Denmark and the Netherlands use renewable hydrogen and captured carbon, awaiting cost parity timelines.
- Additive Systems:Antioxidant and static dissipator additive injection systems at fuel farms ensure storage stability and handling safety for both conventional and SAF grades.
Conventional refining holds installed capacity leadership; biorefining delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's aviation fuel trade flows reflect a structural import dependency for crude feedstocks counterbalanced by biorefinery export capacity concentrated in the Netherlands and Belgium. The region processes substantial volumes through the Rotterdam-Antwerp refining corridor while SAF production investments reshape intra-European supply patterns.
Germany
Lufthansa Group's fleet decarbonization commitments drive SAF procurement volumes at Frankfurt and Munich hubs. The country's national implementation of ReFuelEU Aviation mandates accelerates fuel farm infrastructure retrofits. The Rhine-Main metropolitan cluster anchors conventional refining capacity while Hamburg hosts emerging synthetic fuel research demonstrations.
Netherlands
Amsterdam Schiphol's position as Europe's third-largest passenger gateway concentrates sustainable aviation fuel demand from KLM and transiting carriers. The EU Green Deal channels public financing toward Rotterdam port biorefinery expansions. The Randstad conurbation integrates Neste Oyj's production facility with pipeline delivery networks serving Northwest European airports.
United Kingdom
International Airlines Group's decade-long offtake contracting bypasses traditional fuel suppliers for SAF volumes at Heathrow and Gatwick. The country's post-Brexit regulatory alignment with ASTM certification maintains fleet interoperability. London's airport system combines hub concentration with business aviation demand at Biggin Hill and Farnborough.
France
Air France-KLM's dual-hub strategy splits procurement between Paris Charles de Gaulle and Amsterdam Schiphol supply pools. The national transposition of ReFuelEU Aviation mandates supports biorefinery investments at La Mède and Grandpuits. The Île-de-France region concentrates fuel logistics infrastructure serving long-haul carrier networks.
Belgium
Antwerp's refining complex sustains conventional Jet A-1 production for North Atlantic route supply chains. The country's central European location positions it as a transit hub for German and French airport deliveries. The Flemish port region hosts additive blending operations supporting fuel quality specifications across multiple carrier fleets.
Europe Aviation Fuel Market Competitive Landscape
Concentration sits with integrated petroleum majors and specialized biorefinery operators rather than fragmented independent traders. The market structure reflects a dual-tier configuration where conventional refining capacity dominates volume throughput while sustainable aviation fuel production commands premium positioning and forward contract structures. Strategic archetypes include legacy petroleum refiners pivoting toward co-processing capabilities, pure-play biorefinery developers securing long-term airline offtake, and integrated energy majors balancing conventional supply security with SAF portfolio expansion. Competitive moves center on biorefinery capacity expansion in the Rotterdam corridor and direct airline contracting that disintermediates traditional fuel resellers.
Among the integrated petroleum majors, Shell plc, BP plc, and TotalEnergies SE exemplify archetypes navigating the transition from conventional refining dominance toward sustainable aviation fuel market positioning. Shell plc occupies a position anchored by Rotterdam biorefinery infrastructure serving Amsterdam Schiphol hub operations. BP plc represents the conventional supply security specialist through Antwerp refining network relationships with transatlantic carriers. TotalEnergies SE sits within the European major tier balancing La Mède biorefinery investments with legacy refining asset optimization.
| Leading Market Players |
|---|
| Repsol SA |
| Exxon Mobil Corporation |
| BP plc |
| Chevron Corporation |
| Gazprom Neft PJSC |
| Shell plc |
| Neste Oyj |
| Kuwait Petroleum Corporation |
| TotalEnergies SE |
| Others |
Supply & Pricing Matrix
Hydroprocessed esters and fatty acids feedstock substitution for conventional crude oil is redrawing supply geography around Rotterdam port infrastructure while compressing refining margins through used cooking oil price volatility against biodiesel competition. ReFuelEU Aviation mandates accelerate this transition by binding blend requirements that force parallel logistics investment at Charles de Gaulle and Frankfurt fuel farms.
Pricing Analysis
Commercial airlines anchor long-term offtake contracting that displaces spot market purchasing for SAF volumes, with pricing stratifying across ASTM D7566-certified premium tiers, conventional Jet A-1 standard supply, and residual fuel economy grades. Price differentiation rests on certification tier and volume scale, with business aviation commanding 40-60 percent premiums through direct FBO terminal arrangements. Cost compression in SAF refining is intensifying because feedstock competition with biodiesel producers squeezes HEFA pathway economics. Regional operators exhibit highest price sensitivity due to allocation constraints, while flag carriers secure decade-long supply agreements that lock in volume priority.
Supply Chain Analysis
Container availability constraints on Atlantic trade lanes complicate used cooking oil and animal fat inbound logistics from North American and Southeast Asian collection networks. Geographic supply concentration centers on the Netherlands, Belgium, and Germany, with Neste Oyj's Rotterdam facility and BP's Antwerp complex anchoring Northwest European output. Raw material dependencies draw from lipid feedstocks, renewable hydrogen, and captured carbon dioxide for synthetic pathways. Single-source vulnerability around Rotterdam biorefinery capacity creates structural risk for Amsterdam and Frankfurt hub security. Distribution runs through pipeline networks from port biorefineries to airport fuel farms, with segregated SAF storage requiring hydrant system retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's aviation fuel market represents a high-growth disruption as ReFuelEU Aviation mandates force simultaneous reconfiguration of procurement contracts, storage infrastructure, and fleet certification pathways across the continent.
For Market Incumbents: Compound biorefinery co-processing capabilities at existing Rotterdam and Antwerp facilities to defend against pure-play SAF developers capturing direct airline offtake. Secure backward integration into used cooking oil and animal fat collection networks to mitigate feedstock cost volatility that threatens HEFA refining margins. Prioritize ASTM D7566 certification maintenance for hydroprocessed esters and fatty acids pathways as alcohol-to-jet competitors await unresolved approval timelines. For New Entrants and Emerging Players: ASTM certification fast-track for lignocellulosic ethanol-to-jet pathways unlocks white-space opportunity in forestry-residue feedstock commercialization before ECHA safety assessment bottlenecks resolve. Target regional French and Swedish airports piloting modular 50,000-tonne HEFA units that bypass hub congestion and global commodity sourcing. Pursue power-to-liquid synthetic fuel demonstrations in Denmark and the Netherlands where EU Green Deal public financing de-risks e-kerosene production scale-up. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biorefinery developers holding decade-long offtake contracts with International Airlines Group and Air France-KLM that insulate revenue visibility. Long-term viability across the analysis window favors synthetic fuel production platforms with renewable hydrogen integration over conventional refining pivots. Monitor ASTM certification timelines for alcohol-to-jet pathways as the inflection signal determining lignocellulosic feedstock commercialization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Capacity Expansion | Neste Oyj's Rotterdam facility scaling secures supply security for Amsterdam Schiphol and Frankfurt hub operations. |
| Long-term Supply Agreement | Decade-long offtake contracts between airlines and biorefinery developers disintermediate traditional fuel supplier intermediaries. |
| Backward Integration | Captive supply of used cooking oil and animal fat collection networks mitigates biodiesel competition margin compression. |
| Green Certification Program | CSRD disclosure requirements push corporate enterprises toward SAF-booking programs for scope 3 emissions reduction. |
| Joint Venture | Power-to-liquid demonstration partnerships in Denmark and the Netherlands leverage public financing for e-kerosene cost parity advancement. |
Research Methodology
Desk research of customs and trade flow databases, ECHA chemical safety assessment filings, and EU Green Deal policy documentation preceded structured interviews with biorefinery operations managers, airline fuel procurement directors, airport infrastructure planners, and EPC contractors specializing in fuel farm retrofits. Primary fieldwork with Rotterdam port logistics coordinators and Antwerp refining complex technical leads validated secondary data on capacity utilization and feedstock sourcing patterns. Bottom-up volume modeling triangulated against top-down regulatory mandate impact assessments.
Variance decomposition across fuel type, end-user segment, distribution channel, and technology maturity dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against ReFuelEU Aviation blending mandate trajectories, with hydroprocessed esters and fatty acids capacity buildout schedules and synthetic fuel demonstration timelines serving as key forecast inputs.
Underlying assumptions cover ASTM D7566 certification continuity for HEFA pathways and ECHA REACH registration progression for novel biogenic feedstocks, with deviation risk concentrated in alcohol-to-jet approval delays and renewable hydrogen cost curves for power-to-liquid economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
China Bunker Fuel Market
Fuels
Fuel Oxygenate Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
India Petrol Station Market
Fuels
Wood Pellet Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
North America Wood Pellet Market
Fuels
Renewable Heating Fuels Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Pyrolysis Gas Market
Fuels
Brazil LNG Market
Fuels
Gas Pooling Mechanism Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Fuel Conditioning System Market
Fuels
Australia Coal Market
Fuels
Methane Market