
 Middle-East and Africa Bunker Fuel Market | 2026-2036
Middle-East and Africa Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Bunker Fuel Market Foresight
Container shipping lines are redrawing procurement priorities across Middle-East and Africa bunkering hubs as vessel operators prioritize low sulfur compliance and supply security. Saudi Aramco leverages its integrated refining network to dominate high-volume marine fuel supply from the Red Sea to the Gulf. ENOC Company anchors its position through dedicated storage and blending infrastructure at Fujairah, the region's largest bunkering port. Shell PLC competes across multiple African coastal markets with specialized low sulfur product lines.
Bunker fuel denotes residual and distillate marine fuels used for propulsion and auxiliary power in commercial vessels, with IFO 380 and low sulfur variants representing the dominant volume grades refined to maximum sulfur content specifications. The fuel serves as the primary energy input for international maritime trade, where vessel operators optimize between energy density, port availability, and regulatory compliance cost. IFO 380 remains the mature volume anchor across bulk carrier and tanker applications, while low sulfur fuel oil captures expanding share as IMO 2020 sulfur regulations enforce cleaner burning standards. Marine gas oil occupies a narrower premium tier serving cruise ships and fishing vessels where operational flexibility justifies higher unit cost.
The International Maritime Organization enforces global sulfur caps that directly determine product specification requirements at Middle-East and Africa supply points. South Africa's National Regulator for Compulsory Specifications and port authorities across the Gulf Cooperation Council states implement local testing and certification regimes that filter market access. Fleet operators and oil traders must monitor evolving carbon intensity regulations and alternative fuel pilot programs that will reshape long-term bunker procurement strategies.
Market Dynamics
IMO sulfur regulations are compressing residual fuel demand while forcing rapid infrastructure conversion across Red Sea and Gulf bunkering hubs. Refiners must rebalance output toward low sulfur fuel oil as vessel operators abandon high sulfur IFO 380.
Growth Catalysts
- Suez Canal Transit Volume:Container traffic through this corridor generates concentrated bunkering demand at Egyptian and Saudi Arabian ports. Vessel operators prioritize refueling stops that minimize deviation from primary routes.
- IMO 2020 Sulfur Cap:The International Maritime Organization's enforcement mechanism mandates maximum sulfur content in marine fuels. Compliance requirements pull fleet operators toward certified low sulfur supply points.
- Fujairah Storage Expansion:Dedicated blending tanks and deepwater berths at this UAE port enable high-throughput marine fuel logistics. Infrastructure scale attracts major trading houses seeking supply security.
Market Restraints
- Crude Price Volatility:Bunker fuel pricing tracks residual fuel oil benchmarks that swing with Brent crude movements. Fleet operators face unhedged exposure during extended voyage contracts.
- Gulf Refinery Concentration:Saudi Aramco and ADNOC control the majority of regional marine fuel output. Buyer negotiating power weakens when alternative suppliers require costly deviation from main shipping lanes.
- Limited African Refining:South Africa's Engen and Sasol refineries serve coastal demand, but West and East Africa depend on imported cargoes. Long supply chains inflate delivered costs and create stockout risk.
Strategic Opportunities
- Mozambique LNG Corridor:Offshore gas development is creating new vessel traffic patterns along the East African coast. Bunkering infrastructure at Maputo and Nacala remains underdeveloped relative to projected demand.
- Methanol Pilot Programs:Maersk and other container lines are testing dual-fuel engines capable of burning methanol. Early adoption creates first-mover positioning for ports offering alternative fuel bunkering.
- Green Hydrogen Incentives:The EU Green Deal's carbon border adjustments and South Africa's hydrogen valley initiative are channeling capital toward synthetic marine fuel production. Regulatory tailwinds favor low-carbon bunkering hubs.
Industry Challenges
- Marine Chemist Certification:Fuel quality testing requires accredited laboratories with gas chromatography and sulfur analysis capability. Gulf ports face shortages of IMO-certified inspectors during peak vessel arrival windows.
- Legacy Tank Conversion:Storage terminals built for high sulfur fuel oil require cleaning, retrofitting, and segregation systems to handle low sulfur grades. Capex requirements strain independent terminal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Bunker Fuel Market |
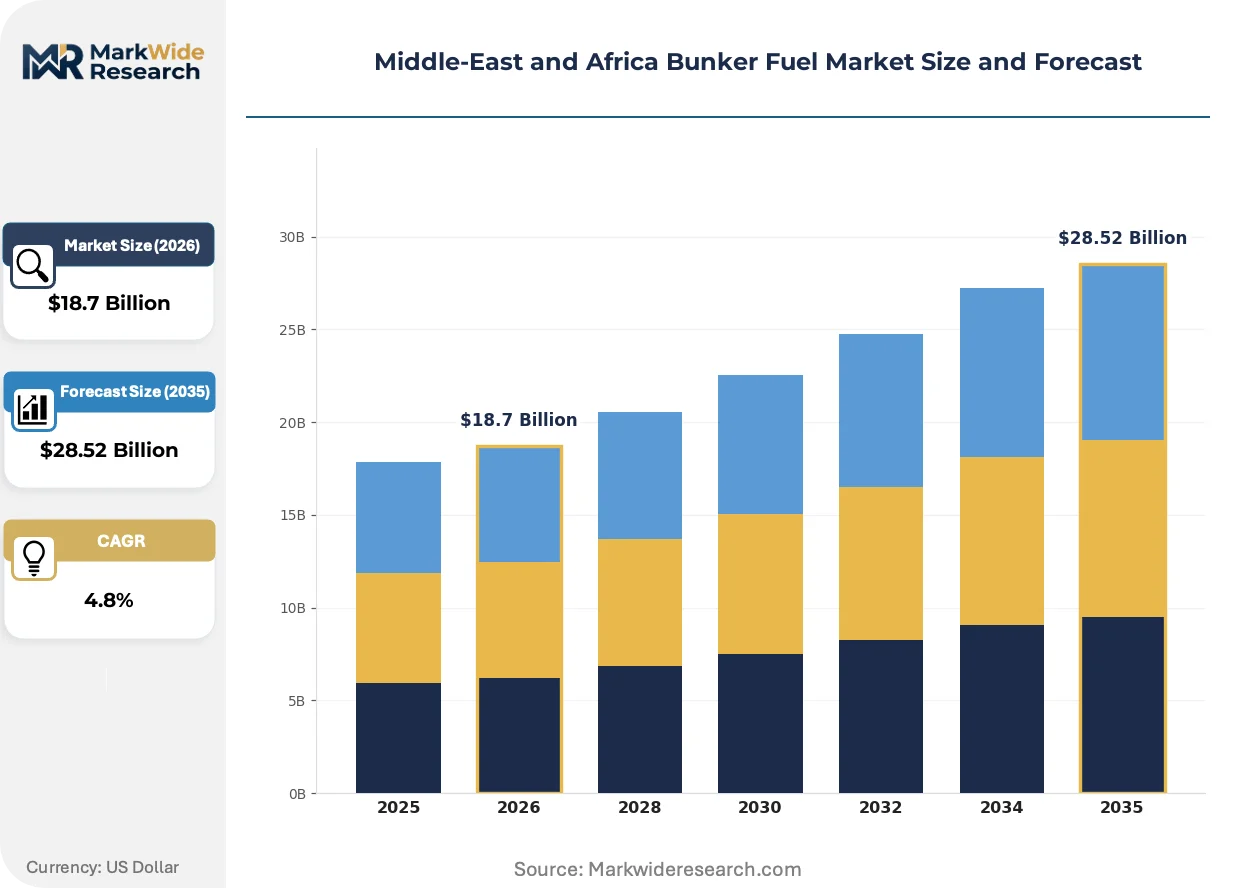
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: IFO 180, IFO 380, Marine Gas Oil, Low Sulfur Fuel Oil Application: Commercial Shipping, Fishing Vessels, Bulk Carriers, Cruise Ships End User: Shipping Companies, Oil Traders, Fleet Operators, Marine Service Providers Distribution Channel: Direct Sales, Broker, Reseller, Online Platforms |
| Companies Covered | Saudi Arabian Oil Company (Saudi Aramco), ENOC Company, QatarEnergy, Kuwait Petroleum Corporation, Abu Dhabi National Oil Company, Exxon Mobil Corporation, Shell PLC, TotalEnergies SE, Chevron Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Bunker Fuel Market Shifts & Advancements
Digital fuel metering and blockchain traceability are disrupting traditional bunkering verification methods. Supply chain transparency is becoming a competitive differentiator as vessel operators face carbon accounting pressure.
Mass flow meters are fragmenting conventional volume-based bunkering transactions. These coriolis-based systems measure fuel mass directly, eliminating temperature and density conversion disputes. Container lines at Singapore and Rotterdam have adopted mass-based contracting, and Middle-East ports are following to reduce quantity claim arbitration. The technology is fragmenting long-established trading conventions based on metric ton equivalents.
The International Maritime Organization's carbon intensity indicator is tightening vessel efficiency requirements annually. Shipowners must document fuel consumption and transport work metrics or face operational penalties. Bulk carrier and tanker fleets calling at Durban and Fujairah are retrofitting engine performance monitoring systems to generate compliant data trails.
Long-term charter contracts are displacing spot bunkering for container shipping alliances. Ocean carriers now negotiate annual supply agreements with fixed pricing bands and dedicated storage allocations. This pattern concentrates procurement volume with integrated refinery-trading houses and squeezes independent bunker suppliers in the Middle-East and Africa region.
Middle-East and Africa Bunker Fuel Market Segmentation
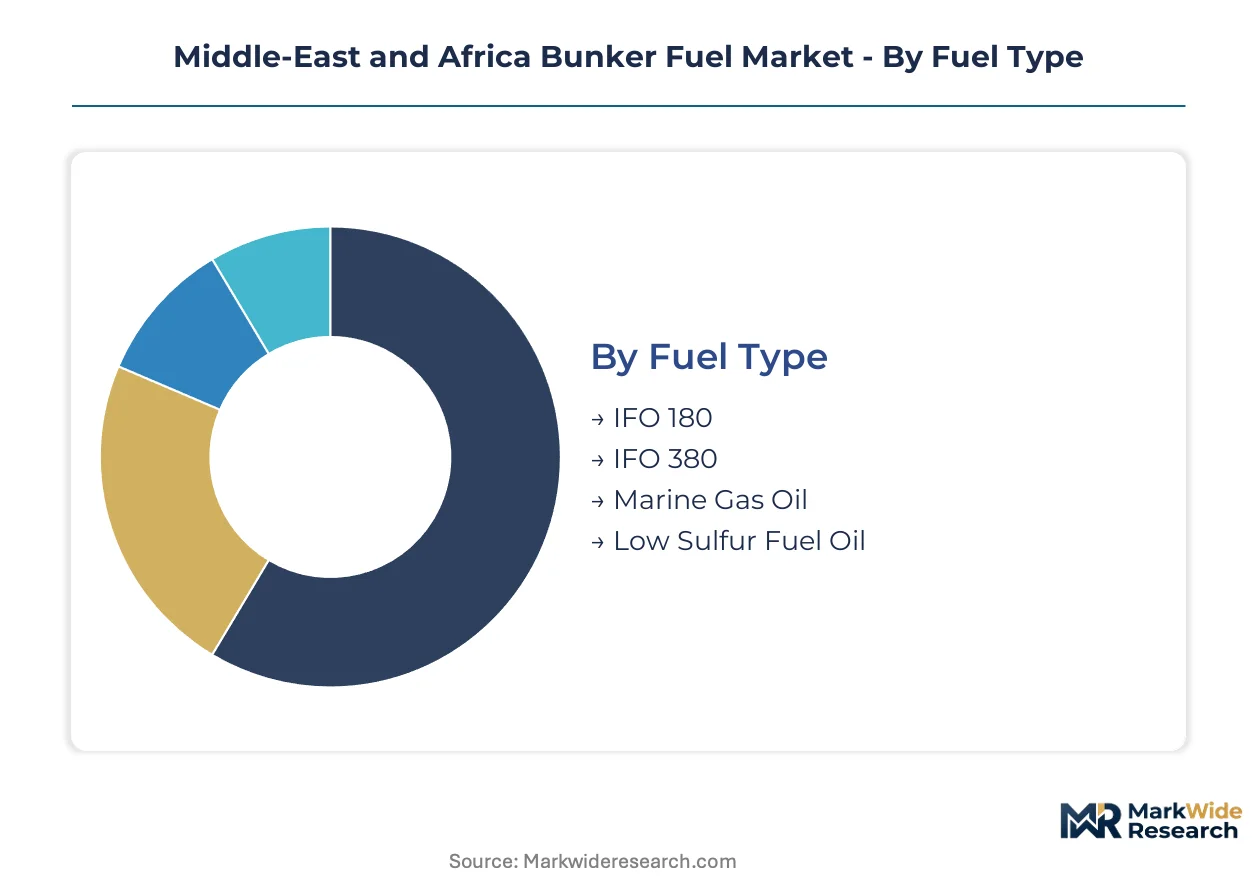
Vessel operators select bunker grades based on sulfur compliance mandates, engine compatibility, and voyage economics. Procurement patterns across Middle-East and Africa ports reveal sharp divergence between legacy residual demand and low sulfur transition. Segmentation clarity enables suppliers to align storage infrastructure with regulatory trajectory.
Fuel Type:
IMO sulfur caps have restructured refinery output specifications across Fujairah and Durban supply points. The International Maritime Organization's enforcement mechanism now determines which grades command terminal allocation priority.
- IFO 380:High-viscosity residual fuel oil with maximum sulfur content historically at 3.5% serves deep-draft bulk carriers and tankers with compatible engine systems. Demand concentrates at Egyptian Red Sea ports serving Suez Canal transits where older fleets minimize fuel switching costs.
- Low Sulfur Fuel Oil:Blended distillate-residual hybrid meeting 0.5% sulfur specification under IMO 2020 mandates captures expanding procurement share at UAE and Saudi Arabian bunkering hubs. Container shipping alliances prioritize certified low sulfur supply points to avoid non-compliance penalties.
- IFO 180:Lower-viscosity residual grade suited to medium-speed marine engines in regional coastal trade.
- Marine Gas Oil:Distillate fuel with sub-0.1% sulfur content serves cruise ships and fishing vessels where operational flexibility justifies premium pricing.
Established volume favors IFO 380; emerging adoption favors Low Sulfur Fuel Oil.
Application:
Vessel category determines fuel grade selection, storage duration, and bunkering frequency at Middle-East and Africa ports.
- Commercial Shipping:Container lines and general cargo operators dominate procurement volume at Fujairah and Port of Durban. IMO carbon intensity indicators force fleet operators toward documented low sulfur consumption trails.
- Bulk Carriers:Iron ore and coal transport fleets favor high-density residual fuels for long-haul efficiency. Capesize vessels calling at Mozambican and South African ports generate concentrated demand during commodity export windows.
- Cruise Ships:Passenger vessels require ultra-low sulfur distillates and cold-ironing shore power compatibility at Dubai and Durban cruise terminals.
- Fishing Vessels:Coastal and deep-water fishing fleets in East African and Gulf waters consume marine gas oil for engine reliability in variable load conditions.
Procurement scale concentrates in commercial shipping; regulatory pressure accelerates most quickly in cruise operations.
End User:
Buyer type shapes contracting structure, credit terms, and storage allocation priority at regional bunkering hubs.
- Shipping Companies:Ocean carriers with owned or chartered fleets negotiate annual supply agreements with fixed pricing bands. Maersk and Mediterranean Shipping Company procurement teams dominate volume allocation at Fujairah blending terminals.
- Oil Traders:Independent trading houses arbitrage price differentials between Singapore and Middle-East benchmarks. Vitol and Trafigura maintain floating storage positions off UAE and Oman coastlines.
- Fleet Operators:Third-party vessel managers coordinate multi-owner bunkering schedules across African coastal markets with limited supply competition.
- Marine Service Providers:Port agents and technical managers arrange spot deliveries for tramp shipping and specialized cargo vessels.
Contract security favors shipping companies; spot flexibility favors marine service providers.
Distribution Channel:
Channel selection reflects buyer sophistication, volume scale, and supply chain risk tolerance across Middle-East and Africa markets.
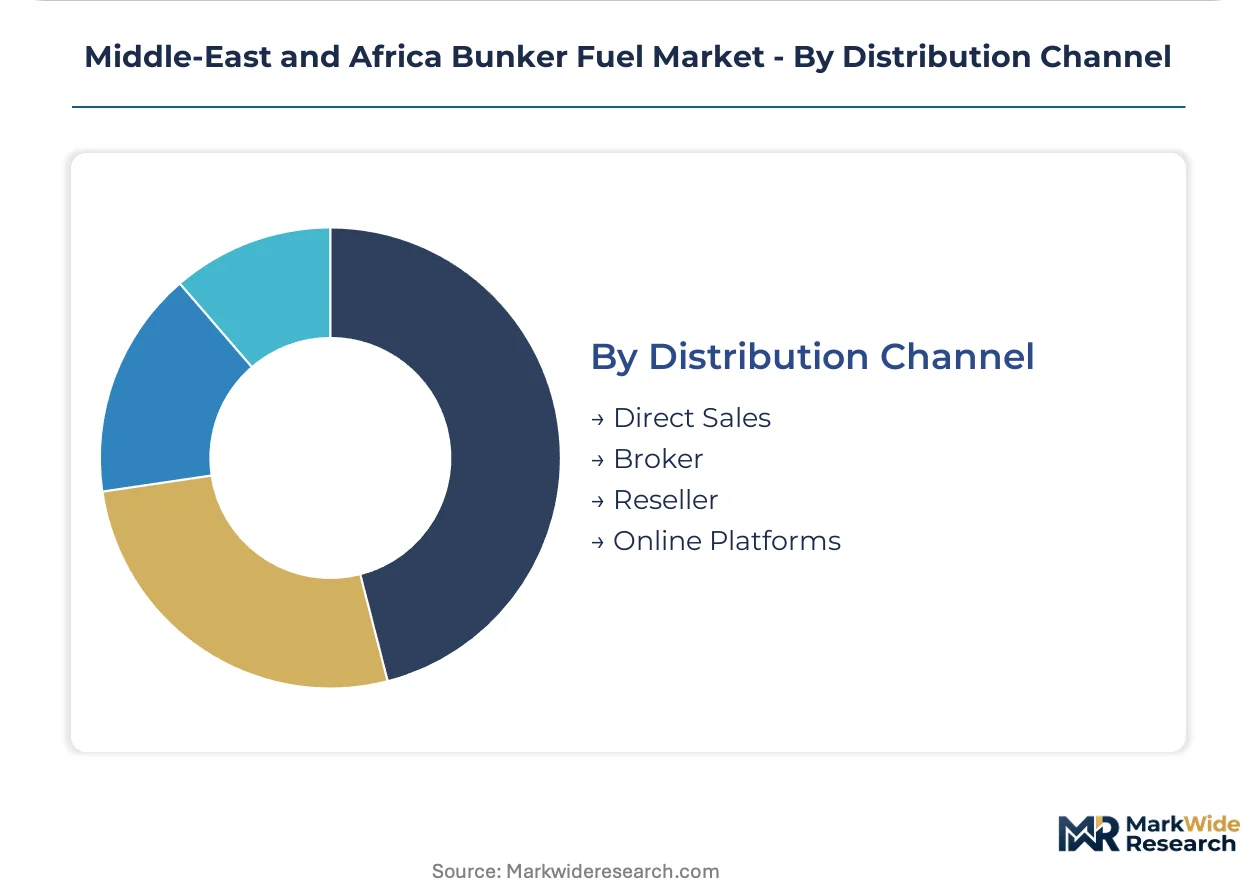
- Direct Sales:Integrated refinery-trading houses supply major container lines through dedicated storage allocations. Saudi Aramco and ENOC Company bypass intermediaries for high-volume accounts.
- Broker:Independent intermediaries match tramp shipping demand with available cargo across fragmented African port networks. Broker networks dominate West and East African markets lacking refinery infrastructure.
- Reseller:Regional distributors purchase bulk cargoes for fractional sale to fishing fleets and coastal traders. Reseller margins compress when crude volatility exceeds hedging coverage.
- Online Platforms:Digital procurement portals enable price discovery and delivery scheduling for mid-size fleet operators. Platform adoption remains nascent outside UAE and South African markets.
Relationship depth favors direct sales; market access favors broker networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal transit corridor underwrites Egypt's centrality to Middle-East bunkering logistics, with vessel traffic generating concentrated demand at Port Said and Alexandria terminals. Saudi Arabia's Red Sea ports anchor high-volume marine fuel supply chains stretching from Jeddah to Yanbu. South Africa's Port of Durban functions as the primary bunkering hub for vessels rounding the Cape of Good Hope.
United Arab Emirates
Fujairah's deepwater berths and dedicated blending infrastructure attract major trading houses seeking supply security for container shipping alliances. MOHAP implements local testing and certification regimes that filter market access for marine fuel suppliers. The port's storage expansion enables high-throughput logistics for low sulfur fuel oil distribution across the Gulf.
Saudi Arabia
Saudi Aramco leverages its integrated refining network to dominate high-volume marine fuel supply from Jeddah Islamic Port to Yanbu Commercial Port. The kingdom's National Center for Environmental Compliance enforces sulfur content specifications aligned with IMO mandates. Ras Tanura's terminal complex anchors residual fuel output for Suez Canal transit vessels.
South Africa
The Port of Durban generates concentrated bunkering demand from bulk carriers and tankers calling during commodity export windows. The National Regulator for Compulsory Specifications implements fuel quality testing requirements for marine chemist certification. Engen and Sasol refineries serve coastal demand while West Africa depends on imported cargoes.
Egypt
Container traffic through the Suez Canal generates refueling stops at Port Said East and Alexandria where vessel operators minimize deviation from primary routes. The Egyptian General Petroleum Corporation coordinates marine fuel allocation across Mediterranean and Red Sea terminals. Damietta's liquefied natural gas infrastructure is creating alternative fuel pilot opportunities.
Qatar
QatarEnergy's integrated production and export facilities position Ras Laffan as an emerging bunkering location for LNG carrier traffic and associated vessel support. The Ministry of Environment and Climate Change monitors carbon intensity indicators for vessels calling at Qatari ports. Mesaieed Industrial City's storage capacity supports regional marine fuel arbitrage between Singapore and Middle-East benchmarks.
Middle-East and Africa Bunker Fuel Market Competitive Landscape
Listed leaders compete with private specialists across storage infrastructure and blending capability in the Middle-East and Africa bunker fuel market. State-controlled national oil companies dominate refinery output and terminal allocation, while international majors compete through specialized low sulfur product lines and trading expertise. Three archetypes define competitive positioning: integrated refinery-trading houses with captive crude supply, international oil companies with global marine fuel portfolios, and independent terminal operators seeking storage arbitrage. Capacity expansion at Fujairah and strategic partnerships for methanol bunkering infrastructure represent dominant competitive moves.
Within the integrated refinery-trading tier, Saudi Arabian Oil Company and Abu Dhabi National Oil Company exemplify state-controlled players leveraging upstream crude access to dominate marine fuel output across Red Sea and Gulf supply points. ENOC Company occupies a position among UAE-based operators with dedicated Fujairah infrastructure. Shell PLC sits within the international major archetype, competing across African coastal markets where independent suppliers face stockout risk from long supply chains.
| Leading Market Players |
|---|
| Saudi Arabian Oil Company (Saudi Aramco) |
| ENOC Company |
| QatarEnergy |
| Kuwait Petroleum Corporation |
| Abu Dhabi National Oil Company |
| Exxon Mobil Corporation |
| Shell PLC |
| TotalEnergies SE |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
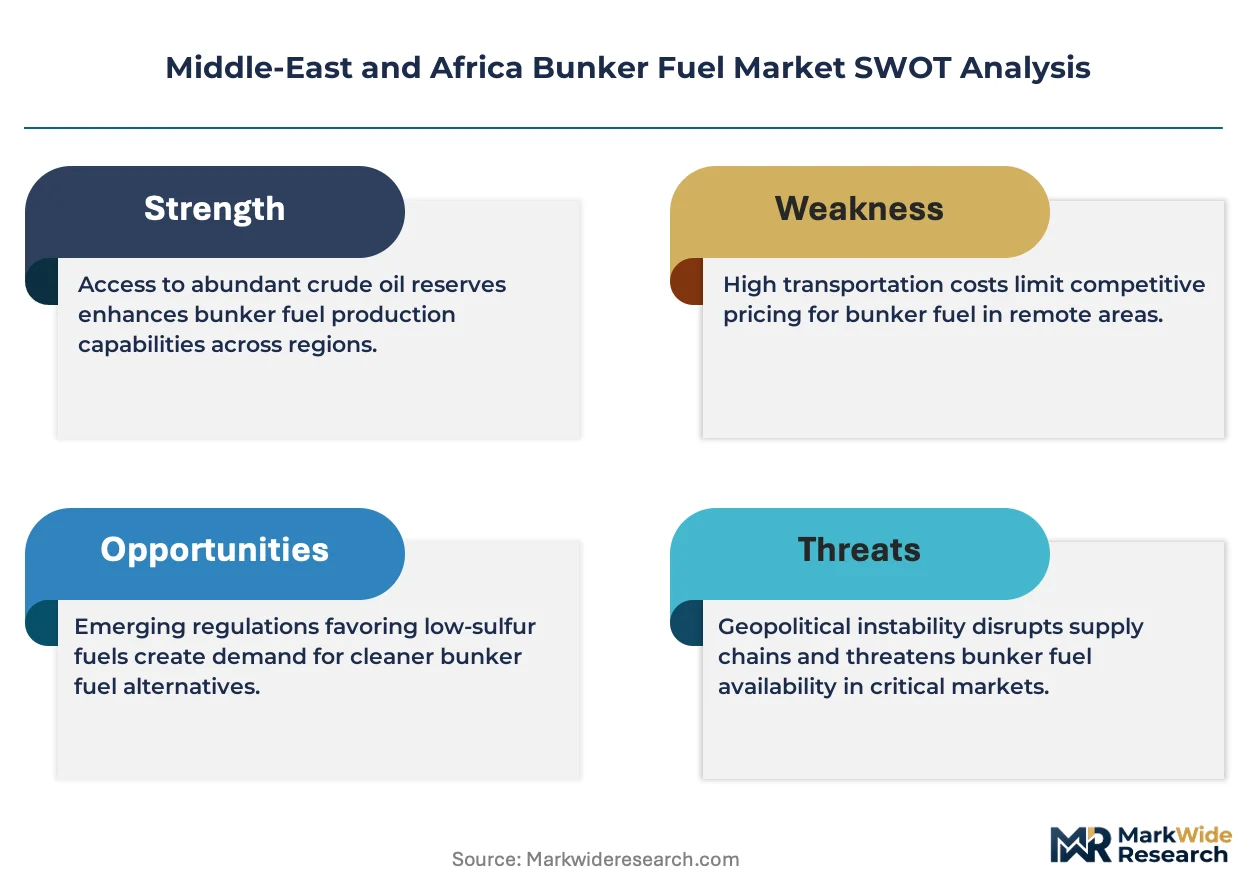
Low sulfur fuel oil substitution for high sulfur IFO 380 is compressing refinery margins while redrawing supply geography across Red Sea and Gulf bunkering hubs. This grade transition concentrates pricing power with integrated refiners in Saudi Arabia and the UAE who control blending infrastructure, while forcing independent terminal operators to absorb tank conversion costs.
Pricing Analysis
Volume-discount tiering structures separate annual contract holders from spot purchasers at Fujairah and Jeddah terminals. Container shipping alliances with fixed offtake agreements secure preferential rates through dedicated storage allocations, while tramp operators face spot price exposure amplified by crude volatility. Price differentiation hinges on IMO certification status and sulfur testing documentation, with certified low sulfur cargoes commanding premiums. Cost compression in the spot tier is intensifying as Brent-linked benchmarks transmit crude swings directly to unhedged buyers. Fleet operators with annual contracts demonstrate lowest price sensitivity; independent fishing vessels and coastal traders exhibit highest sensitivity.
Supply Chain Analysis
Saudi Arabia and the United Arab Emirates anchor regional marine fuel production through integrated refining complexes at Ras Tanura and Ruwais. The supply chain draws from heavy crude feedstocks and vacuum gasoil intermediates, with blending components sourced from FCC units and hydrocracker outputs. Single-source vulnerability concentrates in Fujairah storage terminals where three operators control over sixty percent of deepwater berth capacity. Distribution runs through refinery-direct sales to major container lines, broker-mediated spot transactions across African coasts, and reseller networks serving fragmented coastal demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IMO 2020 compliance deadlines pull fleet operators toward certified low sulfur supply points, with methanol pilot programs and carbon intensity regulations extending the technology transition runway.
For Market Incumbents: Fortify blending infrastructure at Suez Canal corridor ports before competitor terminal expansions capture transit vessel volume. Saudi Aramco and ADNOC should accelerate low sulfur tank conversion at legacy high sulfur facilities to preempt supply security concerns from container alliances. Certification investment in IMO-compliant marine chemist laboratories represents a critical defensive lever against quality dispute arbitrage.
For New Entrants and Emerging Players: IMO certification fast-tracks through partnership with established testing houses in South Africa and Egypt lower barriers for regional resellers seeking refinery-direct supply relationships. White-space targets concentrate in Mozambique LNG corridor bunkering at Maputo and Nacala, plus methanol bunkering infrastructure at Damietta and Durban. The most penetrable segment is mid-size fleet operators in East African coastal trade currently served by high-cost broker networks.
For Investors and Strategic Acquirers: The market sits at a substitution-driven phase that favors integrated refinery-trading houses with captive crude supply and blending capability. Long-term viability over the next decade hinges on positioning for synthetic marine fuel production as EU carbon border adjustments reshape bunker procurement. Acquisition target archetypes include independent terminal operators with Fujairah or Durban storage positions and methanol infrastructure development rights. The signal to watch is container line methanol dual-fuel engine orders as commitment indicators for alternative fuel bunkering demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Low Sulfur Tank Conversion | Legacy terminal retrofitting enables IMO 2020 compliance at Fujairah and Jeddah storage facilities. |
| Methanol Bunkering Infrastructure | Dual-fuel vessel support positions Damietta and Durban for container line pilot programs. |
| Marine Chemist Certification Investment | Accredited laboratory capacity at Suez Canal ports reduces quality dispute arbitration exposure. |
| Annual Supply Agreement Expansion | Fixed pricing bands with container alliances secure volume allocation against spot market volatility. |
| Mozambique Corridor Storage Buildout | Deepwater berth development at Nacala captures LNG project vessel traffic along East African coast. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, container line procurement directors, marine fuel traders, port authority technical officers, and IMO certification inspectors and refined through secondary validation. Primary fieldwork encompassed stakeholder interviews across Saudi Arabia, UAE, Egypt, and South Africa. Secondary sources included customs and trade flow databases, SEC filings from listed energy majors, IMO sulfur regulation enforcement reports, and port authority throughput statistics. Bottom-up volume estimates from terminal-level storage and throughput data were triangulated against top-down refinery output allocations.
Variance-decomposition framing separated volume growth drivers from price trajectory components across the projection horizon. The analytical framework modeled segmentation dimensions spanning fuel grade tier, vessel application category, buyer type, and distribution channel structure. CAGRs were derived from regression-based trending of historical throughput data against forward vessel traffic projections. Industry-specific forecast inputs incorporated Suez Canal transit volume forecasts and LNG carrier fleet expansion schedules for Mozambique corridor demand.
Underlying assumptions cover IMO regulatory enforcement continuity, refinery capacity utilization rates, and crude price band stability, with deviation risk concentrated in carbon intensity regulation acceleration and alternative fuel technology adoption curves. Recalibration cycles align with material shifts in container line fleet renewal schedules and bunker fuel specification amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America Aviation Fuel Market
Fuels
Solid Recovered Fuel Market
Fuels
Canada Coal Market
Fuels
Coal Briquette Box Market
Fuels
Global Gas Treatment Market
Fuels
United States Bunker Fuel Market
Fuels
Underground Coal Gasification Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Liquid Propellants Market
Fuels
Gas Hydrates Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Oil Dispenser Market
Fuels
Biobutanol Market
Fuels
Europe Aviation Fuel Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Europe Renewable Aviation Fuel Market