
 Global Charcoal Market | 2026-2036
Global Charcoal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Charcoal Market Analysis
Foodservice grilling is pivoting toward premium hardwood grades as restaurants seek consistent heat profiles and clean-burning fuel. Kingsford Products Company leverages its supermarket shelf presence to dominate North American retail channels. Royal Oak Enterprises specializes in lump hardwood production, sustaining brand loyalty among barbecue enthusiasts. Vina Charcoal anchors Southeast Asian supply chains through integrated eucalyptus plantations.
Charcoal comprises carbonized biomass produced by pyrolysis of wood, coconut shell, or bamboo at temperatures between 400°C and 700°C in oxygen-limited environments, yielding a porous, high-carbon material with calorific values typically exceeding 29 MJ per kilogram. Its primary commercial purpose spans metallurgical reduction, water and air filtration, outdoor cooking, and agricultural soil amendment. Hardwood charcoal leads product type segments due to established foundry demand and premium grilling markets, while activated charcoal commands the highest margin pools in healthcare and filtration applications. Briquette form dominates volume flows through supermarkets and direct industrial contracts, though granular activated carbon displaces powder in municipal water treatment upgrades.
The US EPA enforces emissions standards for charcoal manufacturing facilities under the Clean Air Act, while the EU Deforestation Regulation mandates geolocation traceability for wood-based charcoal entering European markets. Brazil's environmental licensing framework through IBAMA restricts native forest clearing for charcoal feedstock, redirecting supply toward planted eucalyptus and acacia. Stakeholders must monitor regulatory divergence between carbon-accounting jurisdictions to align certification investments with destination-market compliance thresholds.
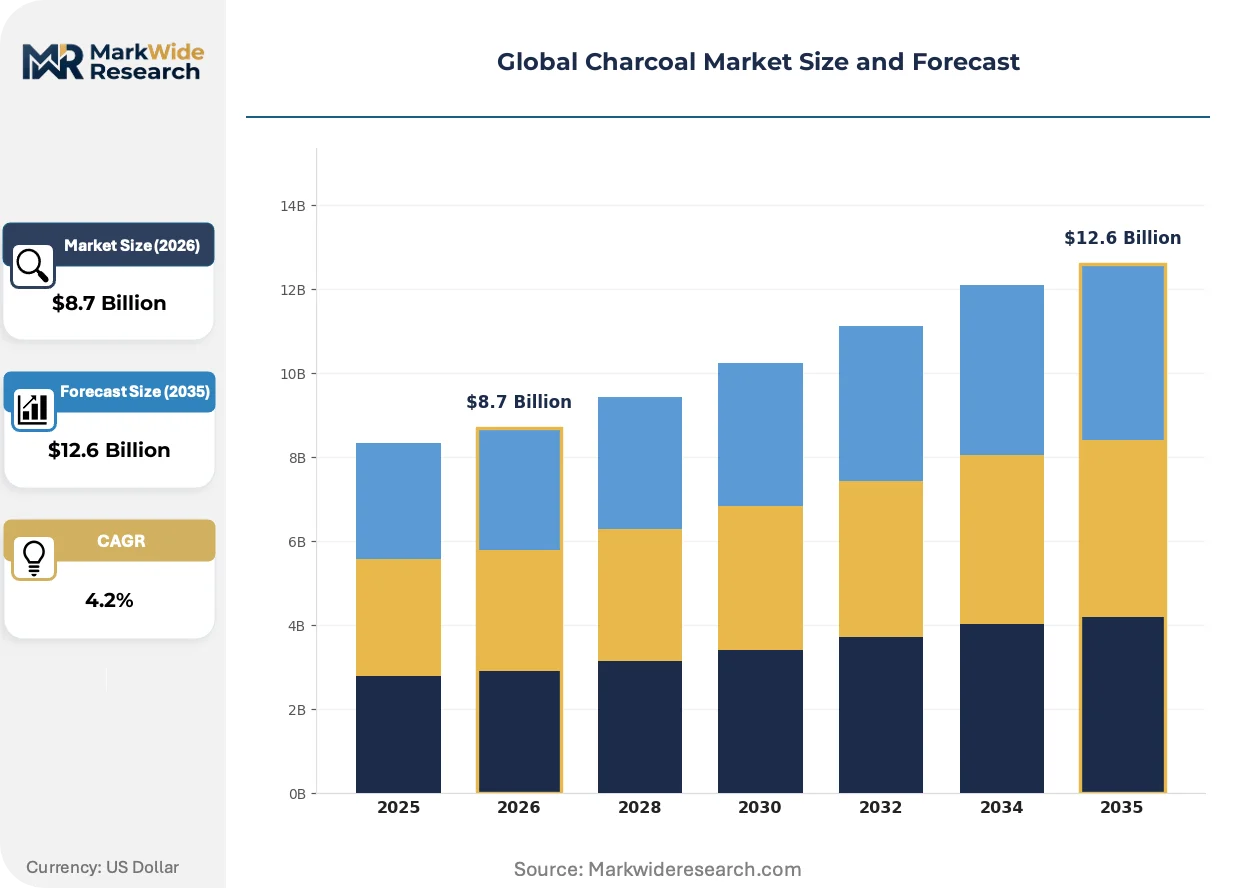
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing charcoal importers to rebuild supply chains around geolocation-verified feedstock, compressing margins for non-compliant producers while rewarding certified plantation-based suppliers.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation traceability for wood-based charcoal entering European markets is accelerating certification infrastructure investments across supplier countries.
- Brazilian steel sector:Integrated charcoal-to-steel operations anchor industrial offtake volumes, sustaining demand for metallurgical-grade hardwood charcoal.
- Pyrolysis optimization:Advanced kiln controls raising fixed-carbon yields above 75% are improving foundry efficiency and reducing per-ton consumption rates.
Market Restraints
- Native forest feedstock restrictions:Brazil's IBAMA environmental licensing framework blocks clearing of native forests for charcoal production, constraining supply expansion.
- LPG substitution:Liquefied petroleum gas is displacing charcoal in urban Brazilian households as pipeline distribution networks expand into peri-urban zones.
- Input cost volatility:Eucalyptus plantation management costs fluctuate with fertilizer and fuel prices, squeezing producer margins during commodity spikes.
Strategic Opportunities
- Activated carbon filtration:Municipal water treatment upgrades in Southeast Asia are opening demand for granular activated carbon with superior adsorption capacity.
- Agricultural biochar:Soil amendment applications in degraded croplands across Sub-Saharan Africa represent underpenetrated demand for pyrogenic carbon.
- Clean Air Act compliance services:US EPA emissions standards for charcoal manufacturing facilities are creating advisory and technology retrofit revenue streams.
Industry Challenges
- Carbonization kiln engineering expertise:Scarce technical talent for designing oxygen-limited pyrolysis systems limits capacity expansion in emerging supply regions.
- Certification timeline compression:EU Deforestation Regulation geolocation documentation requirements demand faster audit cycles than traditional forest certification schemes allow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Charcoal Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Charcoal, Bamboo Charcoal, Hardwood Charcoal, Bricket Charcoal End User: Retail, Industrial, Foodservice, Healthcare Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Form: Powder, Granular, Pellets, Briquettes |
| Companies Covered | Plantar, Fogo Charcoal, Kingsford Products Company, Vina Charcoal, Linyi Guotai Charcoal, Royal Oak Enterprises, Haycarb PLC, Profagus, Duraflame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Charcoal Market Emerging Trajectories
Carbonization technology and regulatory compliance frameworks are actively reshaping competitive positioning in charcoal production, with digital traceability and process automation emerging as decisive capability differentiators.
Continuous carbonization kilns with automated temperature control are overtaking traditional batch beehive ovens in industrial-scale operations. Brazilian steel-integrated producers are adopting these systems to meet IBAMA emissions thresholds while maintaining metallurgical-grade output. The technology is compressing labor requirements and standardizing fixed-carbon consistency across production runs.
REACH chemical safety protocols in Europe are tightening impurity thresholds for charcoal used in food-contact and filtration applications. Manufacturers must now document polycyclic aromatic hydrocarbon levels below 0.5 mg/kg to access premium healthcare and water treatment segments. German and French importers are demanding third-party laboratory certification as a standard procurement condition.
Direct-to-restaurant distribution is bypassing traditional wholesale layers in North American barbecue markets. Pitmasters and foodservice operators are sourcing container-load quantities directly from Indonesian and Vietnamese coconut shell charcoal producers. This channel compression is most visible in Texas and California metro clusters where specialized importers maintain bonded warehouse inventory for rapid replenishment cycles.
Global Charcoal Market Segmentation
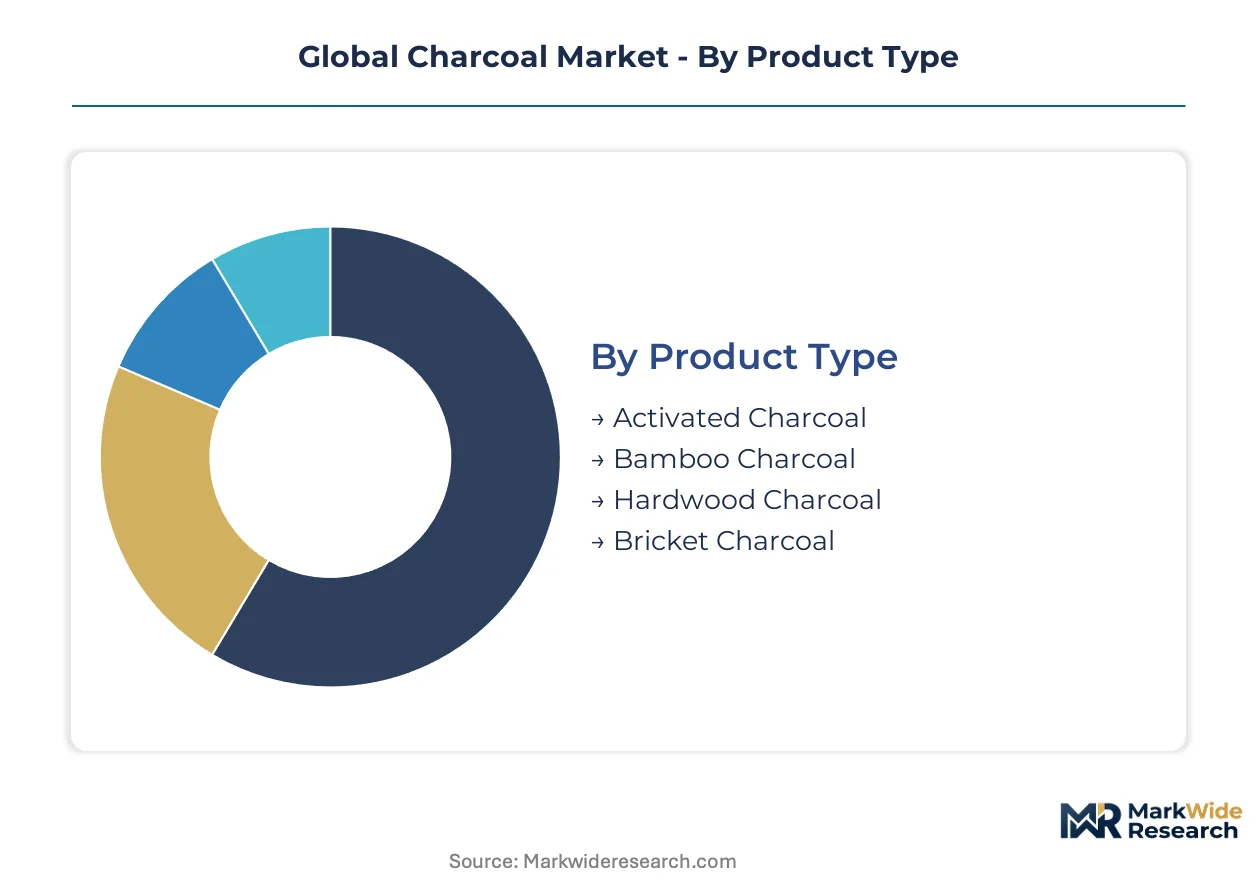
Charcoal market segmentation reveals divergent compliance burdens across product grades, with activated carbon facing REACH chemical safety protocols while metallurgical grades navigate IBAMA environmental licensing. Distribution channel selection directly determines which certification investments producers must prioritize.
Product Type:
REACH documentation requirements in Europe and IBAMA licensing in Brazil impose distinct compliance costs across product categories, fragmenting competitive economics by grade.
- Hardwood Charcoal:Carbonized dense timber species yielding fixed-carbon content above 75% and calorific values exceeding 29 MJ/kg. Brazilian steel-integrated operations anchor metallurgical offtake, though IBAMA restrictions on native forest feedstock redirect supply toward planted eucalyptus and acacia plantations.
- Activated Charcoal:Thermally or chemically activated material with surface areas exceeding 500 m²/g, produced from coconut shell or wood precursors. REACH polycyclic aromatic hydrocarbon thresholds below 0.5 mg/kg govern European healthcare and filtration procurement, with German and French importers demanding third-party laboratory certification.
- Bamboo Charcoal:Pyrolyzed bamboo culm with microporous structure suited for air purification and humidity control applications. Southeast Asian producers in Vietnam and Indonesia supply container loads to North American wellness and home goods retailers.
- Bricket Charcoal:Compressed charcoal fines bound with starch or clay binders, standardized for consistent burn duration. Supermarket retail channels in the United States and Canada favor this form for backyard barbecue convenience.
Leading the category by volume: Hardwood Charcoal. Growing fastest: Activated Charcoal.
End User:
Customer type determines specification stringency, with healthcare and foodservice segments imposing purity standards that commodity industrial buyers rarely require.
- Industrial:Metallurgical reduction in Brazilian steel mills consumes metallurgical-grade hardwood with strict fixed-carbon and ash content specifications. Pyrolysis optimization technologies raising yields above 75% reduce per-ton consumption rates.
- Foodservice:Restaurants and pitmasters demand consistent heat profiles and clean-burning fuel, driving direct procurement from Indonesian and Vietnamese coconut shell producers in Texas and California metro clusters.
- Retail:North American households purchase briquette and lump forms through supermarket and home improvement channels for outdoor cooking applications.
- Healthcare:Activated carbon for medical detoxification and pharmaceutical processing requires documented purity credentials under FDA and EMA frameworks.
Dominating current offtake: Industrial. Expanding most quickly: Foodservice.
Distribution Channel:
Channel selection dictates margin capture and traceability investment, with direct sales bypassing wholesale markups while imposing documentation burdens on producers.
- Direct Sales:Container-load procurement by Brazilian steel mills and North American foodservice operators eliminates intermediary margins. EU Deforestation Regulation geolocation traceability requirements compress timelines for documentation delivery.
- Supermarkets:Kingsford Products Company dominates North American retail shelf presence with briquette and instant-light formulations for household barbecue markets.
- Specialty Stores:Barbecue enthusiasts source lump hardwood through independent retailers and grilling supply boutiques, sustaining Royal Oak Enterprises' brand loyalty.
- Online:E-commerce platforms enable Southeast Asian producers to reach small-scale industrial buyers and agricultural biochar customers in Sub-Saharan Africa.
Capturing highest volume: Supermarkets. Gaining share fastest: Direct Sales.
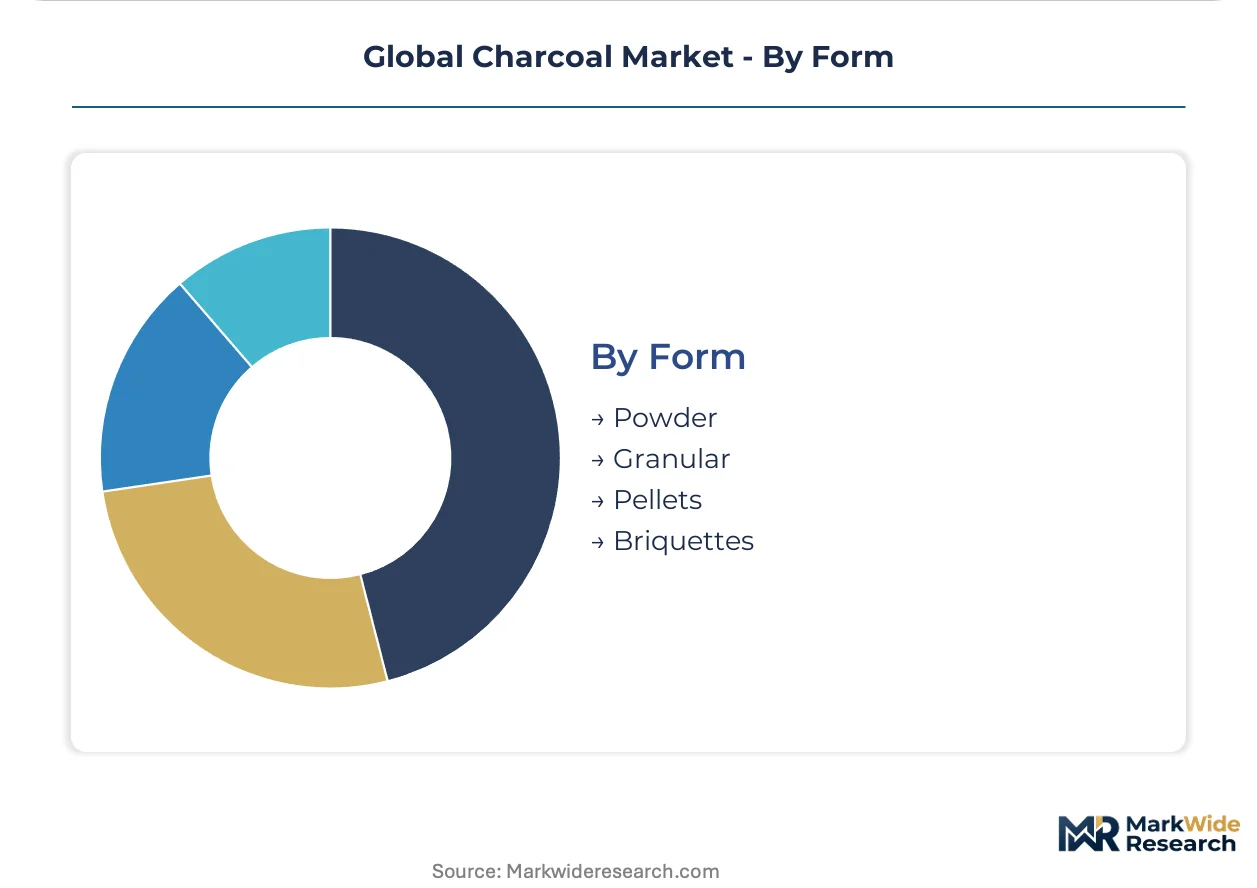
Form:
Physical configuration determines application suitability and handling economics, with granular forms commanding filtration premiums while briquettes optimize combustion predictability.
- Briquettes:Compressed uniform shapes with controlled density and burn duration, preferred by retail consumers and institutional foodservice for predictable heat output. Standardized dimensions enable automated grilling equipment compatibility.
- Granular:Irregular particles sized for packed-bed filtration systems, dominating municipal water treatment upgrades in Southeast Asia with superior adsorption kinetics and pressure-drop characteristics.
- Powder:Fine particulate for pharmaceutical and chemical processing applications, though granular forms increasingly displace powder in municipal water treatment due to handling advantages.
- Pellets:Densified cylindrical form for automated feeding systems in industrial carbonization and specialized combustion applications.
Highest current throughput: Briquettes. Steepest expansion trajectory: Granular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Brazil and Southeast Asia, while consumption splits between North American grilling markets and European industrial filtration. This geographic divide shapes compliance investments and logistics costs.
Brazil
Metallurgical-grade hardwood charcoal supplies integrated steel mills in Minas Gerais. IBAMA environmental licensing restricts native forest clearing, redirecting feedstock toward planted eucalyptus and acacia. The Cerrado and Atlantic Forest regions host plantation-based carbonization operations serving domestic foundry demand.
United States
Backyard barbecue culture sustains retail briquette consumption through supermarket channels. EPA Clean Air Act emissions standards govern domestic manufacturing facilities. Texas and California metro clusters drive direct-to-restaurant procurement from Southeast Asian coconut shell producers.
Germany
Healthcare and water filtration sectors import activated carbon under REACH polycyclic aromatic hydrocarbon thresholds below 0.5 mg/kg. ECHA chemical safety protocols tighten impurity documentation. The Rhine-Ruhr industrial corridor processes granular activated carbon for municipal treatment upgrades.
Vietnam
Coconut shell charcoal production serves North American foodservice and wellness retail segments. Geolocation traceability investments accelerate under EU Deforestation Regulation compliance pressure. The Mekong Delta and Central Highlands concentrate pyrolysis operations near feedstock sources.
Indonesia
Hardwood and coconut shell exports supply Japanese industrial carbonization and European activated carbon markets. Domestic environmental ministry regulations govern plantation expansion permits. Java and Sumatra host integrated kiln operations with automated temperature controls.
Global Charcoal Market Vendor Landscape
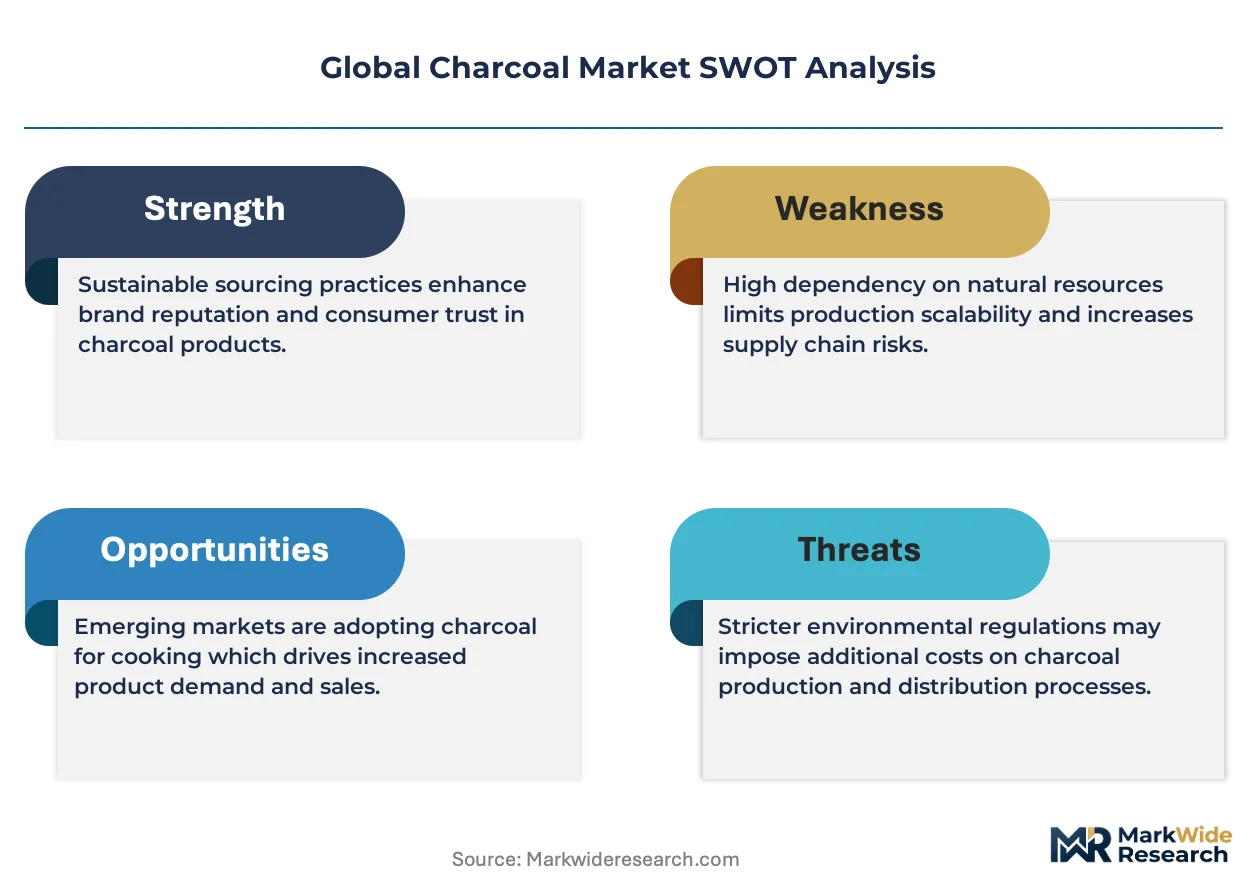
Top-tier vendors anchor metallurgical and activated carbon supply chains, while mid-scale producers compete on plantation traceability and retail shelf presence. The structure splits between steel-integrated Brazilian operations and Southeast Asian export specialists. Three archetypes dominate: plantation-integrated carbonizers, retail brand licensors, and activated carbon purifiers. Capacity expansion and certification infrastructure represent the primary competitive vectors.
Among Brazilian plantation-integrated operators, Plantar exemplifies captive feedstock control through eucalyptus holdings. Kingsford Products Company and Royal Oak Enterprises occupy positions in North American retail channels, with the former representing supermarket distribution scale and the latter exemplifying lump hardwood specialization for barbecue enthusiasts. Vina Charcoal anchors Southeast Asian supply integration through eucalyptus plantation ownership.
| Leading Market Players |
|---|
| Plantar |
| Fogo Charcoal |
| Kingsford Products Company |
| Vina Charcoal |
| Linyi Guotai Charcoal |
| Royal Oak Enterprises |
| Haycarb PLC |
| Profagus |
| Duraflame |
| Others |
Supply Flow & Price Mechanics
EU Deforestation Regulation geolocation traceability mandates are forcing importers to absorb certification infrastructure costs, compressing margins for non-compliant producers while rewarding plantation-verified suppliers with pricing power in European markets. This procurement specification shift is redrawing cost structures across Brazilian and Southeast Asian supply bases.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation in foodservice procurement, with Texas and California pitmasters paying container-load premiums for rapid replenishment cycles from Vietnamese coconut shell producers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified activated carbon from industrial metallurgical grades and uncertified commodity briquettes. Price erosion runs through standard-grade hardwood as eucalyptus plantation management costs fluctuate with fertilizer and fuel inputs. Retail supermarket channels show highest price sensitivity, while healthcare filtration buyers absorb certification premiums without volume elasticity.
Supply Chain Analysis
Certification gating through EU Deforestation Regulation geolocation documentation and REACH polycyclic aromatic hydrocarbon thresholds is filtering supplier eligibility, concentrating viable export capacity among Brazilian plantation-integrated operators and Vietnamese coconut shell specialists. Feedstock draws from planted eucalyptus in Minas Gerais, Mekong Delta coconut husks, and Central Highlands bamboo culm. Single-source vulnerability concentrates in Indonesian hardwood exports facing domestic environmental ministry permit delays. Distribution runs through direct container-load contracts for industrial offtake, bonded warehouse layers for foodservice rapid replenishment, and supermarket retail channels for household briquette consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plantation licensing bottlenecks in Brazil and traceability infrastructure gaps in Southeast Asia are constraining certified supply expansion, propping pricing power for compliant producers across metallurgical and activated carbon tiers.
For Market Incumbents: Lock in captive eucalyptus feedstock through long-term plantation leases before IBAMA licensing windows narrow further. Defend metallurgical-grade margins by accelerating continuous kiln automation to meet emissions thresholds without yield sacrifice. Channel control through direct-to-restaurant distribution partnerships in Texas and California metro clusters insulates against wholesale margin compression. For New Entrants and Emerging Players: E-commerce platform routes into Sub-Saharan African agricultural biochar markets bypass established wholesale layers and certification-heavy European channels. Agricultural soil amendment applications in degraded croplands represent the most penetrable white-space segment, with minimal incumbent presence and lower specification stringency than healthcare or metallurgical tiers. Direct online procurement relationships with small-scale farming cooperatives enable rapid scaling without traceability infrastructure investments. For Investors and Strategic Acquirers: The window for entry favors plantation-integrated carbonizers with existing IBAMA licensing and EU Deforestation Regulation audit completion. Long-term viability across the analysis window rests on backward integration into feedstock control rather than merchant carbonization capacity. Watch for EU Deforestation Regulation enforcement acceleration as the inflection signal tightening compliant supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Eucalyptus Plantations | Captive feedstock secures IBAMA licensing continuity and EU Deforestation Regulation compliance. |
| Continuous Kiln Automation Deployment | Automated temperature control raises fixed-carbon yields above 75% while meeting EPA emissions standards. |
| REACH Certification Investment | Third-party laboratory documentation below 0.5 mg/kg polycyclic aromatic hydrocarbon thresholds unlocks German and French healthcare procurement. |
| Direct-to-Restaurant Distribution Buildout | Bypassing wholesale layers in Texas and California captures pitmaster loyalty and margin compression recovery. |
| Geolocation Traceability Infrastructure | EU Deforestation Regulation audit completion filters competitor eligibility and concentrates pricing power. |
Methodological Framework
Independent corroboration across carbonization plant managers, Brazilian steel mill procurement leads, Southeast Asian export distributors, and healthcare filtration specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from customs and trade data, IBAMA licensing records, ECHA chemical safety protocols, and SEC filings of publicly listed activated carbon producers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across product grades and end-use segments.
Comparable historical reference periods anchored the projection horizon to observed regulatory implementation timelines and kiln technology adoption curves. Segmentation modeling spanned product type, end-use industry, distribution channel, and physical form dimensions. CAGRs derived from supply-demand balance analysis incorporating pyrolysis yield improvements, plantation expansion rates, and substitution elasticity between charcoal and LPG in Brazilian household markets. Forecast inputs included IBAMA enforcement intensity trajectories and EU Deforestation Regulation audit completion rates.
The model holds under steady regulatory enforcement and plantation licensing continuity; deviation in Brazilian environmental policy stringency or EU traceability timeline acceleration would shift supply availability assumptions. A model refresh is warranted upon material change in EU Deforestation Regulation enforcement thresholds or IBAMA native forest clearing restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Briquette Market
Fuels
Brazil LNG Market
Fuels
Gas Feed System Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Mobile Fuel Delivery Market
Fuels
Global Gas Cylinder Market
Fuels
Compressed Natural Gas Market
Fuels
Industrial Fuel Filter Market
Fuels
Gas Pooling Mechanism Market
Fuels
Japan Bunker Fuel Market
Fuels
North America Bunker Fuel Market
Fuels
China LNG Bunkering Market
Fuels
LPG Tanker Market
Fuels
India Retail Fuel Market
Fuels
India Coal Market
Fuels
Gas to Liquid (GTL) Market