
 LPG Gas Cylinder Market | 2026-2036
LPG Gas Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
LPG Gas Cylinder Market Outlook
Market Context
Buyer concentration among national oil companies and large retail distributors is hardening across developing economies. Worthington Industries leverages its manufacturing scale to supply standardized steel cylinders across North American utility networks. Hexagon Composites anchors the composite segment through proprietary filament-winding technology that reduces weight. Time Technoplast sustains its position in emerging markets via cost-optimized polymer-lined designs.
Technical Definition and Segment Structure
An LPG gas cylinder is a pressure vessel designed to store liquefied petroleum gas—primarily propane and butane mixtures—at pressures up to 25 bar, manufactured through deep drawing, welding, or filament winding depending on material. The device serves as the critical interface between bulk LPG supply and end-use combustion in residential cooking, commercial heating, and automotive propulsion. Steel cylinders dominate installed base volumes due to established recycling infrastructure and lower unit costs, while composite variants represent the fastest-expanding category as weight-sensitive automotive and camping segments prioritize portability. The 15 kg capacity segment captures the largest margin pool in residential markets, whereas 45 kg units anchor commercial and industrial accounts through wholesale channel economics.
Regulatory Frame and Outlook
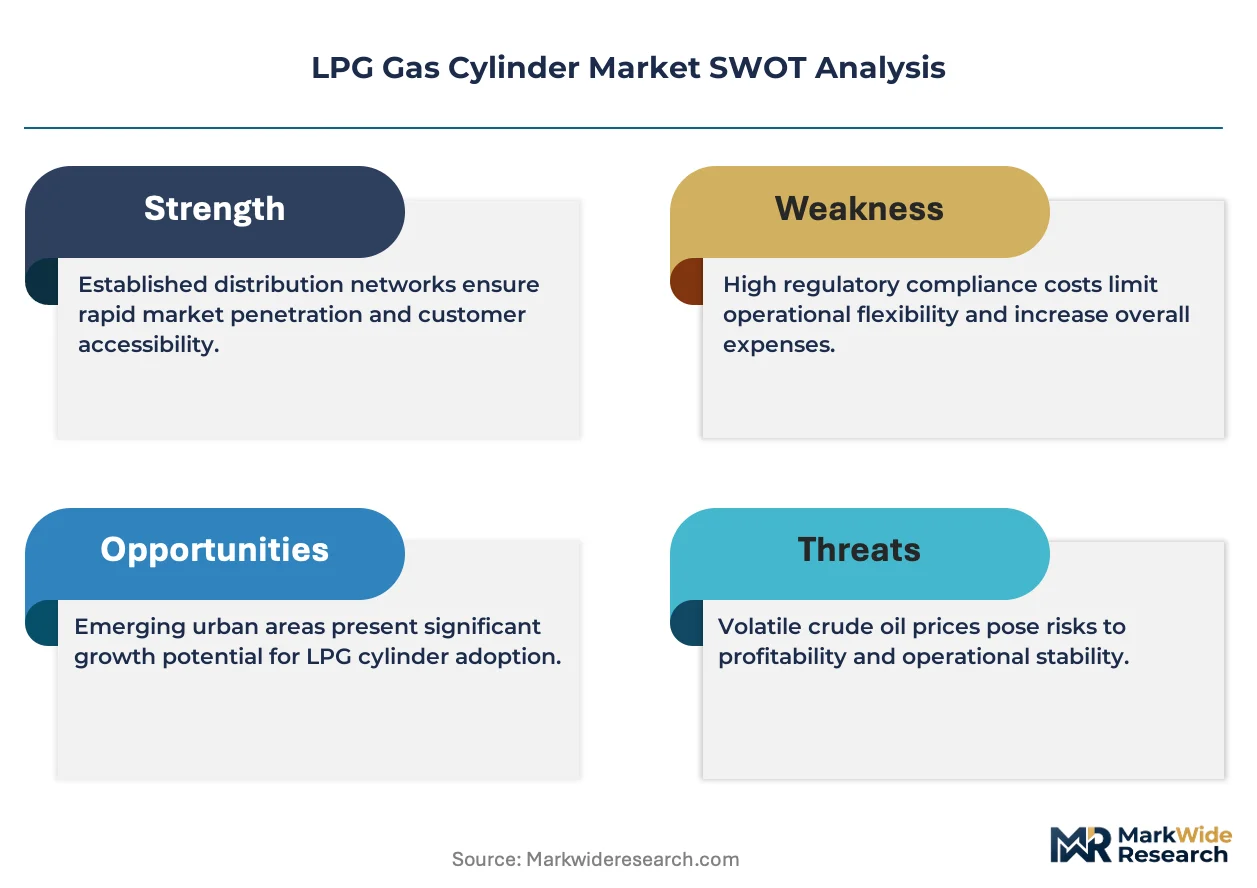
India's BIS certification, the EU's F-Gas Regulation, and the US DOT specifications collectively govern cylinder design, testing intervals, and material permissible stress limits across major demand centers. These frameworks elevate compliance costs for new entrants while creating durable certification barriers that protect incumbents with established testing relationships. Stakeholders must monitor evolving composite material standards and recycling mandates as regulators weigh decarbonization targets against incumbent steel supply chains.
Market Dynamics
Composite cylinder technology is overtaking steel across weight-sensitive applications, while India's BIS certification mandates force manufacturing upgrades that compress margins for regional fabricators.
Growth Catalysts
- Clean cooking mandates:India's national LPG subsidy expansion targets rural households, creating sustained demand pull for 15 kg residential cylinders. The program connects previously wood-dependent populations to centralized fuel distribution.
- Filament-winding automation:Advances in automated fiber placement reduce composite cylinder production cycle times by half. This process innovation narrows the cost gap with steel alternatives.
- Automotive fuel conversion:Turkey and Poland subsidize LPG vehicle retrofits for taxi and delivery fleets. These programs generate bulk orders for lightweight 30-40 liter automotive cylinders.
Market Restraints
- Steel scrap volatility:Hot-rolled coil prices swing with Chinese export quotas, compressing margin predictability for cylinder fabricators dependent on deep-drawn steel construction.
- Indian supply concentration:Three public sector oil marketing companies control 90% of domestic cylinder procurement, creating single-buyer pricing power that squeezes independent manufacturers.
- Composite recycling void:Thermoset polymer liners lack established end-of-life processing infrastructure. This technical limitation threatens circular economy compliance in EU markets.
Strategic Opportunities
- Peri-urban India penetration:Satellite towns around Mumbai, Delhi, and Bangalore show cylinder density gaps of 40% below urban cores. Distributor network expansion here captures first-mover positioning.
- Camping and outdoor recreation:European and North American consumers purchase 5-10 kg composite cylinders for RV and marine applications. This emerging application commands 3x steel cylinder pricing.
- EU F-Gas Regulation alignment:Pressure vessel standards revisions favor lightweight alternatives in transport refrigeration. Manufacturers certifying early capture specification-setting influence.
Industry Challenges
- Composite welder certification scarcity:Filament-winding technicians require 18-month training programs. This skill gap constrains production scaling for emerging market entrants.
- Hydrostatic test facility bottlenecks:BIS-accredited testing centers in India face 90-day backlogs. This certification timeline delay stalls new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPG Gas Cylinder Market |
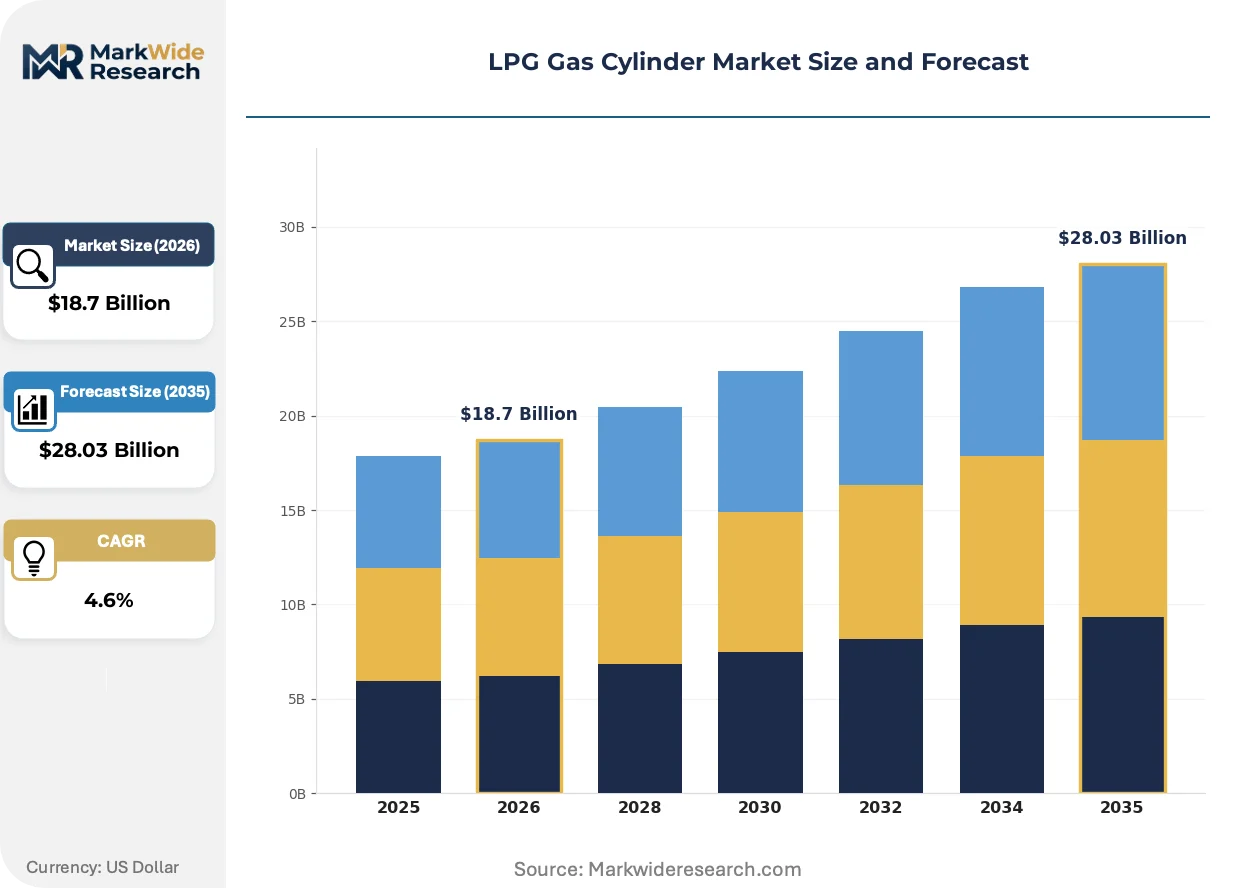
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refillable, Exchangeable, Composite, Steel End User: Residential, Commercial, Industrial, Automotive Capacity: 5 kg, 10 kg, 15 kg, 45 kg Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Hexagon Composites, Aburi Composites, Amtrol-Alfa, Time Technoplast, ALAMAN Gas Cylinders, Worthington Industries, Manchester Tank, Faber Industrie, Luxfer Gas Cylinders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPG Gas Cylinder Market Strategic Shifts
Material substitution and regulatory tightening are compressing traditional manufacturing economics while opening premium segments for certified composite suppliers.
Filament-wound carbon fiber cylinders store LPG at equivalent pressure with 70% weight reduction versus steel. Fleet operators in Turkey and South Korea specify these for taxi conversions to maximize vehicle payload. Composite construction is overtaking steel in automotive applications where every kilogram of tank weight translates to fuel savings.
The EU's F-Gas Regulation tightens leak-rate thresholds for transport refrigeration systems. Cylinder manufacturers must redesign valve interfaces and seam geometries to meet sub-5 gram annual loss specifications. European cold-chain logistics providers now require third-party certification documentation before procurement approval.
Indian national oil companies consolidate distributor appointments, reducing independent channel partners by 30% in Maharashtra and Gujarat. Surviving distributors invest in ERP-linked delivery tracking to demonstrate last-mile reliability. This concentration shift squeezes regional players lacking capital for digital infrastructure.
LPG Gas Cylinder Market Segmentation
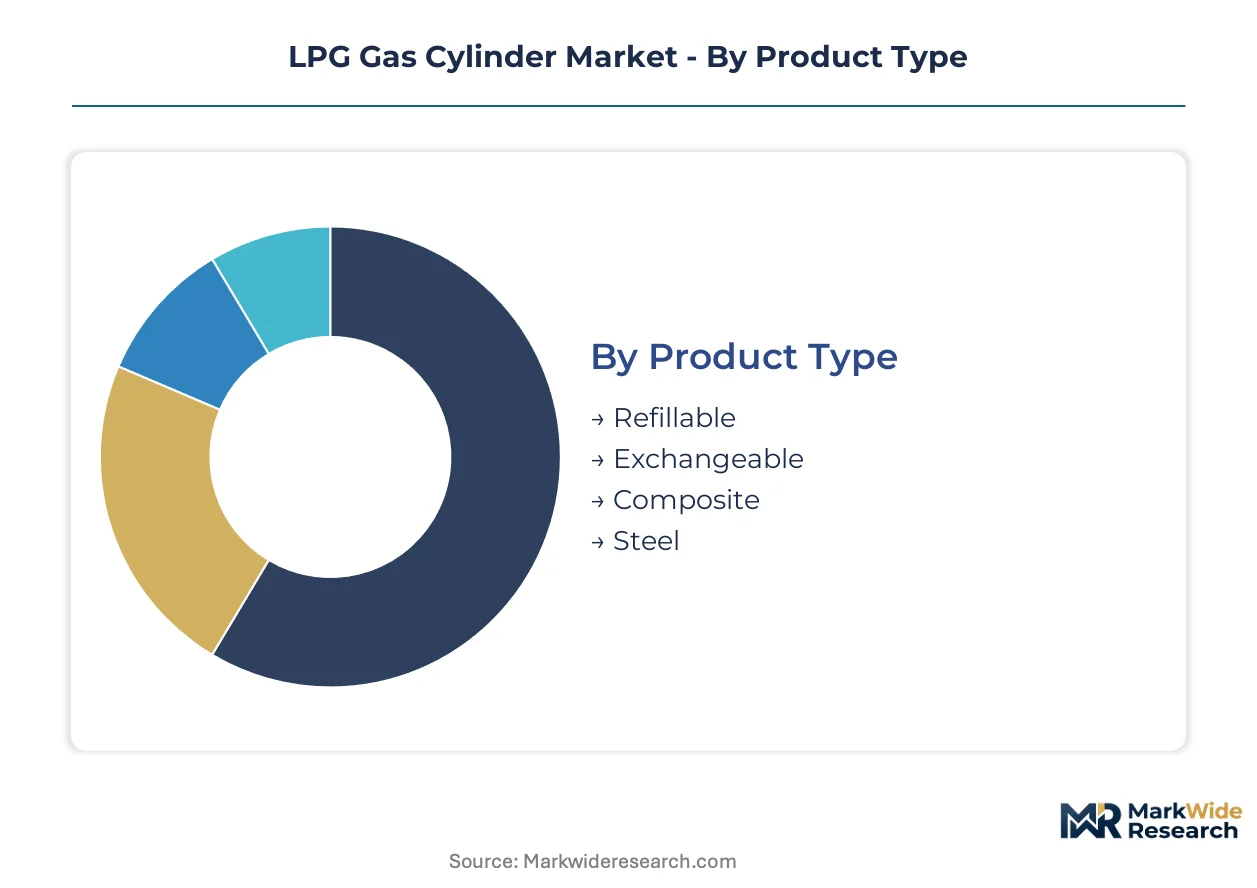
LPG cylinder purchasing patterns split sharply between bulk industrial procurement and fragmented household demand. Material technology and regulatory certification create tiered value pools that reward specialized manufacturing capabilities.
Product Type:
Material composition and reusability protocols define performance boundaries across pressure vessel categories.
- Refillable:Designed for repeated hydrostatic testing and valve replacement cycles under DOT and BIS protocols. Indian national oil companies mandate this format for residential cooking connections, locking in standardized 15 kg specifications.
- Exchangeable:Pre-filled units swapped at retail points eliminate consumer refilling logistics. North American propane retailers deploy this model for residential heating and grilling segments, capturing recurring revenue through tank rental fees.
- Composite:Filament-wound carbon fiber construction achieves pressure ratings at 30% of steel weight. Automotive retrofits in Turkey and South Korea specify these for taxi fleet conversions where payload efficiency governs fuel economics.
- Steel:Deep-drawn welded construction dominates installed base volumes through established recycling infrastructure and sub-$50 unit economics at wholesale scale.
Mature deployment sits with Steel. Newer deployment is concentrated in Composite.
End User:
Volume concentration and margin structure diverge across consumption settings.
- Residential:India's clean cooking subsidy program targets rural household conversion from biomass, generating sustained 15 kg cylinder demand. Three public sector oil marketing companies control procurement, squeezing independent fabricator margins through consolidated tendering.
- Commercial:Restaurants, hotels, and food processing facilities consume 45 kg units through wholesale distributor networks. Peri-urban corridors around Mumbai and Delhi show 40% penetration gaps versus urban cores.
- Industrial:Metal cutting, ceramic firing, and chemical processing applications require bulk tanker-fed systems rather than portable cylinders, limiting addressable market scope.
- Automotive:Poland and Turkey subsidize LPG vehicle retrofits for taxi and delivery fleets. These programs generate bulk orders for lightweight 30-40 liter automotive cylinders.
Volume leadership rests with Residential. Steepest expansion trajectory belongs to Automotive.
Capacity:
Weight-class specifications align with handling logistics and consumption intensity.
- 5 kg:Compact camping and marine applications command 3x steel cylinder pricing in European and North American outdoor recreation markets. Composite construction dominates this premium segment.
- 10 kg:Mid-size format serves small commercial kitchens and mobile food vendors requiring portability without forklift handling.
- 15 kg:India's standard residential cooking unit captures the largest margin pool through national subsidy-linked distribution. BIS certification mandates govern valve and weld specifications exclusively.
- 45 kg:Industrial and commercial anchor format moves through wholesale channel economics with bulk pricing tiers tied to volume commitments.
Subsidy-linked deployment centers on 15 kg. Premium pricing concentrates in 5 kg.
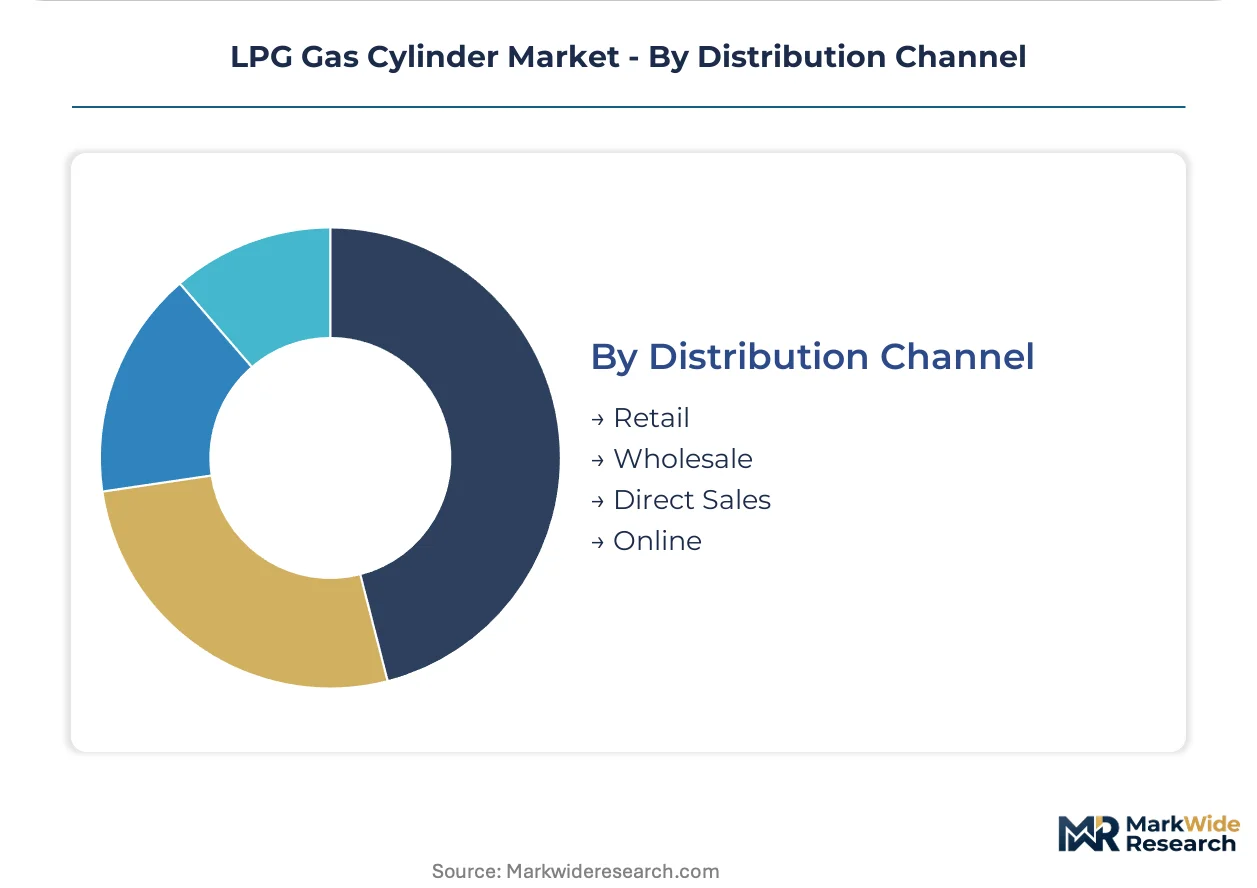
Distribution Channel:
Channel selection determines working capital intensity and customer relationship depth.
- Retail:Dealer networks with physical cylinder exchange points dominate Indian residential access. Surviving distributors invest in ERP-linked delivery tracking to demonstrate last-mile reliability.
- Wholesale:Direct supply to industrial and commercial accounts bypasses retail markup, capturing volume discounts and contractual supply security.
- Direct Sales:Manufacturer-to-end-user relationships emerge in automotive retrofit programs where fleet operators specify custom cylinder configurations.
- Online:Digital ordering platforms gain traction in urban India for cylinder booking and delivery scheduling, though physical exchange remains mandatory.
Established infrastructure favors Retail. Digital integration is advancing fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates residential cylinder demand through its national clean cooking subsidy program, while automotive retrofit incentives in Turkey and Poland pull lightweight composite volumes. Regulatory divergence across major economies fragments certification requirements and shapes regional manufacturing investment patterns.
India
Rural household conversion from biomass to LPG drives 15 kg cylinder procurement through three public sector oil marketing companies. BIS certification mandates govern valve specifications and hydrostatic testing intervals exclusively. Maharashtra and Gujarat host distributor consolidation where surviving partners deploy ERP-linked delivery tracking to demonstrate last-mile reliability.
Turkey
Taxi and delivery fleet operators generate bulk orders for 30-40 liter automotive cylinders under government retrofit subsidy schemes. The country's national energy regulator oversees pressure vessel compliance for transport applications. Istanbul anchors conversion demand where payload efficiency governs fuel economics for commercial vehicle operators.
United States
Propane retailers capture recurring revenue through exchangeable tank rental models in residential heating and outdoor grilling segments. DOT specifications govern cylinder design, testing intervals, and material stress limits for interstate commerce. Texas and the Midwest host manufacturing clusters where deep-drawn steel construction dominates wholesale utility networks.
Poland
Automotive LPG retrofit programs for taxi fleets generate concentrated demand for lightweight cylinder configurations. EU F-Gas Regulation alignment pressures manufacturers to redesign valve interfaces for sub-5 gram annual leak-rate thresholds. Warsaw and Krakow metropolitan areas anchor fleet operator procurement decisions.
Germany
Transport refrigeration cold-chain logistics providers require third-party certification documentation before cylinder procurement approval. ECHA oversight of composite material standards intersects with pressure vessel safety frameworks. Bavaria and North Rhine-Westphalia concentrate industrial gas distribution infrastructure serving metal cutting and ceramic firing applications.
LPG Gas Cylinder Market Competitive Environment
North American producers anchor one tier through standardized steel cylinder supply to utility networks; European and Asian specialists hold differentiated positions in composite filament-winding and cost-optimized polymer designs. The vendor base splits between scale-driven steel fabricators and technology-differentiated composite manufacturers. Three archetypes dominate: integrated steel processors with recycling infrastructure, filament-winding automation leaders, and emerging market cost optimizers. Capacity expansion and certification-driven portfolio diversification constitute the dominant competitive moves.
Among the composite technology tier, Hexagon Composites and Time Technoplast occupy positions representing divergent strategic approaches to material substitution. Hexagon anchors premium positioning through proprietary manufacturing architectures. Time Technoplast exemplifies emerging market adaptation through cost-optimized design configurations. Worthington Industries represents the scale-driven steel archetype with established supply relationships across North American utility networks. These three fabricators illustrate how geographic origin and structural format shape competitive positioning within fragmented certification environments.
| Leading Market Players |
|---|
| Hexagon Composites |
| Aburi Composites |
| Amtrol-Alfa |
| Time Technoplast |
| ALAMAN Gas Cylinders |
| Worthington Industries |
| Manchester Tank |
| Faber Industrie |
| Luxfer Gas Cylinders |
| Others |
Value Chain & Pricing Dynamics
Filament-winding technician scarcity in Gujarat and Maharashtra widens labor-cost spreads between premium composite and standard steel cylinder tiers. BIS-accredited testing facility backlogs compress margins for regional fabricators unable to absorb 90-day certification delays.
Pricing Analysis
Volume leadership sits with steel cylinders at sub-$50 wholesale unit economics, while composite variants capture 3x pricing in 5 kg camping and marine segments. Price differentiation hinges on BIS certification grade and filament-winding automation level. Cost compression in steel tiers intensifies as hot-rolled coil volatility from Chinese export quotas squeezes margin predictability. National oil companies in India exercise consolidated procurement power, rendering independent fabricators most price-sensitive versus automotive fleet operators specifying lightweight configurations.
Supply Chain Analysis
Reverse-logistics flows for hydrostatic testing and valve refurbishment anchor steel cylinder economics through established recycling infrastructure in India, China, and the United States. Raw material dependencies center on hot-rolled coil steel, carbon fiber tow, and thermoset polymer liners. Single-source vulnerability concentrates in BIS-accredited testing capacity where 90-day backlogs stall new product launches. Distribution runs through national oil company dealer networks in India and propane retailer exchange programs in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite welder certification scarcity constrains capacity expansion, propping pricing power for accredited manufacturers across the analysis window.
For Market Incumbents: Anchor market position through backward integration into filament-winding automation and captive BIS testing relationships. Composite recycling infrastructure investment defends against EU circular economy compliance threats. Capacity addition in peri-urban Maharashtra and Gujarat corridors captures distributor consolidation survivors deploying ERP-linked delivery tracking. For New Entrants and Emerging Players: Capture white-space in European camping and outdoor recreation segments where 5-10 kg composite cylinders command premium positioning. Peri-urban India penetration gaps around Mumbai, Delhi, and Bangalore offer first-mover distributor network expansion. Direct sales to automotive fleet operators in Turkey and Poland bypass consolidated retail channel economics. For Investors and Strategic Acquirers: Re-rating potential sits with filament-winding automation leaders given automotive retrofit subsidy expansion in Turkey, Poland, and South Korea. Long-term viability favors manufacturers with diversified material exposure across steel and composite portfolios. Monitor BIS certification timeline compression and EU F-Gas Regulation alignment progress as inflection indicators for specification-setting influence.| Strategic Initiative | Industry Significance |
|---|---|
| Filament-Winding Automation Scale-Up | Hexagon Composites and Time Technoplast reduce production cycle times by half through automated fiber placement advances. |
| BIS Certification Investment | Regional Indian fabricators secure testing relationships to bypass 90-day hydrostatic facility backlogs stalling competitors. |
| Composite Recycling Infrastructure | EU-facing manufacturers address thermoset polymer liner end-of-life processing gaps threatening circular economy compliance. |
| Peri-Urban Distributor Expansion | Surviving partners in Maharashtra and Gujarat deploy ERP-linked tracking to demonstrate last-mile reliability to national oil companies. |
| Automotive Fleet Direct Sales | Lightweight cylinder suppliers in Turkey and South Korea bypass retail markup through manufacturer-to-operator relationships. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with filament-winding technicians, BIS certification officers, national oil company procurement managers, and automotive fleet operators informed demand-side validation. Petroleum and Explosives Safety Organization directives, EU F-Gas Regulation amendments, and US DOT specification updates supplemented customs import records and steel price indices. Bottom-up cylinder shipment tallies and top-down energy consumption models were triangulated to reconcile volume estimates.
Data-stream reconciliation across production capacity surveys, distributor inventory audits, and end-use consumption patterns shaped the analytical framework. Segmentation dimensions modeled include material composition, capacity class, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline estimates. Forecast inputs incorporated BIS certification expansion timelines and automotive retrofit subsidy program trajectories across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to composite material standard revisions and steel scrap price volatility. Forecasts reflect documented assumptions regarding subsidy program continuity and certification capacity expansion. Practitioners should monitor BIS testing facility backlog durations and EU circular economy mandate progression for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Mobile Gas Pumping System Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Wood Charcoal Market
Fuels
LPG Vaporizer Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Wood Pellet Market
Fuels
Europe Coal Market
Fuels
High Octane Racing Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
North America Aviation Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
Smart Gas Market
Fuels
Aboveground Fuel Storage Market
Fuels
Global Industrial Burner Market
Fuels
Storage Tank Market
Fuels
Chafing Fuel Market