
 India LNG Market | 2026-2036
India LNG Market Size, Share, and Industry Trends Forecast 2026-2036
India LNG Market Outlook
Coal is restructuring product economics across India's gas value chain as industrial buyers substitute LNG for furnace oil and petcoke in cement, ceramics, and textiles. Petronet LNG Limited leverages its Dahej and Kochi terminal infrastructure to sustain throughput leadership on the west coast. GAIL Limited anchors the national pipeline grid, while Adani Ports and Special Economic Zone Limited controls emerging import capacity at Mundra and Dhamra.
Liquefied natural gas is natural gas cooled to approximately minus 162 degrees Celsius, reducing volume by roughly 600 times for maritime transport and storage in cryogenic tanks before regasification for pipeline injection or direct industrial use. Power Generation occupies the largest demand share among application segments, though Transportation is recording the fastest structural expansion as compressed natural gas and LNG dual-fuel systems penetrate long-haul trucking and coastal shipping. Tankers dominate distribution channel flows for import logistics, while Pipelines capture margin pools in last-mile connectivity to utility and manufacturing offtakers.
The Petroleum and Natural Gas Regulatory Board mandates third-party access to LNG terminals, while the Central Electricity Authority enforces emission norms that push power utilities toward gas-fired capacity. The Bureau of Indian Standards prescribes cryogenic equipment and storage safety codes that shape capital deployment timelines. Stakeholders must monitor terminal utilization rates, pipeline interconnection progress, and state-level city gas distribution licensing rounds to calibrate capacity commitments against actual offtake velocity.
Market Dynamics
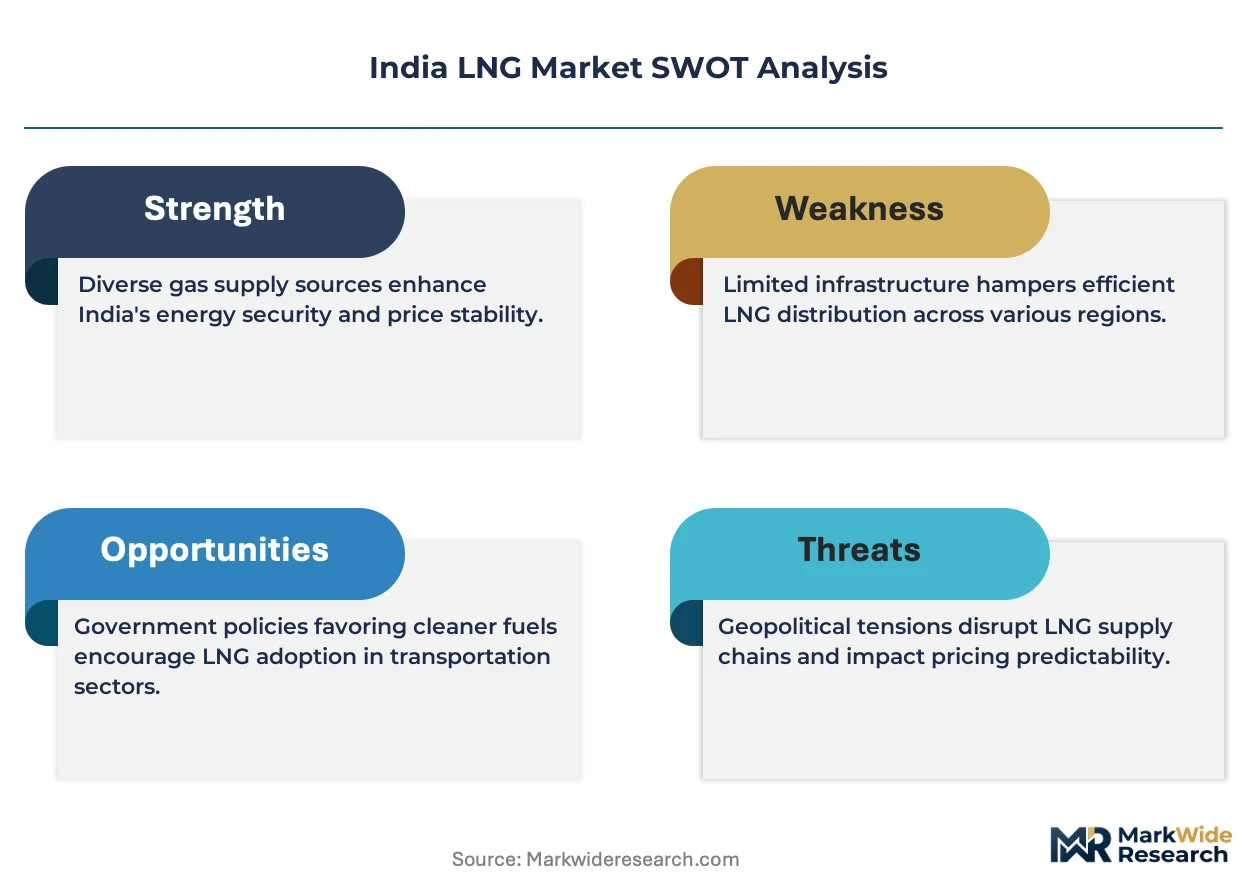
The Petroleum and Natural Gas Regulatory Board's open access mandate for LNG terminals is fragmenting import capacity control and forcing incumbent terminal operators to compete for throughput volumes against new market entrants seeking regasification services.
Growth Catalysts
- CEA emission norms:The Central Electricity Authority's tightened particulate matter standards for thermal power plants are compelling utilities in Maharashtra and Gujarat to switch from coal to gas-fired generation, expanding baseload LNG demand.
- City gas distribution licensing:The PNGRB's eleventh and twelfth bidding rounds for CGD networks are extending pipeline connectivity to tier-two industrial clusters in Rajasthan and Madhya Pradesh, creating new anchor offtakers.
- Floating storage and regasification units:FSRU deployment at underutilized ports is compressing terminal development timelines from five years to eighteen months, accelerating import capacity additions on India's eastern seaboard.
Market Restraints
- Henry Hub-linked pricing volatility:Indian LNG contracts indexed to US natural gas benchmarks expose industrial buyers to currency and commodity double exposure, eroding cost predictability for ceramics and textile manufacturers.
- Qatar-Singapore supply concentration:Over sixty percent of India's LNG imports originate from a two-source corridor, creating geopolitical and logistics concentration risk that no domestic storage buffer can fully offset.
- Pipeline interconnection gaps:The National Gas Grid's missing links between Kochi and Mangalore, and between Barauni and Haldia, force stranded demand to rely on higher-cost trucking.
Strategic Opportunities
- Odisha industrial corridor:The Dhamra LNG terminal and adjacent SEZ infrastructure position the state to capture metal, fertilizer, and refining demand currently served by distant Hazira supply.
- LNG bunkering for coastal shipping:The Ministry of Ports, Shipping and Waterways' mandate for green fuel transition at major ports is creating marine fuel demand at Mumbai, Visakhapatnam, and Chennai.
- Small-scale LNG distribution:Cryogenic road tankers and skid-mounted regasification units are unlocking demand from remote cement and steel plants beyond pipeline reach in Chhattisgarh and Jharkhand.
Industry Challenges
- Cryogenic welding certification scarcity:The Bureau of Indian Standards' stringent qualification requirements for 9% nickel steel welders are extending project commissioning timelines for new storage tanks.
- Regasification tolling disputes:Third-party access pricing arbitration between terminal owners and shippers is creating contractual uncertainty that delays long-term supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India LNG Market |
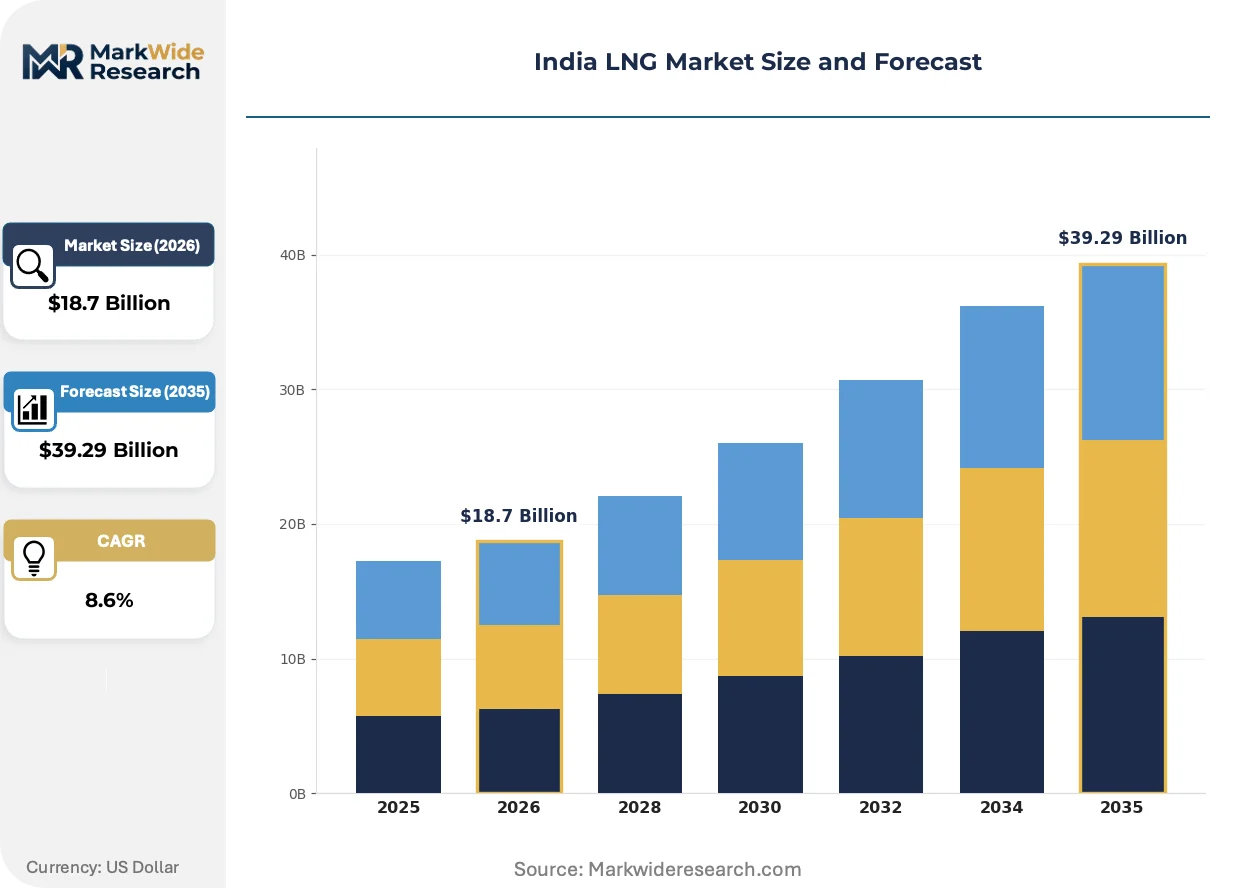
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Usage, Transportation, Residential Technology: LNG Cryogenic Cooling, Regasification, Compression, Storage Systems End User: Utilities, Manufacturing, Shipping, Households Distribution Channel: Pipelines, Tankers, Trucks, Others |
| Companies Covered | Petronet LNG Limited, GAIL Limited, Adani Ports and Special Economic Zone Limited, Indian Oil Corporation Limited, Shell PLC, GSPC LNG Limited, Bharat Petroleum Corporation Limited, H-Energy Private Limited, JSW Infrastructure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India LNG Market Strategic Shifts
Modular liquefaction and digital cargo tracking are compressing supply chain lead times while reconfiguring how industrial buyers contract for flexible, short-tenor LNG deliveries.
Modular mini-liquefaction plants are rewriting access economics for stranded gas fields and biogas upgraders. Reliance Industries and smaller independent operators are deploying skid-mounted units at CBM blocks and agricultural waste clusters. This distributed production model is compressing the traditional hub-and-spoke import structure and enabling direct industrial offtake without terminal intermediation.
The PNGRB's unified tariff framework for natural gas pipelines is flattening transportation cost gradients across the national grid. Steel, fertilizer, and power utilities in Uttar Pradesh and Bihar now face reduced locational disadvantages versus Gujarat-based competitors. This regulatory compression is triggering demand migration toward previously uneconomic hinterland markets.
Industrial procurement is fragmenting from annual term contracts toward spot-indexed tenders and medium-curve agreements. Cement and ceramic manufacturers in Andhra Pradesh and Telangana are aggregating demand through buying consortiums to secure volume discounts. This collective bargaining structure is compressing supplier margins and accelerating price discovery transparency.
India LNG Market Segmentation
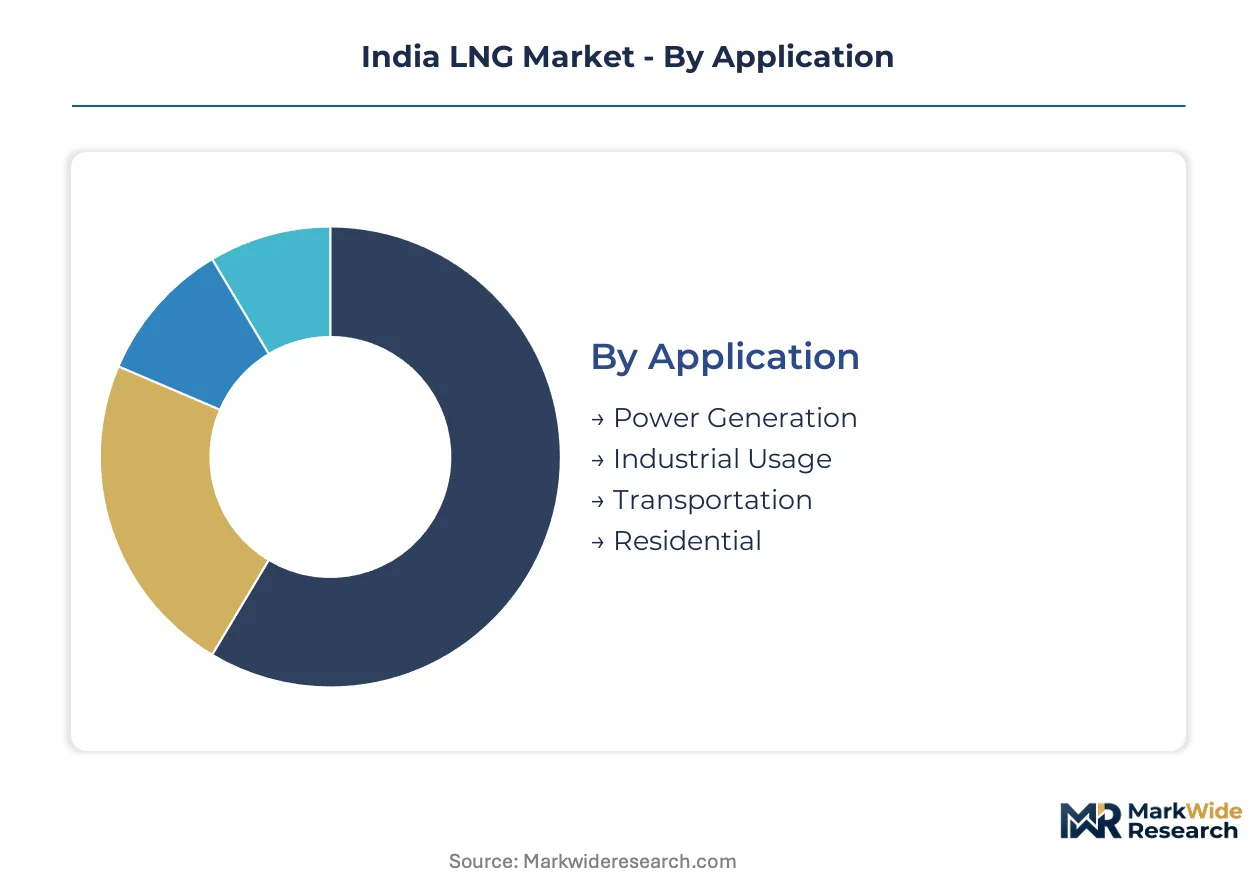
Segmentation in India's LNG market reveals how infrastructure constraints and regulatory frameworks fragment demand across incompatible delivery modes. Understanding these divisions exposes where capital deployment faces technical bottlenecks versus policy-driven acceleration.
Application:
Standalone baseload demand segments operate independently from intermittent or embedded consumption patterns across India's gas value chain.
- Power Generation:Combined-cycle gas turbine plants in Gujarat and Maharashtra consume regasified LNG for grid-stabilizing capacity. Maharashtra's coastal utilities anchor volumes under Central Electricity Authority emission compliance deadlines.
- Industrial Usage:Furnace fuel substitution in ceramics, cement, and textiles drives consumption clusters. Gujarat's industrial corridors concentrate demand where pipeline connectivity intersects with coal displacement economics.
- Transportation:Compressed natural gas and LNG dual-fuel systems penetrate long-haul trucking and coastal shipping through city gas distribution networks.
- Residential:Piped natural gas connections in urban CGD license areas serve cooking and heating demand through localized distribution infrastructure.
Power Generation leads volumes today; Transportation is gaining share fastest.
Technology:
Cost tiers separate capital-intensive liquefaction infrastructure from lower-capex downstream handling equipment across the value chain.
- LNG Cryogenic Cooling:Natural gas liquefaction at minus 162 degrees Celsius reduces volume by 600 times for maritime transport. Dahej and Kochi terminals anchor this high-cost tier through imported cargo regasification.
- Regasification:Heat exchange systems convert cryogenic liquid back to gaseous state for pipeline injection. Floating storage and regasification units compress project timelines from five years to eighteen months on India's eastern seaboard.
- Compression:CNG and LNG dispensing systems enable vehicle fueling at city gas distribution stations.
- Storage Systems:Cryogenic tanks and insulated vessels maintain sub-zero temperatures through vacuum-insulated double-wall construction.
Regasification infrastructure absorbs the largest capital allocation; cryogenic cooling capacity is expanding most quickly through FSRU deployment.
End User:
Volume concentration varies between centralized offtakers with dedicated terminal contracts versus dispersed demand requiring aggregation mechanisms.
- Utilities:State electricity boards and independent power producers secure long-term supply agreements for baseload generation.
- Manufacturing:Steel, fertilizer, and refinery operators source spot-indexed or term LNG through direct terminal access or pipeline nominations.
- Shipping:Coastal vessel operators and port authorities procure marine fuel under Ministry of Ports, Shipping and Waterways green transition mandates.
- Households:Residential consumers access piped natural gas through city gas distribution network retail connections.
Manufacturing leads volumes today; Shipping is gaining share fastest.
Distribution Channel:
Margin pools concentrate in last-mile connectivity modes versus bulk import logistics where tolling fees compress returns.
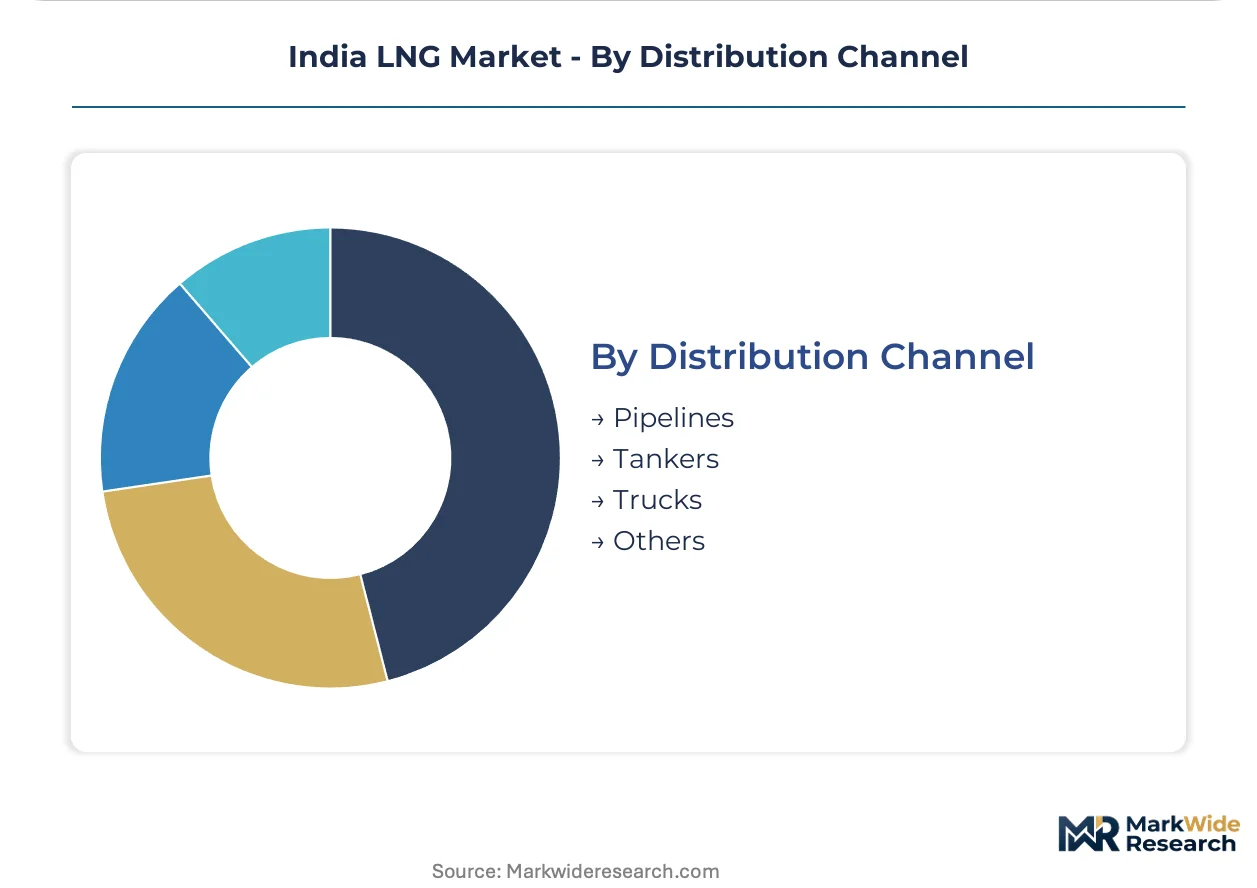
- Pipelines:High-pressure transmission networks deliver regasified gas to utility and industrial offtakers. The Petroleum and Natural Gas Regulatory Board's unified tariff framework flattens transportation cost gradients across the national grid.
- Tankers:Cryogenic maritime vessels dominate import logistics from Qatar and Singapore supply corridors.
- Trucks:Cryogenic road tankers serve stranded demand in Chhattisgarh and Jharkhand beyond pipeline reach.
- Others:Small-scale LNG distribution through skid-mounted regasification units unlocks remote industrial clusters.
Tankers lead volumes today; Trucks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridors concentrate India's LNG demand through cement, ceramics, and textile clusters substituting gas for coal. The state's Dahej terminal anchors west coast import volumes. Maharashtra and Andhra Pradesh power utilities drive coastal demand growth under emission compliance deadlines.
Maharashtra
Coastal utilities in Ratnagiri and Dabhol anchor baseload power demand under Central Electricity Authority emission norms. The state's combined-cycle gas turbine fleet consumes regasified LNG for grid stabilization. Mumbai's city gas distribution networks extend into Thane and Pune industrial belts.
Gujarat
Industrial fuel substitution in cement and ceramics clusters drives consumption around Hazira and Mundra. The Petroleum and Natural Gas Regulatory Board's open access rules fragment terminal control at Dahej and Kochi. Jamnagar refineries and Kutch manufacturing zones anchor spot-indexed procurement.
Andhra Pradesh
Fertilizer and power utilities in Visakhapatnam and Kakinada create anchor demand on the eastern seaboard. The Ministry of Ports, Shipping and Waterways mandates green fuel transition for coastal shipping. Krishnapatnam port infrastructure positions the state for FSRU deployment.
Odisha
Metal, fertilizer, and refining demand in Paradeep and Dhamra shifts from distant Hazira supply to local terminal access. The Dhamra LNG terminal and adjacent SEZ infrastructure compress logistics costs. Angul-Talcher industrial belt steel plants evaluate small-scale LNG trucking.
Tamil Nadu
Ennore LNG terminal serves Chennai's power generation and industrial clusters. The state's city gas distribution licensing rounds extend pipeline connectivity to Coimbatore textile manufacturers. Tuticorin port authorities prepare LNG bunkering infrastructure under coastal shipping mandates.
India LNG Market Competitive Environment
Global majors compete with regional champions across terminal capacity and pipeline grid control. The market structures around incumbent regasification infrastructure operators, national pipeline grid anchors, and emerging port-based import capacity developers. Three archetypes dominate: legacy terminal operators with throughput leadership, state-backed pipeline grid controllers, and private port developers deploying FSRU assets. Competitive moves concentrate on capacity expansion at underutilized eastern ports and strategic partnerships for city gas distribution network penetration.
Within the legacy terminal operator tier, Petronet LNG Limited exemplifies throughput leadership through west coast infrastructure positioning. GAIL Limited occupies the state-backed pipeline grid controller archetype, anchoring national transmission connectivity. Adani Ports and Special Economic Zone Limited represents the emerging private port developer model, controlling import capacity at Mundra and Dhamra through FSRU deployment.
| Leading Market Players |
|---|
| Petronet LNG Limited |
| GAIL Limited |
| Adani Ports and Special Economic Zone Limited |
| Indian Oil Corporation Limited |
| Shell PLC |
| GSPC LNG Limited |
| Bharat Petroleum Corporation Limited |
| H-Energy Private Limited |
| JSW Infrastructure |
| Others |
Value Chain & Pricing Dynamics
Henry Hub-linked contract volatility cascades through Indian LNG procurement tiers, compressing margins for ceramics and textile manufacturers while rewarding integrated terminal operators with captive regasification capacity. Currency-commodity double exposure in spot-indexed agreements forces industrial buyers toward medium-curve hedging structures that flatten cost predictability across Gujarat's cement clusters and Maharashtra's power utilities.
Pricing Analysis
Input-cost pass-through from Qatari and Singapore supply corridors dominates Indian LNG contract structures, with Henry Hub volatility transmitting directly to industrial offtakers under oil-indexed and hybrid pricing models. Price differentiation rests on volume scale and terminal access tier—baseload utilities secure preferential tolling rates at Dahej and Kochi, while fragmented ceramics manufacturers absorb higher spot-market exposure. Pricing pressure stems from Henry Hub volatility eroding cost predictability, particularly for ceramics and textile segments. Manufacturing buyers exhibit highest price sensitivity due to thin fuel-switching margins versus coal alternatives; integrated power utilities demonstrate lowest sensitivity through long-term offtake security.
Supply Chain Analysis
Direct-to-utility channels handle baseload demand through dedicated pipeline nominations, while cryogenic road tankers serve stranded industrial clusters beyond grid reach in Chhattisgarh and Jharkhand. Geographic supply concentrates in Qatar, Singapore, and emerging US Gulf volumes following trade route diversification. Raw material dependencies center on liquefaction capacity at source terminals, maritime vessel availability, and 9% nickel steel for cryogenic storage fabrication. Single-source vulnerability runs through the Qatar-Singapore corridor where over sixty percent of Indian imports originate. Distribution runs through a hybrid structure: tanker imports feed terminal regasification, pipelines capture last-mile margin pools, and small-scale LNG trucking unlocks remote demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indian LNG margins expand through FSRU deployment compressing terminal development timelines from five years to eighteen months, enabling faster capacity monetization at underutilized eastern ports. Premium-tier shift toward small-scale LNG distribution captures pricing power in stranded industrial corridors beyond pipeline reach.
For Market Incumbents: Anticipate third-party access fragmentation eroding tolling margins at legacy terminals by accelerating FSRU partnerships at Dhamra and Mundra before new entrants secure eastern seaboard positioning. Defensive consolidation through backward integration into city gas distribution licensing rounds in Rajasthan and Madhya Pradesh locks in anchor offtake volumes. Priority lever: cryogenic welding certification investment to preempt commissioning delays from BIS-qualified labor scarcity.
For New Entrants and Emerging Players: City gas distribution operators represent the most penetrable channel partner type for small-scale LNG equipment deployment, particularly in tier-two industrial clusters where pipeline interconnection gaps persist. White-space targets include Odisha's metal and fertilizer corridor around Dhamra, and LNG bunkering infrastructure at Visakhapatnam and Chennai under Ministry of Ports mandates. Go-to-market angle: skid-mounted regasification units bundled with cryogenic road tanker logistics for remote cement and steel plants.
For Investors and Strategic Acquirers: Roll-up economics work for FSRU-based terminal operators because fragmented import capacity control under PNGRB open access rules rewards scale players with throughput aggregation advantages. Long-term viability centers on eastern seaboard positioning where pipeline interconnection gaps and industrial demand growth converge. Acquisition target archetype: private port developers with Mundra or Dhamra capacity and adjacent SEZ land rights. Signal to watch: state-level CGD licensing round velocity in Madhya Pradesh and Rajasthan as demand migration indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Deployment | Compresses terminal development timelines from five years to eighteen months at eastern ports. |
| Backward Integration into CGD Networks | Locks in anchor offtake volumes through PNGRB licensing rounds in tier-two clusters. |
| Small-Scale LNG Distribution Buildout | Unlocks stranded cement and steel demand in Chhattisgarh and Jharkhand beyond pipeline reach. |
| LNG Bunkering Infrastructure | Captures marine fuel demand under Ministry of Ports green transition mandates at major harbors. |
| Cryogenic Certification Investment | Preempts BIS-qualified welder scarcity extending storage tank commissioning timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with terminal operations managers, city gas distribution license holders, industrial procurement leads at cement and ceramics clusters, and PNGRB regulatory officers with secondary validation. Secondary sources included Petroleum and Natural Gas Regulatory Board licensing databases, Central Electricity Authority emission compliance filings, Bureau of Indian Standards cryogenic equipment codes, and customs import records for LNG cargo volumes. Bottom-up terminal throughput modeling and top-down national demand projections were triangulated against pipeline interconnection progress and CGD network expansion timelines.
Segment-weighting approaches distributed value and volume across application dimensions including power generation baseload, industrial fuel substitution, transportation fuel, and residential piped gas, with technology tiers separating regasification infrastructure from cryogenic handling equipment. End-user segmentation differentiated utility offtakers, manufacturing procurement patterns, shipping demand, and household consumption. CAGRs were derived through regression analysis of historical terminal utilization rates against projected pipeline completion schedules and state-level emission compliance deadlines. Industry-specific forecast inputs incorporated FSRU deployment timelines and small-scale LNG trucking penetration rates in stranded demand zones.
Revisions become necessary when Henry Hub volatility exceeds modeled currency-commodity exposure bands, when PNGRB regulatory arbitration alters third-party access pricing structures, or when pipeline interconnection gaps persist beyond projected completion schedules. Forecasts reflect assumptions regarding emission norm enforcement continuity, CGD licensing round velocity, and Qatar-Singapore supply corridor stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Wood Charcoal Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Coal Briquette Box Market
Fuels
Tire Derived Fuel Market
Fuels
China Bunker Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Bunker Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Coal Trading Market
Fuels
Wood Pellet Market
Fuels
Mobile Fuel Delivery Market
Fuels
Iso-Octane Market
Fuels
Pyrolysis Gas Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
Hybrid Propellants Market
Fuels
Mobile Fuel Storage Tank Market