
 Fuel Quality Testing Market | 2026-2036
Fuel Quality Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Quality Testing Market Analysis
Third-party laboratory networks is fragmenting as fuel quality testing migrates from centralized refineries toward distributed bunkering terminals and retail fuel depots. SGS SA leverages its marine fuel testing infrastructure across major port clusters to sustain volume leadership in bunker fuel verification. Bureau Veritas differentiates through integrated cargo inspection and laboratory analytics at key energy trading hubs. Intertek Group plc anchors its position in aviation fuel testing through long-term contracts with airport fuel farm operators.
Fuel quality testing encompasses the analytical verification of physical and chemical fuel properties against specified standards, including cetane index, sulfur content, flash point, and distillation curve parameters measured through standardized ASTM and ISO protocols. Gas chromatography and spectroscopy methods dominate laboratory-grade verification where precision requirements exceed field-testing capabilities. Diesel and aviation fuels command premium testing margins due to stringent sulfur and particulate specifications, while biofuels represent the fastest-expanding fuel type segment as blend mandates intensify feedstock verification needs. Oil refineries remain the largest end-user category, though fuel distributors are accelerating testing frequency to manage custody transfer liability.
The US EPA enforces Tier 3 gasoline sulfur standards that mandate downstream quality surveillance, while the EU F-Gas Regulation and REACH framework constrain fluorinated tracer use in certain fuel marker technologies. IMO 2020 sulfur regulations have permanently reshaped marine fuel testing protocols at bunkering ports. Stakeholders must monitor the divergence between regional biofuel authentication standards and the readiness of portable analyzer technology to match laboratory-grade detection limits.
Market Dynamics
Marine fuel testing protocols are fragmenting as IMO 2020 sulfur enforcement pushes verification from centralized laboratories toward distributed bunkering terminals at major port clusters worldwide.
Growth Catalysts
- IMO 2020 Sulfur Cap:The International Maritime Organization's sulfur regulations mandate on-site fuel verification at bunkering ports, expanding demand for rapid testing instrumentation across Singapore, Rotterdam, and Fujairah.
- Aviation Fuel Farm Modernization:Commercial airports in the United States, Germany, and the United Arab Emirates are deploying automated sampling systems to meet ICAO fuel quality standards for jet A-1 certification.
- Biofuel Blend Mandates:The EU Renewable Energy Directive and California's Low Carbon Fuel Standard require feedstock authentication, driving chromatography demand for fatty acid methyl ester verification.
Market Restraints
- Reference Standard Volatility:The cost of certified reference materials for sulfur and cetane calibration fluctuates with crude oil price movements, compressing laboratory margin structures.
- Equipment Supply Concentration:Gas chromatography-mass spectrometry hardware depends on specialized component suppliers concentrated in Germany and Japan, creating procurement bottlenecks.
- Fluorinated Tracer Restrictions:The EU F-Gas Regulation and REACH framework constrain marker compound use, forcing reformulation of certain fuel authentication technologies.
Strategic Opportunities
- Portable Analyzer Deployment:Handheld near-infrared spectrometers are penetrating retail fuel depot networks in India and Brazil where laboratory infrastructure remains sparse.
- Hydrogen Fuel Quality Protocols:The EU Hydrogen Strategy and Japan's METI roadmap are establishing purity standards for fuel cell applications, opening new analytical service lines.
- Blockchain-Verified Certification:Digital custody transfer platforms are converging with testing data, enabling real-time quality documentation for marine fuel trading at Singapore and Houston.
Industry Challenges
- Spectroscopy Technician Scarcity:Interpretation of complex chromatograms and spectral data requires specialized analytical chemists, with training pipelines failing to match bunkering port expansion rates.
- Multi-Jurisdictional Accreditation:Laboratories serving both EPA Tier 3 gasoline surveillance and EU marine fuel markets must maintain parallel ISO 17025 scopes, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Quality Testing Market |
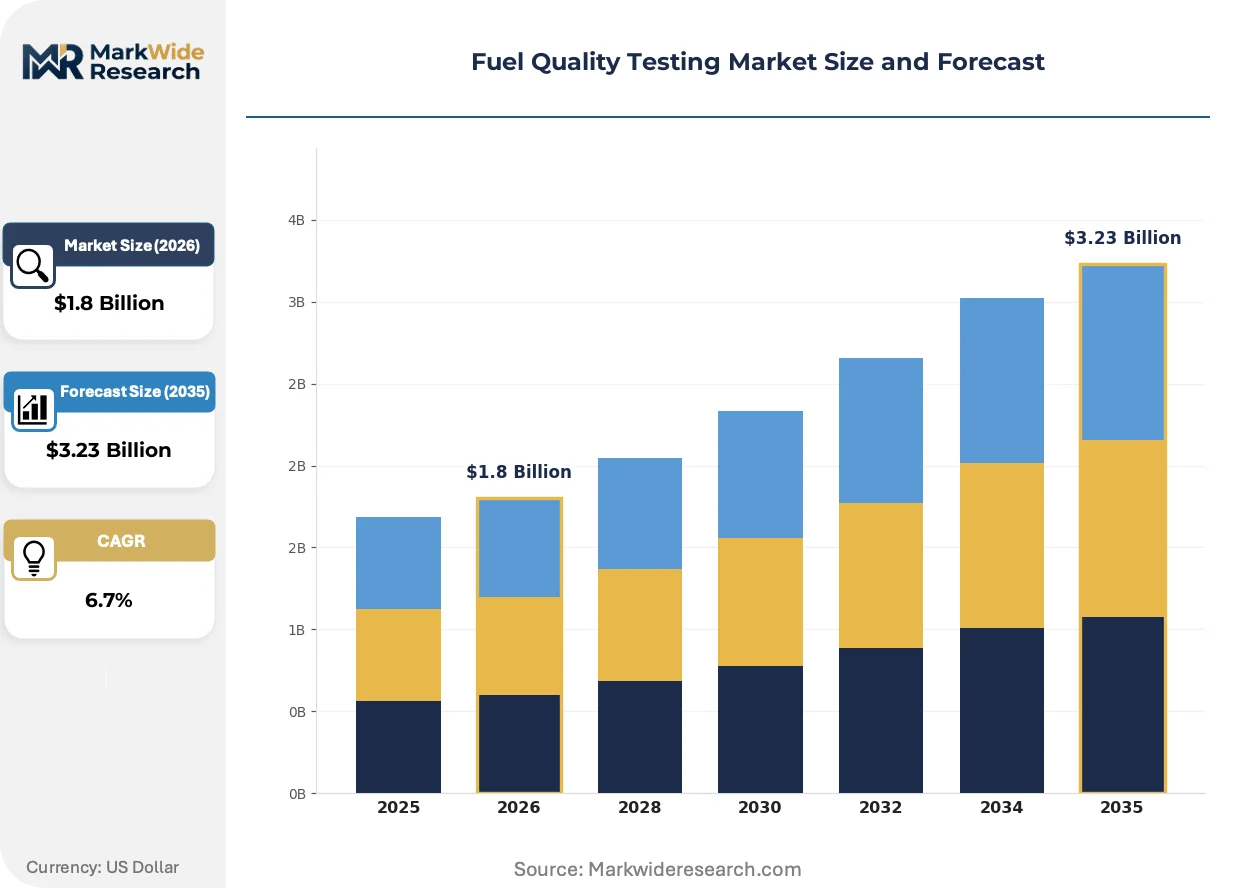
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Gas Chromatography, Spectroscopy, Octane Rating, Field Testing End User: Oil Refineries, Fuel Distributors, Automotive Manufacturers, Research Laboratories Fuel Type: Gasoline, Diesel, Biofuels, Aviation Fuels Equipment Type: Handheld Analyzers, Laboratory Analyzers, Portable Test Kits, Stationary Testing Equipment |
| Companies Covered | Eurofins Scientific, Applus+, SGS SA, Veritas Petroleum Services, ALS Limited, Bureau Veritas, TÜV SÜD, MEG Corp, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Quality Testing Market Emerging Trajectories
Digital instrumentation and remote monitoring architectures are compressing the traditional laboratory-to-field testing hierarchy, enabling real-time fuel quality decisions at the point of custody transfer.
Near-infrared spectroscopy combined with chemometric modeling is virtualizing the traditional distillation curve analysis. Fuel distributors at US Gulf Coast terminals and ARA hub operators are adopting these systems to replace 45-minute laboratory procedures with 30-second field measurements. This virtualization is collapsing the time window between sampling and release authorization, reducing tankage holding costs.
The EPA's Tier 3 gasoline sulfur standards and downstream quality surveillance mandates are forcing refiners to deploy continuous online analyzers at pipeline injection points. US refineries are integrating these systems with distributed control architectures to prevent batch contamination events. The gasoline retail segment bears the compliance burden through enhanced third-party testing frequency at terminal racks.
Airport fuel farm operators are consolidating procurement around integrated service contracts that bundle sampling, laboratory analysis, and digital certification. This behavior is displacing transactional testing relationships at major European hubs including Amsterdam Schiphol and Frankfurt. Germany and the Netherlands show the strongest concentration of multi-year service agreements with embedded compliance reporting.
Fuel Quality Testing Market Segmentation
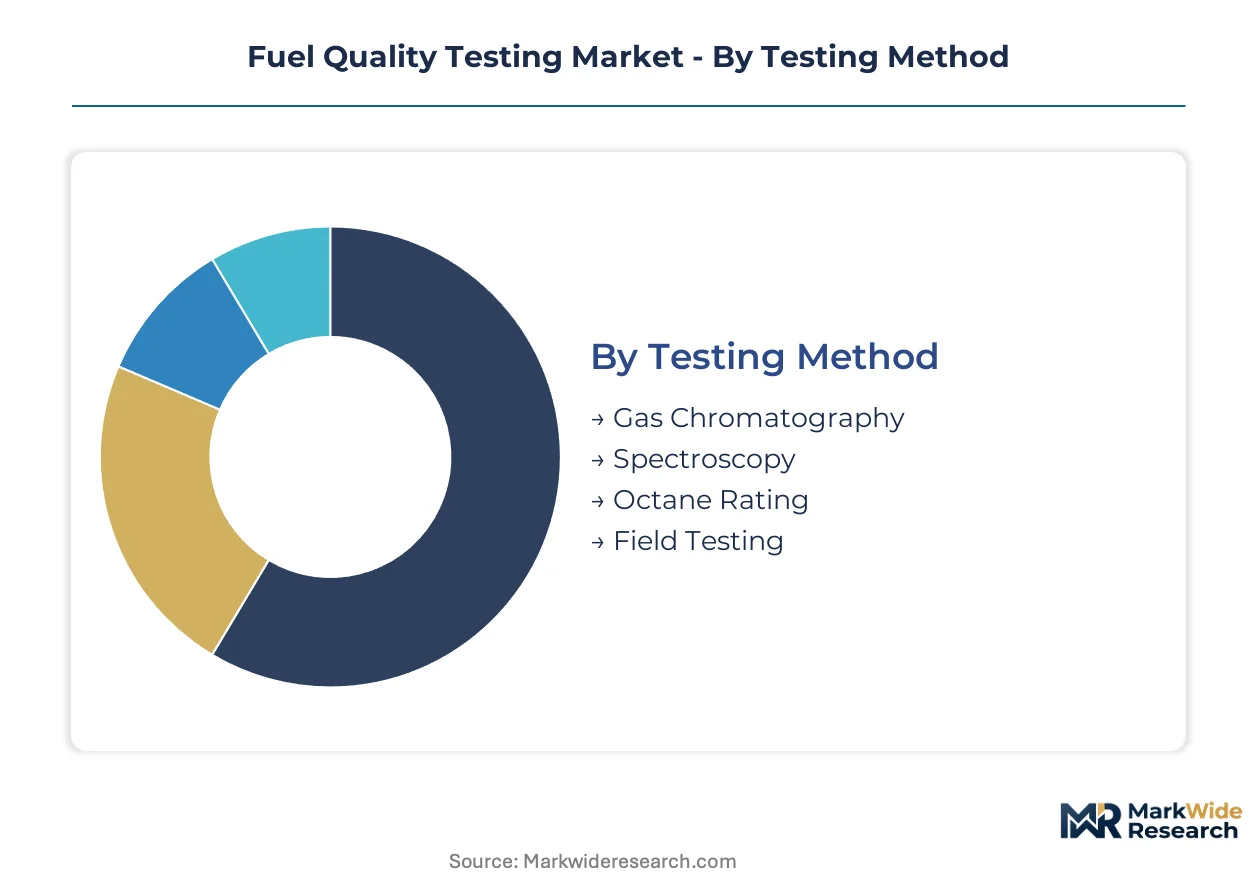
Fuel quality testing segments reflect divergent technical requirements across custody transfer points, from pipeline injection to retail dispensing. Each dimension—method, user, fuel type, and equipment—carries distinct margin structures and regulatory compliance burdens that reshape competitive positioning.
Testing Method:
Mature chromatography platforms dominate laboratory verification while emerging field technologies compress turnaround times at distributed terminals.
- Gas Chromatography:Separates and quantifies hydrocarbon components through vapor-phase analysis with flame ionization detection. Demand concentrates at Singapore and Rotterdam bunkering terminals where IMO sulfur verification requires precise compound identification. The method anchors laboratory revenue despite 45-minute cycle times that conflict with just-in-time fuel release schedules.
- Spectroscopy:Deploys infrared and ultraviolet absorption patterns to identify molecular structures without chromatographic separation. US Gulf Coast refineries integrate near-infrared systems at pipeline injection points for continuous sulfur monitoring under EPA Tier 3 surveillance mandates. Equipment costs and chemometric calibration complexity limit penetration at smaller depots.
- Octane Rating:Measures knock resistance through standardized engine or indirect methods for gasoline certification. Automotive manufacturers and terminal operators require periodic verification against ASTM D2699 protocols.
- Field Testing:Encompasses rapid sulfur, density, and visual inspection protocols executed at point of delivery without laboratory infrastructure. Indian and Brazilian retail networks drive adoption where centralized labs remain inaccessible.
Gas Chromatography retains volume leadership; Field Testing holds the steepest expansion curve.
End User:
Cost tier segmentation separates capital-intensive refinery laboratories from distributed third-party service networks.
- Oil Refineries:Maintain captive analytical capabilities for process control and regulatory compliance at production source. Continuous online analyzers at US pipeline injection points prevent batch contamination events that trigger EPA enforcement. Capital intensity and specialized staffing requirements create barriers to service provider substitution.
- Fuel Distributors:Bear custody transfer liability through enhanced testing frequency at terminal racks and retail depots. Third-party laboratory contracts at ARA hub operators bundle sampling, analysis, and digital certification into multi-year agreements. Margin pressure from reference material cost volatility compresses service provider profitability.
- Automotive Manufacturers:Require fuel certification for engine calibration and emissions compliance validation. OEM testing programs focus on cetane index and particulate specifications for diesel powertrain development.
- Research Laboratories:Support method development and regulatory standard-setting through reference material production. Academic and national laboratory participation concentrates in Germany and Japan where chromatography hardware suppliers maintain technical centers.
Oil Refineries retain volume leadership; Fuel Distributors hold the steepest expansion curve.
Fuel Type:
Application-driven segmentation separates transportation fuels with stringent sulfur limits from emerging biofuel authentication requirements.
- Diesel:Faces the most stringent sulfur surveillance under EPA Tier 3 and EU fuel quality directives. Cetane index and lubricity specifications demand laboratory-grade precision that field methods struggle to replicate. Demand concentrates at US Gulf Coast refining corridors and European automotive corridors.
- Biofuels:Require fatty acid methyl ester verification and feedstock authentication under EU Renewable Energy Directive and California LCFS mandates. Chromatography demand climbs fastest as blend intensities rise and sustainability certification tightens. Laboratory capacity constraints emerge at Brazilian ethanol terminals and European biodiesel hubs.
- Gasoline:Subject to vapor pressure, benzene, and sulfur specifications that vary by seasonal formulation. Refinery process analyzers dominate quality control with spot verification at retail terminals.
- Aviation Fuels:Mandate jet A-1 certification through flash point, freezing point, and particulate testing under ICAO standards. Airport fuel farm operators at Amsterdam Schiphol and Frankfurt consolidate procurement around integrated service contracts.
Diesel retains volume leadership; Biofuels hold the steepest expansion curve.
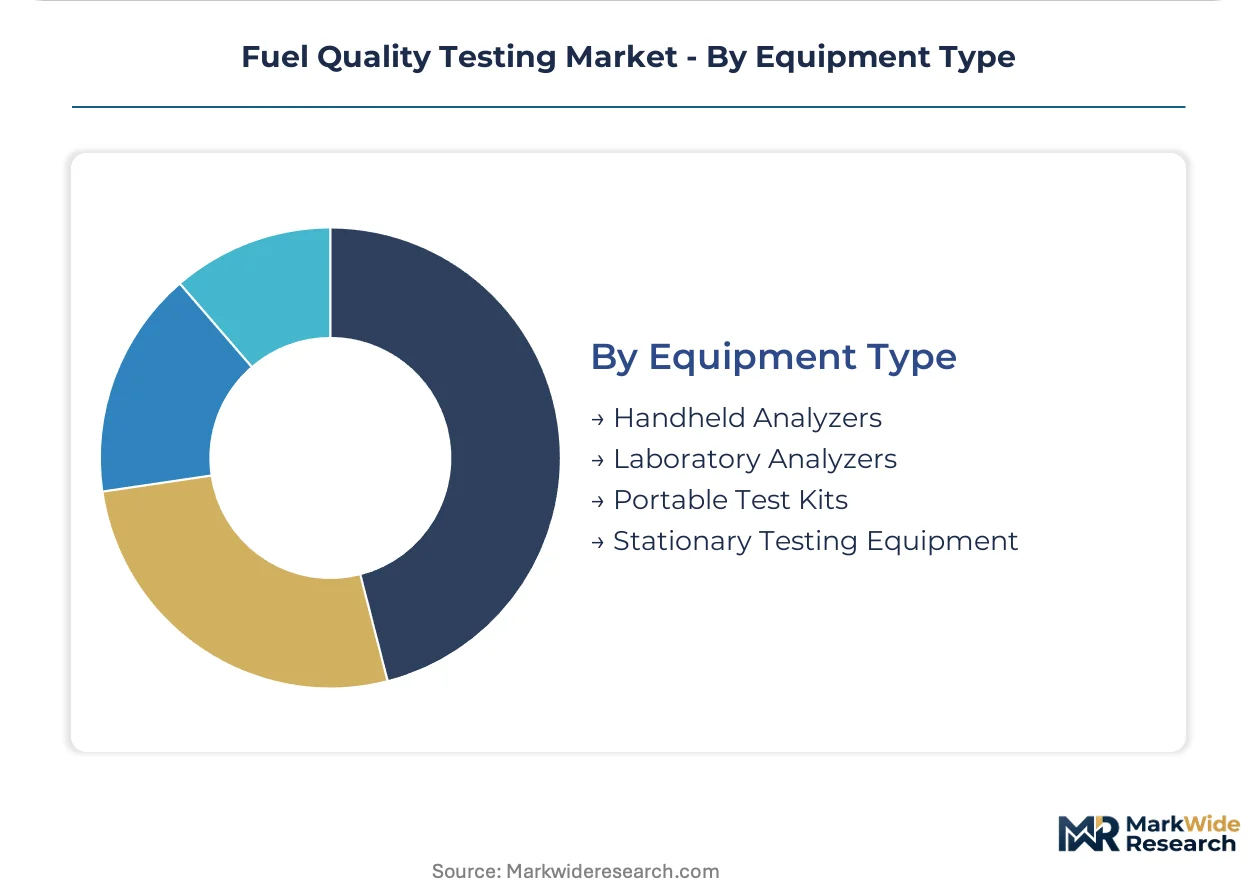
Equipment Type:
Customer type segmentation separates high-volume laboratory installations from distributed handheld deployments.
- Laboratory Analyzers:Encompass gas chromatography-mass spectrometry and high-resolution spectroscopy platforms requiring controlled environments and specialized operators. Hardware procurement concentrates at Singapore marine fuel hubs and US refinery complexes where ISO 17025 accreditation is mandatory.
- Handheld Analyzers:Deploy near-infrared spectrometers and X-ray fluorescence units for rapid sulfur screening without sample transport. Indian and Brazilian retail depot networks accelerate adoption where laboratory infrastructure remains sparse and regulatory enforcement intensifies.
- Portable Test Kits:Provide colorimetric and density-based screening for visual contamination and basic specification checks. Smaller distributors employ these for preliminary acceptance testing before laboratory confirmation.
- Stationary Testing Equipment:Includes continuous online analyzers integrated with refinery distributed control systems. Pipeline injection point installations prevent downstream contamination events that trigger regulatory penalties.
Laboratory Analyzers retain volume leadership; Handheld Analyzers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO 2020 sulfur regulations have redistributed testing demand toward bunkering hubs and refining corridors. National enforcement intensity and laboratory infrastructure gaps now determine regional competitive dynamics.
Singapore
The Maritime and Port Authority enforces strict bunker fuel verification protocols at the world's largest marine fuel hub. The city-state's ISO 17025-accredited laboratories process over 25,000 samples monthly from anchorage deliveries. Jurong Island's integrated petrochemical complex anchors captive testing capacity for export-oriented refineries.
United States
EPA Tier 3 gasoline sulfur surveillance mandates continuous analyzer deployment at Gulf Coast pipeline injection points. The US Gulf Coast refining corridor concentrates laboratory demand from Corpus Christi to Lake Charles. Houston's third-party service providers bundle sampling with digital custody transfer documentation for marine fuel trading.
Germany
The Federal Motor Transport Authority enforces diesel quality directives that sustain laboratory demand at ARA hub terminals. Frankfurt and Amsterdam Schiphol airports consolidate procurement around multi-year integrated service contracts for jet A-1 certification. Bavaria's automotive corridors generate sustained cetane index verification requirements for OEM powertrain development.
Brazil
National biofuel blend mandates under the RenovaBio program intensify fatty acid methyl ester authentication needs at ethanol terminals. The country's national petroleum regulator enforces sulfur specifications that outpace laboratory infrastructure expansion. São Paulo's fuel distributors accelerate handheld analyzer adoption where centralized testing remains inaccessible.
India
Bureau of Indian Standards mandates sulfur surveillance that strains laboratory capacity at expanding retail depot networks. The Petroleum and Natural Gas Regulatory Board enforces quality specifications across the country's fragmented distribution infrastructure. Gujarat's refining complexes and Maharashtra's logistics hubs concentrate demand for rapid field testing instrumentation.
Fuel Quality Testing Market Vendor Landscape
On the supply side, the industry is consolidating around integrated service providers with multi-jurisdictional accreditation capabilities. Testing volume leadership concentrates among firms with captive infrastructure at Singapore, Rotterdam, and Houston port clusters. Three archetypes dominate: diversified inspection conglomerates with marine fuel specialization, aviation-focused service integrators, and regional laboratory networks serving custody transfer liability. Competitive moves center on multi-year service contract consolidation and portable analyzer technology licensing.
Within the diversified inspection tier, SGS SA, Bureau Veritas, and Intertek Group plc exemplify scale-driven positioning. These firms occupy positions defined by geographic infrastructure density rather than technology differentiation. SGS SA anchors marine fuel verification through port cluster presence. Bureau Veritas represents integrated cargo inspection and laboratory analytics convergence. Intertek Group plc sits within aviation fuel farm service integration.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Applus+ |
| SGS SA |
| Veritas Petroleum Services |
| ALS Limited |
| Bureau Veritas |
| TÜV SÜD |
| MEG Corp |
| Intertek Group plc |
| Others |
Supply Flow & Price Mechanics
Overcapacity at European chromatography hardware manufacturers is compressing equipment margins and forcing extended warranty bundling, which in turn pushes service providers toward multi-year analytical contracts that lock in pricing stability against volatile reference material costs.
Pricing Analysis
Volume-discount tiering structures dominate fuel quality testing procurement, with three-tier pricing separating ISO 17025-accredited laboratory services from rapid field testing and basic screening kits. Price differentiation rests on certification grade and geographic delivery cost, as Singapore and Rotterdam port clusters command premiums for same-day bunker fuel verification. Pricing pressure stems from reference standard cost volatility tied to crude oil movements, squeezing mid-tier service providers. Fuel distributors at Indian and Brazilian retail depots exhibit highest price sensitivity, while aviation fuel farm operators at Frankfurt and Amsterdam Schiphol demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Extended payment terms from German and Japanese chromatography component suppliers are straining working capital for testing equipment assemblers, forcing supply-chain finance facilities at major port laboratory networks. Geographic supply concentration centers on Germany, Japan, and the United States for precision optical and detection components. Hardware production draws from specialized fused silica columns, electron multiplier detectors, and chemometric software licenses. Single-source vulnerability persists for gas chromatography-mass spectrometry ion source assemblies. Distribution runs through authorized distributor networks serving refinery complexes, third-party laboratories, and handheld analyzer deployers at remote fuel terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel quality testing represents a high-growth disruption as IMO 2020 sulfur enforcement fragments verification from centralized laboratories toward distributed bunkering terminals, permanently expanding addressable market scope beyond traditional refinery captive demand.
For Market Incumbents: Entrench position through backward integration into reference material production and captive certification of portable analyzer distribution networks. SGS SA and Bureau Veritas must defend against handheld spectrometer disruptors by embedding multi-year service contracts with blockchain-verified custody transfer documentation at Singapore and Houston marine fuel hubs. ISO 17025 accreditation investment across parallel EPA and EU regulatory scopes remains the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Indian and Brazilian retail fuel depot networks where laboratory infrastructure scarcity creates unmet demand for rapid sulfur screening. Portable near-infrared spectrometer deployment through equipment-leasing models offers the most penetrable entry path, bypassing capital-intensive laboratory buildouts. Partner with national petroleum regulators to secure preferred vendor status under enforcement intensification programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers bundling sampling, analysis, and digital certification at major aviation and marine fuel hubs. Long-term viability favors acquisition targets with multi-jurisdictional accreditation capabilities and established relationships with port authorities. Watch for inflection signals in hydrogen fuel quality protocol standardization under EU Hydrogen Strategy and Japan METI roadmaps, which will open new analytical service lines and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Portable Analyzer Technology Licensing | Enables rapid market entry into Indian and Brazilian retail depot networks lacking laboratory infrastructure. |
| Blockchain-Verified Certification Integration | Converges testing data with digital custody transfer platforms at Singapore and Houston marine fuel trading hubs. |
| Multi-Jurisdictional ISO 17025 Accreditation | Extends service provider reach across parallel EPA Tier 3 and EU marine fuel regulatory compliance markets. |
| Reference Material Backward Integration | Captures margin compression from certified sulfur and cetane calibration standard cost volatility. |
| Hydrogen Fuel Quality Protocol Development | Positions analytical service lines for EU Hydrogen Strategy and Japan METI fuel cell purity standard implementation. |
Methodological Framework
Initial hypotheses were tested against primary input from laboratory operations directors, marine fuel surveyors, aviation fuel farm managers, and chromatography equipment procurement leads and refined through secondary validation against customs trade data, EPA enforcement records, ISO 17025 accreditation registries, and SEC filings from diversified inspection conglomerates. Bottom-up demand modeling across testing method, end user, fuel type, and equipment type segments was triangulated with top-down market sizing from refinery throughput and bunkering port activity indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume expansion from IMO 2020 enforcement, biofuel blend mandate intensification, and aviation fuel farm modernization against laboratory capacity constraints and technician training pipeline limitations. Segmentation dimensions included testing method sophistication, custody transfer point in the value chain, fuel sulfur specification stringency, and equipment portability tier. CAGRs were derived from regression analysis of historical testing frequency trends against regulatory enforcement phase-in schedules and refinery capacity expansion patterns.
Sensitivities concentrate around IMO regulatory amendment timelines, biofuel authentication standard divergence between EU and California frameworks, and portable analyzer technology achieving laboratory-grade detection limits. Forecasts embody assumptions regarding sustained enforcement intensity at Singapore, Rotterdam, and Fujairah bunkering hubs and continued reference material cost volatility. Macroeconomic contraction reducing marine fuel trade volumes, regulatory relaxation of sulfur surveillance protocols, or breakthrough field-testing technology obsoleting chromatography methods would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Multifuel Gas Turbine Market
Fuels
Global Wood Gas Generator Market
Fuels
Emulsified Fuel Market
Fuels
Brazil LNG Market
Fuels
Hydrogen Cylinder Market
Fuels
Briquette Market
Fuels
Oil & Gas Lubricants Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Europe Coal Market
Fuels
Global Fuel Ethanol Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
LPG Vaporizer Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Gas Feed System Market
Fuels
Gasoline As a Fuel Market