
 Bituminous Coal Market | 2026-2036
Bituminous Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Bituminous Coal Market Analysis
EPA emissions standards under the Clean Air Act is recalibrating the cost-of-entry calculus for US bituminous coal producers, forcing capital allocation toward scrubber retrofits and low-sulfur seam development. Peabody Energy Corp leverages its Powder River Basin and Illinois Basin footprint to sustain long-haul supply contracts with Midwestern utilities. Arch Resources anchors its portfolio in metallurgical-grade output, competing directly with Australian and Canadian coking coal in Atlantic basin steel markets. Core Natural Resources Inc differentiates through integrated rail-to-port logistics, controlling terminal access at Hampton Roads and Mobile.
Bituminous coal is a dense, black sedimentary rock with carbon content ranging from 45% to 86% by weight, formed under moderate burial pressure and heat; its volatile matter content of 20% to 35% and calorific value of 24 to 35 MJ/kg make it suitable for both combustion and carbonization processes in power generation and iron-making. Steam coal for electricity generation occupies the largest volume share but faces structural decline in OECD markets as renewable dispatch and gas switching erode baseload burn. Metallurgical coal commands premium pricing and margin concentration, with steel mills in Asia driving import dependency for high-fluidity coking varieties. Thermal coal for industrial heating retains niche resilience in cement manufacturing and process industries where fuel switching costs remain prohibitive.
China's MEE enforces mining capacity caps and environmental restoration bonds that constrain domestic supply elasticity, while India's CEA mandates supercritical boiler standards that favor higher-calorific imported bituminous grades. The EU F-Gas Regulation and carbon border adjustment mechanism progressively tighten market access for unabated coal-intensive inputs, redirecting trade flows toward Asian demand centers. Stakeholders must monitor regulatory arbitrage between emissions trading systems and carbon border regimes to anticipate which supply corridors retain cost-competitive access to premium metallurgical segments.
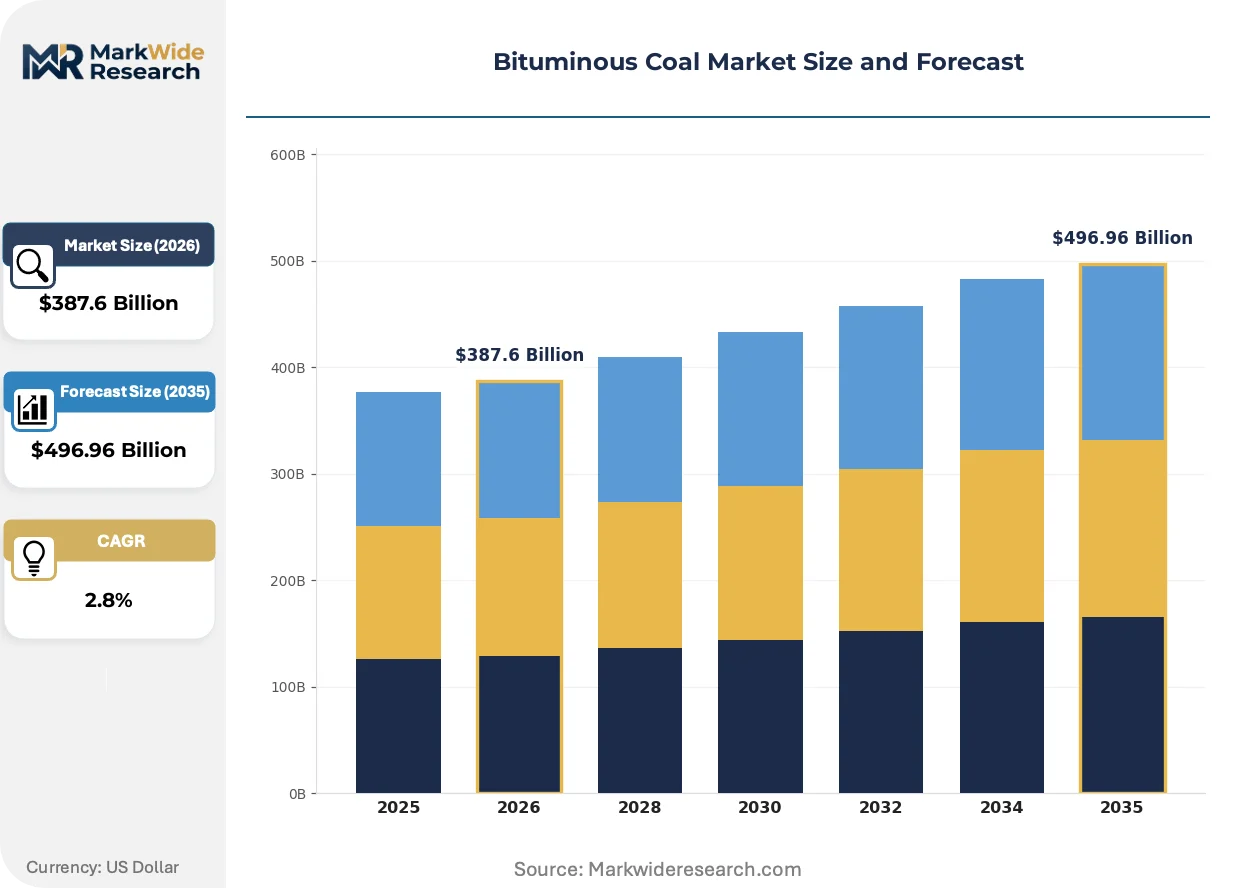
Market Dynamics
Blast furnace capacity expansion in India is recalibrating metallurgical coal trade flows, while China's dual carbon goals compress domestic mining output and redirect import dependency toward Australian and Mongolian supply corridors.
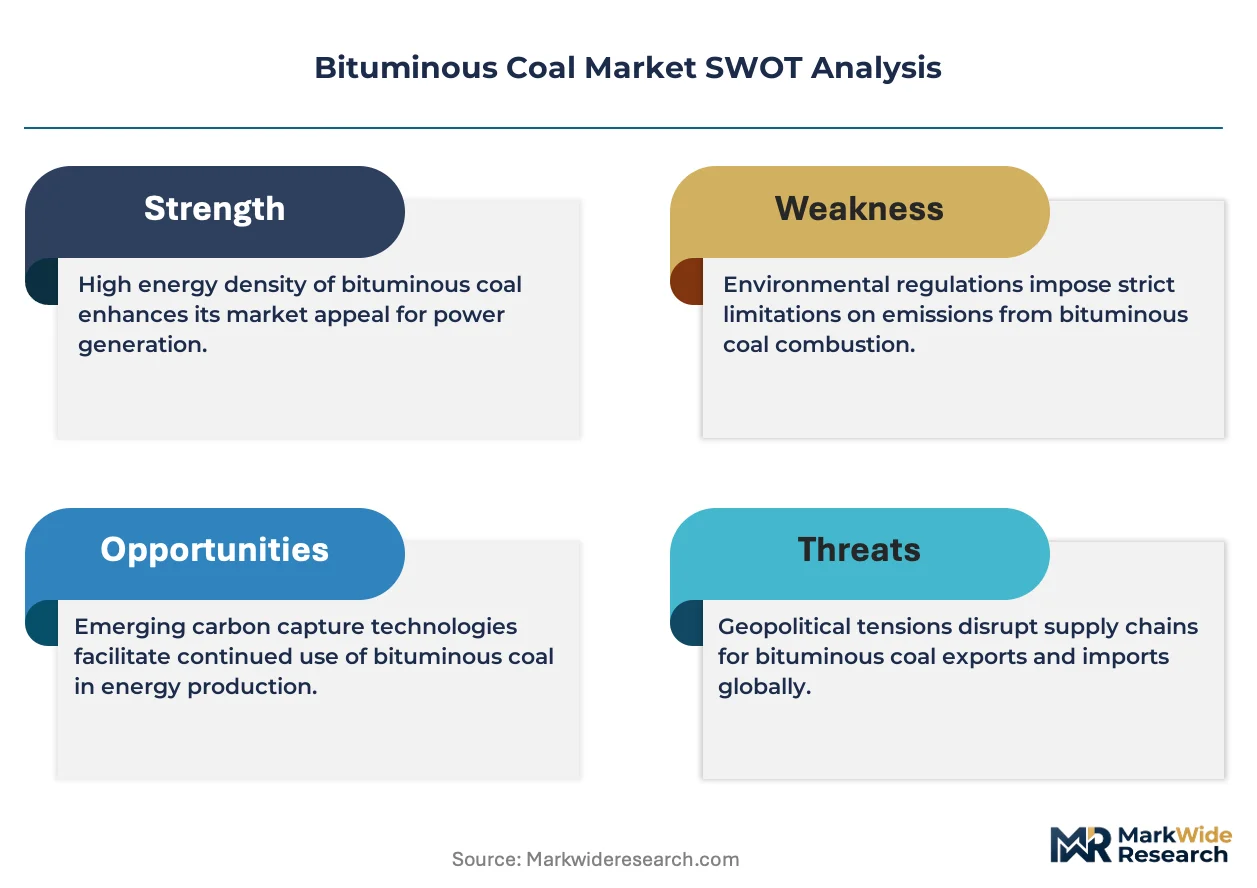
Growth Catalysts
- CEA supercritical mandates:India's Central Electricity Authority mandates supercritical boiler standards that favor higher-calorific imported bituminous grades, pulling premium thermal coal into national power procurement.
- Blast furnace commissioning:Steelmakers in India and Southeast Asia are expanding basic oxygen furnace capacity, anchoring metallurgical coal demand for high-fluidity coking varieties.
- Environmental restoration bonds:China's Ministry of Ecology and Environment enforces mining capacity caps that constrain domestic supply elasticity, opening import arbitrage for seaborne traders.
Market Restraints
- EU carbon border adjustment:The CBAM progressively tightens market access for unabated coal-intensive inputs, redirecting Atlantic basin cargoes toward Asian demand centers and compressing European offtake.
- Gas switching economics:Combined-cycle natural gas turbines in OECD power markets undercut thermal coal dispatch costs during peak renewable generation, eroding baseload burn volumes.
- Port concentration risk:Metallurgical coal export capacity concentrates at Dalrymple Bay and Hay Point in Queensland, creating single-point vulnerability for Atlantic basin steel mills.
Strategic Opportunities
- Mongolian rail expansion:New cross-border heavy-haul corridors to China's Gashun Sukhait border point offer alternative coking coal sourcing outside Australian supply dominance.
- CCUS retrofit integration:Post-combustion carbon capture retrofits at existing supercritical plants in South Korea and Japan create regulatory-compliant thermal coal demand extension.
- PLI scheme alignment:India's production-linked incentive schemes for specialty steel are pulling integrated primary steel capacity online, expanding metallurgical coal consumption per tonne of crude steel output.
Industry Challenges
- Geological modeling expertise:Reserve estimation for deep multi-seam deposits requires specialized geostatistical capabilities that mining engineering programs in producing regions are failing to replenish.
- Scrubber capex cycles:US EPA mercury and air toxics standards force capital allocation toward flue gas desulfurization retrofits at aging subcritical plants with uncertain remaining operational life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bituminous Coal Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $496.96 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Coal, Coking Coal, Thermal Coal, Metallurgical Coal Usage: Electricity Generation, Steel Production, Cement Manufacturing, Industrial Heating End User: Power Plants, Steel Mills, Manufacturing Units, Construction Companies Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Peabody Energy Corp, Core Natural Resources Inc, Arch Resources, Alliance Resource Partners, Alpha Metallurgical Resources Inc, NACCO Industries Inc, Shenhua Group, Vale S.A., Signal Peak Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bituminous Coal Market Emerging Trajectories
Operational technology deployment is fragmenting traditional mining economics, while regulatory emissions frameworks and buyer procurement recalibration are compressing long-term contracting conventions across supply corridors.
Autonomous haulage systems deployed by Rio Tinto and BHP at Queensland metallurgical coal operations are decentralizing pit-to-port logistics control. Mid-tier miners are adopting modular autonomous truck fleets without full-scale capital commitment. This technology is decentralizing production scheduling authority from centralized control rooms to distributed pit supervisors.
China's dual carbon goals under the 14th Five-Year Plan are hardening domestic mining capacity caps and import substitution timelines. The policy compresses allowable output from high-sulfur inland provinces while accelerating Mongolian and Russian import quotas. Metallurgical coal consumers in Jiangsu and Hebei are responding by diversifying coking coal blend formulations to accommodate lower-fluidity domestic grades.
Steel mill procurement departments are consolidating annual contract volumes and compressing spot market participation windows. Japanese and South Korean buyers are shifting from quarterly benchmark pricing toward monthly index-linked settlements with volume flexibility clauses. This pattern is most visible in the premium low-volatility hard coking coal segment serving POSCO and JFE Steel blast furnace operations.
Bituminous Coal Market Segmentation
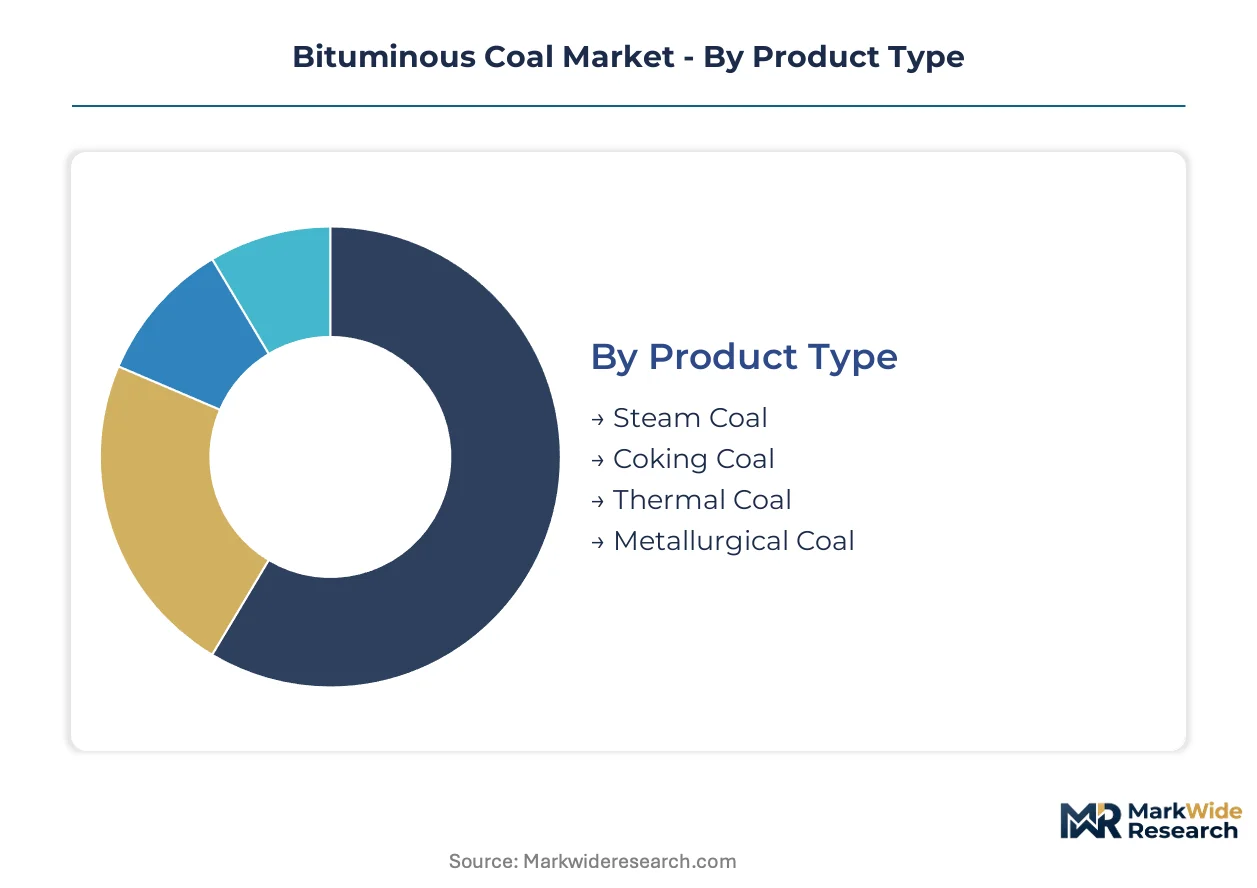
Segmentation in the bituminous coal market tracks how regulatory mandates and industrial upgrade cycles redirect procurement patterns across combustion, carbonization, and process heating applications. Each category isolates where capital expenditure concentrates as utilities and steelmakers recalibrate fuel sourcing strategies.
Product Type:
Upgrade cycles in power generation and steelmaking are recalibrating which coal specifications command procurement priority as utilities retire subcritical units and mills expand blast furnace capacity.
- Steam Coal:Lower-grade bituminous varieties with higher volatile matter content serve pulverized coal injection systems and industrial boilers. Demand concentrates in Indian power procurement under CEA supercritical mandates, though OECD utilities are accelerating phase-out timelines.
- Coking Coal:Metallurgical-grade material with specific plasticity and swelling indices enables coke oven battery operations. Steel mills in Jiangsu and Hebei provinces are diversifying blend formulations to accommodate lower-fluidity domestic grades amid import quota pressures.
- Thermal Coal:Mid-range calorific material supplies cement kilns and process industries where fuel switching costs remain prohibitive. Niche resilience persists in clinker production clusters.
- Metallurgical Coal:Premium low-volatility hard coking varieties command the highest per-tonne pricing. POSCO and JFE Steel procurement departments are compressing spot market participation windows in favor of index-linked annual contracts.
Steam coal sits at the top of the volume ranking, with metallurgical coal climbing the fastest as Asian blast furnace capacity expands.
Usage:
Application-specific demand patterns reveal where cost tiers separate baseload thermal consumption from premium metallurgical offtake.
- Electricity Generation:Supercritical and ultra-supercritical boiler fleets in India and Southeast Asia anchor thermal coal procurement. CEA mandates favor higher-calorific imported bituminous grades over domestic sub-bituminous supplies.
- Steel Production:Basic oxygen furnace operations consume high-fluidity coking varieties for coke production. Indian integrated mills are expanding capacity under PLI scheme alignment for specialty steel output.
- Cement Manufacturing:Rotary kiln operations require consistent calorific input for clinker formation. Fuel switching to alternative fuels progresses slowly due to process chemistry constraints.
- Industrial Heating:Process industries including chemicals and paper retain coal-fired boiler infrastructure where pipeline gas access remains limited. Regional price differentials against natural gas determine dispatch economics.
Electricity generation retains the largest volume footprint, with steel production gaining share fastest as Asian capacity commissioning accelerates.
End User:
Customer concentration patterns expose where procurement consolidation is compressing supplier negotiation leverage.
- Power Plants:Central and state-owned gencos dominate procurement through long-term fuel supply agreements. India's NTPC and Adani Power are locking in multi-year import contracts with Indonesian and Australian suppliers.
- Steel Mills:Integrated primary producers and merchant coke oven operators compete for seaborne metallurgical cargoes. Japanese and South Korean buyers are shifting from quarterly benchmark pricing toward monthly index-linked settlements.
- Manufacturing Units:Process industry captives maintain smaller spot market participation for seasonal demand spikes. Logistics cost sensitivity favors domestic sourcing where rail connectivity permits.
- Construction Companies:Limited direct coal procurement; primarily indirect consumption through steel and cement purchased for infrastructure projects. Demand fluctuates with public expenditure cycles.
Power plants command the largest procurement volumes, with steel mills expanding their share most steeply as blast furnace capacity multiplies.
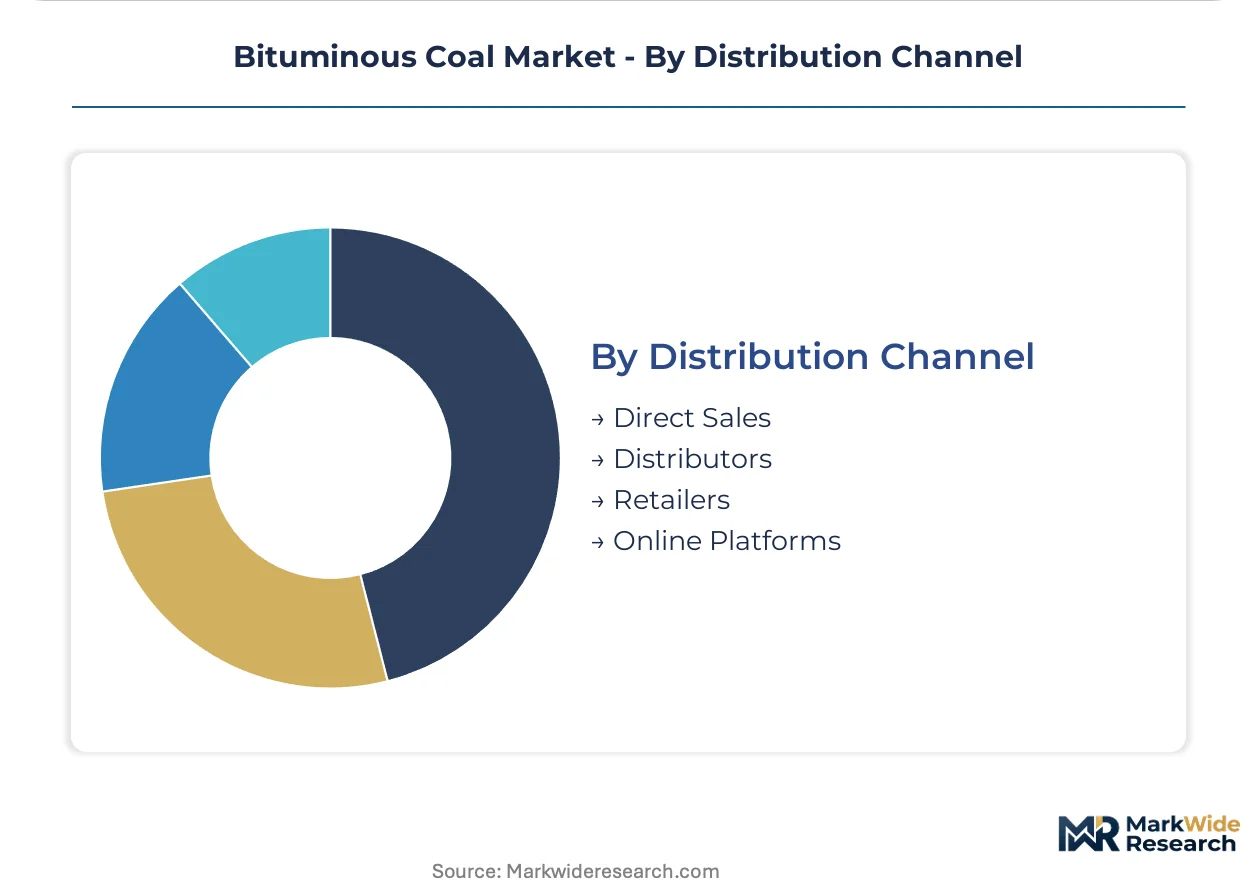
Distribution Channel:
Supply chain configuration determines where margin capture concentrates between producers and intermediaries.
- Direct Sales:Major mining houses contract directly with utility and steelmaker procurement departments. Peabody Energy and Arch Resources leverage long-haul rail contracts to sustain Midwestern utility relationships.
- Distributors:Regional traders aggregate smaller volumes for industrial consumers lacking direct mine access. Credit terms and inventory management services justify margin extraction.
- Retailers:Limited relevance in bulk commodity markets; primarily serve small-scale industrial and heating applications in fragmented geographies.
- Online Platforms:Emerging digital marketplaces for spot cargo trading remain nascent. Price transparency tools are displacing traditional broker relationships in seaborne cargo matching.
Direct sales dominate volume flows, with online platforms expanding most quickly as spot market digitization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining engineering programs in Queensland and New South Wales anchor the Asia-Pacific metallurgical coal supply base, while Appalachian geological expertise sustains North American coking coal output.
United States
Midwestern utility procurement and Atlantic basin metallurgical exports drive demand concentration. EPA mercury and air toxics standards force capital allocation toward scrubber retrofits at aging subcritical plants. The Powder River Basin and Illinois Basin sustain long-haul supply contracts with regional power generators.
Australia
Premium low-volatility hard coking coal exports to Japanese and South Korean steel mills anchor seaborne trade volumes. Queensland's Dalrymple Bay and Hay Point terminals concentrate export capacity for Atlantic basin customers. Autonomous haulage systems at BHP and Rio Tinto operations decentralize pit-to-port logistics control.
China
Jiangsu and Hebei province steel mills diversify coking coal blend formulations amid import quota pressures. The Ministry of Ecology and Environment enforces mining capacity caps that constrain domestic supply elasticity. Cross-border heavy-haul corridors to Gashun Sukhait border point expand Mongolian import arbitrage.
India
NTPC and Adani Power lock in multi-year import contracts under Central Electricity Authority supercritical mandates. Production-linked incentive schemes for specialty steel pull integrated primary steel capacity online. Blast furnace commissioning in Odisha and Chhattisgarh expands metallurgical coal consumption per tonne of crude steel output.
South Korea
POSCO procurement departments compress spot market participation windows in favor of index-linked annual contracts. Post-combustion carbon capture retrofits at existing supercritical plants create regulatory-compliant thermal coal demand extension. Monthly settlement pricing displaces quarterly benchmarks for premium hard coking coal cargoes.
Bituminous Coal Market Vendor Landscape
The competitive structure tilts toward integrated miners with captive rail-to-port logistics and metallurgical-grade portfolio concentration. Tier-one operators control terminal access at Hampton Roads and Queensland export hubs. Two strategic archetypes dominate: diversified resource majors with multi-basin thermal exposure, and pure-play metallurgical specialists competing in Atlantic basin steel markets. Capacity consolidation and scrubber capex cycles at aging subcritical plants represent the dominant competitive moves reshaping supplier positioning.
Among North American integrated miners, Peabody Energy Corp exemplifies the diversified thermal archetype through Powder River Basin and Illinois Basin footprint concentration. Arch Resources occupies a position within the metallurgical-specialist tier, competing directly with Australian and Canadian coking coal in seaborne steel markets. Core Natural Resources Inc represents the logistics-integrated model, controlling terminal access at Hampton Roads and Mobile to sustain long-haul supply relationships.
| Leading Market Players |
|---|
| Peabody Energy Corp |
| Core Natural Resources Inc |
| Arch Resources |
| Alliance Resource Partners |
| Alpha Metallurgical Resources Inc |
| NACCO Industries Inc |
| Shenhua Group |
| Vale S.A. |
| Signal Peak Energy |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and state-owned mining enterprises in India anchor supply discipline through production quota management, translating directly into pricing power for metallurgical grades and thermal contract premiums.
Pricing Analysis
Bundled long-term offtake contracts dominate premium metallurgical coal flows to Japanese and South Korean steel mills, while unbundled spot cargoes trade at volatile discounts to quarterly benchmarks. Price differentiation rests on fluidity indices and volatile matter specifications, with premium low-volatility hard coking coal commanding substantial premiums over standard grades. Pricing pressure stems from renewable dispatch eroding baseload thermal demand in OECD power markets. Merchant coke oven operators exhibit highest price sensitivity due to thin conversion margins, while integrated steel mills absorb cost volatility through captive coke capacity.
Supply Chain Analysis
Direct-to-steel-mill channels handle hyperscale metallurgical demand from POSCO and JFE Steel, bypassing trader intermediation for annual contract volumes. Geographic supply concentrates in Australia, Mongolia, and the United States, with Queensland's Dalrymple Bay and Hay Point terminals serving as critical export chokepoints. Raw material dependencies include diesel fuel for pit operations, ammonium nitrate explosives for overburden removal, and steel grinding media for preparation plants. Single-source vulnerability runs through concentrated Queensland port capacity, where weather disruptions or labor actions cascade through Atlantic basin steel supply schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement departments consolidating annual contract volumes around premium metallurgical specifications as blast furnace capacity expands across Asia.
For Market Incumbents: Lock in terminal access at Hampton Roads and Queensland export hubs to defend against logistics arbitrage from emerging Mongolian rail corridors. Prioritize scrubber retrofit completion at captive power assets before EPA enforcement windows tighten. Vertical integration into rail-to-port infrastructure preserves margin capture against trader intermediation.
For New Entrants and Emerging Players: Regional distributors with cement sector relationships offer the most penetrable channel for mid-grade thermal coal volumes excluded from utility procurement. Target industrial heating applications in process industries where pipeline gas access remains limited. Position around alternative fuel blending expertise to differentiate from commodity traders.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play metallurgical specialists with stranded Appalachian reserves and limited export terminal access. Long-term viability hinges on Asian blast furnace capacity retention against electric arc furnace substitution trends. Watch Mongolian rail expansion timelines as the critical inflection signal for Queensland supply dominance erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| CCUS Retrofit Integration | Post-combustion carbon capture at South Korean supercritical plants extends regulatory-compliant thermal coal demand. |
| Mongolian Rail Expansion | Cross-border heavy-haul corridors to Gashun Sukhait diversify coking coal sourcing outside Australian supply dominance. |
| Scrubber Capex Deployment | Flue gas desulfurization retrofits at aging US subcritical plants sustain operational life under EPA mercury standards. |
| PLI Scheme Alignment | India's production-linked incentive schemes for specialty steel expand metallurgical coal consumption per tonne of output. |
| Autonomous Haulage Adoption | Modular autonomous truck fleets at mid-tier Queensland operations decentralize pit-to-port logistics control. |
Methodological Framework
Coverage spans Asia-Pacific, North America, and Atlantic basin steel markets, with primary inputs from each region combined with secondary validation. Primary interviews engaged mining operations executives, utility procurement directors, steel mill fuel supply managers, and terminal logistics coordinators. Secondary sources include EIA thermal coal dispatch data, IEA energy outlooks, FERC generator fuel filings, and customs trade statistics. Bottom-up reserve estimates and top-down demand projections were triangulated to anchor volume forecasts.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include product type, end-use application, and regional regulatory framework. CAGRs were derived through regression analysis against steel production capacity commissioning schedules and power generation fuel mix transitions. Industry-specific inputs incorporate blast furnace operating rates and supercritical boiler deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to China's dual carbon policy enforcement intensity and European carbon border adjustment implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Storage Tank Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Briquette Market
Fuels
United States Bunker Fuel Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Gasoline Octane Improvers Market
Fuels
Global Turbine Oil Market
Fuels
Pyrolysis Gas Market
Fuels
South America Bunker Fuel Market
Fuels
Smart Gas Market
Fuels
India Retail Fuel Market