
 Industrial Fuel Filter Market | 2026-2036
Industrial Fuel Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fuel Filter Market Insights
ISO 4406 cleanliness code certification is collapsing the supplier base for high-pressure common-rail fuel systems. Donaldson Company leverages its vertically integrated media manufacturing to sustain pricing power in North American mining fleets. MANN+HUMMEL Group anchors European aftermarket distribution through captive service networks. Cummins Inc. differentiates by embedding filtration into integrated powertrain packages for stationary generators.
An industrial fuel filter mechanically separates particulate contaminants, water, and microbial growth from hydrocarbon fuels prior to combustion, typically achieving beta ratios of 1000 or greater at specified micron ratings to protect precision fuel injection components. Cartridge filters dominate OEM installations due to lower changeout labor and compact sump designs, while pleated filters capture margin pools in retrofit applications where space constraints are less severe. Mechanical filtration still leads volume shipments, though electrostatic filtration is gaining share in maritime bunkering where heavy fuel oil pretreatment demands higher water separation efficiency.
EPA Tier 4 Final and the EU F-Gas Regulation shape product roadmaps by mandating filtration performance that enables downstream emissions compliance, effectively raising the technical floor for market entry. The US FAA and Germany's KBA enforce parallel fuel system integrity standards in aviation and on-highway sectors that cascade into industrial equipment specifications. Stakeholders must monitor how ISO 4406 revision cycles and emerging alternative fuel compatibility requirements will redraw qualification boundaries for filter media suppliers.
Market Dynamics
ISO 4406 cleanliness certification is compressing the supplier base for high-pressure common-rail fuel systems, forcing media manufacturers to consolidate or exit as technical barriers harden.
Growth Catalysts
- EPA Tier 4 Final mandates:Diesel genset operators in the United States must install finer particulate capture systems, accelerating replacement cycles across stationary power fleets.
- Mining fleet expansion:Australian and Chilean extraction operations are extending filtration replacement schedules to protect injection components in remote operating conditions.
- Electrostatic filtration:Maritime bunkering applications for heavy fuel oil pretreatment are pulling this technology into industrial fuel conditioning systems.
Market Restraints
- Specialized cellulose and synthetic media costs:Raw material volatility for multi-layer pleated constructions constrains margin flexibility at the component level.
- Vertically integrated media manufacturing:Captive supply chains among North American filtration specialists limit third-party supplier entry into OEM specifications.
- EU Stage V compliance friction:The transition timeline for off-road diesel equipment is compressing qualification windows for non-integrated filter suppliers.
Strategic Opportunities
- India power generation sector:Diesel genset operators face tightening emissions enforcement, creating aftermarket retrofit demand for cartridge filter upgrades.
- Alternative fuel compatibility:Biodiesel and renewable diesel blends require modified elastomer and media specifications, opening qualification races for adaptive suppliers.
- Aviation-to-industrial technology transfer:Water separation standards enforced by the US FAA for jet fuel systems are cascading into stationary turbine fuel conditioning specifications.
Industry Challenges
- ISO 4406 revision cycle alignment:Filter media suppliers must synchronize R&D pipelines with unpredictable cleanliness code updates to maintain certification validity.
- Common-rail injection protection expertise:The talent pool for high-pressure fuel system contamination control remains concentrated among legacy automotive suppliers, constraining industrial specialist hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fuel Filter Market |
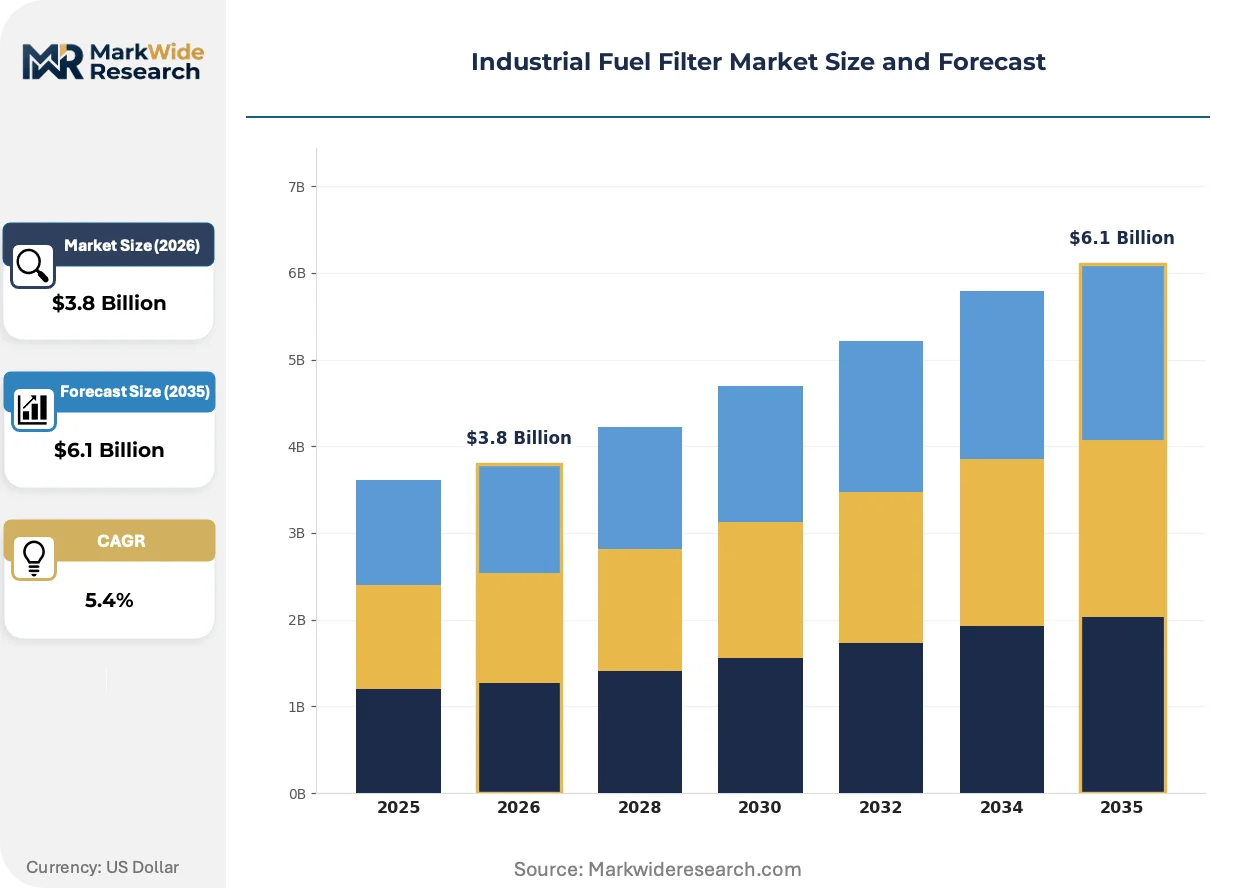
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-on Filters, Cartridge Filters, Magnetic Filters, Pleated Filters Filtration Technology: Mechanical Filtration, Electrostatic Filtration, Centrifugal Filtration, Depth Filtration Application: Power Generation, Construction Equipment, Maritime Vessels, Agricultural Machinery End User Industry: Mining Operations, Heavy Machinery Rentals, Energy Producers, Equipment Maintenance Services |
| Companies Covered | Donaldson Company, Inc., MANN+HUMMEL Group, MAHLE GmbH, Clarcor Inc., Cummins Inc., Sogefi SpA, Hengst SE & Co. KG, Parker Hannifin Corporation, Ahlstrom Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fuel Filter Market Trends and Innovations
Filtration technology is splitting between legacy mechanical separation and advanced electrostatic conditioning, with regulatory emissions mandates forcing convergence at the system integration level.
Nanofiber surface-loading media is bifurcating the cartridge filter segment. This technology captures sub-micron particulates without depth-loading penalties, enabling extended service intervals. Gas turbine operators in Germany and the United States are specifying nanofiber layers for critical fuel conditioning skids. The structural consequence is compressing commodity cellulose suppliers into price-driven retrofit channels while premium positions consolidate around certified nanofiber formulations.
REACH chemical substance restrictions are reshaping elastomer compound selection for filter seals and gaskets. The regulation limits certain plasticizers and stabilizers used in nitrile and fluorocarbon formulations, forcing reformulation cycles. Filter manufacturers serving EU Stage V equipment must validate alternative compounds without compromising fuel compatibility or temperature performance, extending product development timelines.
Power generation operators are unbundling filtration service from bundled maintenance contracts. Large diesel genset fleets in India and the United States are negotiating direct filter supply agreements, bypassing traditional distributor markups. This disintermediation pressures captive service networks to demonstrate value-add beyond product delivery, compressing aftermarket margin pools for non-specialized distributors.
Industrial Fuel Filter Market Segmentation
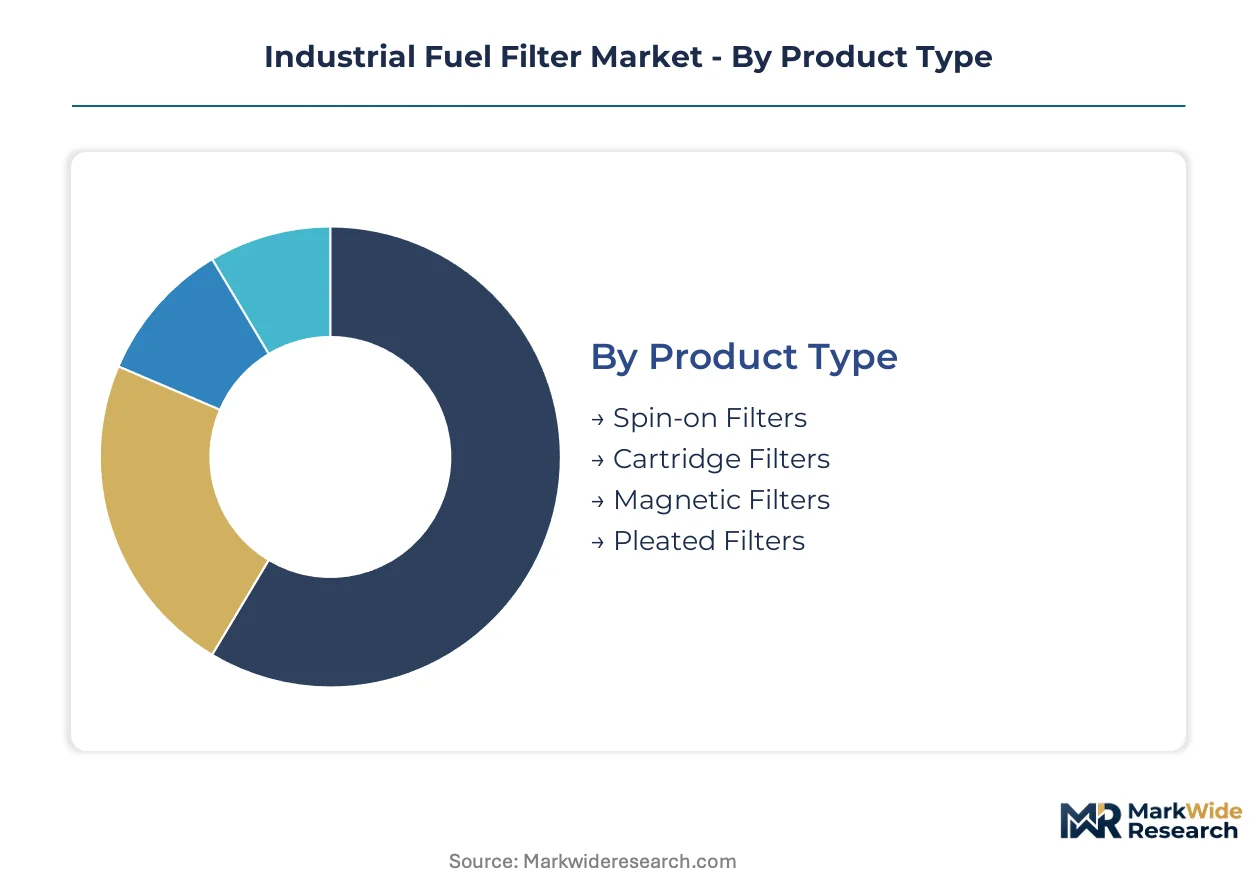
Segmentation in the industrial fuel filter market reveals how technical specifications diverge across operating environments. Equipment operators select filtration architectures based on contamination profiles, service accessibility, and regulatory exposure rather than unit cost alone.
Product Type:
Cartridge filters face the most acute substitution pressure from pleated designs in retrofit channels, while spin-on formats defend OEM installed base through integrated sump geometries.
- Cartridge Filters:Compact sump designs with lower changeout labor requirements dominate OEM installations for stationary diesel gensets. Demand concentrates in United States power generation fleets where EPA Tier 4 Final mandates accelerate replacement cycles for finer particulate capture.
- Spin-on Filters:Self-contained housings with integrated seals simplify field service in remote mining operations. Australian and Chilean extraction fleets specify these for rapid turnaround where technician availability is constrained.
- Pleated Filters:Greater media surface area captures margin pools in retrofit applications where space constraints are less severe.
- Magnetic Filters:Ferrous particle pre-filtration extends downstream element life in heavy fuel oil conditioning systems.
Cartridge filters anchor the volume base while pleated filters gain share at the steepest rate.
Filtration Technology:
Cost tier stratification separates commodity mechanical systems from premium electrostatic installations, with centrifugal formats occupying mid-tier positions in maritime bunkering.
- Mechanical Filtration:Depth-loading cellulose and synthetic media still lead volume shipments across construction and agricultural equipment. German gas turbine operators specify multi-layer pleated constructions for critical fuel conditioning skids where ISO 4406 cleanliness codes mandate beta ratios of 1000 or greater.
- Electrostatic Filtration:Charged particle separation achieves higher water removal efficiency without consumable media replacement. Maritime bunkering applications for heavy fuel oil pretreatment in international shipping lanes pull this technology into industrial fuel conditioning specifications.
- Centrifugal Filtration:Rotational force separation handles high-solids loading in mining hydraulic systems without filter element consumption.
- Depth Filtration:Gradient density media provides progressive contaminant capture for biodiesel blends with elevated particulate content.
Mechanical filtration retains the largest installed base while electrostatic systems climb the fastest on maritime emissions compliance requirements.
Application:
Customer type fragmentation splits procurement between capital-intensive fleet operators and rental-driven equipment pools with divergent service strategies.
- Power Generation:Continuous-duty diesel gensets and gas turbines demand the highest cleanliness specifications. Indian operators face tightening emissions enforcement from the Central Electricity Authority, creating aftermarket retrofit demand for cartridge filter upgrades in distributed generation fleets.
- Maritime Vessels:Heavy fuel oil bunkering and distillate conditioning for auxiliary engines drive water separation requirements. The US FAA fuel system integrity standards for aviation are cascading into stationary turbine specifications, elevating technical floors for maritime suppliers.
- Construction Equipment:Intermittent operation with high shock loading favors robust spin-on formats in rental fleets.
- Agricultural Machinery:Seasonal use patterns with extended storage periods prioritize microbial growth prevention in filter media selection.
Power generation anchors the revenue base while maritime applications expand most quickly on international sulfur cap compliance.
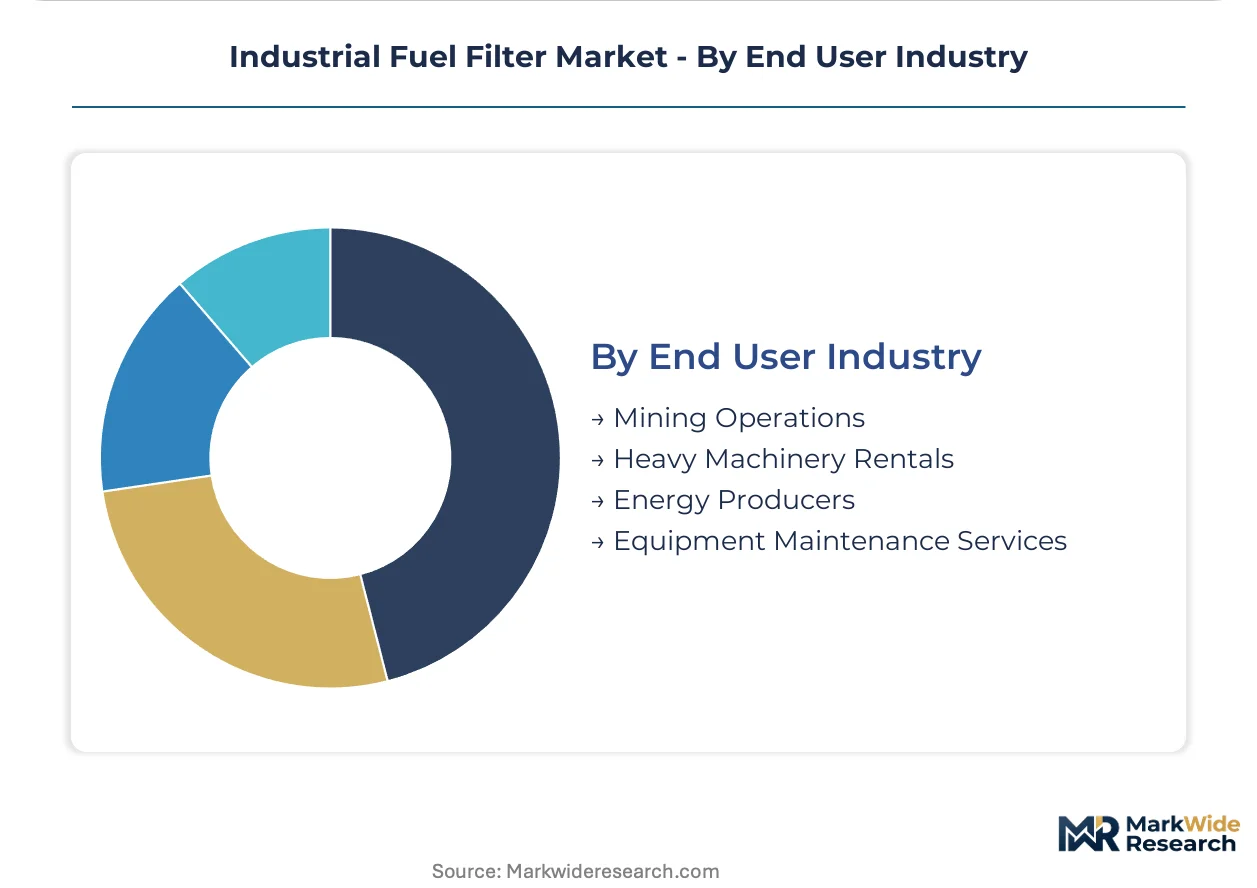
End User Industry:
Supply concentration among vertically integrated media manufacturers shapes procurement leverage differently across captive maintenance networks and independent service providers.
- Mining Operations:Remote operating conditions in Australian and Chilean extraction sites demand extended service intervals and rapid filter changeout protocols. Fleet operators negotiate direct supply agreements, bypassing traditional distributor markups and compressing aftermarket margin pools for non-specialized channels.
- Energy Producers:Combined-cycle gas turbine and diesel genset operators in Germany and the United States unbundle filtration service from bundled maintenance contracts. These large fleets specify nanofiber surface-loading media for critical fuel conditioning skids, consolidating premium positions around certified formulations.
- Heavy Machinery Rentals:High equipment utilization rates with multiple operators drive standardized spin-on specifications for service simplicity.
- Equipment Maintenance Services:Third-party service providers face margin pressure as end users internalize filter procurement.
Mining operations anchor the volume base while energy producers gain share at the steepest rate on emissions-driven upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power generation operators and mining fleet managers concentrate procurement leverage in the United States, Germany, and India, with maritime bunkering and gas turbine maintenance driving secondary demand clusters in specialized coastal corridors.
United States
EPA Tier 4 Final mandates force diesel genset operators into accelerated replacement cycles for finer particulate capture systems. The FAA enforces fuel system integrity standards that cascade into stationary turbine specifications. Texas and California power generation clusters specify nanofiber surface-loading media for critical fuel conditioning skids.
Germany
Combined-cycle gas turbine operators unbundle filtration service from bundled maintenance contracts to negotiate direct supply agreements. The KBA enforces parallel fuel system standards that elevate technical floors for industrial equipment specifications. Bavaria and North Rhine-Westphalia anchor European aftermarket distribution through captive service networks.
India
Diesel genset operators face tightening emissions enforcement from the Central Electricity Authority, creating aftermarket retrofit demand for cartridge filter upgrades. BIS certification requirements for industrial filtration components compress qualification windows for non-integrated suppliers. Maharashtra and Gujarat distributed generation fleets drive volume demand in distributed power clusters.
Australia
Remote mining operations in Western Australia and Queensland extend filtration replacement schedules to protect injection components in harsh operating conditions. The country's national mining safety regulator mandates equipment reliability standards that elevate preventive maintenance protocols. Perth and Brisbane serve as procurement hubs for extraction fleet filtration contracts.
Chile
Copper extraction operations in the Atacama Desert specify spin-on formats for rapid turnaround where technician availability is constrained. The national environmental regulator enforces emissions compliance for off-road diesel equipment in mining concessions. Antofagasta and Santiago metropolitan areas concentrate fleet maintenance infrastructure for northern extraction sites.
Industrial Fuel Filter Market Competitive Landscape
Player mix skews toward vertically integrated filtration specialists with captive media manufacturing capabilities. The supplier base compresses around ISO 4406 cleanliness certification holders as technical barriers harden for high-pressure common-rail fuel systems. Two strategic archetypes dominate: integrated powertrain bundlers and standalone aftermarket distributors. Competitive moves center on backward integration into synthetic media production and geographic expansion into Indian and Australian mining procurement channels.
Within the integrated filtration tier, Donaldson Company and MANN+HUMMEL Group exemplify vertically integrated specialists with North American and European captive supply chains respectively. Cummins Inc. occupies a distinct position as a powertrain integrator embedding filtration into bundled generator packages. These three anchors represent how certification-holding manufacturers with in-house media production sustain pricing power against commodity cellulose competitors.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| MANN+HUMMEL Group |
| MAHLE GmbH |
| Clarcor Inc. |
| Cummins Inc. |
| Sogefi SpA |
| Hengst SE & Co. KG |
| Parker Hannifin Corporation |
| Ahlstrom Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with cellulose and synthetic media suppliers lock in multi-year price visibility for North American filtration specialists while insulating them from raw material volatility that compresses margin flexibility at the component level. These arrangements bind OEM procurement teams to certified nanofiber formulations at predetermined indexation rates, creating asymmetric pricing power for vertically integrated manufacturers against commodity pleated-filter competitors.
Pricing Analysis
Cost-plus contracts with cellulose pulp and synthetic fiber indexation dominate procurement between media manufacturers and mining fleet operators across Australia and Chile. Price differentiation separates ISO 4406-certified nanofiber cartridges from uncertified cellulose retrofit elements, with premium tiers commanding sustained margins through EPA Tier 4 Final and EU Stage V compliance bundling. Cost compression in the standard tier is intensifying because third-party suppliers face compressed qualification windows and captive service network exclusion. Rental fleet operators in construction equipment prove most price-sensitive due to standardized spin-on specifications and high equipment turnover, while German gas turbine operators demonstrate least sensitivity given continuous-duty cleanliness mandates.
Supply Chain Analysis
Inbound logistics costs from German and US Gulf Coast ports constrain just-in-time delivery for nanofiber media formulations to Indian power generation clusters. Geographic supply concentration centers on Germany for multi-layer pleated constructions, the United States for vertically integrated cartridge production, and China for cellulose substrate refining. Raw material dependencies draw from specialized cellulose pulp, electrostatic charging substrates, and REACH-compliant elastomer compounds. Single-source vulnerability runs through certified nanofiber media suppliers holding ISO 4406 validation. Distribution runs through captive service networks in Europe and direct supply agreements in North American mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial fuel filtration operates as a defensive-moat market where regulatory entrenchment through ISO 4406 certification cycles creates structural barriers that compound over successive compliance phases. Switching costs for high-pressure common-rail fuel systems lock fleet operators into validated supplier relationships with multi-year qualification timelines.
For Market Incumbents: Shield pricing power by deepening backward integration into synthetic nanofiber media production and accelerating certification investment ahead of ISO 4406 revision cycles. Consolidate channel control through captive service network expansion in Australian mining procurement corridors to counter disintermediation pressure from direct supply agreements. For New Entrants and Emerging Players: Anchor in India's distributed diesel genset retrofit segment where tightening Central Electricity Authority enforcement creates aftermarket cartridge upgrade demand without entrenched incumbent relationships. Pursue alternative fuel compatibility qualification as the primary go-to-market angle, targeting biodiesel blend specifications that require modified elastomer and media formulations. For Investors and Strategic Acquirers: Regional nanofiber specialists with captive ISO 4406 certification and established mining fleet contracts represent the most defensible acquisition profile for portfolio exposure to emissions-driven replacement cycles. Long-term viability hinges on regulatory trajectory durability across multiple compliance phases rather than cyclical capital expenditure patterns. Monitor EU Stage V and EPA Tier 4 Final enforcement intensity as the critical inflection signal for aftermarket demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Media Production | Captive nanofiber manufacturing secures ISO 4406 certification continuity against supply disruption. |
| Alternative Fuel Compatibility Certification | Biodiesel and renewable diesel validation opens qualification races ahead of incumbent reformulation cycles. |
| Direct Supply Agreement Expansion | Bypassing distributor markups captures margin pools in Indian and US power generation fleet procurement. |
| Captive Service Network Densification | Integrated maintenance bundling defends against unbundling pressure from large diesel genset operators. |
| Aviation-to-Industrial Technology Transfer | FAA-enforced water separation standards cascade into stationary turbine specifications, elevating technical floors. |
Research Methodology
Cross-validation between primary interviews with maintenance directors at Australian mining operations and secondary validation through EPA enforcement databases anchors the qualitative findings on replacement cycle acceleration. Plant engineers at German gas turbine facilities, OEM procurement teams at US power generation equipment manufacturers, aftermarket service heads at Indian diesel genset distributors, and filtration media R&D directors provided operational perspective. Secondary sources include SEC 10-K filings from vertically integrated suppliers, customs trade data on cellulose and synthetic fiber imports, ISO 4406 certification registries, and Central Electricity Authority emissions enforcement records. Bottom-up unit shipment estimates triangulate against top-down fuel consumption modeling by application segment.
Sensitivity analysis across cellulose pulp price volatility scenarios, ISO 4406 revision timing assumptions, and alternative fuel blend penetration rates tests forecast robustness throughout the projection horizon. The analytical framework segments by product type, filtration technology, application, and end user industry, with additional modeling on certification tier and geographic regulatory cluster. CAGRs derive from replacement cycle frequency projections tied to emissions enforcement intensity and fleet expansion patterns in named extraction corridors. Industry-specific inputs include mining fleet utilization rates and gas turbine fuel conditioning skid specifications.
Decision-makers should treat outputs as directional under sustained EPA Tier 4 Final and EU Stage V enforcement assumptions; material deviation in regulatory implementation timelines or alternative fuel adoption curves would warrant model refresh. Specific risk factors include REACH chemical substance restriction expansion, raw material supply disruption from cellulose pulp market concentration, and electrostatic filtration technology displacement of mechanical formats in maritime bunkering. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Black and Wood Pellets Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Aviation Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
India Retail Fuel Market
Fuels
Coal Briquette Box Market
Fuels
Fuel Oxygenate Market
Fuels
Brazil LNG Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Oil Dispensing Stations Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Japan Bunker Fuel Market
Fuels
Global Fuel Ethanol Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Mobile Fuel Delivery Market