
 Wood Charcoal Market | 2026-2036
Wood Charcoal Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Charcoal Market Outlook
Restaurant and foodservice procurement of lump charcoal is decoupling from traditional household buying patterns as commercial kitchens prioritize consistent heat output and flavor neutrality. Kingsford Products Company leverages its retail channel density to sustain dominance in the North American grocery segment. PyroWood Products anchors its position through specialized hardwood sourcing relationships that ensure uniform carbonization. TimberChar Industries competes in European markets with kiln technologies that meet stringent emission protocols.
Wood charcoal consists of carbonized hardwood or softwood biomass produced through controlled pyrolysis at temperatures between 400°C and 700°C in oxygen-limited environments, yielding a porous carbon matrix with fixed carbon content typically exceeding 75 percent and ash residues below 5 percent. Its primary commercial purpose spans metallurgical reduction, water filtration media, soil amendment, and thermal fuel for cooking and heating applications. Lump charcoal commands premium positioning in the product type dimension due to minimal binder content and superior combustion characteristics, while activated charcoal extracts the highest margin pools through healthcare and cosmetics applications. Briquettes occupy the volume-heavy household segment where packaging standardization and retail distribution efficiency determine competitive outcomes.
The EPA regulates kiln emissions under Clean Air Act provisions for particulate matter and volatile organic compounds, while the EU Green Deal's deforestation-free supply chain requirements reshape import sourcing for European processors. Brazil's environmental licensing framework and Indonesia's sustainable forest management certifications increasingly determine market access for tropical hardwood-derived charcoal. Stakeholders must monitor evolving carbon border adjustment mechanisms and traceability mandates that will reshape procurement geography and production technology investments.
Market Dynamics
Restaurant and foodservice procurement of lump charcoal is decoupling from traditional household buying patterns as commercial kitchens prioritize consistent heat output and flavor neutrality over cost minimization. This structural shift is compressing the premium segment while fragmenting the volume-heavy household tier.
Growth Catalysts
- Street food commercialization:Southeast Asian urban centers are driving commercial charcoal consumption through vendor density and municipal food zone licensing.
- EU Green Deal deforestation-free mandates:Import sourcing requirements are accelerating traceability investments among European processors seeking compliant tropical hardwood supply chains.
- Pyrolysis automation:Kiln temperature control systems are expanding fixed carbon yields above 75 percent while reducing volatile organic compound emissions.
Market Restraints
- Hardwood supply concentration:Tropical hardwood sourcing relationships concentrate among Brazilian and Indonesian suppliers, exposing buyers to licensing delays.
- Emission compliance costs:Brazil's environmental licensing framework for kiln particulate matter is raising production thresholds for small-scale carbonizers.
- Electrification substitution:Induction and infrared cooking technologies are displacing charcoal in institutional catering contracts across developed markets.
Strategic Opportunities
- Soil amendment applications:Biochar integration into agricultural carbon credit schemes is opening premium pricing channels for pyrolysis byproducts.
- Water filtration media:Activated charcoal demand from municipal treatment facilities is outpacing traditional metallurgical offtake in select Asian markets.
- Direct-to-restaurant distribution:Bypassing retail grocery channels allows lump charcoal producers to capture margin from chef-specified procurement.
Industry Challenges
- Carbonization skill scarcity:Traditional kiln operators lack training in automated pyrolysis systems, constraining yield consistency at scale.
- Certification timeline compression:Sustainable forest management certifications from Indonesia's Ministry of Environment require 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Charcoal Market |
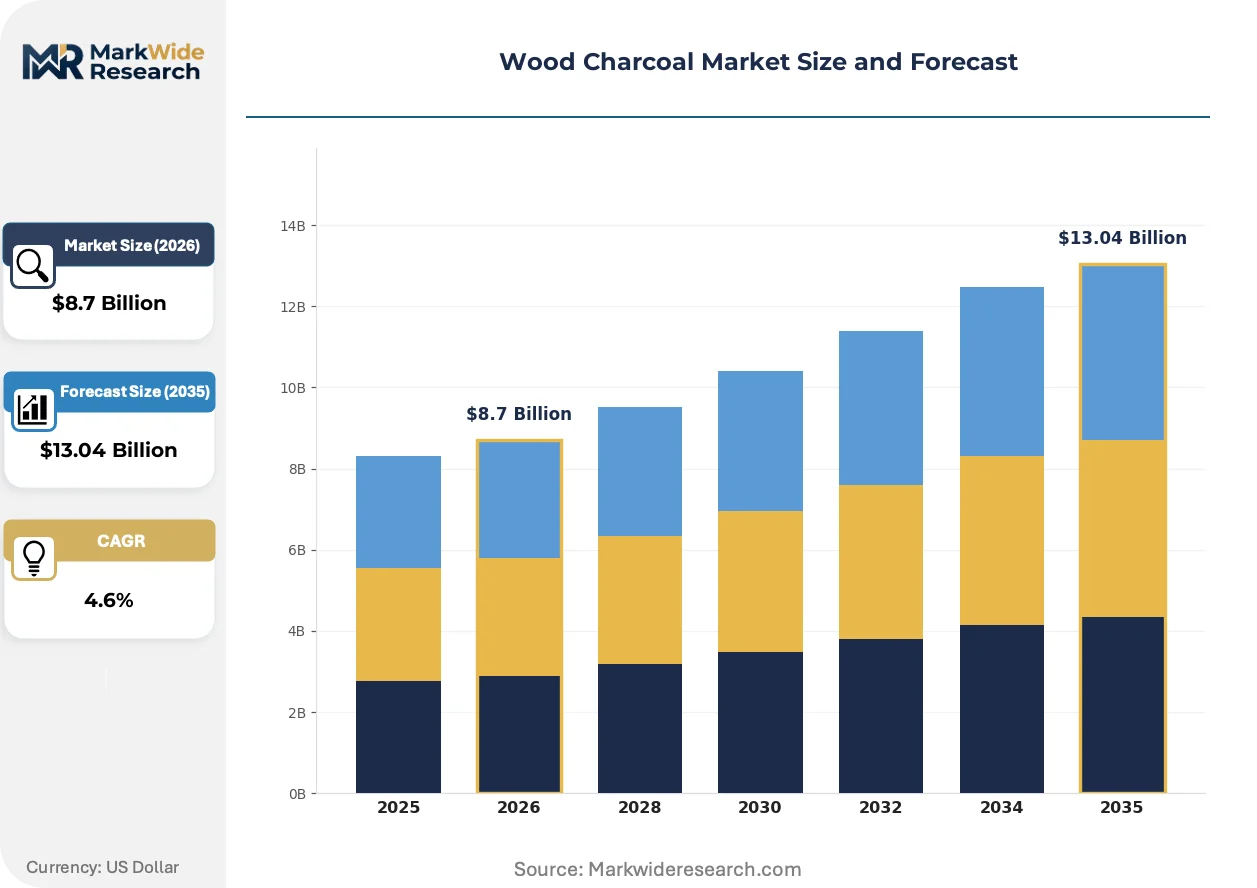
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Charcoal, Briquettes, Lump Charcoal, Powdered Charcoal Application: Food & Beverage, Cosmetics, Healthcare, Industrial End User: Households, Restaurants, Retailers, Distribution Centers Packaging Type: Bags, Cartons, Bulk Containers, Other |
| Companies Covered | TimberChar Industries, PyroWood Products, Kingsford Products Company, HardwoodEmber Group, CarbonBlaze Manufacturing, Royal Oak Enterprises, ForestFuel Co., Haycarb PLC, Duraflame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Charcoal Market Strategic Shifts
Controlled pyrolysis technologies are reshaping production economics while regulatory traceability mandates and procurement model fragmentation are compressing legacy channel structures across both household and commercial segments.
Retort kiln systems with continuous carbonization capability are consolidating market share among mid-scale producers seeking emission compliance without batch-processing inefficiencies. Restaurant chains and catering cooperatives are adopting these systems to secure supply chain control. The technology is consolidating production geography around industrial zones with established environmental permitting.
REACH substance registration requirements for charcoal dust and EU Green Deal deforestation-free supply chain documentation are reshaping import sourcing protocols for European processors. Compliance costs are filtering smaller traders from the market. Metallurgical-grade charcoal contracts are most affected, with buyers demanding batch-level origin certificates.
Chef-specified procurement is displacing centralized foodservice purchasing for premium lump charcoal in North American and European urban markets. Independent restaurants are forming buying cooperatives to secure direct mill relationships. This pattern is most visible in barbecue-centric metropolitan clusters where flavor differentiation commands menu pricing power.
Wood Charcoal Market Segmentation
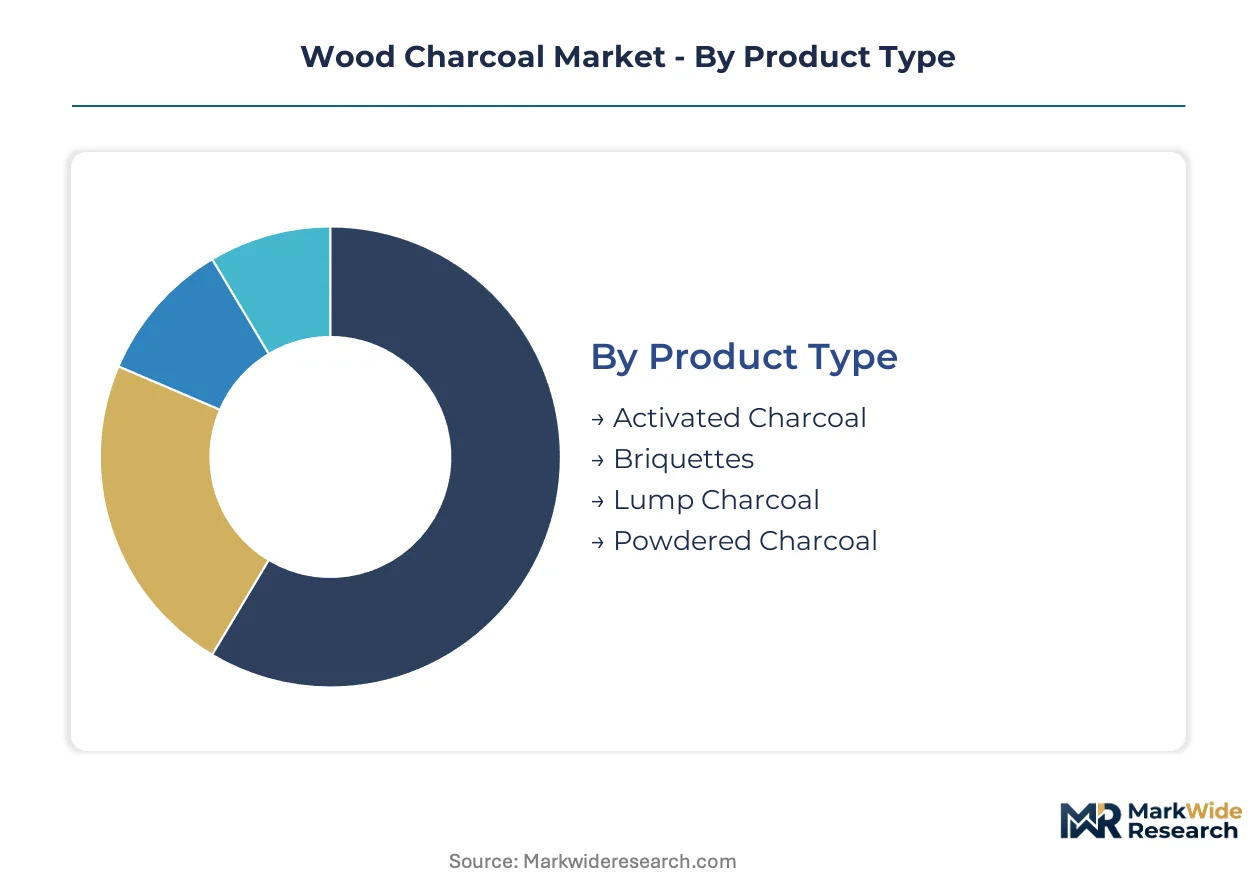
Wood charcoal segmentation reveals divergent margin structures across product types and sharply contrasting procurement patterns between household and commercial channels. Understanding these divides enables targeted positioning for premium extraction versus volume capture.
Product Type:
Integration depth varies dramatically: activated charcoal embeds into complex downstream formulations, while lump charcoal and briquettes serve as standalone thermal fuels with minimal processing requirements.
- Lump Charcoal:Carbonized hardwood chunks retain natural lignin structures and volatile compounds that deliver distinct flavor profiles. Restaurant procurement in Southeast Asian urban centers and North American barbecue markets prioritizes consistent heat output over cost minimization, decoupling from household buying patterns.
- Activated Charcoal:Steam-activated or chemically activated carbon achieves surface areas exceeding 500 m²/g through controlled oxidation. Municipal water treatment facilities in select Asian markets and healthcare formulators drive demand, extracting the highest margin pools through purification and detoxification applications.
- Briquettes:Compressed charcoal fines with starch binders standardize combustion duration for retail grocery channels.
- Powdered Charcoal:Finely milled carbon serves metallurgical reduction and soil amendment applications with minimal processing overhead.
Briquettes lead volumes today; activated charcoal is gaining share fastest.
Application:
Cost tier stratification separates commodity thermal fuel from specialized functional materials, with healthcare and cosmetics commanding 3-5x unit economics over industrial reduction.
- Industrial:Metallurgical reduction in iron and steel foundries demands high fixed carbon content above 75 percent and controlled ash chemistry. Brazilian and Indonesian supply relationships concentrate among established carbonizers with sustainable forest management certifications.
- Healthcare:Medical-grade activated charcoal meets pharmacopeia standards for toxin adsorption in emergency medicine and dialysis applications. Regulatory validation cycles through FDA and EMA pathways create multi-year qualification barriers for new suppliers.
- Food & Beverage:Filtration and decolorization applications span sugar refining, alcoholic beverage clarification, and cooking fuel.
- Cosmetics:Activated carbon integrates into skincare formulations for oil absorption and purification claims.
Industrial applications anchor volume; healthcare shows the steepest expansion trajectory.
End User:
Customer type fragmentation splits procurement between centralized retail distribution and direct commercial relationships, with restaurants forming buying cooperatives to bypass traditional channels.
- Restaurants:Chef-specified procurement in barbecue-centric metropolitan clusters prioritizes hardwood provenance and flavor neutrality. Independent establishments in North American and European urban markets secure direct mill relationships, capturing margin from specification control.
- Households:Price-sensitive consumers purchase through grocery retail where Kingsford's channel density dominates shelf placement. Weekend grilling occasions drive seasonal demand concentration with minimal brand loyalty.
- Retailers:Supermarket and home improvement chains intermediate volume-heavy briquette sales with standardized packaging requirements.
- Distribution Centers:Foodservice wholesalers aggregate procurement for institutional catering contracts facing electrification substitution pressure.
Households dominate unit volumes; restaurants are climbing the fastest.
Packaging Type:
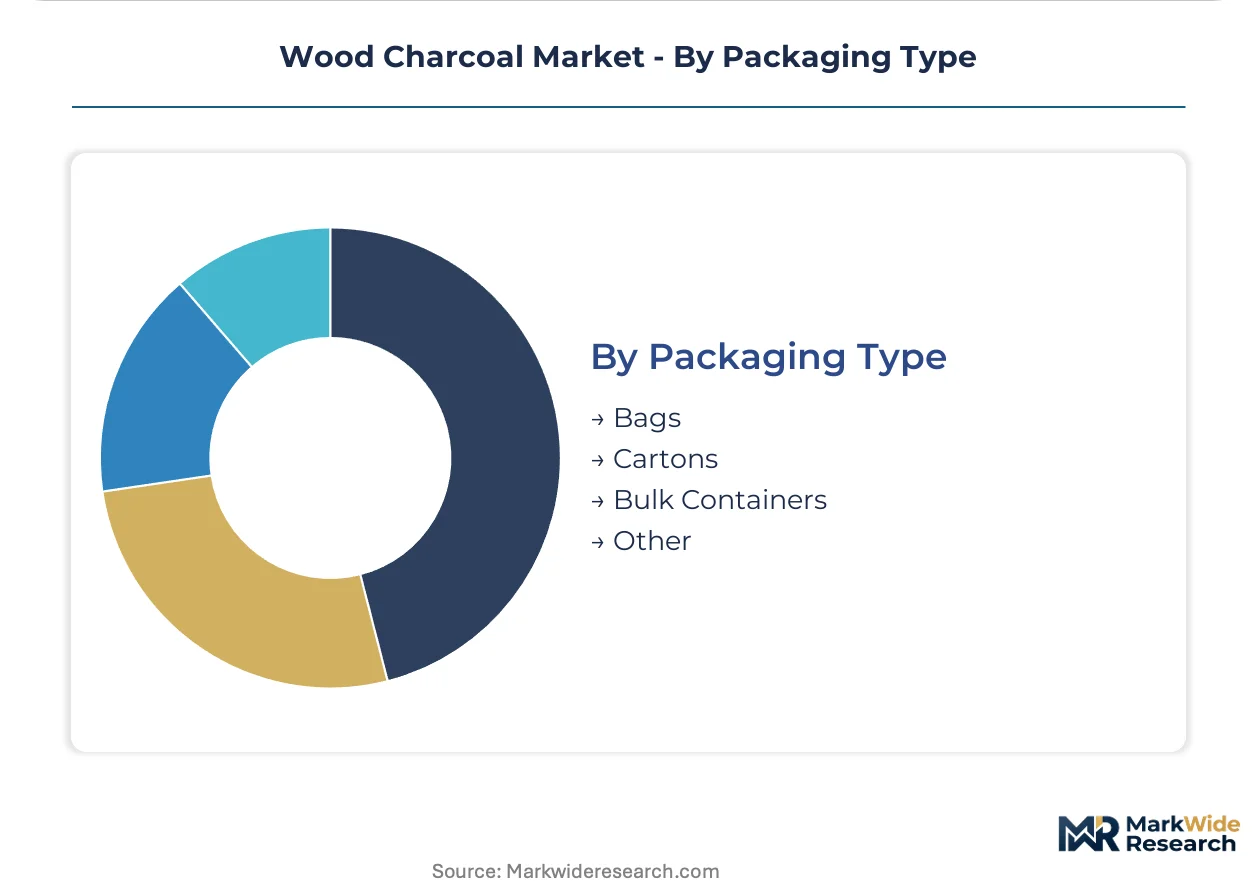
Supply concentration in bag manufacturing shapes cost structures, while bulk containers enable direct-to-restaurant bypass strategies that fragment legacy distribution.
- Bags:Multi-wall paper and woven polypropylene formats dominate retail grocery with 5-20 pound standardization. Printing requirements for origin certification and EU Green Deal deforestation-free documentation add compliance cost layers.
- Bulk Containers:Flexible intermediate bulk containers and pneumatic discharge systems serve restaurant chains and catering cooperatives seeking supply chain control. PyroWood Products and similar specialists leverage this channel for chef-specified relationships.
- Cartons:Retail-ready packaging for premium lump charcoal emphasizes hardwood provenance and sustainability claims.
- Other:Custom formats include moisture-resistant barrier packaging for humid climate distribution.
Bags maintain volume leadership; bulk containers show the most rapid share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration follows regulatory-arbitrage logic as carbonization operations relocate toward jurisdictions with lower emission compliance costs. Brazil and Indonesia attract kiln investments despite tightening licensing, while European processors absorb traceability mandates through supply chain restructuring.
Brazil
Street food commercialization in São Paulo and Rio de Janeiro drives restaurant procurement of premium lump charcoal. ANVISA coordinates with environmental agencies on kiln emission standards that raise production thresholds for small-scale operators. Minas Gerais hosts retort kiln consolidation as mid-scale producers seek industrial zone permitting advantages.
Indonesia
Jakarta and Surabaya urban food zones concentrate commercial charcoal consumption through vendor density and municipal licensing. The Ministry of Environment extends sustainable forest management certification timelines to 18-24 months, filtering trader participation. Kalimantan production clusters face supply concentration risks as hardwood sourcing relationships narrow.
United States
Barbecue-centric metropolitan clusters in Texas and the Southeast prioritize chef-specified hardwood provenance. EPA Clean Air Act provisions govern particulate matter from carbonization facilities, though enforcement varies by state environmental agencies. Kingsford Products Company leverages retail channel density across grocery segments in suburban markets.
Germany
REACH substance registration requirements reshape import protocols for charcoal dust used in metallurgical applications. EU Green Deal deforestation-free mandates accelerate traceability investments among processors seeking compliant tropical hardwood supply chains. The Ruhr industrial zone concentrates activated charcoal demand from water treatment facilities.
Thailand
Bangkok street food culture sustains vendor-level charcoal consumption despite electrification pressure in institutional catering. National environmental standards for kiln emissions remain less stringent than Brazilian or Indonesian frameworks, attracting regional production investment. Chiang Mai and northern provinces supply hardwood feedstock through plantation forestry programs.
Wood Charcoal Market Competitive Environment
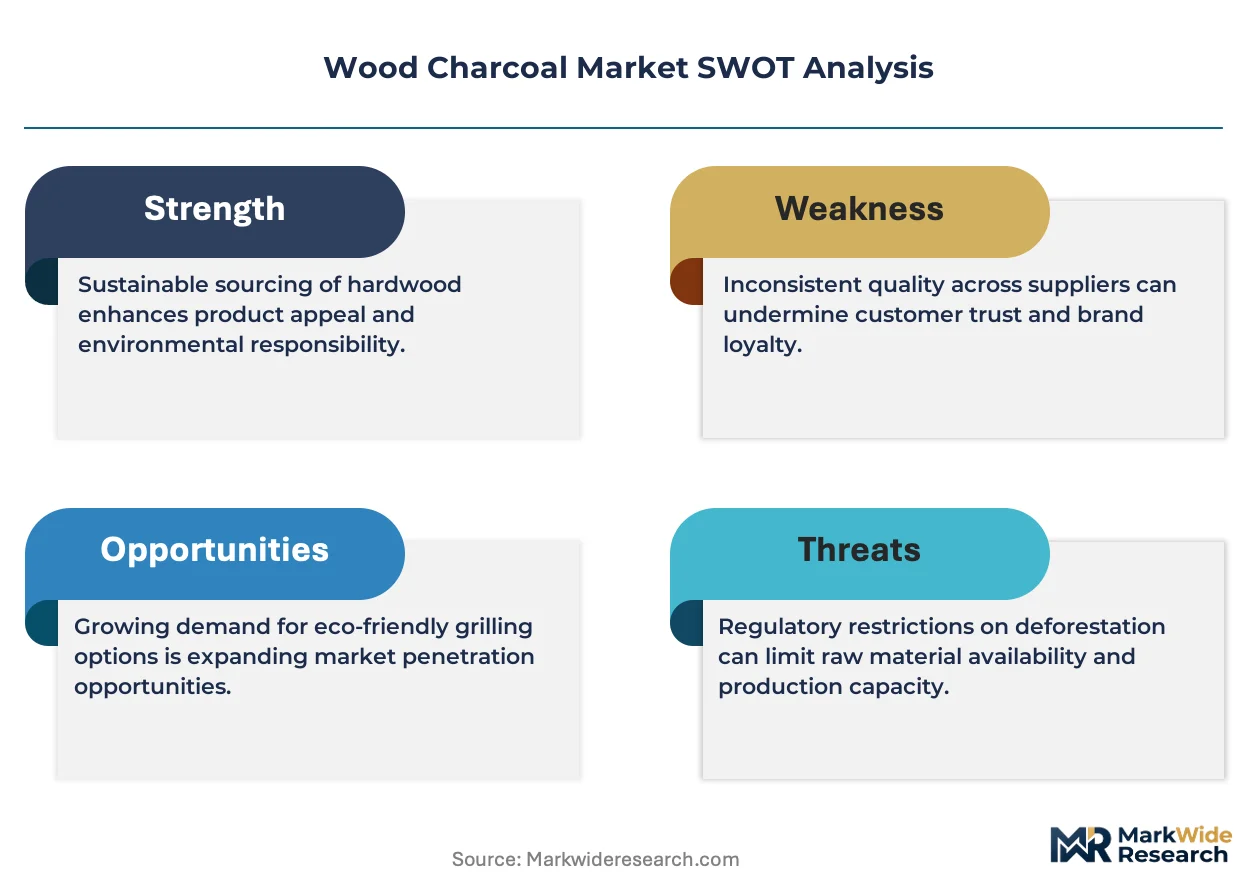
Capacity expansion dominates the current landscape as producers scale retort kiln installations to meet emission compliance without sacrificing yield. The vendor base splits between integrated hardwood-carbonization operations and specialized activated carbon processors. Three archetypes define positioning: retail-channel dominants leveraging grocery density, hardwood sourcing specialists controlling feedstock relationships, and emission-technology leaders capturing European compliance premiums. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players seek deforestation-free certification coverage.
Among North American retail-channel dominants, Kingsford Products Company occupies a position exemplifying grocery shelf presence and household segment capture. PyroWood Products represents the hardwood sourcing specialist archetype through feedstock relationship control. TimberChar Industries anchors the emission-technology tier with European market positioning around kiln compliance standards.
| Leading Market Players |
|---|
| TimberChar Industries |
| PyroWood Products |
| Kingsford Products Company |
| HardwoodEmber Group |
| CarbonBlaze Manufacturing |
| Royal Oak Enterprises |
| ForestFuel Co. |
| Haycarb PLC |
| Duraflame |
| Others |
Value Chain & Pricing Dynamics
Restaurant buying cooperatives in North American and European urban markets command disproportionate pricing leverage through chef-specified procurement that bypasses retail markups. This buyer concentration forces producers to choose between margin capture in direct commercial channels and volume defense through grocery distribution.
Pricing Analysis
Distributor margin compression separates premium lump charcoal from standardized briquette tiers. Three-tier pricing structure across premium, standard, and economy levels reflects hardwood provenance certification, EU Green Deal deforestation-free documentation, and kiln emission compliance grades. Pricing pressure stems from electrification substitution in institutional catering contracts across developed markets. Household grocery segments exhibit highest price sensitivity; chef-specified restaurant procurement shows lowest.
Supply Chain Analysis
Reverse-logistics flows for bulk container returns from restaurant chains and catering cooperatives reduce packaging waste while enabling direct mill relationships. Hardwood feedstock draws from Brazilian Minas Gerais and Indonesian Kalimantan production clusters. Supply chain risk centers on single-source vulnerability as sustainable forest management certifications from Indonesia's Ministry of Environment require 18-24 month validation cycles. Distribution runs through foodservice wholesalers aggregating institutional contracts and direct-to-restaurant bulk channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on pyrolysis automation reducing volatile organic compound emissions while lifting fixed carbon yields above 75 percent. Premium tier capture accelerates as chef-specified procurement displaces centralized foodservice purchasing.
For Market Incumbents: Anchor hardwood sourcing relationships through long-term plantation forestry agreements in Thailand and Vietnam. Defend position against retort kiln automation entrants by securing industrial zone environmental permits ahead of licensing queue bottlenecks. Prioritize emission-technology certification for EU Green Deal compliance premiums. For New Entrants and Emerging Players: Independent barbecue restaurants in Texas and Southeast Asian metropolitan clusters represent the most penetrable buyer archetype. Target direct-to-restaurant bulk distribution bypassing Kingsford's grocery channel density. Pursue soil amendment applications through biochar integration into agricultural carbon credit schemes. For Investors and Strategic Acquirers: Foodservice conglomerates are the most active acquirer in this space, seeking backward integration into可控 supply chains. Five-to-ten year viability favors emission-technology leaders with European compliance positioning over retail-channel dominants facing electrification substitution. Monitor carbon border adjustment mechanism announcements as inflection indicator for procurement geography shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Kiln Automation | ANVISA emission standards in Brazil favor continuous carbonization systems over batch processing. |
| Deforestation-Free Certification | EU Green Deal mandates accelerate traceability investments among European processors. |
| Direct-to-Restaurant Distribution | Chef-specified procurement in barbecue-centric clusters captures margin from specification control. |
| Biochar Soil Amendment | Agricultural carbon credit schemes open premium pricing channels for pyrolysis byproducts. |
| Hardwood Plantation Forestry | Thailand's northern provinces reduce tropical supply concentration risk through domestic feedstock. |
Study Parameters
Direct dialogue with carbonization plant managers, restaurant procurement leads, foodservice distribution channel partners, and kiln technology suppliers grounded qualitative findings. Secondary validation drew from EPA Clean Air Act filings, EU ECHA REACH substance registrations, Brazilian ANVISA emission standards, Indonesian Ministry of Environment certification databases, and customs trade data for hardwood charcoal flows. Bottom-up capacity assessments across production clusters triangulated against top-down demand modeling by end-use segment.
Bottom-up analysis of retort kiln installations and hardwood feedstock availability by region converged with top-down expenditure tracking across restaurant, industrial, and household procurement channels. Segmentation dimensions spanned product type, application, end user, and packaging format. CAGRs derived from weighted average of historical trajectory and driver-based projection across the analysis window. Forecast inputs included municipal food zone licensing velocity and electrification substitution rates in institutional catering.
Underlying measurement precision varies by segment; activated charcoal healthcare applications carry tighter precision than fragmented household briquette sales due to regulatory validation requirements. Forecasts reflect assumptions on certification timeline compression and carbon border adjustment implementation. Practitioners should monitor EU Green Deal deforestation-free enforcement actions and induction cooking technology cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Saudi Arabia Fuel Station Market
Fuels
Europe Coal Market
Fuels
Brazil Bunker Fuel Market
Fuels
Oil Dispenser Market
Fuels
Asia-Pacific Coal Market
Fuels
LNG Fueling Station Market
Fuels
Oil & Gas Lubricants Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Tire Derived Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
Europe Wood Pellet Market
Fuels
Gasoline Market
Fuels
Canada Coal Market
Fuels
Fuel Oxygenate Market
Fuels
Electric Fuel Heater Market
Fuels
Wood Pellet Market