
 Heavy Fuel Oil Market | 2026-2036
Heavy Fuel Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Fuel Oil Market Analysis
Middle Eastern refinery expansions in Saudi Arabia and Kuwait are rewriting regional heavy fuel oil availability. ExxonMobil leverages integrated refining and marine terminal networks to sustain supply continuity across Atlantic basin bunkering hubs. TotalEnergies anchors European low-sulfur fuel oil production through its Antwerp and Le Havre refining platforms. Rosneft dominates Baltic and Black Sea cargo flows through pipeline-connected inland refineries.
Heavy fuel oil denotes a residual petroleum product derived from atmospheric or vacuum distillation of crude oil, typically exhibiting viscosity above 180 centistokes at 50°C and sulfur content ranging from 0.5% to 3.5% by weight depending on source crude and desulfurization intensity. The substance serves primarily as boiler fuel for industrial heat and power generation, as well as propulsion fuel for large two-stroke marine diesel engines operating in deep-sea shipping. Bunker fuel and marine fuel oil categories command the largest value share within product type segmentation, reflecting structural dependence of global trade logistics on residual fuel compatibility with existing vessel engine infrastructure. Power generation application segments face structural decline in OECD markets while retaining demand concentration across emerging economy coastal manufacturing zones where grid reliability remains inconsistent.
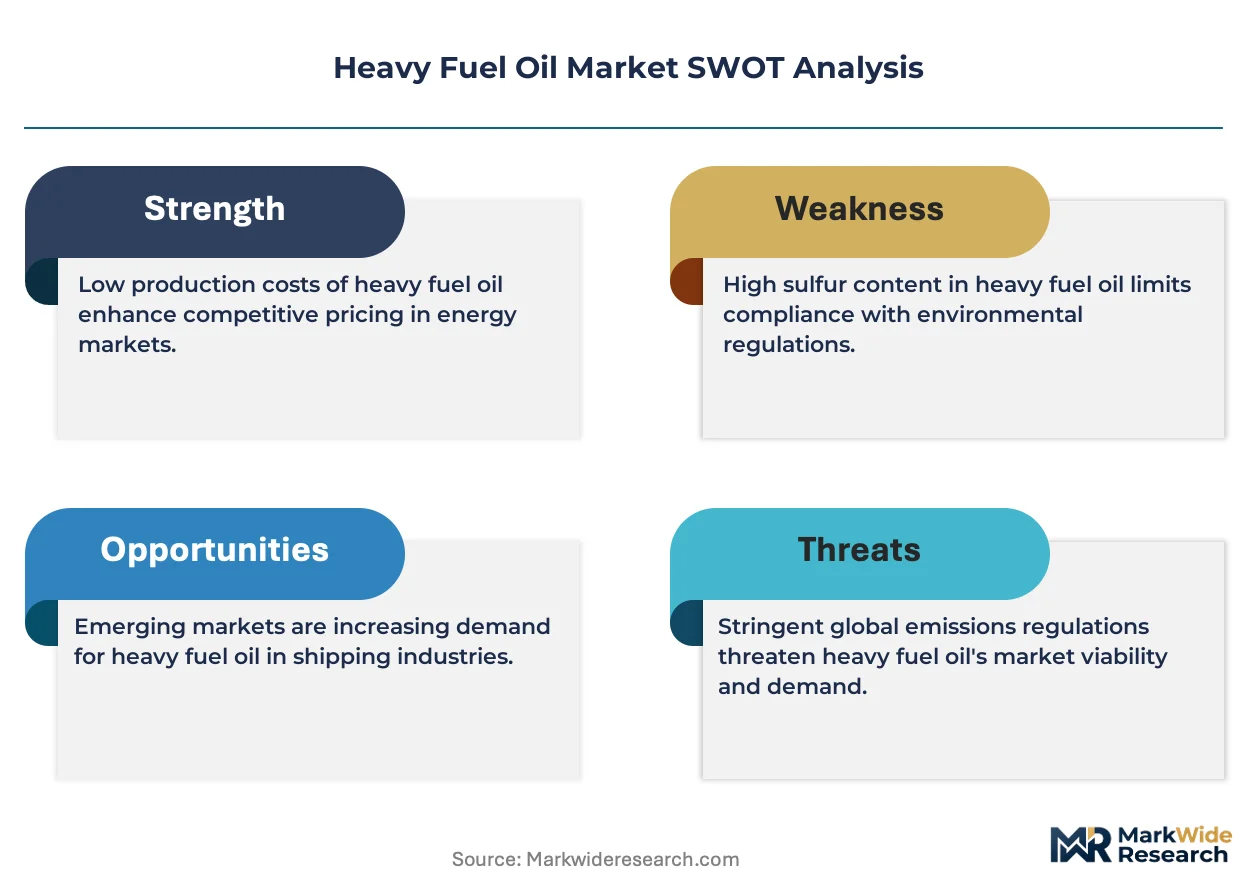
International Maritime Organization MARPOL Annex VI sulfur regulations, EPA residual fuel oil combustion standards under Clean Air Act provisions, and EU F-Gas Regulation monitoring protocols collectively constrain high-sulfur product formulations while redirecting investment toward scrubber installations and low-sulfur blending capacity. Compliance timelines vary across flag state enforcement regimes, creating fragmented product specification requirements at major bunkering ports including Singapore, Rotterdam, and Fujairah. Stakeholders must monitor scrubber payback economics against LNG dual-fuel conversion capital commitments as competing marine propulsion pathways.
Market Dynamics
The International Maritime Organization's sulfur cap enforcement is compressing demand for high-sulfur residual fuel while redirecting investment toward scrubber retrofits and low-sulfur blending infrastructure across major bunkering ports.
Growth Catalysts
- IMO MARPOL Annex VI:The sulfur regulation mandate is forcing vessel operators to either install exhaust gas cleaning systems or switch to compliant fuel blends, sustaining demand for low-sulfur heavy fuel oil formulations at Singapore, Rotterdam, and Fujairah.
- Captive power generation:Steel and cement complexes in China's coastal manufacturing belt rely on heavy fuel oil for grid-independent electricity supply where utility reliability remains inconsistent.
- Scrubber technology diffusion:Exhaust gas cleaning system retrofits on container shipping fleets are preserving compatibility with existing high-sulfur fuel infrastructure while meeting emission standards.
Market Restraints
- Crude oil price volatility:Residual fuel oil pricing tracks Dubai and Brent crude benchmarks, exposing industrial buyers to input cost swings that compress operating margins at power generation facilities.
- Middle Eastern supply concentration:Saudi Aramco and Kuwait Petroleum Corporation refinery expansions are centralizing regional heavy fuel oil availability, creating single-source dependency risks for Atlantic basin buyers.
- LNG dual-fuel substitution:Liquefied natural gas propulsion systems are displacing residual fuel demand among newbuild container vessels and cruise ships with capital commitments favoring lower-carbon alternatives.
Strategic Opportunities
- India's coastal manufacturing zones:Grid reliability gaps at Gujarat and Tamil Nadu industrial corridors present captive power generation demand for low-sulfur fuel oil as the country's Bureau of Indian Standards tightens emission norms.
- EU F-Gas Regulation alignment:The European Union's fluorinated gas monitoring protocols are creating compliance-driven demand for cleaner-burning residual fuel formulations at Antwerp and Le Havre refining hubs.
- Digital bunker trading platforms:Blockchain-enabled fuel oil procurement systems are disintermediating traditional broker networks, reducing transaction friction for vessel operators at Singapore and Rotterdam.
Industry Challenges
- Scrubber wastewater treatment expertise:Exhaust gas cleaning system operators face shortage of marine engineers certified to manage open-loop discharge compliance across fragmented flag state enforcement regimes.
- Low-sulfur blending infrastructure:Refinery upgrades to produce IMO 2020-compliant fuel oil require capital deployment at aging European and North American facilities with compressed payback timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Fuel Oil Market |
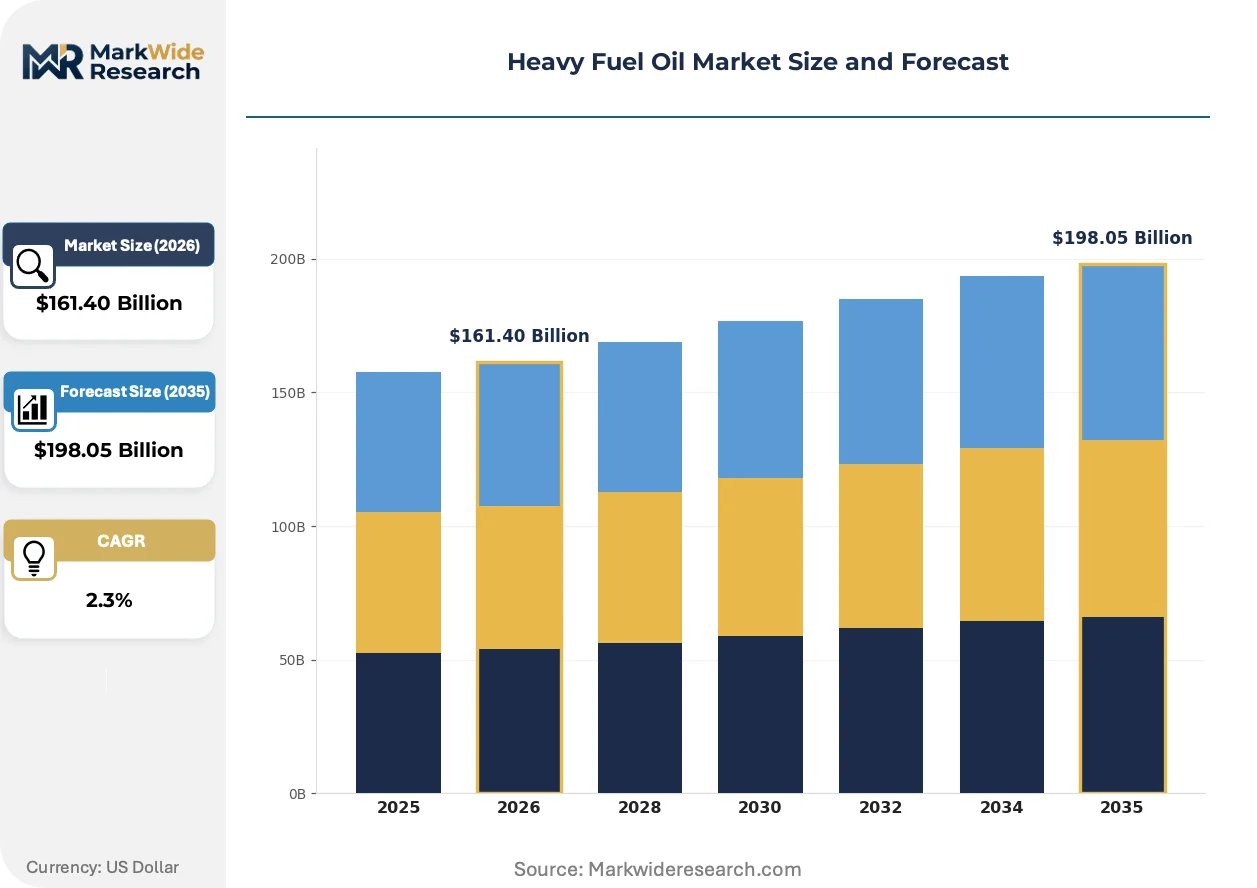
| Market Size in 2026 | $161.40 Billion |
| Market Size in 2035 | $198.05 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residual Fuel Oil, Bunker Fuel, Marine Fuel Oil, Industrial Fuel Oil Application: Shipping Industry, Power Generation, Manufacturing, Oil Refineries End User: Marine Operators, Power Plants, Industrial Facilities, Refineries Source: Crude Oil, Waste Oil, Biomass, Others |
| Companies Covered | TotalEnergies SE, Phillips 66, ExxonMobil Corporation, Marathon Petroleum, Valero Energy, Chevron Corporation, BP Plc, Rosneft Oil Company, Shell Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Fuel Oil Market Emerging Trajectories
Digital fuel management systems and regulatory compliance technologies are restructuring how residual fuel is traded, blended, and consumed across marine and industrial applications.
Artificial intelligence-powered bunker fuel quality verification is digitizing supply chain transparency. Port authorities at Singapore and Rotterdam are deploying machine learning algorithms to detect sulfur content deviations in real-time during vessel refueling operations. This technology is digitizing trust mechanisms between suppliers and buyers, reducing dispute resolution cycles and enabling spot-market contracting.
The European Union's F-Gas Regulation monitoring protocols are tightening residual fuel oil combustion standards across EU member states. Industrial boiler operators in Germany and France must now report fluorinated compound emissions alongside sulfur dioxide, adding compliance layers to fuel procurement decisions. Power generation facilities are responding by sourcing pre-certified low-sulfur blends from Antwerp and Le Havre refining platforms.
Long-term offtake contracting is displacing spot-market purchasing among container shipping lines. Mediterranean Shipping Company and Maersk Line are negotiating multi-year bunker supply agreements directly with integrated refiners, bypassing traditional trading houses. This concentration is most visible in Asia-Pacific routes where Singapore and Fujairah suppliers are locking in volume commitments ahead of scrubber retrofit completion cycles.
Heavy Fuel Oil Market Segmentation
Segmentation in heavy fuel oil markets separates commodity flows by sulfur specification, vessel compatibility, and end-use emission profiles. Refiners optimize cut points and blending ratios differently for marine bunkering versus industrial boiler contracts. Procurement cycles vary dramatically: container lines negotiate annual supply agreements while power plants issue quarterly tenders.
Product Type:
Inventory velocity differs sharply across residual fuel grades, with bunker formulations turning over fastest due to IMO compliance deadlines while industrial fuel oil sits longer in storage.
- Residual Fuel Oil:The heaviest distillation fraction, typically exceeding 180 centistokes at 50°C with sulfur content ranging 0.5% to 3.5% depending on desulfurization intensity. Demand concentrates at coastal power plants in China and India where grid reliability gaps force continuous combustion. EPA residual fuel standards and MARPOL Annex VI sulfur caps constrain high-sulfur formulations.
- Bunker Fuel:Blended specifically for marine diesel engines, split between high-sulfur varieties for scrubber-equipped vessels and very-low-sulfur blends for compliant combustion. Singapore and Rotterdam terminals handle the largest bunkering volumes as container operators retrofit exhaust gas cleaning systems. IMO 2020 enforcement compressed the high-sulfur segment while expanding compliant blend demand.
- Marine Fuel Oil:Intermediate viscosity grades optimized for two-stroke crosshead engines on deep-sea bulk carriers and tankers. Mediterranean Shipping Company and Maersk Line source directly from integrated refiners.
- Industrial Fuel Oil:Lower viscosity cuts for stationary boiler combustion at cement and steel complexes. Gujarat and Tamil Nadu manufacturing corridors in India present expanding demand.
Bunker fuel anchors the volume base while residual fuel oil gains share at the steepest rate among industrial procurement categories.
Application:
Margin structures diverge across applications, with shipping contracts commanding premium pricing for sulfur certification while power generation operates on thinner spreads tied to coal and natural gas alternatives.
- Shipping Industry:Deep-sea container, bulk, and tanker fleets consume the largest residual fuel volumes globally. Scrubber retrofits preserve high-sulfur compatibility on older vessels while newbuilds shift toward LNG dual-fuel systems. Fujairah and Singapore suppliers lock in multi-year offtake agreements with Mediterranean Shipping Company and Maersk Line.
- Power Generation:Captive electricity production at industrial complexes where grid connection is unreliable or prohibitively expensive. China's coastal manufacturing belt concentrates procurement at steel and cement facilities. India's Bureau of Indian Standards emission tightening is redirecting demand toward low-sulfur formulations.
- Manufacturing:Process heat for cement kilns, aluminum smelters, and chemical plants. Antwerp and Le Havre refining platforms serve EU F-Gas Regulation compliance requirements.
- Oil Refineries:Internal fuel consumption for process heat and power, plus intermediate feedstock for further upgrading. Saudi Aramco and Kuwait Petroleum Corporation expansions are centralizing regional availability.
Shipping industry contracts anchor the volume base while power generation gains share at the steepest rate as emerging economy grid gaps persist.
End User:
Procurement sophistication varies by end-user category, with marine operators deploying digital bunker trading platforms while industrial facilities rely on traditional broker networks.
- Marine Operators:Container lines, bulk carriers, and tanker fleets managing sulfur compliance across fragmented flag state enforcement regimes. Blockchain-enabled procurement systems at Singapore and Rotterdam are disintermediating traditional trading houses. Scrubber wastewater treatment expertise shortages constrain open-loop discharge operations.
- Power Plants:Grid-connected and captive facilities burning residual fuel for baseload or backup generation. China's coastal manufacturing belt and India's Gujarat corridor concentrate procurement.
- Industrial Facilities:Cement, steel, and chemical complexes requiring continuous process heat. EU F-Gas Regulation monitoring protocols add compliance layers to fuel procurement in Germany and France.
- Refineries:Integrated operators consuming residual fuel internally or supplying external markets. ExxonMobil leverages Atlantic basin terminal networks for supply continuity.
Marine operators anchor the volume base while industrial facilities gain share at the steepest rate as manufacturing capacity expands in emerging economies.
Source:
Feedstock origin determines sulfur content, viscosity profile, and carbon intensity, with crude-derived residual commanding premium pricing against waste oil and biomass alternatives.
- Crude Oil:Atmospheric and vacuum distillation of conventional petroleum yields the highest-volume residual fuel streams. Middle Eastern refinery expansions in Saudi Arabia and Kuwait are rewriting regional availability patterns. Dubai and Brent crude benchmarks directly track residual fuel pricing.
- Waste Oil:Re-refined lubricant bases and industrial byproducts blended into lower-specification fuel oil. Environmental regulations constrain combustion applications in EU member states.
- Biomass:Pyrolysis oils and bio-residuals from agricultural waste processing. Limited commercial scale due to supply chain fragmentation and combustion compatibility challenges.
- Others:Synthetic fuels, coal-to-liquids residues, and emerging alternative feedstocks. Rosneft dominates Baltic and Black Sea cargo flows through pipeline-connected inland refineries.
Crude oil anchors the volume base while biomass gains share at the steepest rate as carbon intensity regulations tighten across marine and industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE sulfur emission standards anchor Chinese demand patterns while IMO MARPOL Annex VI enforcement reshapes marine fuel procurement across Singapore, Rotterdam, and Fujairah bunkering hubs. Refinery capacity expansions in Saudi Arabia and Kuwait are redirecting Middle Eastern cargo flows toward Atlantic basin markets.
China
Steel and cement complexes along the Yangtze River Delta and Pearl River Delta sustain captive power generation demand for residual fuel oil where grid reliability gaps persist. MEE dual carbon goals and GB emission standards are tightening sulfur content requirements for industrial boiler combustion. Shandong Province refining clusters are upgrading desulfurization capacity to serve coastal manufacturing belt procurement.
Singapore
The Port of Singapore handles the world's largest bunkering volumes as container operators retrofit scrubber systems to preserve high-sulfur fuel compatibility. Maritime and Port Authority regulations enforce real-time sulfur verification through digital fuel management systems. Jurong Island refining infrastructure supports low-sulfur blend production for IMO 2020-compliant vessel refueling.
United States
Gulf Coast refineries in Texas and Louisiana supply residual fuel for domestic power generation and marine bunkering along the Mississippi River corridor. EPA Clean Air Act residual fuel oil combustion standards constrain high-sulfur formulations for industrial boiler operators. Houston Ship Channel terminals anchor Atlantic basin supply continuity for Caribbean and Latin American cargo destinations.
Germany
Industrial boiler operators in the Rhine-Ruhr manufacturing belt face EU F-Gas Regulation monitoring protocols alongside sulfur dioxide emission limits. ECHA REACH compliance requirements add certification layers to residual fuel procurement decisions for cement and chemical complexes. Hamburg port infrastructure supports Baltic Sea bunkering for scrubber-equipped container vessels.
India
Gujarat and Tamil Nadu manufacturing corridors present expanding captive power generation demand as BIS tightens industrial emission norms. Bureau of Indian Standards sulfur specifications are redirecting procurement toward low-sulfur fuel oil blends at coastal steel and aluminum smelter facilities. Mumbai and Chennai port terminals are upgrading bunkering infrastructure to serve scrubber-retrofitted shipping fleets.
Heavy Fuel Oil Market Vendor Landscape
Capability concentration sits with integrated majors commanding refining and marine terminal networks; scale advantage sits with national oil companies leveraging pipeline-connected inland assets. The market structures around three tiers: global integrated refiners with Atlantic and Pacific basin terminal footprints, Middle Eastern national oil companies expanding downstream capacity, and specialized bunkering operators concentrated at Singapore and Fujairah. Competitive moves center on scrubber retrofit timing coordination with long-term offtake contracting, plus low-sulfur blending infrastructure deployment at aging European and North American facilities.
Within the integrated major tier, ExxonMobil Corporation and TotalEnergies SE represent archetypes of Atlantic basin supply continuity through combined refining and marine terminal network control. BP Plc anchors a position spanning both European low-sulfur production and global bunkering logistics. Rosneft Oil Company exemplifies the national oil company archetype with pipeline-connected inland refinery dominance over Baltic and Black Sea cargo flows.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Phillips 66 |
| ExxonMobil Corporation |
| Marathon Petroleum |
| Valero Energy |
| Chevron Corporation |
| BP Plc |
| Rosneft Oil Company |
| Shell Plc |
| Others |
Supply Flow & Price Mechanics
Middle Eastern refinery expansions in Saudi Arabia and Kuwait concentrate upstream residual fuel supply, directing margin pools toward integrated majors with Atlantic and Pacific basin terminal networks. Pricing power accrues to operators controlling desulfurization capacity and marine bunkering infrastructure at Singapore, Rotterdam, and Fujairah.
Pricing Analysis
Geographic price spreads between Singapore and Rotterdam bunkering hubs reflect sulfur certification tiers and scrubber retrofit completion cycles. Contract-based long-term offtake agreements dominate container shipping procurement, with price differentiation driven by IMO 2020 compliance grade and volume scale. Cost compression in high-sulfur residual fuel is intensifying as LNG dual-fuel newbuilds displace demand. Industrial power generators in China and India exhibit highest price sensitivity, while scrubber-equipped marine operators accept premium spreads for supply security.
Supply Chain Analysis
Crude oil vacuum distillation residues feed refinery output across Saudi Arabia, Kuwait, and Russia, with viscosity and sulfur content varying by source crude quality. Feedstock supply rests on Dubai and Brent crude benchmark availability, plus vacuum gas oil for blending into low-sulfur formulations. Single-source vulnerability concentrates around Middle Eastern national oil company refinery expansions. Distribution runs through pipeline-connected inland refineries, marine terminal networks, and digital bunker trading platforms at major port hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment and infrastructure switching costs. Marine fuel oil supply contracts lock in multi-year relationships that resist displacement by alternative propulsion technologies.
For Market Incumbents: Harden terminal network control at Singapore and Fujairah against scrubber wastewater treatment expertise shortages threatening open-loop discharge compliance. Deepen backward integration into desulfurization capacity at Antwerp and Le Havre refining platforms to capture low-sulfur blend premiums. Lock in long-term offtake agreements with Mediterranean Shipping Company and Maersk Line ahead of LNG dual-fuel conversion capital commitments. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu coastal manufacturing corridors where BIS emission tightening redirects captive power generation demand toward certified low-sulfur fuel oil. Target digital bunker trading platform development at Mumbai and Chennai port terminals. Partner with scrubber retrofit yards to bundle fuel supply with exhaust gas cleaning system commissioning. For Investors and Strategic Acquirers: Capital is best deployed toward integrated refiners with pipeline-connected inland assets and marine terminal network control. Long-term viability hinges on IMO MARPOL Annex VI enforcement durability and scrubber economics against LNG dual-fuel alternatives. Watch for inflection signals in LNG bunkering infrastructure buildout rates at Singapore and Rotterdam.| Strategic Initiative | Industry Significance |
|---|---|
| Scrubber Retrofit Coordination | Preserves high-sulfur fuel compatibility for container fleets while meeting IMO 2020 sulfur caps. |
| Low-Sulfur Blending Capacity Expansion | Captures compliant fuel demand at Antwerp and Le Havre refining platforms under EU F-Gas Regulation. |
| Digital Bunker Trading Platform Deployment | Disintermediates traditional broker networks at Singapore and Rotterdam through blockchain-enabled procurement. |
| Long-Term Offtake Contract Negotiation | Locks in volume commitments with Mediterranean Shipping Company and Maersk Line across Asia-Pacific routes. |
| Backward Integration into Desulfurization | Secures low-sulfur residual fuel output at Shandong Province and Jurong Island refining clusters. |
Methodological Framework
A standing panel of refinery operations directors, marine fuel procurement managers, scrubber retrofit yard engineers, and port authority compliance officers provided ongoing calibration across primary interview rounds. Secondary validation drew from IMO MARPOL Annex VI enforcement documentation, EPA Clean Air Act residual fuel standards, EU F-Gas Regulation monitoring protocols, customs trade data for residual fuel flows, and SEC filings from integrated refining majors. Bottom-up segmentation modeling triangulated against top-down macroeconomic energy demand projections.
Scenario bracketing around crude price volatility bands, IMO enforcement stringency variations, and LNG dual-fuel penetration rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included sulfur specification tier, vessel engine compatibility, end-use emission profile, and regional regulatory cluster. CAGRs derived from historical residual fuel demand elasticity and forward scrubber installation schedules. Industry-specific forecast inputs incorporated bunker fuel quality verification technology diffusion rates and captive power generation capacity additions at coastal manufacturing zones.
Stress conditions across Dubai and Brent crude benchmark spreads, IMO flag state enforcement fragmentation, and LNG bunkering infrastructure buildout timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding scrubber payback economics and low-sulfur blending capacity deployment rates. Material shifts in International Maritime Organization sulfur regulation timelines or liquefied natural gas propulsion capital cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India Bunker Fuel Market
Fuels
Fuel Analyzer Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Global Steam Coal Market
Fuels
South Africa Bunker Fuel Market
Fuels
North America Bunker Fuel Market
Fuels
Australia Coal Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Electric Fuel Heater Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
CNG Dispenser Market
Fuels
Chafing Fuel Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Mobile Gas Pumping System Market
Fuels
North America LNG Bunkering Market
Fuels
Smart Gas Solutions Market