
 Marine Fuel Optimization Market | 2026-2036
Marine Fuel Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fuel Optimization Market Outlook
Marine equipment distribution through OEM-integrator networks is rewriting how fuel optimization technology reaches vessel operators. ABB Ltd. leverages its turbocharging and power electronics portfolio to bundle optimization software with propulsion hardware. Wärtsilä Corporation anchors its position through integrated energy management systems that span engine control to voyage planning. MAN Energy Solutions SE competes by specializing in two-stroke engine tuning and digital advisory tools for slow-steaming regimes.
Marine fuel optimization encompasses hardware, software, and advisory services that reduce bunker fuel consumption through engine performance tuning, voyage routing algorithms, and real-time hull condition monitoring. Systems typically integrate with existing vessel automation architectures via IEC 61162-compliant data buses to deliver specific fuel oil consumption reductions. Fuel Management Systems dominate current installation bases across commercial shipping fleets, while Analytics Platforms represent the fastest-expanding segment as cloud-based machine learning models process satellite weather and ocean current data. IoT Solutions concentrate margin pools in subscription recurring revenue rather than one-time hardware sales.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that mandate documented fuel efficiency improvements for vessels above 400 gross tonnage. The EU extends regulatory pressure through its Emissions Trading System inclusion of maritime transport and FuelEU Maritime mandates for greenhouse gas intensity reductions. Classification societies including DNV GL AS verify compliance and certify optimization system performance claims. Stakeholders must weigh capital deployment between retrofit hardware and software-only solutions as regulatory thresholds tighten without grandfathering older vessels.
Market Dynamics
The International Maritime Organization's Carbon Intensity Indicator enforcement is compressing vessel operators into documented fuel efficiency investments, forcing capital allocation toward verifiable optimization systems rather than discretionary operational tweaks.
Growth Catalysts
- IMO CII Compliance Deadlines:The Carbon Intensity Indicator mandates annual efficiency reporting for vessels above 400 gross tonnage, compelling documented fuel consumption reductions through certified optimization platforms.
- Bunker Price Volatility in Singapore:Container shipping lines operating through the world's largest bunkering hub face margin compression that accelerates payback calculations for fuel management system installations.
- Machine Learning Weather Routing:Cloud-based analytics platforms processing satellite ocean current data now deliver voyage-specific fuel savings that exceed static routing algorithms by measurable margins.
Market Restraints
- Sensor Hardware Cost Concentration:Fuel flow meters and engine performance monitors rely on specialized marine-grade instrumentation suppliers concentrated in Northern Europe, creating input cost rigidity.
- Legacy System Integration Friction:Vessel automation architectures running proprietary protocols incompatible with IEC 61162-compliant data buses force expensive middleware development.
- Slow-Steaming Substitution Risk:Operational speed reduction delivers fuel savings without capital expenditure, compressing the addressable market for technology-intensive optimization solutions.
Strategic Opportunities
- EU Emissions Trading System Expansion:Maritime transport inclusion under the EU ETS from 2024 creates compliance cost visibility that justifies optimization system ROI calculations for European-flagged fleets.
- Retrofit-First Vessel Classes:Handysize bulk carriers and small tankers built 2010-2015 lack original fuel optimization equipment, representing an underpenetrated installation base.
- Edge-to-Cloud Convergence:Onboard edge computing for real-time engine tuning combined with shore-based fleet analytics enables subscription revenue models that displace one-time hardware sales.
Industry Challenges
- Marine Data Science Talent Scarcity:Vessel operators lack internal capability to interpret machine learning model outputs for engine tuning decisions, creating implementation bottlenecks.
- Classification Society Certification Timelines:DNV GL AS and Lloyd's Register verification processes for optimization system performance claims extend sales cycles by six to twelve months.
- Multi-Vendor Architecture Complexity:Integrating engine control systems from MAN Energy Solutions with voyage planning software from separate suppliers creates interoperability failures requiring costly custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fuel Optimization Market |
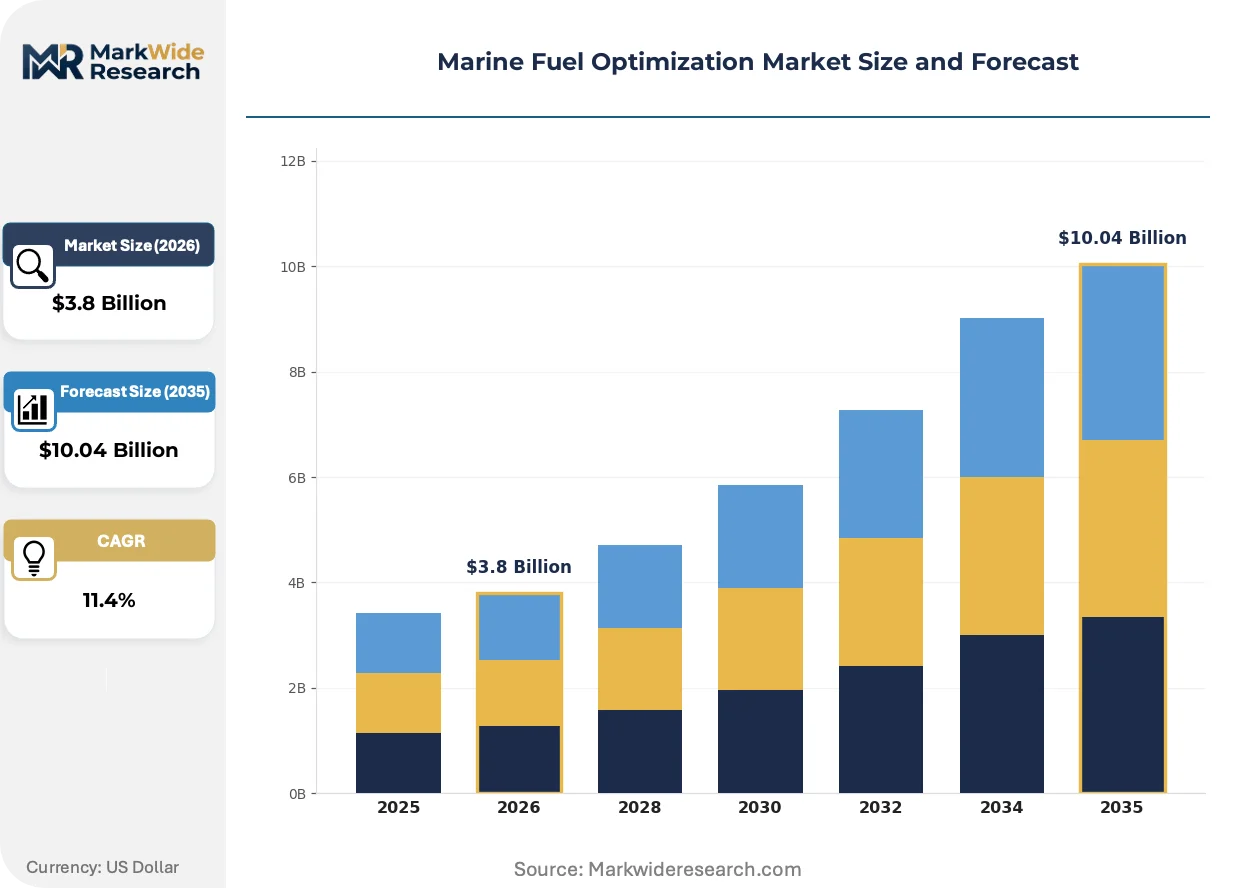
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Management Systems, Emission Control Systems, Analytics Platforms, IoT Solutions Application: Commercial Shipping, Recreational Boating, Fishing Vessels, Offshore Support End User: Shipping Companies, Fleet Operators, Vessel Owners, Harbor Authorities Service Type: Consulting, Training, Maintenance, Software Support |
| Companies Covered | ABB Ltd., MAN Energy Solutions SE, Siemens AG, DNV GL AS, Kongsberg Maritime AS, General Electric Company, Honeywell International Inc., Rolls-Royce Holdings plc, Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fuel Optimization Market Strategic Shifts
Digital twin technology is compressing the feedback loop between vessel design assumptions and operational reality, enabling real-time hull condition monitoring that rewrites maintenance scheduling and fuel consumption baselines.
Digital twin platforms for hull and propeller performance monitoring are hybridizing physics-based hydrodynamic models with operational sensor streams. Container shipping lines deploying these systems on post-Panamax vessels capture continuous fouling detection that compresses dry-dock intervals. The technology is hybridizing traditional condition-based maintenance with predictive fuel penalty calculations, shifting supplier value capture toward ongoing analytics subscriptions.
The EU FuelEU Maritime regulation mandates progressive greenhouse gas intensity reductions for marine fuels bunkered in European ports, with penalties for non-compliance beginning in 2025. This policy forces vessel operators to document fuel consumption per transport work with third-party verification. Container shipping lines and cruise operators with regular European port calls are accelerating procurement of certified fuel management systems to avoid accumulating compliance deficits.
Charter party agreements are embedding fuel consumption performance clauses that transfer optimization responsibility from shipowners to technical managers. This contractual shift concentrates buying authority with specialized vessel management firms in Greece and Singapore that operate multi-owner fleets. The model is most visible in the dry bulk segment where spot market exposure makes fuel efficiency a direct profitability lever for technical managers competing on operating cost benchmarks.
Marine Fuel Optimization Market Segmentation
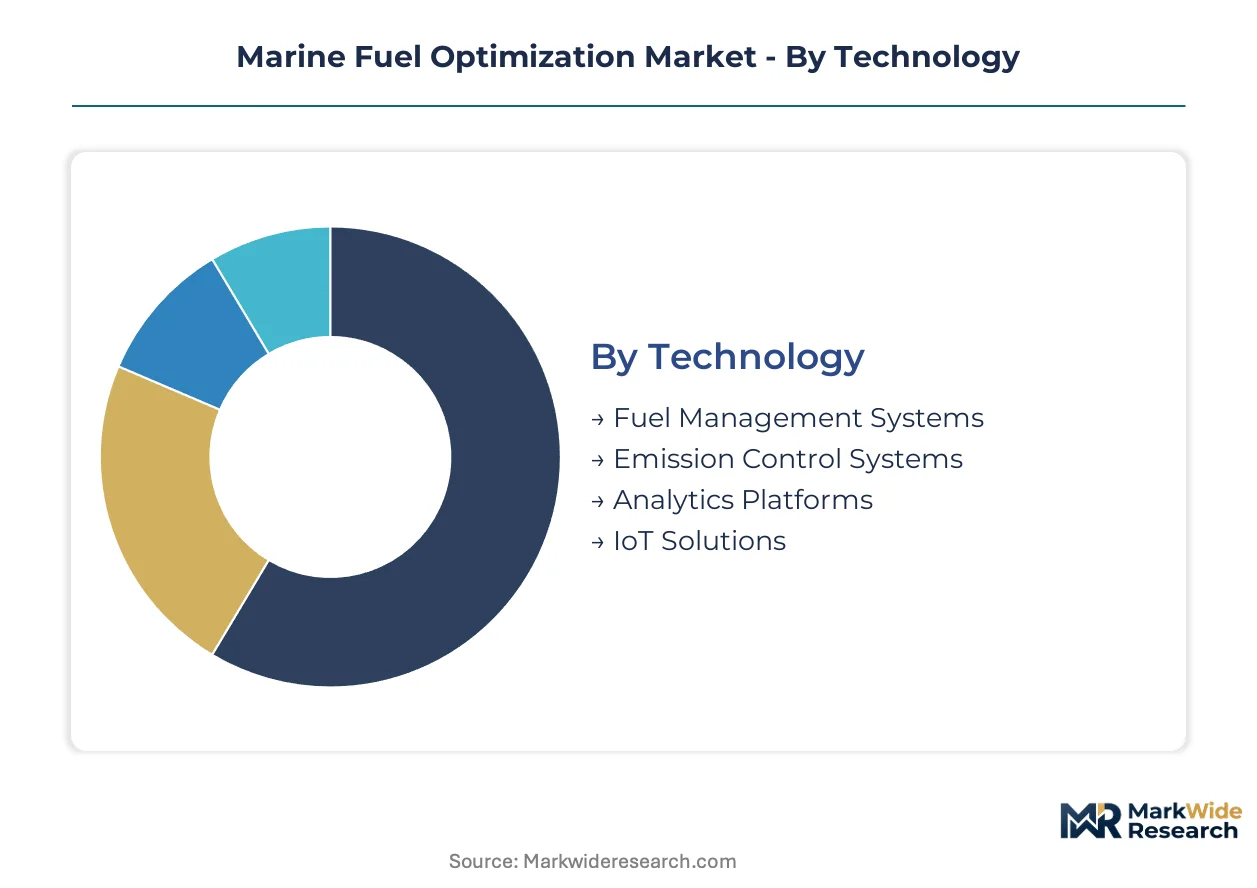
Segmentation in marine fuel optimization reveals how technology deployment, vessel class economics, and regulatory exposure create divergent value capture opportunities. Understanding these dimensions clarifies where hardware margins concentrate versus where subscription revenue scales.
Technology:
After-sales service intensity varies sharply across technology categories, with hardware-intensive segments demanding field engineering presence while software platforms monetize through remote support tiers.
- Fuel Management Systems:Onboard sensor networks and flow metering hardware that measure real-time bunker consumption against engine load profiles. Container shipping lines operating Singapore-rotterdam routes prioritize these systems for CII compliance documentation. Installation concentrates on post-Panamax vessels where fuel volumes justify capital expenditure.
- Analytics Platforms:Cloud-based voyage optimization engines processing satellite weather, ocean current, and port congestion data to generate route-specific fuel savings. Demand clusters with technical managers in Greece and Singapore who oversee multi-owner fleets under performance-based charter clauses. Machine learning model accuracy determines renewal rates and pricing power.
- Emission Control Systems:Exhaust gas cleaning and selective catalytic reduction hardware for SOx and NOx compliance.
- IoT Solutions:Connected sensor infrastructure enabling predictive maintenance and remote performance monitoring.
Fuel Management Systems holds the largest share; momentum sits with Analytics Platforms.
Application:
Application segmentation tracks fuel burn intensity and regulatory scrutiny, with high-volume commercial operators facing sharper optimization imperatives than discretionary-use segments.
- Commercial Shipping:Container lines, bulk carriers, and tankers where fuel constitutes 50-70% of operating costs. EU ETS inclusion from 2024 and FuelEU Maritime mandates accelerate procurement of certified optimization systems for European-trading vessels. CII rating pressure forces documented efficiency investments rather than operational workarounds.
- Offshore Support:Platform supply vessels and anchor handlers serving oil and gas installations. Dynamic positioning operations create unique fuel optimization challenges combining station-keeping precision with engine load management. North Sea and Gulf of Mexico operators face dual pressure from charterer sustainability requirements and regulatory compliance.
- Fishing Vessels:Trawlers and long-liners with intermittent engine loading patterns and limited capital budgets.
- Recreational Boating:Yachts and pleasure craft where fuel optimization remains secondary to performance and convenience.
Commercial Shipping dominates absolute demand; offshore support is climbing fastest on regulatory and charterer pressure.
End User:
End user concentration shapes sales cycle complexity, with fragmented vessel ownership creating channel challenges that integrated fleet operators avoid.
- Shipping Companies:Integrated container lines and bulk operators with in-house technical departments. These buyers negotiate enterprise-wide platform licenses spanning hundreds of vessels. Procurement authority centralizes in headquarters locations—Singapore, Copenhagen, Geneva—where sustainability officers and bunker desks collaborate on CII strategy.
- Fleet Operators:Third-party technical managers in Greece and Singapore operating vessels for multiple owners under performance-based contracts. Fuel efficiency clauses transfer optimization accountability to these operators, concentrating buying authority with firms competing on operating cost benchmarks.
- Vessel Owners:Single-ship or small-fleet owners lacking technical infrastructure for system operation.
- Harbor Authorities:Port operators monitoring vessel emissions and fuel quality for regulatory enforcement.
Shipping Companies command the largest procurement volumes; fleet operators are expanding most quickly as charter structures evolve.
Service Type:
Service segmentation tracks value migration from upfront system sales toward recurring revenue, with software support and training creating stickier customer relationships than discrete consulting engagements.
- Software Support:Continuous platform updates, cloud infrastructure management, and machine learning model retraining. Vessel operators lack internal data science capability to interpret optimization outputs, creating dependency on vendor support tiers. Subscription pricing displaces perpetual licenses as the dominant commercial model.
- Maintenance:Scheduled calibration of fuel flow sensors, engine performance monitors, and emission analyzers. Marine-grade instrumentation requires specialized technicians concentrated in Northern Europe, creating geographic service gaps that remote diagnostics partially address.
- Consulting:One-time efficiency audits and optimization strategy development.
- Training:Crew and shore staff education on system operation and data interpretation.
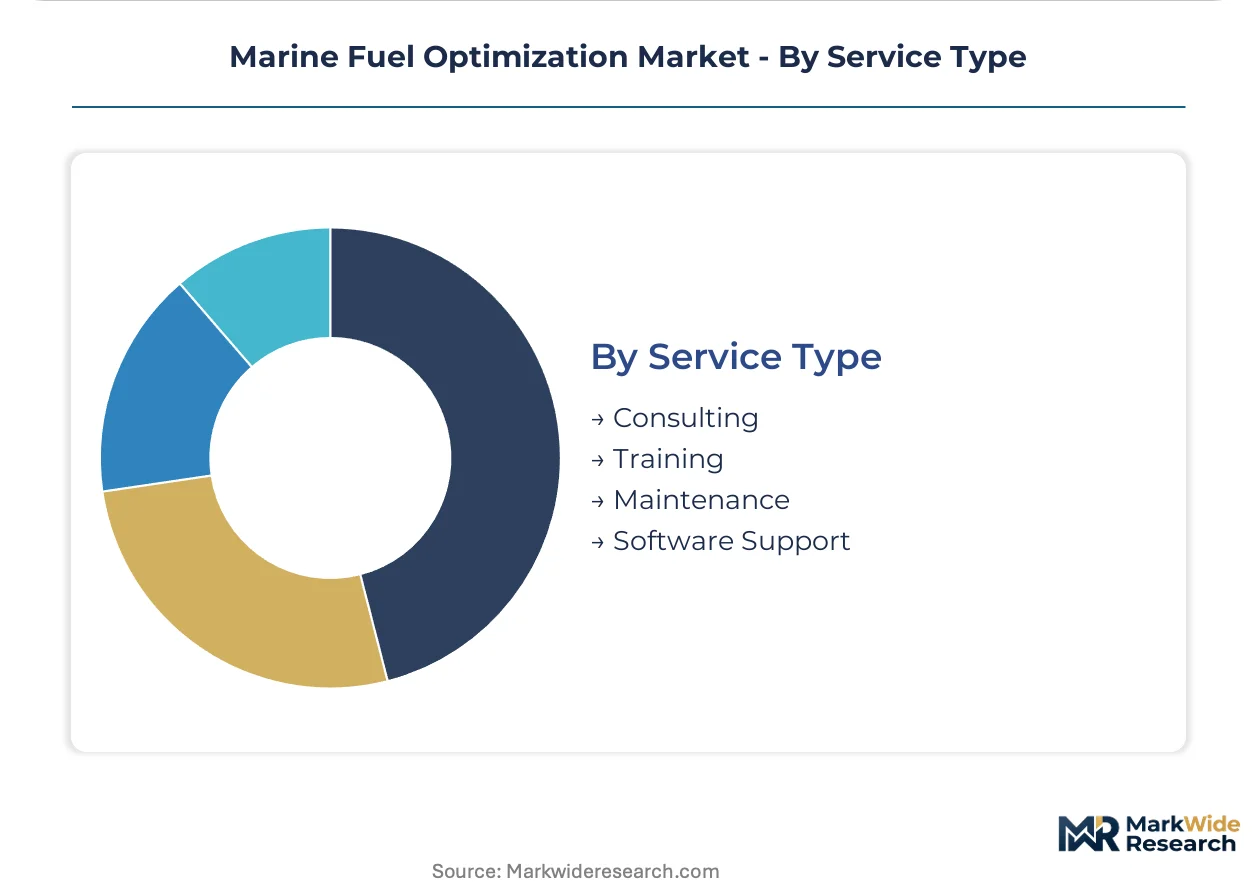
Software Support captures the largest service revenue share; maintenance is gaining fastest as installed sensor bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore anchors Asia-Pacific bunkering demand, processing over 50 million tonnes of marine fuel annually and underwriting optimization technology procurement for container lines transshipping through the Strait of Malacca.
Singapore
Container shipping lines operating Singapore-Rotterdam routes prioritize fuel management systems for CII compliance documentation. The Maritime and Port Authority of Singapore enforces emission standards that align with IMO protocols. Technical managers based in Singapore's Marina Bay financial district oversee multi-owner fleet optimization under performance-based charter clauses.
Germany
Hamburg's container terminals generate concentrated demand for voyage optimization platforms processing North Sea weather patterns. The EU Emissions Trading System inclusion of maritime transport from 2024 accelerates certified system procurement for European-flagged vessels. Shipowners in Hamburg-Altona negotiate enterprise-wide platform licenses spanning hundreds of vessels.
China
Shanghai's Yangshan Deep Water Port drives analytics platform adoption among state-owned shipping conglomerates. The Ministry of Ecology and Environment implements dual carbon goals that pressure vessel operators toward documented efficiency investments. Dalian and Qingdao shipyards integrate fuel optimization hardware during newbuild construction for domestic bulk carriers.
Netherlands
Rotterdam's bunkering infrastructure supports optimization system deployment across European short-sea shipping. The EU FuelEU Maritime regulation mandates greenhouse gas intensity reductions for marine fuels bunkered in Dutch ports. Maritime technology clusters in Delft and Rotterdam harbor develop edge-to-cloud convergence solutions for real-time engine tuning.
United States
Houston's petrochemical corridor influences fuel quality monitoring system demand for Gulf Coast tanker operations. The Environmental Protection Agency enforces vessel emission standards under the Clean Air Act that complement international regulations. Seattle-based technical managers serving Alaska crude oil routes deploy weather routing algorithms for North Pacific fuel savings.
Marine Fuel Optimization Market Competitive Environment
On the supply side, the industry is consolidating around integrated energy management providers that bundle hardware, software, and advisory services. Three strategic archetypes dominate: turbocharging specialists extending into digital optimization, classification societies certifying system performance claims, and industrial conglomerates leveraging power electronics portfolios. Competitive moves center on strategic partnerships with shipyards and technology licensing agreements that accelerate installation base expansion.
Among European-integrated industrial groups, ABB Ltd., Siemens AG, and Wärtsilä Corporation exemplify the full-stack archetype combining propulsion hardware with optimization software. These entities occupy positions where energy management system expertise anchors recurring revenue models. MAN Energy Solutions SE represents the engine-native specialist tier, while classification society DNV GL AS sits within the verification and certification layer that validates competitor performance claims.
| Leading Market Players |
|---|
| ABB Ltd. |
| MAN Energy Solutions SE |
| Siemens AG |
| DNV GL AS |
| Kongsberg Maritime AS |
| General Electric Company |
| Honeywell International Inc. |
| Rolls-Royce Holdings plc |
| Wärtsilä Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in marine-grade sensor manufacturing across Northern Europe is compressing hardware margins while simultaneously accelerating subscription pricing migration among platform vendors seeking recurring revenue stability.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between container shipping lines and fuel management system vendors, with enterprise-wide platform licenses commanding 30-40% unit economics advantages over single-vessel installations. Pricing stratifies across CII certification grade, after-sales service bundling, and fleet-scale commitments. Cost compression in sensor hardware is intensifying because OEMs in Germany and Norway compete for shrinking newbuild order books. Technical managers operating multi-owner fleets exhibit highest price sensitivity due to performance-based charter clauses that cap technology pass-through.
Supply Chain Analysis
Export-control regimes limiting dual-use marine automation technology flows from the EU to Chinese shipyards are fragmenting procurement channels for integrated energy management systems. Component manufacturing concentrates in Germany, Norway, and Finland, with specialized fuel flow meters and engine performance monitors drawing from precision instrumentation clusters in Hamburg and Oslo. Single-source vulnerability runs through marine-grade sensor suppliers concentrated in Scandinavia. Distribution runs through shipyard-integrator partnerships and direct technical manager relationships in Singapore and Greece.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine fuel optimization vendors face acute shortages of data scientists capable of interpreting machine learning model outputs for engine tuning decisions, creating competitive advantage for firms that solve this talent pipeline constraint.
For Market Incumbents: Build switching-cost moats through deeper integration of voyage planning software with engine control systems from MAN Energy Solutions and Wärtsilä, raising interoperability barriers against point-solution entrants. Accelerate certification investment with DNV GL AS to compress six-to-twelve-month verification timelines that currently stall sales cycles. Defend against slow-steaming substitution by quantifying technology ROI against operational speed reduction through documented fuel savings. For New Entrants and Emerging Players: Build out white-space positions in handysize bulk carriers and small tankers built 2010-2015, an underpenetrated retrofit installation base lacking original fuel optimization equipment. Target technical managers in Greece and Singapore who concentrate buying authority under evolving performance-based charter structures. Enter through edge-to-cloud convergence offerings that displace one-time hardware sales with subscription revenue models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across analytics platform sub-segments as cloud infrastructure displaces onboard hardware, improving cash conversion and scalability. Long-term viability favors vendors with demonstrated machine learning model accuracy and renewal rates rather than hardware-dependent installation bases. Acquisition target archetype: software-native voyage optimization platforms with proven European-flagged fleet deployments. Watch for EU ETS compliance cost visibility as inflection indicator accelerating procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| CII Certification Investment | DNV GL AS verification compresses sales cycles and unlocks European-flagged fleet procurement. |
| Edge-to-Cloud Platform Migration | Subscription revenue models displace one-time hardware sales and improve customer lifetime value. |
| Shipyard Integration Partnership | Dalian and Qingdao newbuild channels embed fuel optimization during vessel construction. |
| Technical Manager Channel Control | Greece and Singapore-based operators concentrate buying authority under performance clauses. |
| Machine Learning Model Retraining | Continuous satellite weather and ocean current data ingestion sustains voyage optimization accuracy. |
Study Parameters
Desk research of IMO regulatory filings, EU ETS implementation documents, and classification society certification databases preceded structured interviews with vessel technical superintendents, fleet operations directors, marine automation procurement managers, and sustainability officers at container shipping lines. Primary fieldwork with technical managers in Greece and Singapore validated charter party evolution and buying authority concentration. Secondary sources included Lloyd's Register equipment certification records, SEC filings from listed marine technology vendors, and customs data on marine sensor trade flows. Bottom-up vessel installation estimates triangulated against top-down bunkering volume projections.
Assumptions held fixed include IMO CII regulatory enforcement timelines, EU ETS carbon price trajectories, and machine learning model accuracy improvements observed historically. The analytical framework modeled technology segmentation, vessel class economics, end-user concentration, and service type revenue migration across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycles, and subscription pricing adoption curves. Industry-specific inputs encompassed Singapore bunker price volatility patterns and FuelEU Maritime penalty structures.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by industrial conglomerates into software-native optimization platforms would shift outcomes. Material shifts in IMO regulatory grandfathering provisions or EU carbon border adjustment mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline As a Fuel Market
Fuels
LPG Vaporizer Market
Fuels
North America Bunker Fuel Market
Fuels
Global Chemical Logistics Market
Fuels
South Africa Bunker Fuel Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Electric Fuel Heater Market
Fuels
Global Steam Coal Market
Fuels
South America Aviation Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Briquette Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
India LNG Market
Fuels
China LNG Bunkering Market