
 South Africa Refined Petroleum Products Market | 2026-2036
South Africa Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Refined Petroleum Products Market Analytics
The ultra-low sulphur diesel specification tier is unwinding legacy product lines across South Africa's downstream sector. Sasol Limited leverages its Fischer-Tropsch synthesis expertise to sustain high cetane outputs that meet stringent transport fuel mandates. Astron Energy (Pty) Ltd. anchors coastal supply through its Cape Town refinery complex, while ENGEN PETROLEUM LTD competes aggressively in the inland retail network.
Refined petroleum products comprise hydrocarbon streams separated and upgraded through atmospheric distillation, catalytic cracking, and hydrotreating to achieve defined flash points, viscosity grades, and sulphur thresholds below 10 parts per million for road fuels. These products power internal combustion engines, industrial boilers, and aviation turbines across Southern Africa's energy-intensive economy. Diesel dominates the product type dimension as mining haulage and agricultural mechanization absorb the bulk of middle distillate output. The transportation end user segment commands the deepest margin pools, while power generation applications face structural pressure from renewable alternatives and Eskom's deteriorating baseload capacity.
The Department of Mineral Resources and Energy enforces the Clean Fuels II standard, compelling refiners to invest in desulphurization units or face import dependency for compliant product. The South African Bureau of Standards certifies fuel quality at retail points, with non-compliance triggering distribution licence reviews. Stakeholders must monitor the timing of refinery conversion projects against import infrastructure readiness, as supply security hinges on coordinated capital deployment across the value chain.
Market Dynamics
The Clean Fuels II programme is forcing wholesale refinery reconfiguration across South Africa's downstream infrastructure. Sasol's Secunda complex and coastal refineries must simultaneously absorb desulphurization capex while defending inland market position against import flows through Durban and Richards Bay.
Growth Catalysts
- Mining haulage expansion:Platinum and coal belt operators in Rustenburg and Mpumalanga are scaling diesel procurement as mechanized extraction deepens. Underground equipment fleets require ultra-low sulphur diesel to meet ventilation safety standards.
- Clean Fuels II mandate:The Department of Mineral Resources and Energy's sulphur ceiling of 10 parts per million for road fuels is compelling infrastructure investment that locks in compliant supply capacity for two decades.
- Gauteng demand concentration:The province's pipeline terminus at Jameson Park and Alrode storage farms aggregates 60 percent of national inland consumption, creating procurement density that justifies dedicated logistics investment.
Market Restraints
- Crude import dependency:South Africa lacks domestic crude production, exposing refiners to dollar-denominated feedstock volatility and exchange rate compression on working capital cycles.
- Single-coastal import corridor:Durban's Island View terminal handles the majority of clean product imports, creating concentration risk for Gauteng supply security during weather or labour disruptions.
- Renewable displacement in power generation:Eskom's declining baseload and solar-wind capacity additions are eroding the 20 percent of diesel demand historically absorbed by peaking turbines and remote mine grids.
Strategic Opportunities
- Limpopo agricultural mechanization:Grain and citrus belt expansion is outpacing existing fuel retail infrastructure, creating whitespace for mobile refuelling services and on-farm storage partnerships.
- Fischer-Tropsch synthetic diesel premiumization:Sasol's high-cetane GTL output commands transport fleet preference for cold-start reliability, supporting margin capture above commodity diesel benchmarks.
- Biofuel blending mandate preparation:Draft regulations for 10 percent ethanol and biodiesel incorporation would require dedicated blending infrastructure investment ahead of formal implementation.
Industry Challenges
- Hydrotreater catalyst sourcing:Refinery upgrade timelines depend on specialized cobalt-molybdenum catalyst delivery from European and Asian suppliers, with lead times extending 18 months.
- Pipeline integrity certification:The Transnet Fuel Pipeline network requires continuous smart-pig inspection and sectional replacement to maintain South African Bureau of Standards pressure vessel compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Refined Petroleum Products Market |
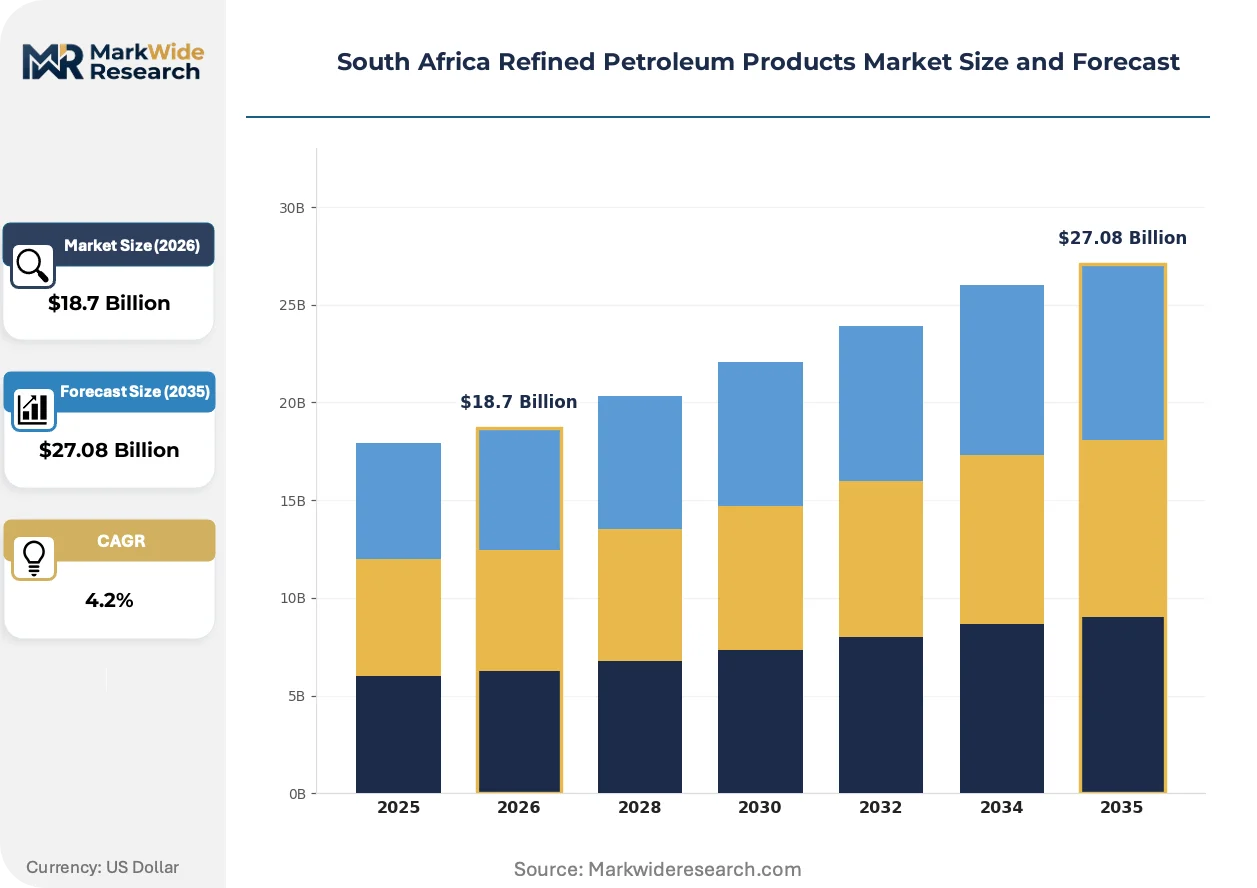
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene End User: Transportation, Power Generation, Industrial, Residential Distribution Channel: Retail Outlets, Wholesalers, Direct Supply, Resellers Application: Automotive, Aviation, Heating, Marine |
| Companies Covered | TotalEnergies SE, Astron Energy (Pty) Ltd., Sasol Limited, BP Southern Africa (Pty) Ltd., Chevron Corporation, ENGEN PETROLEUM LTD, Shell Plc, South African Petroleum Refiners (SAPREF), PetroSA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Refined Petroleum Products Market Evolving Landscape
Refinery technology trajectories and procurement behaviour are diverging sharply as compliance deadlines harden and buyer concentration intensifies. Three forces are compressing legacy operating models while opening asymmetric advantage for prepared operators.
Advanced hydrotreating catalyst formulations are bifurcating the competitive landscape between refiners who invested early in deep desulphurization and those facing stranded asset risk. Coastal operators with hydrocracker units are absorbing licensing fees for proprietary noble-metal catalyst systems that cut sulphur below 5 parts per million. This technology is bifurcating margin pools: compliant product commands logistics priority through the Transnet pipeline network while high-sulphur residual stocks face inland market exclusion.
The South African Bureau of Standards has accelerated fuel quality audit frequency from quarterly to monthly at retail points, deploying mobile testing laboratories to bypass laboratory bottlenecks. This enforcement tightening is compressing non-compliant distributor margins and accelerating licence consolidation. Independent retailers in the Eastern Cape and Free State are most affected, with many seeking wholesale supply reallocation to major brand networks.
Fleet operators in the Johannesburg-Durban corridor are consolidating diesel procurement through direct refinery offtake agreements that bypass traditional wholesale intermediaries. Large logistics groups with 500-plus truck fleets are negotiating 12-month fixed-volume contracts with pipeline-linked terminals. This concentration is most visible in the fast-moving consumer goods sector, where retailers with captive distribution networks are internalizing fuel cost control as a supply chain differentiator.
South Africa Refined Petroleum Products Market Segmentation
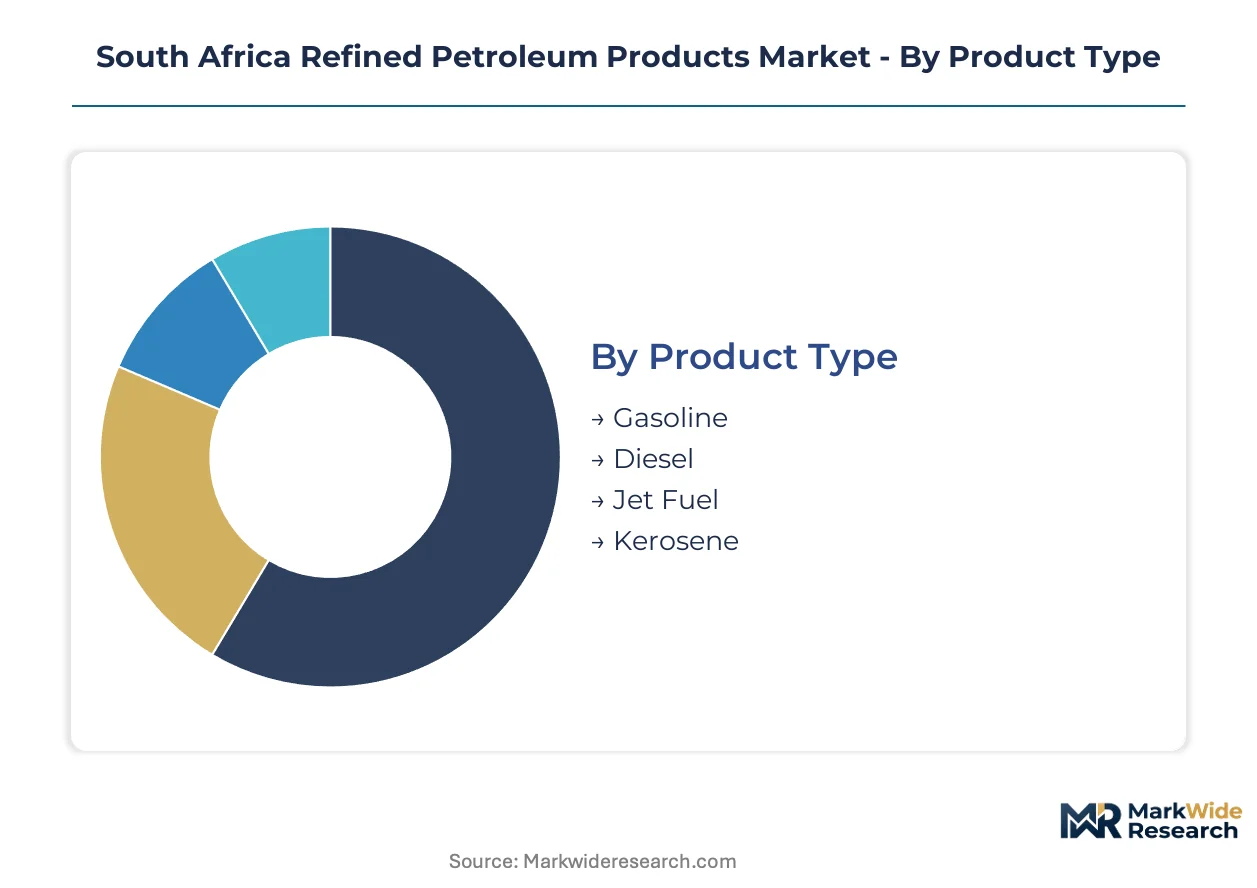
South Africa's refined petroleum products market fragments across four critical dimensions that determine pricing power, logistics configuration, and regulatory exposure. Each segmentation layer reveals distinct margin structures and capital intensity requirements that shape competitive positioning.
Product Type:
Diesel and gasoline dominate domestic consumption volumes, while jet fuel and kerosene serve export corridors and specialized industrial applications.
- Diesel:Middle distillate with ultra-low sulphur specifications below 10 parts per million for road compliance. Mining haulage operators in Mpumalanga and Rustenburg absorb the bulk of high-cetane output, with ventilation safety standards in underground operations mandating clean-burning fuel grades.
- Gasoline:Light distillate blended to 95 and 93 octane ratings for retail distribution. Gauteng's inland pipeline terminus at Jameson Park concentrates procurement activity, where retail network density supports volume-based supply contracts.
- Jet Fuel:Kerosene-based aviation turbine fuel meeting international ASTM specifications. OR Tambo International and Cape Town International anchor demand, with coastal refineries supplying direct pipeline access to airport fuel farms.
- Kerosene:Illuminating and heating-grade middle distillate for residential and remote industrial use. Rural Eastern Cape and KwaZulu-Natal settlements sustain residual demand outside electrified grid coverage.
Diesel holds the largest share; momentum sits with jet fuel as regional aviation connectivity expands.
End User:
Transportation commands premium logistics infrastructure, while power generation faces structural displacement from renewable capacity additions.
- Transportation:Road freight, passenger vehicles, and aviation fleets consuming refined products through retail and direct refinery offtake. The Johannesburg-Durban corridor concentrates diesel procurement through fleet operator consolidation.
- Power Generation:Eskom peaking turbines and remote mine grids historically absorbed residual fuel oil and diesel. Solar-wind capacity additions and baseload deterioration are compressing this segment's long-term trajectory.
- Industrial:Manufacturing boilers, process heating, and captive power plants requiring consistent fuel quality. KwaZulu-Natal's petrochemical cluster and Eastern Cape automotive assembly anchor industrial offtake.
- Residential:Kerosene for lighting and LPG substitutes in unelectrified households. Limpopo and Eastern Cape rural districts sustain this channel despite grid extension programmes.
Transportation captures the deepest margin pools; industrial applications show steadiest volume retention against energy transition pressures.
Distribution Channel:
Channel selection determines working capital intensity and regulatory compliance burden across the downstream value chain.
- Retail Outlets:Branded service stations and independent forecourts selling to end consumers. The South African Bureau of Standards enforces monthly fuel quality audits, compressing non-compliant operator margins.
- Wholesalers:Intermediate distributors aggregating volume for resale to smaller retailers and commercial accounts. Gauteng storage farms at Alrode and Langlaagte anchor wholesale consolidation.
- Direct Supply:Refinery-to-fleet contracts bypassing intermediaries for large consumers. Mining houses and logistics groups with 500-plus truck fleets negotiate fixed-volume agreements with pipeline-linked terminals.
- Resellers:Mobile refuelling services and on-farm storage partnerships addressing agricultural whitespace. Limpopo grain and citrus belt expansion is outpacing fixed retail infrastructure.
Direct supply is gaining share fastest as procurement concentration accelerates; retail outlets remain the volume foundation.
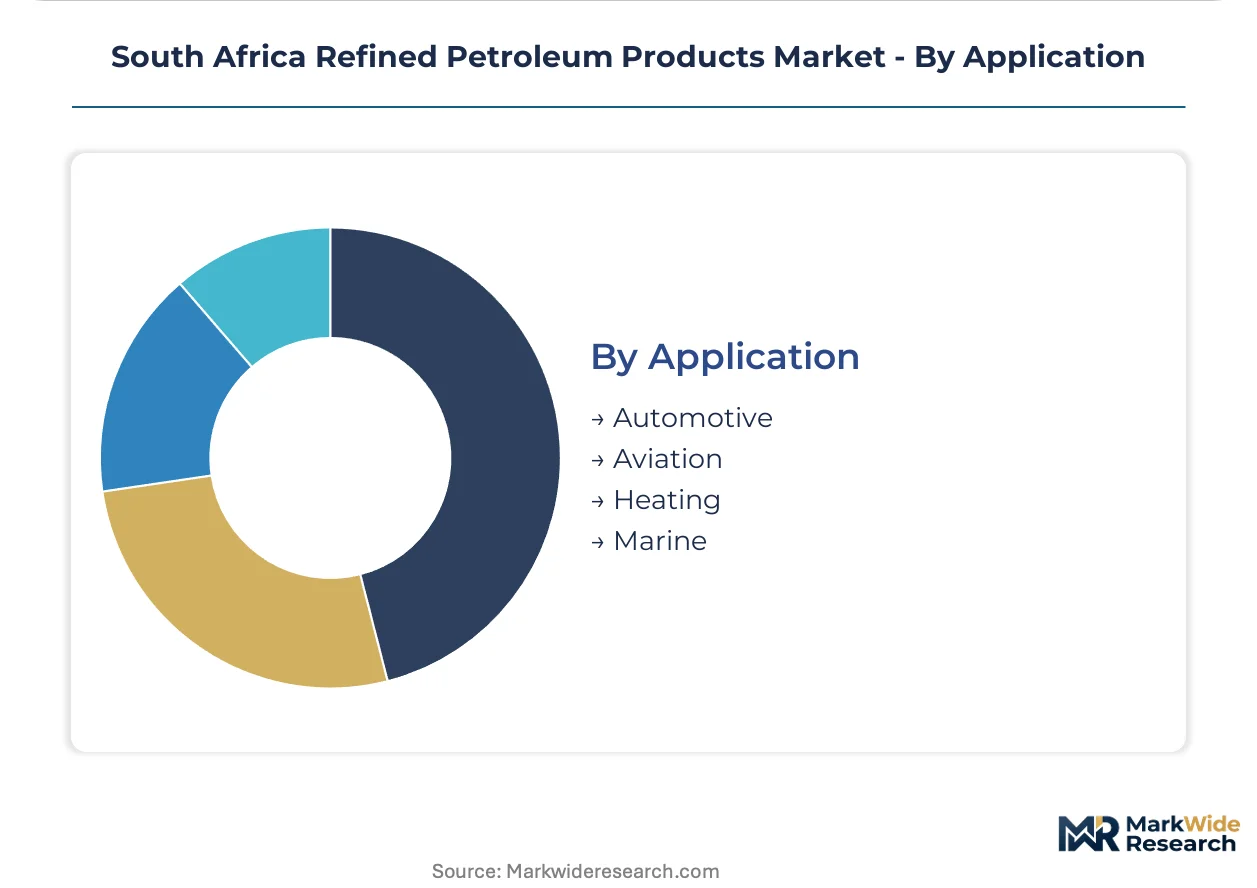
Application:
Application segmentation aligns product specifications with performance requirements and emissions regulations.
- Automotive:Light-duty and heavy-duty vehicles consuming gasoline and diesel formulations. Clean Fuels II mandates enforce 10 parts per million sulphur ceilings, requiring refinery hydrotreater investment.
- Aviation:Commercial and cargo aircraft requiring jet fuel with freeze point and thermal stability certifications. Coastal refinery access to airport fuel farms determines supply security.
- Heating:Industrial process heat and residential warmth from kerosene and residual fuel oils. Declining baseload power reliability is sustaining backup heating demand.
- Marine:Coastal and inland waterway vessels using marine gas oil and residual bunkers. Durban and Richards Bay port facilities handle bunkering operations for regional shipping.
Automotive applications dominate value capture; aviation shows the steepest expansion trajectory as passenger volumes recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's refined petroleum products trade runs a structural deficit, with coastal import terminals feeding inland demand corridors. The country's refinery capacity constraints and Clean Fuels II compliance timelines shape regional supply security.
Gauteng Province
Mining haulage operators in Rustenburg and the platinum belt drive diesel procurement volumes. The Department of Mineral Resources and Energy enforces ultra-low sulphur mandates that concentrate compliant supply through the Transnet pipeline network. Jameson Park and Alrode storage farms aggregate sixty percent of national inland consumption, creating procurement density for direct refinery contracts.
KwaZulu-Natal
Durban's Island View terminal handles the majority of clean product imports for the Southern African corridor. The South African Bureau of Standards certifies fuel quality at coastal discharge points before pipeline injection. Richards Bay port facilities anchor bunkering operations for regional shipping, with marine gas oil demand tied to bulk commodity export schedules.
Western Cape
Cape Town International Airport sustains jet fuel demand through direct coastal refinery pipeline access. The province's refining complex supplies aviation turbine fuel meeting international ASTM specifications. Citrus export logistics and agricultural mechanization in the Breede Valley support residual diesel offtake outside peak harvest windows.
Mpumalanga
Coal belt mining operations absorb high-cetane diesel for mechanized extraction and ventilation safety compliance. Underground equipment fleets require clean-burning fuel grades that meet occupational health standards. The province's position on the Maputo Corridor links it to alternative import routes through Mozambique's Matola terminal.
South Africa Refined Petroleum Products Market Competitive Landscape
Listed leaders compete with private specialists across refinery ownership and retail network control, creating a tiered competitive structure. JSE-listed entities dominate integrated refining and marketing, while unlisted operators concentrate in terminal logistics and specialized distribution. Strategic archetypes split between coastal refinery owners with hydrocracker assets, inland synthetic fuel producers, and import-dependent wholesale marketers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as Clean Fuels II deadlines approach.
Within the integrated refinery tier, Sasol Limited and Astron Energy (Pty) Ltd. occupy positions that exemplify divergent feedstock strategies. Sasol's Secunda complex anchors synthetic diesel output through Fischer-Tropsch synthesis, while Astron Energy's Cape Town coastal facility represents hydrocracking-based supply. ENGEN PETROLEUM LTD sits within the inland retail network specialization, competing for procurement density around Gauteng pipeline termini. These three entities represent the competitive archetypes pressuring smaller wholesale distributors and independent retailers facing South African Bureau of Standards compliance costs.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Astron Energy (Pty) Ltd. |
| Sasol Limited |
| BP Southern Africa (Pty) Ltd. |
| Chevron Corporation |
| ENGEN PETROLEUM LTD |
| Shell Plc |
| South African Petroleum Refiners (SAPREF) |
| PetroSA |
| Others |
Value Network & Pricing Analysis
The Clean Fuels II sulphur specification regime gates both supply qualification and price differentiation across South Africa's downstream sector. Refiners who absorb desulphurization capex capture logistics priority through Transnet's pipeline network, while non-compliant product faces inland market exclusion and margin compression.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate procurement above spot market transactions. Price differentiation rests on cetane grade certification and volume scale, with Sasol's Fischer-Tropsch synthetic diesel commanding premiums for cold-start reliability. Cost compression in standard-grade diesel is intensifying because import dependency exposes working capital to exchange rate volatility. Mining haulage operators show least price sensitivity due to ventilation safety mandates, while independent retailers in the Eastern Cape face acute margin pressure from monthly South African Bureau of Standards audit compliance.
Supply Chain Analysis
South Africa and Mozambique anchor refined product supply through the Maputo Corridor and Durban-Richards Bay coastal terminals. Feedstock draws from Nigerian and Angolan crude streams, with specialized cobalt-molybdenum catalysts sourced from European and Asian suppliers. Single-coastal import vulnerability concentrates risk at Island View terminal during weather or labour disruptions. Distribution runs through Transnet's pipeline network terminating at Jameson Park and Alrode storage farms, with direct refinery-to-fleet contracts bypassing wholesale intermediaries for large consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's refined petroleum products market fragments across compliance tiers and geographic whitespace, with Clean Fuels II deadlines creating distinct competitive niches for prepared operators. Fleet procurement consolidation and agricultural mechanization outpacing retail infrastructure generate asymmetric entry points.
For Market Incumbents: Consolidate inland market position by securing pipeline-linked terminal capacity at Jameson Park and Alrode before import dependency deepens. Lock in long-term offtake agreements with mining houses to defend volume against wholesale margin compression. Hydrotreater catalyst inventory buffers represent the critical lever against 18-month supplier lead times that threaten refinery conversion timelines. For New Entrants and Emerging Players: Lead with mobile refuelling services and on-farm storage partnerships in Limpopo's grain and citrus belt, where fixed retail infrastructure lags agricultural expansion. Target direct supply contracts with mid-tier logistics fleets below 500 trucks that lack negotiating power for refinery offtake agreements. Biofuel blending mandate preparation offers regulatory-aligned positioning ahead of formal 10 percent ethanol and biodiesel implementation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrotreater-equipped refinery assets as Clean Fuels II deadlines harden. Vertically integrated operators with coastal hydrocracker units and inland synthetic capacity offer the strongest 5-10 year viability framing against stranded asset risk. Watch for delays in European and Asian catalyst delivery schedules as the inflection signal for supply security stress and import dependency acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Desulphurization Capacity Buildout | Locks in Clean Fuels II compliance and secures Transnet pipeline logistics priority for two decades. |
| Direct Refinery-to-Fleet Supply Agreements | Bypasses wholesale intermediaries for mining and logistics operators with 500-plus truck fleets. |
| Mobile Refuelling Infrastructure Deployment | Captures Limpopo agricultural whitespace where citrus and grain belt expansion outpaces fixed retail. |
| Biofuel Blending Infrastructure Investment | Positions ahead of Department of Mineral Resources and Energy's draft 10 percent ethanol mandate. |
| Pipeline Terminal Storage Expansion | Aggregates procurement density at Gauteng termini where 60 percent of national inland consumption concentrates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, refinery production disclosures, and South African Bureau of Standards fuel quality audit records. Interviews with fuel supply specialists at Transnet, procurement leads at mining houses, retail network operators, and Department of Mineral Resources and Energy policy officers combined with bottom-up volume triangulation against top-down macroeconomic indicators. Secondary validation drew from Eskom generation statistics, aviation turbine fuel throughput at OR Tambo International, and agricultural mechanization indices.
Segmentation dimensions modeled include product type, end user category, distribution channel, and application across the projection horizon. The analytical framework projected diesel, gasoline, jet fuel, and kerosene demand through mining haulage expansion rates, freight corridor growth, and renewable displacement in power generation. CAGRs derived from regression analysis of historical consumption patterns against refinery capacity utilization and import infrastructure readiness timelines.
The analysis sits within stated boundaries; outcomes outside coordinated capital deployment across the value chain or sustained crude price volatility would require recalibration. Forecasts reflect assumptions regarding Clean Fuels II implementation timing, Transnet pipeline integrity certification schedules, and catalyst supplier delivery reliability. Recalibration cycles align with material shifts in sulphur specification enforcement, renewable capacity additions, and exchange rate trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Base Oil Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Crude Oil Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Automotive Oil Strainer Market