
 Oil Dispensing Stations Market | 2026-2036
Oil Dispensing Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Dispensing Stations Market Analytics
Fleet operators is collapsing as the dominant buyer archetype in the oil dispensing stations landscape, while industrial lubrication users gain procurement momentum. Gilbarco Veeder-Root leverages its installed base across North American retail networks to sustain recurring service revenue. Dover Fueling Solutions anchors its position through integrated payment and wetstock management platforms. Tatsuno Corporation dominates Asian manufacturing scale for electronic dispensing hardware, competing on cost-engineered precision.
Oil dispensing stations are engineered fluid handling systems that meter, filter, and transfer petroleum-based lubricants or fuels from bulk storage to end-use equipment, typically operating at flow rates between 15 and 70 liters per minute with filtration thresholds of 10 to 25 microns. These installations serve to ensure contamination control, inventory accountability, and worker safety across commercial and industrial maintenance operations. Smart dispensing technology is displacing manual systems as fleet managers prioritize real-time consumption tracking and automated authorization protocols. Below ground installations retain structural preference in regulated urban environments where space constraints and fire codes limit above ground footprints, while mobile units capture growth in remote mining and construction logistics.
EPA underground storage tank regulations and OSHA workplace exposure standards shape equipment specifications and installation compliance timelines across the United States, with NHTSA commercial vehicle rules indirectly driving fleet-side demand for precision dispensing. China's MIIT and GB standards enforce metering accuracy and electromagnetic compatibility for domestic manufacturing certification, creating divergent compliance pathways for multinational suppliers. Stakeholders must weigh regulatory divergence against platform standardization as they configure product portfolios for cross-border deployment.
Market Dynamics
Fleet digitization mandates are compressing replacement cycles for legacy dispensing infrastructure as operators prioritize real-time consumption visibility over capital longevity. EPA underground storage tank regulations and China's GB standards are forcing synchronized hardware refreshes across North American and Asian installed bases.
Growth Catalysts
- Smart Dispensing Technology:IoT-enabled flow meters with automated authorization protocols are displacing mechanical systems in commercial fleet yards. Real-time inventory tracking reduces fuel theft and optimizes bulk purchasing cycles.
- OSHA Workplace Exposure Standards:Tighter vapor recovery and spill containment requirements in the United States are mandating equipment upgrades at aging installations. Compliance deadlines accelerate capital deployment.
- Commercial Vehicle Fleet Expansion:E-commerce logistics growth in China and Germany is driving demand for high-throughput dispensing systems capable of servicing 500+ vehicle fleets.
Market Restraints
- Stainless Steel Input Volatility:Dispensing system fabrication depends on grade 316 stainless steel, subject to nickel price swings that compress manufacturer margins.
- Supply Concentration in Asian Electronics:Printed circuit board and sensor module production clusters in Shenzhen and Taipei create single-source vulnerability for smart dispensing controllers.
- Legacy Infrastructure Lock-In:Below-ground tank compatibility constraints limit retrofit options for pre-2000 installations, extending replacement timelines.
Strategic Opportunities
- Remote Mining and Construction Logistics:Mobile dispensing units with solar-powered telemetry are penetrating Australian and Canadian extractive operations lacking fixed infrastructure.
- EU Green Deal Compliance:Carbon footprint reporting requirements are creating demand for dispensing systems with embedded emissions tracking and automated sustainability documentation.
- Industrial Lubrication Convergence:Integration of oil dispensing with predictive maintenance platforms is opening white space in German and Japanese precision manufacturing sectors.
Industry Challenges
- Certified Technician Scarcity:EPA Class A/B operator certification requirements and complex vapor recovery system diagnostics outpace training pipeline capacity in the United States.
- Legacy System Integration Complexity:Retrofitting smart dispensing hardware onto 1990s-era tank monitoring networks requires custom protocol bridges that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Dispensing Stations Market |
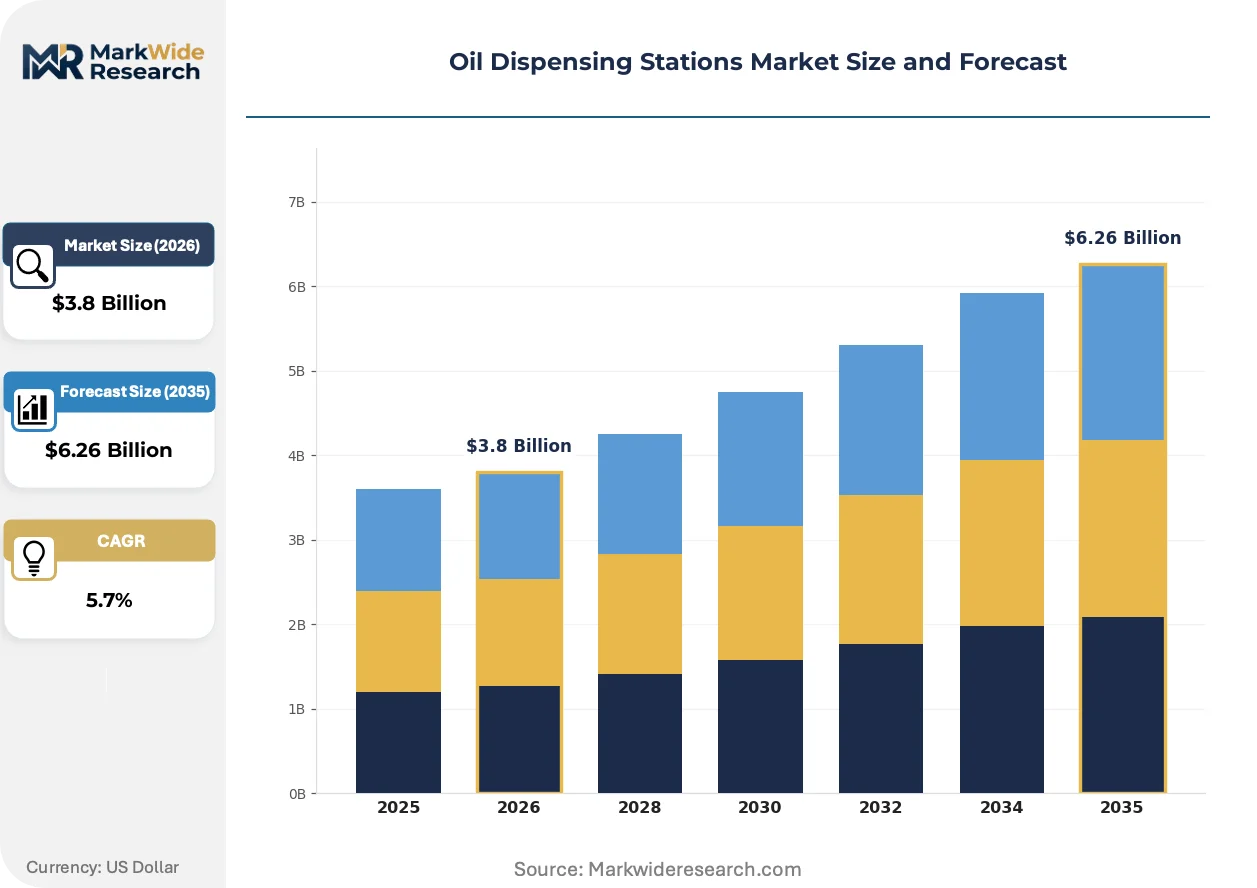
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Commercial, Retail, Industrial, Fleet Technology: Manual Dispensing, Electronic Dispensing, Automatic Dispensing, Smart Dispensing Application: Automotive, Heavy Machinery, Agricultural Equipment, Lubrication Installation: Above Ground, Below Ground, Mobile Units, Fixed Stations |
| Companies Covered | Gilbarco Veeder-Root, Inc., Dover Fueling Solutions, Inc., Franklin Fueling Systems, Inc., Tatsuno Corporation, Bennett Pump Company, Inc., Tokheim Group, Hectronic GmbH & Co. KG, Piusi SpA, Beijing Sanki Petroleum Technology Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Dispensing Stations Market Evolving Landscape
Digital fluid management architectures are redefining competitive differentiation as hardware commoditization accelerates. Vendors now compete on data platform sophistication rather than mechanical precision alone.
Cloud-native dispensing management software is fragmenting the traditional equipment-vendor relationship by enabling third-party analytics platforms to intermediate between hardware and fleet operators. Tier-1 logistics companies in Germany and the United States are piloting API-first consumption tracking that bypasses manufacturer-native dashboards. This interoperability pressure is compressing proprietary ecosystem margins and forcing incumbents to open data protocols.
EPA's 2025 underground storage tank corrosion protection mandates are accelerating fiberglass-reinforced plastic tank installations over steel alternatives. The regulatory timeline compresses replacement decisions for owners of single-wall steel tanks installed before 2009. California and Texas environmental agencies are enforcing earlier compliance deadlines than federal minimums, creating regional demand surges.
Fleet procurement departments are consolidating dispensing system vendors to capture volume-based service pricing and unified data reporting. Large national carriers in the United States are reducing approved supplier lists from twelve to three vendors, prioritizing those with integrated wetstock management and payment processing. This concentration dynamic favors vendors with nationwide service networks over regional specialists.
Oil Dispensing Stations Market Segmentation
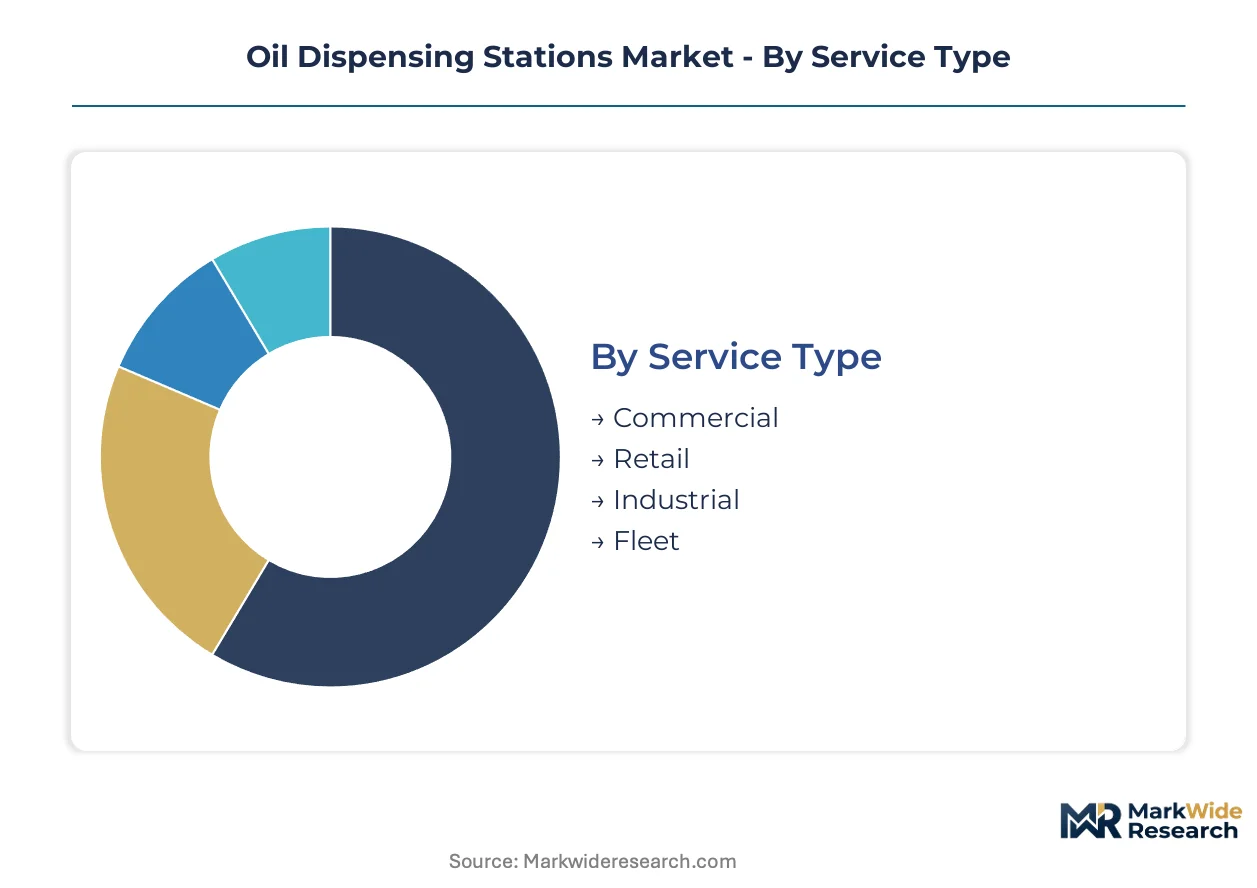
Oil dispensing stations serve divergent operational environments with distinct compliance footprints and capital intensity profiles. Segmentation reveals how technology tiers, installation constraints, and end-use specifications fragment procurement patterns across fleet, industrial, and retail channels.
Service Type:
EPA and OSHA standards in the United States enforce divergent spill containment and vapor recovery protocols across service tiers, creating compliance cost stratification that shapes vendor selection and installation timelines.
- Commercial:High-throughput installations serving 200+ vehicle fleets with integrated wetstock management and automated authorization. Fleet operators in Germany and the United States are consolidating vendor relationships to capture unified data reporting and volume-based service pricing.
- Industrial:Precision lubrication systems operating at 10-25 micron filtration thresholds for manufacturing maintenance. German and Japanese precision manufacturing sectors are driving integration with predictive maintenance platforms.
- Retail:Consumer-facing fuel dispensing with payment processing integration and regulatory compliance for underground storage.
- Fleet:Dedicated yard installations with real-time consumption tracking and theft prevention protocols for logistics operators.
Established volume favors Commercial; emerging adoption favors Industrial.
Technology:
Cost tiers separate legacy mechanical systems from connected platforms, with capital recovery periods and training requirements determining migration pace across end-user categories.
- Smart Dispensing:IoT-enabled architectures with cloud-native management software and API-first consumption tracking. Tier-1 logistics companies in Germany and the United States are piloting third-party analytics platforms that bypass manufacturer-native dashboards.
- Electronic Dispensing:Microprocessor-controlled flow metering with electromagnetic compatibility certification under China's GB standards. Tatsuno Corporation dominates Asian manufacturing scale for this hardware tier.
- Automatic Dispensing:Pre-set volume delivery with minimal operator intervention for standardized fleet servicing.
- Manual Dispensing:Mechanical pump systems with basic flow control, retaining presence in cost-sensitive emerging markets and legacy installations.
Procurement momentum concentrates in Smart Dispensing; replacement cycles sustain Electronic Dispensing.
Application:
Volume scale and contamination sensitivity create divergent specification requirements across equipment categories, with filtration thresholds and flow rate demands shaping hardware selection.
- Heavy Machinery:High-viscosity fluid handling at 50-70 liters per minute for mining and construction equipment. Mobile dispensing units with solar-powered telemetry are penetrating Australian and Canadian extractive operations lacking fixed infrastructure.
- Automotive:Standardized lubricant delivery for passenger and light commercial vehicle servicing. E-commerce logistics growth in China and Germany is driving demand for systems capable of servicing 500+ vehicle fleets.
- Agricultural Equipment:Seasonal demand patterns with corrosion-resistant specifications for outdoor installation environments.
- Lubrication:Precision dispensing for industrial maintenance with contamination control protocols and inventory accountability systems.
Heavy Machinery commands premium specifications; Automotive drives unit volume.
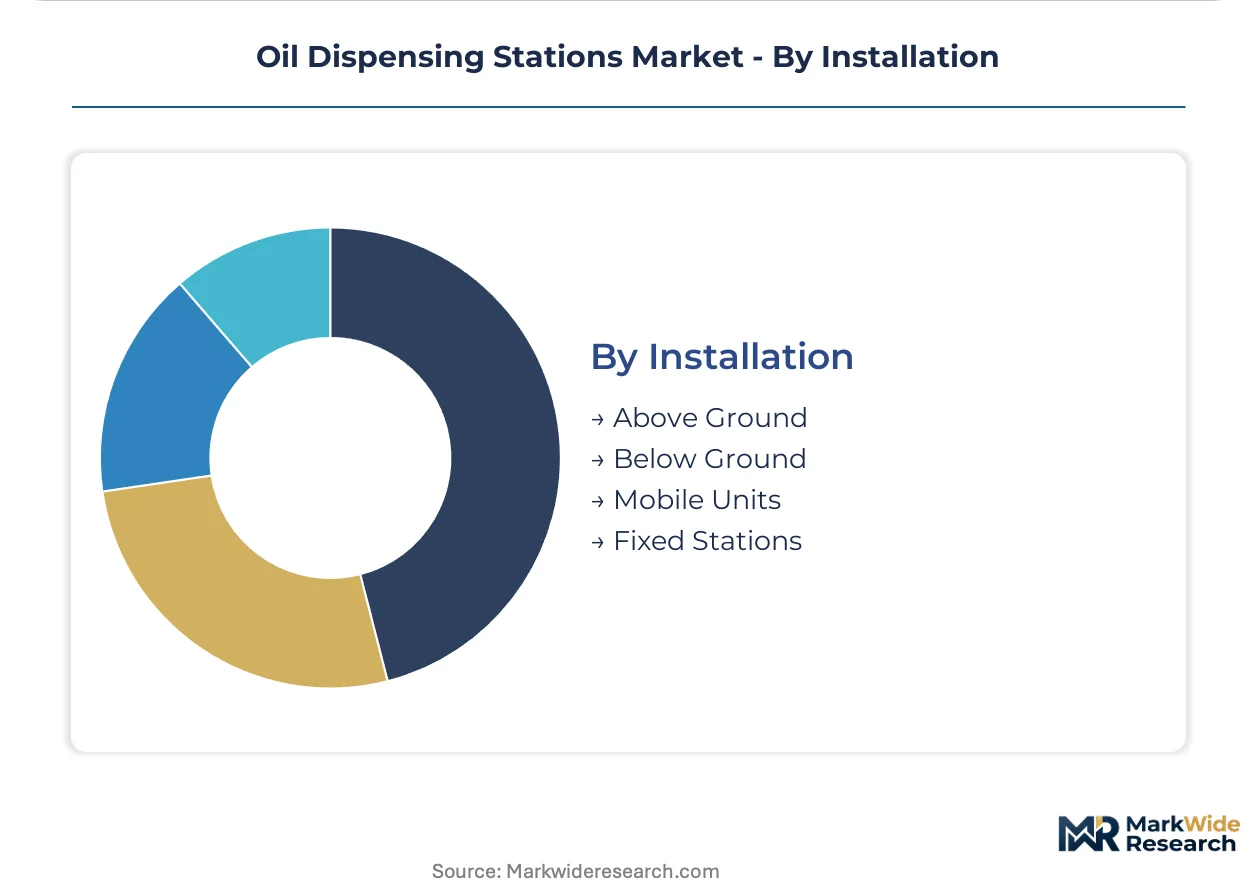
Installation:
Geography and regulatory environment determine structural preference, with fire codes and space constraints governing below-ground versus above-ground selection in urban versus remote settings.
- Below Ground:Tank installations preferred in regulated urban environments where space constraints and fire codes limit above-ground footprints. EPA's corrosion protection mandates are accelerating fiberglass-reinforced plastic tank installations over steel alternatives in the United States.
- Mobile Units:Self-contained dispensing systems for remote operations without fixed infrastructure. Australian and Canadian mining logistics are adopting solar-powered telemetry variants.
- Above Ground:Accessible tank configurations for industrial facilities with dedicated maintenance yards and lower regulatory density.
- Fixed Stations:Permanent installations with integrated storage, dispensing, and management infrastructure for high-volume commercial operations.
Below Ground retains structural preference in regulated markets; Mobile Units capture steepest expansion trajectory in extractive sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling capacity anchors European demand for advanced dispensing infrastructure, while China's West-East Pipeline Network underwrites Asia-Pacific procurement scale. Germany's Rhine-Main corridor and the United States' Colonial Pipeline system shape regional specification requirements.
United States
Commercial fleet yards serving e-commerce logistics hubs in Texas and California are consolidating vendor relationships to capture unified data reporting. EPA underground storage tank corrosion protection mandates are accelerating fiberglass-reinforced plastic tank installations over steel alternatives. The Permian Basin's remote extraction operations are adopting mobile dispensing units with solar-powered telemetry.
Germany
Precision manufacturing sectors in Bavaria and Baden-Württemberg are driving integration of oil dispensing with predictive maintenance platforms. EU Green Deal carbon footprint reporting requirements are creating demand for dispensing systems with embedded emissions tracking. The Rhine-Ruhr industrial corridor is concentrating procurement for high-throughput systems capable of servicing 500+ vehicle fleets.
China
E-commerce logistics expansion in the Yangtze River Delta and Pearl River Delta is driving fleet-side demand for smart dispensing technology. MIIT and GB standards enforce metering accuracy and electromagnetic compatibility for domestic manufacturing certification. Shenzhen's electronics production clusters supply printed circuit boards and sensor modules for smart dispensing controllers.
Australia
Remote mining operations in Western Australia's Pilbara region are penetrating with mobile dispensing units lacking fixed infrastructure. The country's national environmental regulator enforces spill containment protocols for extractive sector fluid handling. Queensland's Bowen Basin coal logistics are adopting solar-powered telemetry variants for seasonal equipment servicing.
Canada
Alberta's oil sands extraction logistics are deploying self-contained dispensing systems for heavy machinery maintenance cycles. Health Canada and provincial environmental agencies enforce vapor recovery requirements for commercial fuel handling. The Athabasca region's remote construction camps are driving procurement of above-ground tank configurations with lower regulatory density.
Oil Dispensing Stations Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform versus component specialization dimensions. The vendor base organizes around three tiers: multinational platform providers with recurring service revenue models, regional hardware fabricators competing on cost-engineered precision, and niche specialists targeting mobile or industrial lubrication segments. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing agreements that accelerate smart dispensing adoption without captive R&D investment.
Among North American platform providers, Gilbarco Veeder-Root and Dover Fueling Solutions exemplify the integrated service revenue archetype. Tatsuno Corporation anchors the Asian manufacturing scale tier. These three occupy positions that reflect divergent strategic bets: installed base leverage across retail networks, payment and wetstock management integration, and cost-engineered electronic hardware production respectively.
| Leading Market Players |
|---|
| Gilbarco Veeder-Root, Inc. |
| Dover Fueling Solutions, Inc. |
| Franklin Fueling Systems, Inc. |
| Tatsuno Corporation |
| Bennett Pump Company, Inc. |
| Tokheim Group |
| Hectronic GmbH & Co. KG |
| Piusi SpA |
| Beijing Sanki Petroleum Technology Co. Ltd |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for grade 316 stainless steel components concentrate pricing power with Asian mill operators and amplify margin compression for European fabricators during nickel price spikes. Fleet procurement consolidation in the United States and Germany rewards vendors with captive foundry capacity and punishes those exposed to spot-market metal sourcing.
Pricing Analysis
Three-tier pricing structure across premium smart-dispensing platforms, standard electronic systems, and economy manual units stratifies procurement decisions. Price differentiation hinges on EPA Class A/B operator certification bundling and wetstock management software integration. Cost compression in the economy tier is intensifying because Chinese manufacturers are flooding export markets with GB-certified hardware. Fleet operators exhibit the highest price sensitivity due to volume-based RFP processes, while precision manufacturing sectors in Germany prioritize contamination-control specifications over unit cost.
Supply Chain Analysis
Shenzhen-to-Taipei electronics corridors create single-source vulnerability for smart dispensing controllers and sensor modules. Component sourcing draws from China for printed circuit boards, Germany for precision filtration elements, and Japan for electromagnetic flow meters. Tariff exposure on steel inputs and semiconductor components threatens margin stability for North American fabricators. Distribution runs through authorized service networks that combine installation, EPA compliance certification, and recurring maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where EPA underground storage tank mandates and OSHA vapor recovery standards create forced-upgrade cycles that lock in incumbent service relationships. Switching costs compound through certified technician scarcity and legacy protocol integration complexity.
For Market Incumbents: Shield recurring revenue streams by embedding predictive maintenance APIs into fleet management platforms before third-party analytics vendors disintermediate hardware relationships. Acquire regional service specialists in Texas and California to capture EPA-mandated replacement surges ahead of compliance deadlines. Backward integration into fiberglass-reinforced plastic tank fabrication reduces exposure to steel price volatility and accelerates turnkey project delivery timelines. For New Entrants and Emerging Players: Lead with mobile dispensing units featuring solar-powered telemetry for Australian and Canadian extractive operations where fixed infrastructure gaps persist. Target industrial lubrication convergence in German precision manufacturing sectors where predictive maintenance platform integration remains underpenetrated. Pursue white-label partnerships with established wetstock management software providers to bypass proprietary ecosystem barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized dispensing divisions lacking smart-technology roadmaps. Long-term viability favors vendors with captive electronics sourcing and nationwide service network density. Monitor EPA regional enforcement variance between California, Texas, and federal minimum timelines as an inflection indicator for replacement demand clustering.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Dispensing Platform Integration | API-first architectures enable third-party analytics bypass of manufacturer-native dashboards. |
| Fiberglass Tank Manufacturing Scale-Up | EPA corrosion protection mandates accelerate substitution away from pre-2009 steel installations. |
| Mobile Unit Solar Telemetry Development | Solar-powered variants penetrate Australian Pilbara and Canadian Athabasca extractive logistics. |
| Predictive Maintenance Partnership | German precision manufacturing sectors demand lubrication-dispensing convergence with condition-monitoring platforms. |
| Certified Technician Training Pipeline | EPA Class A/B operator scarcity constrains deployment velocity and creates service-margin expansion. |
Research Methodology
A spread of perspectives from fleet operations directors, EPA compliance officers, industrial maintenance managers, and dispensing system procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement databases, OSHA workplace exposure standard filings, and customs records tracking grade 316 stainless steel import flows. Bottom-up unit economics triangulated against top-down infrastructure replacement cycles across the analysis window.
Segmentation dimensions modeled include service tier, technology architecture, application equipment category, and installation type across the projection horizon. CAGRs derived from replacement cycle compression rates, regulatory compliance deadline clustering, and fleet digitization mandate penetration curves. Forecast inputs incorporated MIIT certification timelines for Chinese manufacturing and EU Green Deal carbon reporting requirements for German industrial adoption.
Forecasts assume regulatory continuity in EPA underground storage tank regimes and OSHA vapor recovery standards; material policy shifts would require re-modeling. Nickel price volatility, Shenzhen electronics supply disruptions, and fleet procurement consolidation velocity represent specific revision triggers. Practitioners should keep alternative scenarios live as EPA regional enforcement variance and EU emissions documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Bunker Fuel Market
Fuels
China Bunker Fuel Market
Fuels
Gas Hydrates Market
Fuels
Coal Liquefaction Market
Fuels
Germany Bunker Fuel Market
Fuels
Gasoline Octane Improvers Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Electric Fuel Heater Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Collapsible Fuel Tank Market
Fuels
Briquette Market
Fuels
India Retail Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Emulsified Fuel Market
Fuels
Chafing Fuel Market
Fuels
Italy Chemical Logistics Market