
 Oil Refining Market | 2026-2036
Oil Refining Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Refining Market Analysis
Aviation fuel demand is rebalancing the end-use mix as post-pandemic aerospace recovery outpaces stagnant gasoline consumption in passenger vehicle fleets. ExxonMobil Corporation leverages its integrated downstream-chemicals footprint to capture margin across jet fuel and lubricant streams. Saudi Aramco anchors massive crude-to-chemicals complexes that convert straight-run barrels into higher-value petrochemical feedstock. Shell plc competes through its global trading and optimization desk, capturing arbitrage across Atlantic and Pacific basin refining margins.
Oil refining encompasses the thermal and catalytic processing of crude petroleum into transportation fuels, heating oils, and petrochemical precursors through fractional distillation, cracking, and treating units operating at temperatures exceeding 400°C and pressures above 150 psi. The primary commercial purpose centers on transforming heterogeneous crude slates into standardized, specification-grade products for mobility and industrial energy applications. Hydrocracking technology leads capital deployment as refiners seek maximum middle-distillate yield from heavier sour crudes, while catalytic cracking sustains gasoline output in markets where spark-ignition engines retain vehicle parc dominance. The automotive end-user segment remains the largest volume sink but faces structural pressure from electrification, whereas the marine segment is growing fastest as low-sulfur fuel oil demand accelerates under environmental mandates.
The US EPA Tier 3 gasoline sulfur program and the EU F-Gas Regulation constrain product specifications and process emissions, compelling refiners to invest in hydrotreater capacity and carbon capture retrofits. China's MEE enforces national VI fuel standards that tighten benzene and aromatics limits, reshaping catalyst procurement and crude slate selection for domestic operators. India's BIS certification for automotive fuels and the country's PLI scheme for specialty chemicals are redirecting Reliance Industries Limited and public sector refiners toward downstream integration. Stakeholders must monitor carbon border adjustment mechanisms and low-carbon fuel standard adoption to time refinery retrofit cycles and product portfolio pivots.
Market Dynamics
Refinery economics are compressing as electrification erodes gasoline demand while marine and aviation fuel specifications tighten, forcing capital reallocation toward residue upgrading and middle-distillate maximization.
Growth Catalysts
- IMO 2020 Sulfur Caps:The International Maritime Organization's 0.5% sulfur limit on bunker fuels has created sustained demand for very low sulfur fuel oil and marine gasoil, driving hydrotreater investments at coastal refineries.
- India:The country's BIS VI emission standards and expanding vehicle parc are pulling incremental refining capacity additions ahead of domestic demand growth, with public sector refiners expanding distillation capacity.
- Hydrocracking Technology:Advanced hydrocracking units enable maximum diesel and jet fuel yield from heavy sour crudes, improving margin capture as crude slates grow heavier globally.
Market Restraints
- Crude Slate Volatility:Differential volatility between light sweet and heavy sour grades compresses cracking margins unpredictably, complicating refinery feedstock procurement and hedging strategies.
- Electrification Substitution:Battery electric vehicle penetration in passenger transport is structurally displacing gasoline demand in OECD markets, stranding catalytic reformer and FCC capacity.
- US EPA Tier 3:The gasoline sulfur program mandates 10 ppm average sulfur content, requiring additional hydrotreating investment that raises operating costs without corresponding product price recovery.
Strategic Opportunities
- Crude-to-Chemicals:Integrated complexes that bypass fuel production in favor of direct petrochemical feedstock output capture premium margins from polyethylene and aromatics demand in Asia-Pacific.
- Sustainable Aviation Fuel:Hydroprocessed esters and fatty acids pathways using renewable feedstocks qualify for EU ETS exemptions and national blending mandates, opening new product slate diversification.
- Carbon Capture Retrofits:Refinery CO2 capture for enhanced oil recovery or sequestration qualifies for US IRA tax credits and EU Innovation Fund support, improving project returns on marginal capacity.
Industry Challenges
- Process Control Engineering Talent:Advanced process control and digital twin implementation require specialized automation expertise that refiners struggle to attract against technology sector compensation.
- Turnaround Coordination:Synchronized maintenance of integrated process units demands precise contractor scheduling and spare parts logistics, with delays cascading through downstream production.
- EU F-Gas Compliance:Refrigerant management in cryogenic gas processing units faces phase-down schedules that complicate maintenance planning and require refrigerant substitution investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Refining Market |
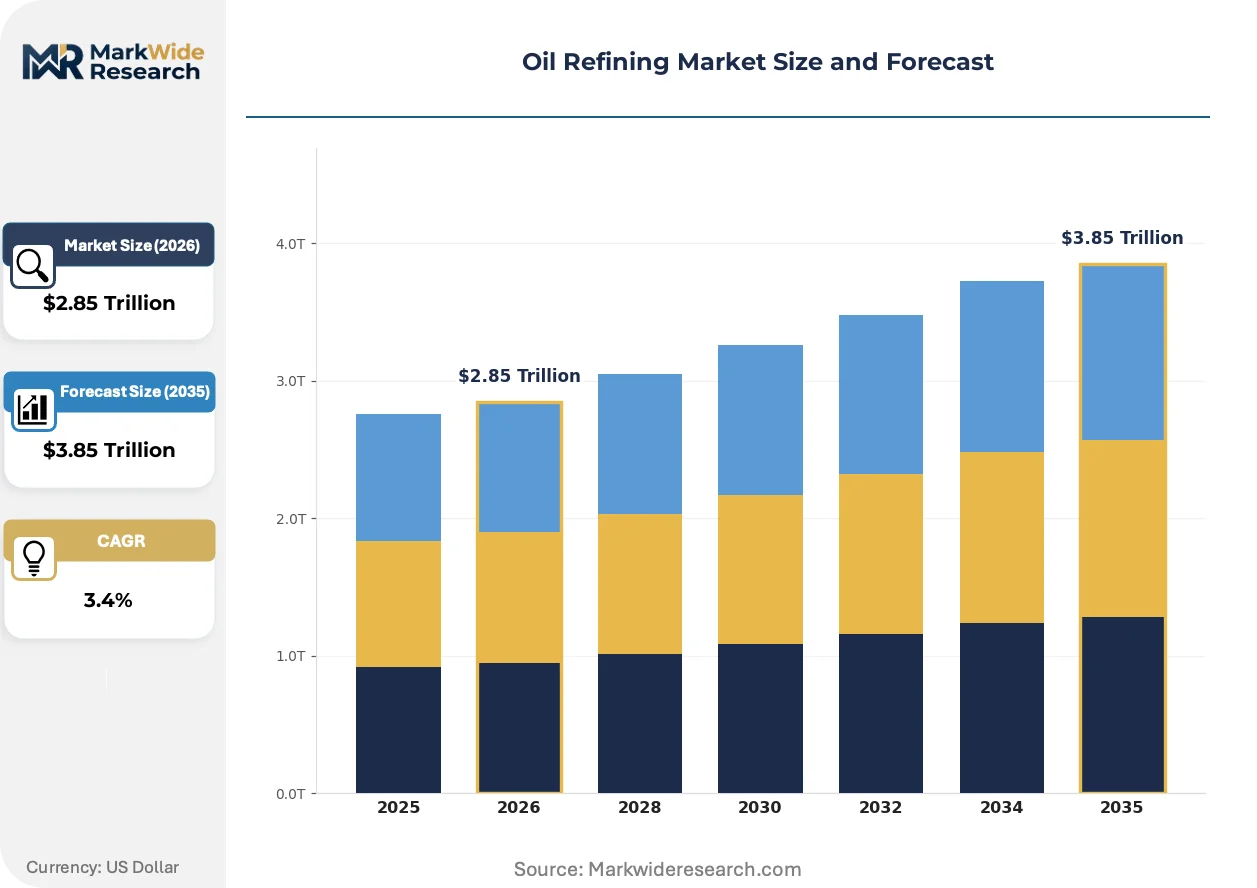
| Market Size in 2026 | $2.85 Trillion |
| Market Size in 2035 | $3.85 Trillion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Technology: Hydrocracking, Distillation, Alkylation, Catalytic Cracking End User: Automotive, Aerospace, Marine, Industrial Service Type: Maintenance, Consultancy, Design, Installation |
| Companies Covered | Sinopec Corp., BP plc, ExxonMobil Corporation, Phillips 66, Valero Energy Corporation, Saudi Aramco, Marathon Petroleum Corporation, Reliance Industries Limited, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Refining Market Emerging Trajectories
Refining technology is pivoting from fuel maximization toward molecular management, with digital optimization and carbon intensity reduction becoming primary investment criteria alongside traditional yield metrics.
Electrification of process heat is expanding into crude distillation and reforming units as refiners seek to reduce Scope 1 emissions and qualify for low-carbon product certifications. European operators are piloting electrode boilers and electric-fired heaters to replace natural gas combustion in preheat trains. This technology is expanding into markets with high renewable electricity penetration, creating new load profiles for grid operators and reshaping refinery energy cost structures.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules for cryogenic gas processing and LNG import terminals, forcing adoption of lower-GWP alternatives like hydrofluoroolefins or ammonia systems. Industrial consequence includes accelerated capital replacement cycles for cold boxes and heat exchangers. Marine fuel and petrochemical feedstock terminals in Rotterdam and Antwerp are most affected, with operators retrofitting storage and vapor recovery systems to maintain operating permits.
After-sales service unbundling is fragmenting the traditional lump-sum catalyst supply contract into separate procurement of base metals, catalyst formulation, and technical services. Refiners are directly sourcing alumina and zeolite substrates while licensing proprietary formulations from technology licensors, compressing margins for integrated catalyst suppliers. This pattern is most visible in North American FCC and hydrotreating operations, where large independent refiners possess in-house technical capabilities to manage catalyst lifecycle optimization.
Oil Refining Market Segmentation
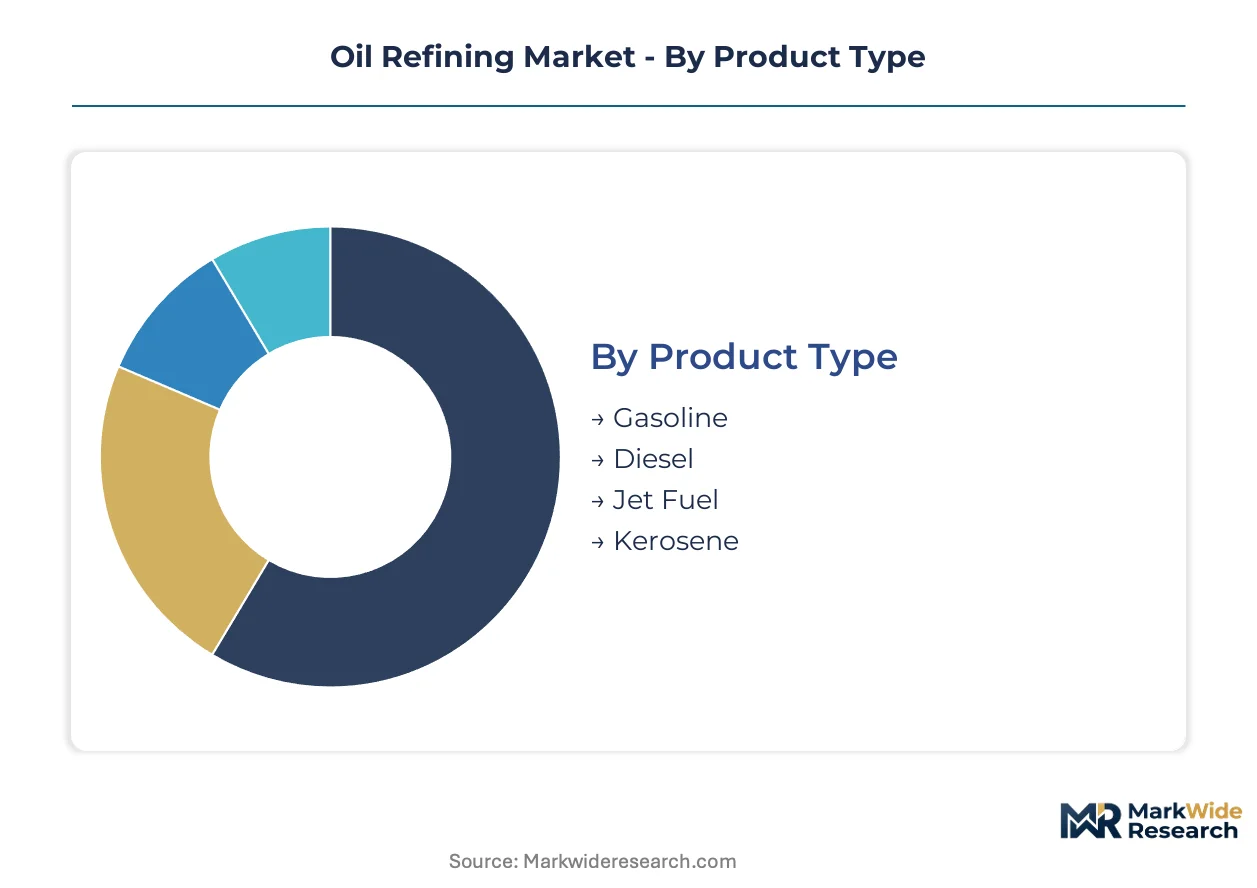
Refining configurations diverge sharply across product slates, processing intensities, and customer integration levels. Each segmentation axis reveals distinct margin structures and capital deployment patterns that shape competitive positioning.
Product Type:
Standardization dominates light distillates while residue upgrading demands bespoke unit configurations tailored to crude slate heterogeneity.
- Gasoline:Catalytic reforming and alkylation produce high-octane blending components for spark-ignition engines. Demand concentrates in India and the United States where vehicle parc expansion outpaces electrification penetration, though EPA Tier 3 sulfur limits compress blending flexibility.
- Diesel:Hydrocracking and hydrotreating yield ultra-low sulfur distillate for compression-ignition engines and industrial power generation. India's BIS VI standards and EU F-Gas-linked carbon intensity schemes are pulling investment toward cetane enhancement and cold-flow improver integration.
- Jet Fuel:Kerosene-range hydroprocessed streams meeting ASTM D1655 and DEF STAN 91-91 specifications. Sustainable aviation fuel co-processing is expanding at Singapore and Rotterdam hubs.
- Kerosene:Straight-run or hydrotreated middle distillate for heating and lighting applications, concentrated in Japan and South Korea for residential and commercial energy.
Most installed capacity flows through gasoline. Expansion is steepest in jet fuel as long-haul aviation recovers and sustainable blending mandates proliferate.
Technology:
Capital intensity stratifies from atmospheric distillation at the low end to residue hydrocracking requiring hydrogen integration and complex catalyst management.
- Hydrocracking:Dual-function catalytic processing combining cracking and hydrogenation in single-reactor or two-stage configurations. Saudi Aramco's crude-to-chemicals complexes and Reliance Industries' Jamnagar expansion anchor maximum middle-distillate yield from heavy sour feedstocks.
- Distillation:Atmospheric and vacuum fractionation separating crude into boiling-range cuts without chemical transformation. China's MEE-licensed refiners in Shandong and Guangdong leverage this baseline technology for straightforward fuel oil and naphtha production.
- Alkylation:Acid-catalyzed combination of olefins and isobutane to produce high-octane alkylate for gasoline blending. North American independent refiners favor sulfuric acid processes for octane recovery.
- Catalytic Cracking:Fluidized bed zeolite cracking of vacuum gas oil to gasoline and light olefins. FCC units face utilization pressure as gasoline demand peaks in OECD markets.
Distillation handles the largest crude throughput volumes. Hydrocracking is climbing the fastest as residue upgrading becomes economically essential under marine sulfur regulations.
End User:
Customer integration depth varies from spot-market commodity offtake to long-term tolling arrangements with dedicated pipeline connections.
- Automotive:Retail and wholesale distribution of gasoline and diesel through branded and unbranded station networks. India's expanding highway corridor and China's provincial fuel standard enforcement sustain volume.
- Aerospace:Into-plane fueling services and long-term supply contracts with international carriers and national flag airlines. Singapore Changi and Dubai International anchor Asia-Pacific and Middle East jet fuel demand.
- Marine:Bunker fuel supply at major port hubs including Rotterdam, Singapore, and Houston under IMO 2020 very low sulfur fuel oil specifications.
- Industrial:Direct fuel oil and naphtha offtake by petrochemical crackers, power generators, and metals processors. Reliance Industries and Saudi Aramco integrate this segment through captive consumption.
Automotive offtake retains the largest volume share. Marine is expanding most quickly as low-sulfur fuel oil demand accelerates and scrubber retrofit cycles complete.
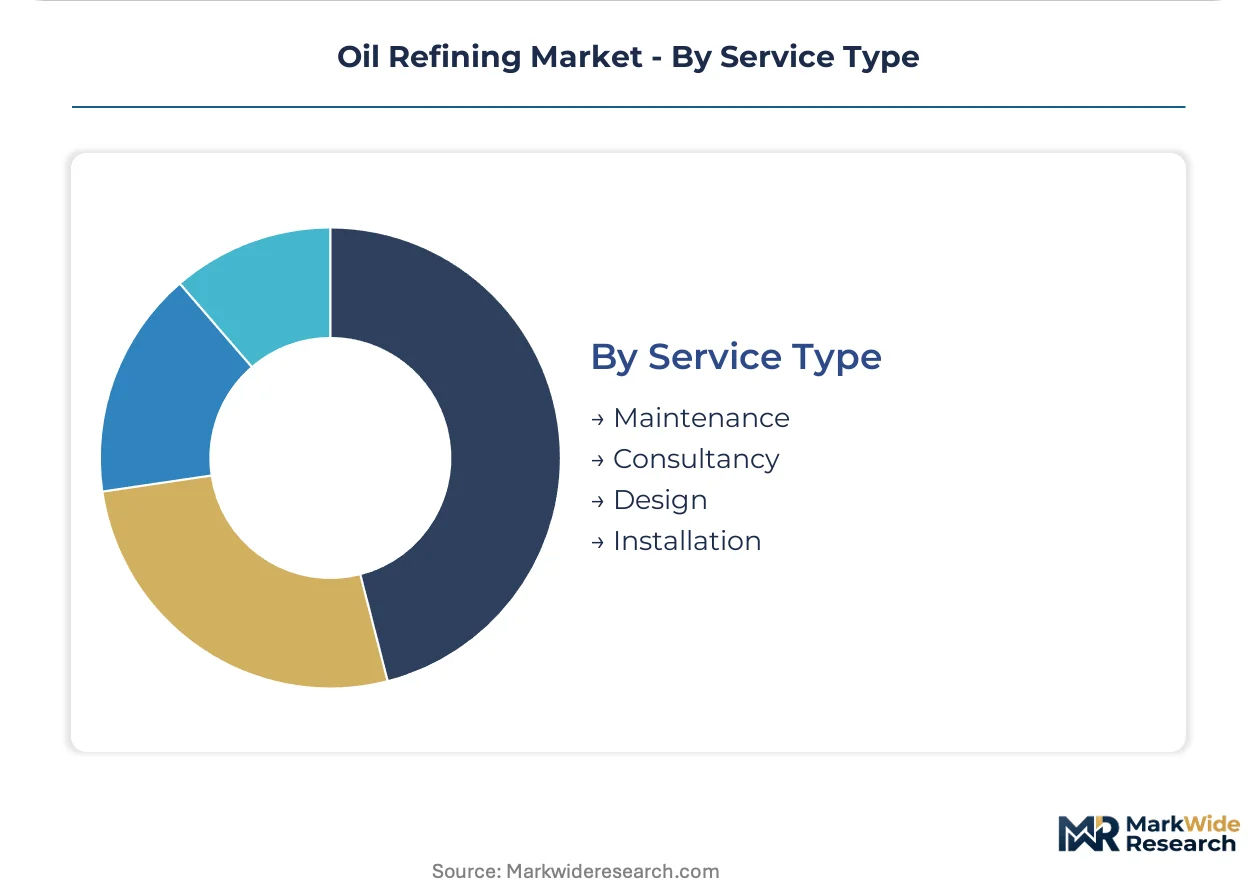
Service Type:
Procurement patterns split between lump-sum EPC contracts for greenfield units and performance-based maintenance agreements for operating assets.
- Maintenance:Turnaround planning, catalyst replacement, and integrity management for hydrocrackers, FCCs, and hydrotreaters. US Gulf Coast refiners favor multi-year service agreements with specialized contractors.
- Consultancy:Process optimization, crude slate selection advisory, and regulatory compliance strategy. European operators engage consultancies for EU ETS carbon accounting and F-Gas transition planning.
- Design:Front-end engineering and process licensing for capacity expansions and residue upgrading retrofits. Technology licensors compete on hydrocracking catalyst formulations and reactor configurations.
- Installation:Field construction and commissioning of process units, storage tanks, and emissions control systems. India's public sector refiners source installation services through domestic engineering contractors.
Maintenance captures the largest service expenditure. Design is gaining share fastest as crude-to-chemicals conversions and carbon capture retrofits multiply project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery investment migrates toward jurisdictions where carbon border costs remain unenforced and fuel specification gaps preserve margin capture. The United States, China, India, Saudi Arabia, and the Netherlands concentrate capacity additions that exploit this regulatory-arbitrage window.
United States
Gulf Coast export-oriented refiners process discounted domestic shale crudes into diesel and jet fuel for Latin American offtake. EPA Tier 3 gasoline sulfur mandates compress blending economics for inland operators. The Houston Ship Channel and Port Arthur complex anchor the world's largest concentration of coking and hydrocracking capacity.
China
Shandong and Guangdong province refiners expand distillation capacity ahead of domestic demand growth in highway freight and aviation. MEE enforces national VI fuel standards that tighten benzene and aromatics limits, reshaping catalyst procurement. The Yangtze River Delta cluster concentrates integrated refining-petrochemical complexes serving polyethylene demand.
India
Public sector refiners expand distillation capacity along the west coast to serve BIS VI emission standards and expanding vehicle parc. The PLI scheme for specialty chemicals redirects Reliance Industries and downstream operators toward petrochemical integration. The Jamnagar complex in Gujarat anchors the country's largest crude-to-chemicals conversion capacity.
Saudi Arabia
Crude-to-chemicals complexes convert straight-run barrels directly into petrochemical feedstock, bypassing fuel production entirely. SFDA and national industrial development frameworks support integrated downstream investments. The Jubail and Yanbu industrial cities on the Persian Gulf concentrate residue upgrading and aromatics production capacity.
Netherlands
Rotterdam and Antwerp terminals face accelerated refrigerant replacement cycles under EU F-Gas Regulation phase-down schedules for cryogenic gas processing. Low-sulfur fuel oil demand from IMO 2020 compliance drives hydrotreater investments at coastal facilities. The Port of Rotterdam cluster serves as Europe's largest marine bunkering and petrochemical feedstock distribution hub.
Oil Refining Market Vendor Landscape
Crude-to-chemicals conversion dominates the current landscape as integrated operators bypass commoditized fuel markets. The structure consolidates around national oil companies with captive crude supply and independent refiners with coastal logistics access. Three archetypes define positioning: integrated majors with chemicals footprint, state-owned crude producers with downstream extension, and merchant refiners with trading optimization capabilities. Capacity expansion and residue upgrading retrofits constitute the primary competitive moves, followed by sustainable aviation fuel co-processing investments.
Among integrated majors, ExxonMobil Corporation and Shell plc exemplify the downstream-chemicals integration archetype. ExxonMobil leverages its global trading and optimization desk to capture arbitrage across Atlantic and Pacific basin refining margins. Shell competes through lubricant and jet fuel stream integration. Saudi Aramco anchors the state-owned producer archetype through massive crude-to-chemicals complexes. Reliance Industries Limited occupies the merchant refiner position with Jamnagar serving as a global pivot for residue upgrading and petrochemical feedstock supply.
| Leading Market Players |
|---|
| Sinopec Corp. |
| BP plc |
| ExxonMobil Corporation |
| Phillips 66 |
| Valero Energy Corporation |
| Saudi Aramco |
| Marathon Petroleum Corporation |
| Reliance Industries Limited |
| Shell plc |
| Others |
Supply Flow & Price Mechanics
Brent crude futures and regional sour crude differentials cascade through refinery gate pricing into product slate premiums, with hydrocracker output commanding spreads over straight-run fuel oil as residue upgrading investments concentrate margin capture in India, China, and Saudi Arabia.
Pricing Analysis
Direct-to-airline offtake contracts and marine bunker spot markets split pricing architecture between long-term tolling arrangements and commodity-indexed transactions. Three-tier pricing structure across premium jet fuel, standard diesel, and economy fuel oil reflects cetane indices, sulfur content, and cold-flow property differentials. Pricing pressure stems from electrification-driven gasoline demand erosion in OECD markets, compressing catalytic cracking margins. Independent refiners exhibit highest price sensitivity due to crude procurement hedging limitations, while integrated majors with captive production absorb volatility through upstream-downstream netting.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and China's domestic catalyst manufacturing mandates are redirecting procurement toward local zeolite and alumina substrate suppliers, reducing import dependency for refinery process units. Supply concentration centers on China for hydrotreating catalysts, the Netherlands for cryogenic gas processing equipment, and the United States for advanced process control systems. Raw material flows draw from Saudi heavy sour crude, Russian Urals blends, and domestic shale condensates. Single-source vulnerability persists in specialized hydrogen plant equipment. Distribution runs through coastal tanker terminals and dedicated pipeline corridors to petrochemical crackers and airport fueling systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where residue upgrading investments in Saudi Arabia and India exploit cost differentials against EU F-Gas compliance burdens and carbon border adjustment exposure in Rotterdam and Antwerp.
For Market Incumbents: Anchor margin defense through crude-to-chemicals conversion capacity at Jubail and Jamnagar, capturing polyethylene and aromatics premiums as gasoline demand peaks. Backward integration into hydrogen production secures hydrocracker feedstock against electrolysis cost inflation. Prioritize sustainable aviation fuel co-processing qualifications for EU ETS exemption eligibility.
For New Entrants and Emerging Players: Enter via modular hydroskimming units serving BIS VI diesel demand in India's western coastal corridor, where public sector capacity additions lag vehicle parc expansion. Target marine gasoil supply at secondary port hubs bypassing Singapore and Rotterdam concentration. Pursue tolling arrangements with stranded FCC assets seeking residue upgrading retrofit partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with merchant refiners possessing coastal logistics access and trading optimization desks capable of Atlantic-Pacific arbitrage. Long-term viability hinges on carbon capture retrofit completion and sustainable fuel certification pipelines. Monitor EU Innovation Fund disbursement velocity as inflection indicator for project finance availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Retrofit | Hydrocracker investments at coastal refineries capture IMO 2020 marine fuel premiums. |
| Crude-to-Chemicals Conversion | Integrated complexes bypass commoditized gasoline markets for polyethylene feedstock margins. |
| Sustainable Aviation Fuel Co-processing | HEFA pathway qualification secures EU ETS exemptions and national blending mandate compliance. |
| Carbon Capture Retrofit | Refinery CO2 capture qualifies for US IRA tax credits and EU Innovation Fund support. |
| After-sales Service Unbundling | Direct substrate procurement compresses integrated catalyst supplier margins in North America. |
Methodological Framework
Bottom-up automotive and aerospace fuel consumption modeling reconciled against top-down refinery capacity and utilization tracking forms the analytical core of this study. Primary interviews with refinery operations managers, catalyst procurement leads, marine fuel traders, and petrochemical cracker operators combined with secondary validation from EIA data, IEA oil market reports, customs trade flows, and SEC refiner filings. Triangulation across stakeholder inputs and statistical sources ensures segmentation integrity.
Historical throughput and margin trendline analysis informs projection frameworks across the modeling period, with CAGR derivation reflecting technology deployment curves and regulatory phase-in schedules. Segmentation dimensions encompass product type, processing technology intensity, end-user integration depth, and regional regulatory cluster. Forecast inputs incorporate crude slate heavification trajectories, hydrogen supply cost curves, and sustainable fuel mandate adoption patterns.
The model holds under stable IMO sulfur enforcement and continued aviation demand recovery; deviation in carbon border adjustment implementation velocity or battery electric vehicle penetration acceleration would shift refinery utilization assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
India White Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Crude Oil Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market