
 Fuel Cell Stack Market | 2026-2036
Fuel Cell Stack Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Stack Market Intelligence
The fuel cell stack landscape is restructuring around a widening gap between premium PEM systems engineered for automotive-grade durability and commodity-oriented alkaline units serving stationary backup applications. Ballard Power Systems dominates the premium transportation tier through captive supply of membrane electrode assemblies. Plug Power anchors the material handling segment through backward integration into green hydrogen production and distribution infrastructure. Cummins competes across both tiers, leveraging its diesel engine service network to penetrate commercial vehicle retrofit markets.
A fuel cell stack is an electrochemical device that converts hydrogen and oxygen into electricity through layered assemblies of bipolar plates, membrane electrode assemblies, and gas diffusion layers, typically operating at voltages from 0.6 to 0.8 volts per cell with power densities exceeding 2.5 kW per liter in advanced PEM configurations. Its primary commercial purpose is to deliver continuous, zero-emission electrical power for mobility, stationary generation, and portable equipment where battery weight or recharge cycles impose operational constraints. Proton exchange membrane stacks command the dominant share of transportation applications due to their cold-start capability and power density advantages, while solid oxide systems occupy the highest-temperature stationary segment where combined heat and power efficiency exceeds 80 percent. Alkaline technology leads in cost-sensitive backup power installations where platinum-free catalysts reduce material costs by substantial margins.
The US Department of Energy and the EPA coordinate hydrogen infrastructure standards that dictate stack durability targets and refueling protocol compatibility for interstate commercial deployment. Japan's METI enforces JIS standards for stationary fuel cell safety and performance that constrain market entry for uncertified foreign suppliers. China's MIIT administers GB standards and dual carbon goals that mandate domestic stack localization rates above thresholds for subsidy eligibility. Stakeholders must monitor how tightening catalyst material sourcing rules and evolving certification reciprocity agreements between these jurisdictions reshape supply chain configuration decisions.
Market Dynamics
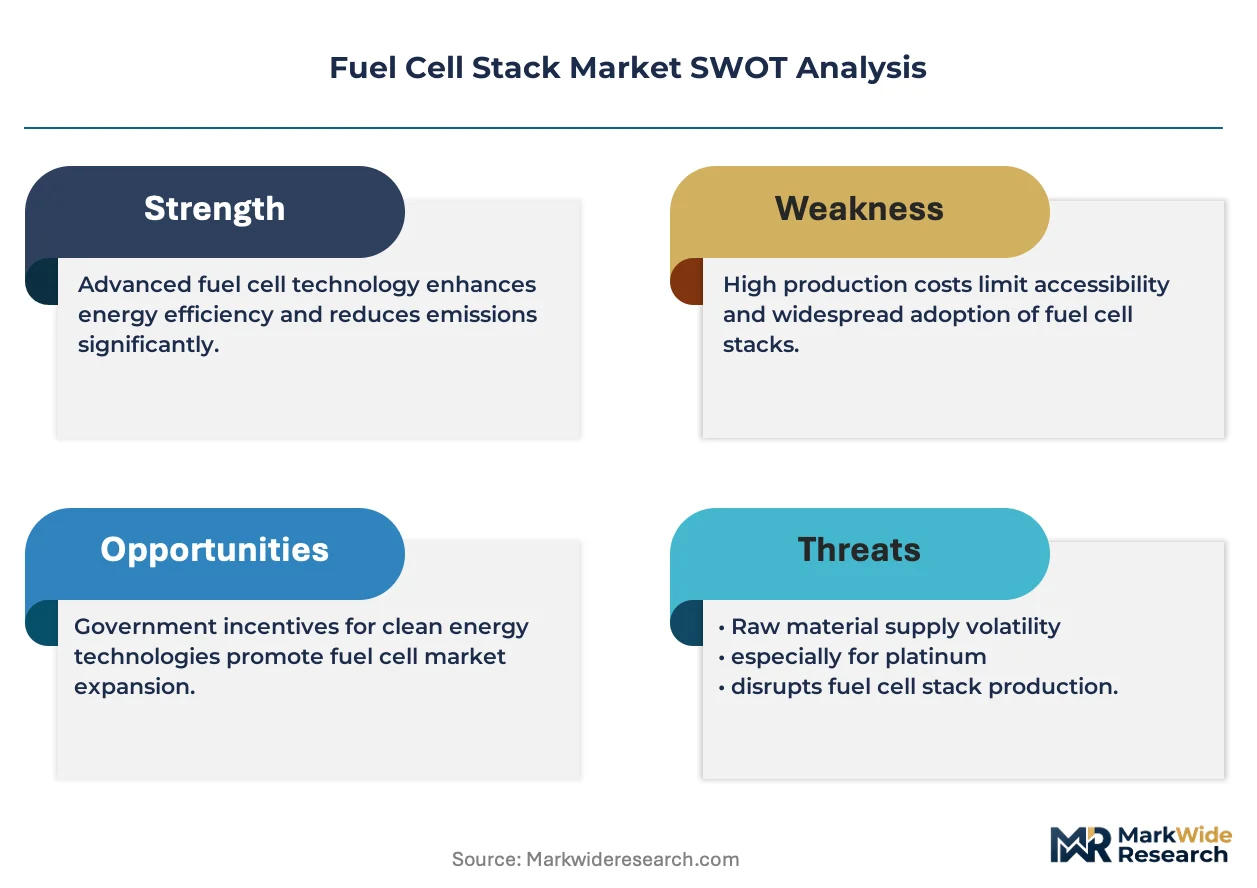
Capital allocation in fuel cell stack manufacturing is bifurcating around the US Inflation Reduction Act hydrogen production tax credits, which are pulling investment toward domestic PEM stack assembly while compressing alkaline system margins in cost-sensitive backup power segments.
Growth Catalysts
- US IRA hydrogen incentives:The production tax credit structure is accelerating capital commitments toward domestic manufacturing scale-up for heavy-duty transportation applications.
- Logistics fleet electrification:Heavy-duty commercial vehicles in freight corridors are emerging as the primary demand anchor for high-durability PEM stack deployments.
- Platinum group metal recycling:Closed-loop catalyst recovery systems are reducing feedstock cost volatility and tightening supply security for membrane electrode assembly producers.
Market Restraints
- Iridium supply concentration:South African and Russian mining operations control over 80 percent of global iridium output, creating vulnerability for PEM stack catalyst loading costs.
- GB standards localization mandates:China's MIIT domestic content thresholds for subsidy eligibility are fragmenting global supply chain configurations and raising compliance overhead for foreign stack suppliers.
- Battery energy density improvement:Lithium-ion pack-level densities exceeding 300 Wh/kg are narrowing the operational gap for medium-duty urban delivery routes previously targeted by fuel cell retrofit programs.
Strategic Opportunities
- Maritime auxiliary power:Harbor craft and short-sea shipping vessels in European port clusters represent an underpenetrated addressable load profile for solid oxide stack integration.
- Data center tri-generation:Combined cooling, heat, and power configurations using high-temperature fuel cells are capturing hyperscale facility procurement evaluations in Nordic and Singaporean markets.
- Green hydrogen offtake contracting:Long-term electrolyzer-stack paired supply agreements are creating captive demand channels that bypass spot hydrogen market price volatility.
Industry Challenges
- Membrane electrode assembly technician scarcity:Thin-film coating and catalyst deposition expertise remains concentrated among a limited pool of specialized manufacturing engineers, constraining qualified facility expansion.
- Interoperability certification timelines:SAE J2601 fueling protocol validation and EPA heavy-duty engine certification sequences are extending product launch cycles by 18-24 months for new stack platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Stack Market |
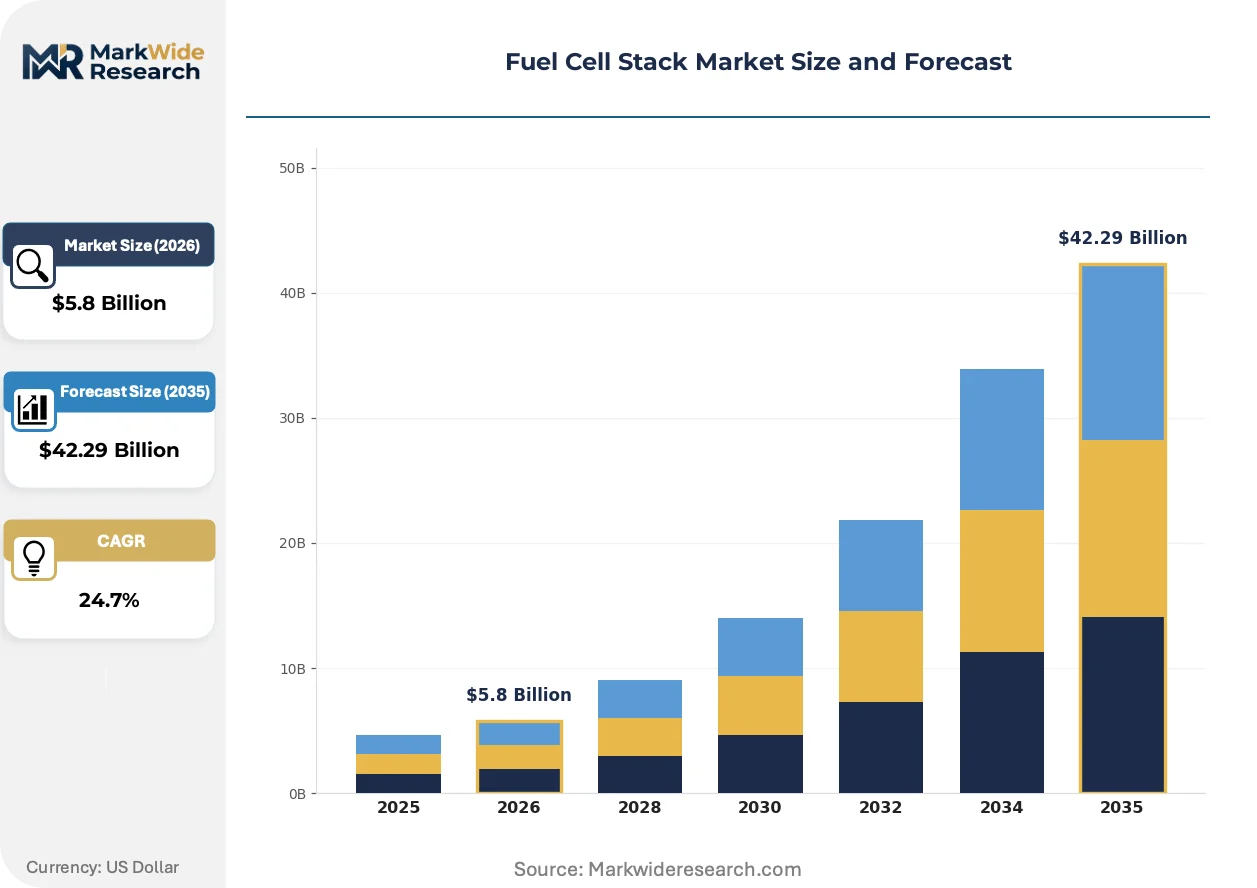
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $42.29 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid, Molten Carbonate Application: Material Handling Equipment, Backup Power, Residential Power, Portable Power, Telecommunication Power End User: Commercial Vehicles, Residential Buildings, Data Centers, Military Facilities, Remote Locations Technology: PEM, SOFC, AFC, PAFC, MCFC |
| Companies Covered | FuelCell Energy, Cummins, Ballard Power Systems, AISIN Corporation, AFC Energy, Plug Power, Doosan Fuel Cell, Ceres Power, Bloom Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Stack Market Strategic Shifts & Innovations
Stack architecture is converging around modular platform designs that decouple bipolar plate stamping from final cell assembly, enabling geographic production flexibility and faster response to regional certification requirements.
Platinum-free alkaline membrane technology is rewriting cost structures for stationary backup installations. Chinese and Korean system integrators are adopting these stacks for telecommunications tower power supplies. The elimination of precious metal catalysts is compressing upfront capital requirements to parity with diesel generator sets in 100-500 kW output ranges.
Japan's METI has tightened JIS C 8802 stationary fuel cell safety standards to require enhanced hydrogen detection response times below 500 milliseconds. Stack manufacturers serving the Japanese residential market are redesigning gas diffusion layer interfaces to meet the accelerated shutdown protocols. The revised certification is forcing non-domestic suppliers to establish local testing partnerships or cede position in the 1-5 kW residential segment.
Asset-light hydrogen-as-a-service contracting is displacing direct equipment purchases in material handling fleets. Forklift operators in North American distribution centers are shifting toward fixed monthly fees covering stack, storage, and refueling infrastructure. California's LCFS credit stacking rules are amplifying this preference by improving project finance terms for third-party fleet operators over captive hydrogen production investments.
Fuel Cell Stack Market Segmentation
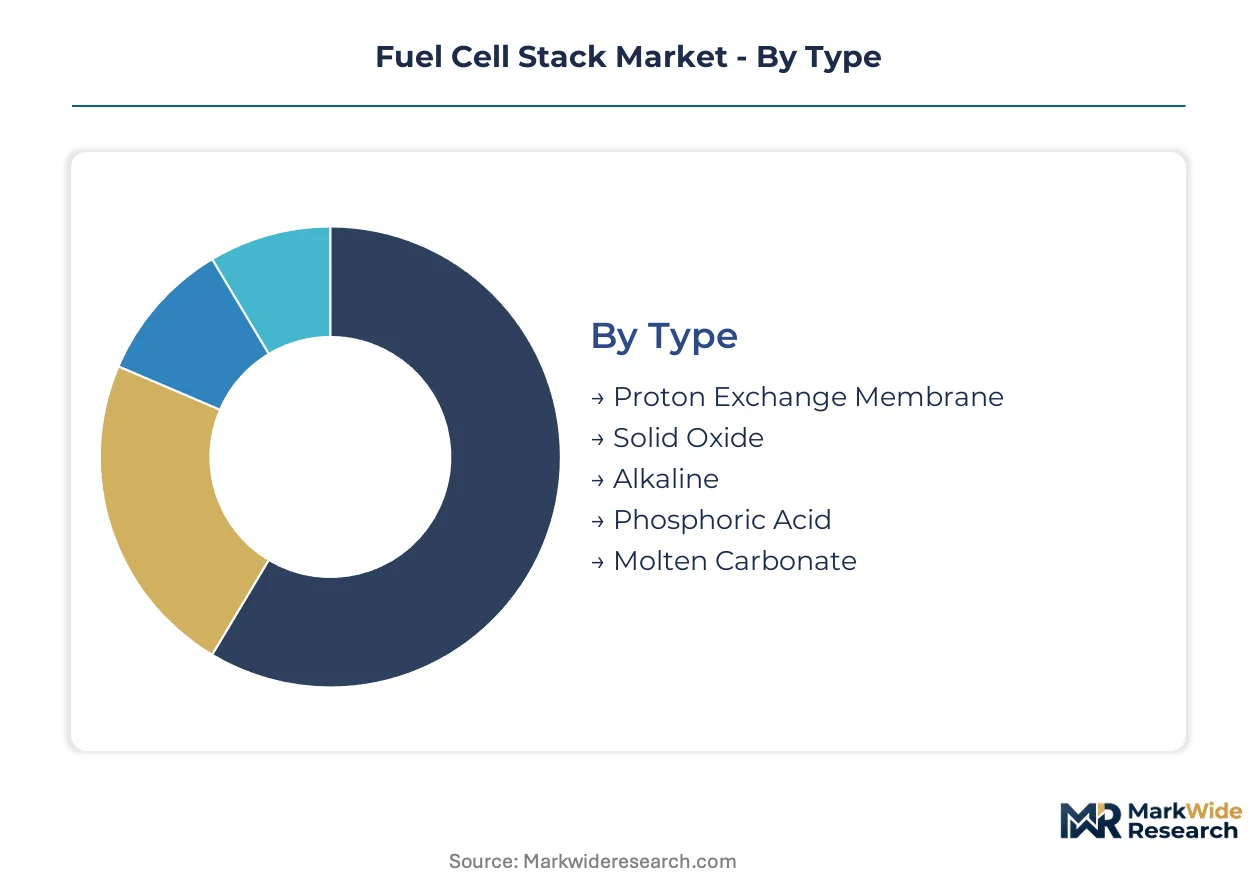
Fuel cell stack segmentation reveals how electrochemical architecture dictates commercial viability across temperature ranges, duty cycles, and capital intensity thresholds. Technology type and application pairing determine margin structures, certification pathways, and supply chain localization requirements.
Type:
Volume concentrates in low-temperature systems for mobility, while premium margins attach to high-temperature stationary configurations.
- Proton Exchange Membrane:Low-temperature operation at 60-80°C enables rapid cold-start capability for automotive and material handling duty cycles. Heavy-duty commercial vehicles in California freight corridors anchor demand, pulled by IRA hydrogen production tax credits and CARB fleet mandates.
- Solid Oxide:Ceramic electrolyte architectures operate at 600-1000°C, delivering combined heat and power efficiency exceeding 80 percent. Data center tri-generation installations in Nordic markets and Singapore drive procurement, attracted by waste heat recovery economics and grid independence.
- Alkaline:Platinum-free catalyst systems reduce material costs substantially for cost-sensitive backup power. Telecommunications tower operators in China and Korea adopt these for 100-500 kW diesel parity.
- Phosphoric Acid:Mid-temperature operation at 150-200°C serves stationary commercial and industrial baseload with established field durability.
- Molten Carbonate:High-temperature carbonate electrolyte systems target large-scale distributed generation above 1 MW output.
Today's leader: Proton Exchange Membrane. Tomorrow's challenger: Solid Oxide.
Application:
Customer procurement patterns bifurcate between captive fleet operators seeking total cost of ownership reduction and infrastructure-dependent buyers requiring fuel security guarantees.
- Material Handling Equipment:Class 1-3 forklift fleets in North American distribution centers represent the most mature fuel cell adoption segment. Asset-light hydrogen-as-a-service contracting displaces direct equipment purchases, with Plug Power and competitors offering fixed monthly fees covering stack, storage, and refueling infrastructure.
- Backup Power:Uninterruptible power supply for critical facilities demands sub-10-second startup and multi-day runtime. Data centers and hospitals in earthquake-prone Japanese and Californian markets specify fuel cell backup against grid instability and natural disaster risk.
- Residential Power:Combined heat and power units at 0.7-5 kW output serve single-family homes in Japan and South Korea with utility interconnection and thermal recovery.
- Portable Power:Man-portable and vehicle-mounted systems address military and disaster response requirements for silent, emission-free generation.
- Telecommunication Power:Off-grid and unreliable-grid tower sites in developing markets deploy fuel cells against diesel theft and fuel logistics costs.
Material Handling Equipment commands current revenue concentration. Backup Power for data centers is climbing the fastest.
End User:
Fleet scale and fuel access determine contract structure, with large commercial operators capturing hydrogen-as-a-service economics unavailable to fragmented residential buyers.
- Commercial Vehicles:Heavy-duty trucks, buses, and specialty vehicles in dedicated freight corridors benefit from centralized hydrogen infrastructure. California's LCFS credit stacking improves project finance terms for third-party fleet operators.
- Residential Buildings:Single-family and multi-family installations in Japan's Ene-Farm program and South Korea's hydrogen city initiatives receive subsidy support for CHP deployment.
- Data Centers:Hyperscale and colocation facilities evaluate tri-generation fuel cells for PUE improvement and carbon reporting compliance under EU CSRD and proposed SEC climate disclosure rules.
- Military Facilities:Silent watch, reduced thermal signature, and logistics burden reduction drive defense procurement for forward operating bases and maritime applications.
- Remote Locations:Mining camps, research stations, and island communities substitute fuel cells for diesel where fuel delivery costs exceed hydrogen production economics.
Commercial Vehicles anchor near-term deployments. Data Centers are gaining share fastest.
Technology:
Abbreviated technology classifications track manufacturing maturity and supply chain localization progress across certification regimes.
- PEM:Proton exchange membrane dominates transportation and material handling with established membrane electrode assembly supply chains and SAE J2601 refueling protocol compatibility.
- SOFC:Solid oxide fuel cell technology advances through planar and tubular cell designs for stationary CHP, with ceramic manufacturing scale-up constraining cost reduction.
- AFC:Alkaline fuel cell variants eliminate precious metal dependency, enabling cost breakthroughs in stationary backup and emerging maritime auxiliary power.
- PAFC:Phosphoric acid systems retain installed base in commercial buildings with long operational track records and established service networks.
- MCFC:Molten carbonate technology serves megawatt-scale distributed generation with internal reforming capability for natural gas feedstocks.
PEM retains manufacturing scale leadership. SOFC shows steepest expansion trajectory in stationary applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized membrane electrode assembly technicians cluster in South Korea's Gyeonggi-do province and Japan's Aichi prefecture, anchoring the Asia-Pacific manufacturing corridor. German engineering centers and US hydrogen hubs compete for this talent pool through targeted immigration and training programs.
United States
California's San Pedro Bay freight corridor drives heavy-duty PEM stack demand through CARB fleet mandates and LCFS credit stacking. The Inflation Reduction Act hydrogen production tax credits accelerate capital commitments toward domestic manufacturing scale-up. Houston's Gulf Coast hydrogen hub anchors electrolyzer-stack paired supply agreements for third-party fleet operators.
China
MIIT domestic content thresholds for subsidy eligibility fragment global supply chain configurations and raise compliance overhead. Shanghai and Beijing metropolitan clusters concentrate government-backed procurement programs for fuel cell commercial vehicle deployment. The Yangtze River Delta hosts the majority of installed alkaline stack capacity for telecommunications backup power.
Germany
The EU Green Deal and national hydrogen strategy pull investment toward PEM stack assembly for heavy-duty transportation applications. Bavaria's automotive engineering centers and North Rhine-Westphalia's industrial corridor anchor stationary fuel cell tri-generation installations. KBA certification requirements and REACH catalyst material sourcing rules reshape supplier qualification timelines.
Japan
METI enforces JIS C 8802 stationary fuel cell safety standards requiring enhanced hydrogen detection response times below 500 milliseconds. The Kanto region's Ene-Farm program subsidizes residential combined heat and power units at 0.7-5 kW output. Nagoya's industrial cluster forces non-domestic suppliers to establish local testing partnerships for residential segment entry.
South Korea
MFDS and KGS coordinate hydrogen infrastructure standards that dictate stack durability targets for commercial deployment. The hydrogen city initiative in Ulsan and the Seoul metropolitan area drives procurement for captive fleet operators. Gyeonggi-do province concentrates membrane electrode assembly production expertise, constraining qualified facility expansion elsewhere.
Fuel Cell Stack Market Key Industry Players
Top-tier vendors anchor premium transportation and material handling segments, while mid-scale specialists compete on cost-sensitive stationary backup applications. The vendor base organizes around captive membrane electrode assembly supply, backward integration into green hydrogen production, and diesel engine service network leverage for commercial vehicle retrofits. Three archetypes dominate: integrated hydrogen-as-a-service providers, captive component manufacturers, and diversified industrial conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with technology licensing gaining traction for regional certification acceleration.
Among North American specialists, FuelCell Energy and Plug Power exemplify divergent strategic positioning within the stationary and material handling archetypes respectively. Ballard Power Systems anchors the premium transportation tier through captive membrane electrode assembly supply. Cummins occupies a hybrid position across both premium and commodity tiers, leveraging its established industrial service infrastructure for commercial vehicle retrofit market penetration.
| Leading Market Players |
|---|
| FuelCell Energy |
| Cummins |
| Ballard Power Systems |
| AISIN Corporation |
| AFC Energy |
| Plug Power |
| Doosan Fuel Cell |
| Ceres Power |
| Bloom Energy |
| Others |
Cost & Logistics Intelligence
Captive membrane electrode assembly production anchors both supply security and pricing power for premium PEM stack manufacturers serving heavy-duty transportation. Ballard Power Systems and South Korean specialists defend margin structures through in-house catalyst deposition expertise that commodity alkaline suppliers cannot replicate.
Pricing Analysis
Bundled hydrogen-as-a-service contracts displace direct equipment purchases in material handling fleets, while unbundled stack-only transactions dominate stationary backup procurement. Pricing stratifies across automotive-grade durability tiers, SAE J2601 certification levels, and after-sales service bundling. Cost compression in alkaline systems is intensifying because platinum-free catalysts eliminate precious metal exposure. Telecommunications tower operators in China exhibit the highest price sensitivity, whereas California freight fleets prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for heavy-duty commercial vehicle retrofits, while system integrators serve fragmented stationary backup markets. Manufacturing concentrates in China, Japan, and South Korea, with membrane electrode assembly expertise clustering in Gyeonggi-do province and Aichi prefecture. Supply chains draw from South African and Russian iridium sources, Japanese gas diffusion layer specialists, and German bipolar plate stamping equipment. Single-source vulnerability in iridium catalyst loading creates exposure for PEM stack cost structures. Distribution runs through captive fleet operators, third-party hydrogen-as-a-service providers, and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fuel cell stacks hinges on platinum group metal recycling scale-up and the shift toward solid oxide systems commanding premium pricing in data center tri-generation.
For Market Incumbents: To counter iridium supply concentration, deepen captive catalyst recovery capabilities and expand membrane electrode assembly capacity in South Korea's Gyeonggi-do corridor. Secure long-term offtake agreements with South African mining operations to hedge feedstock volatility. Invest in SAE J2601 protocol certification acceleration to compress 18-24 month product launch cycles. For New Entrants and Emerging Players: Digital-channel routes through asset-light hydrogen-as-a-service platforms offer the lowest friction entry path for material handling fleet penetration. Maritime auxiliary power for European harbor craft represents the most penetrable white-space segment, with solid oxide stack integration still underdeveloped. Target data center tri-generation procurement evaluations in Nordic markets through combined cooling, heat, and power performance guarantees. For Investors and Strategic Acquirers: Roll-up economics work for alkaline stack specialists with telecommunications tower installation bases because China's MIIT localization mandates fragment global supply chains and raise compliance overhead for foreign suppliers. Acquire targets with established GB standards certification and Yangtze River Delta manufacturing footprints. Watch electrolyzer-stack paired supply agreement momentum as the inflection indicator for captive demand channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Recovery | Closed-loop iridium and platinum recovery reduces feedstock cost volatility for membrane electrode assembly producers. |
| SAE J2601 Protocol Certification Investment | Accelerated fueling protocol validation compresses product launch timelines for new PEM stack platforms. |
| Long-term Hydrogen Offtake Contracting | Electrolyzer-stack paired agreements bypass spot hydrogen market price volatility for fleet operators. |
| Geographic Manufacturing Footprint Expansion | Domestic assembly in IRA credit-eligible zones captures hydrogen production tax credit benefits. |
| Technology Licensing for Regional Certification | Local testing partnerships satisfy Japan's METI JIS C 8802 enhanced hydrogen detection requirements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with stack manufacturing engineers, hydrogen infrastructure project developers, fleet procurement managers at logistics operators, and membrane electrode assembly specialists with secondary validation. Bottom-up shipment data from automotive and stationary system integrators triangulated against top-down hydrogen demand forecasts from EIA and IEA sources. SEC filings from publicly traded fuel cell specialists, DOE hydrogen program disclosures, and CARB fleet mandate progress reports anchored the secondary foundation.
Historical reference periods spanning commercial vehicle deployment waves and stationary fuel cell installation cycles anchored the projection horizon. The analytical framework modeled segmentation across electrochemical architecture type, application duty cycle, end-user fleet scale, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for technology adoption, adjusted for iridium supply constraints and IRA credit phase-out schedules. Forecast inputs incorporated electrolyzer manufacturing capacity buildout, hydrogen hub funding allocation, and battery energy density improvement trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid oxide fuel cell ceramic manufacturing scale-up would alter the outlook. Forecasts reflect assumptions regarding iridium supply continuity, GB standards localization enforcement, and LCFS credit stacking permanence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Portable Fuel Cells Market