
 Asia-Pacific Direct Methanol Fuel Cell Market | 2026-2036
Asia-Pacific Direct Methanol Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Direct Methanol Fuel Cell Market Insights
GB/T 31035 compliance is unwinding competitive access across the Asia-Pacific Direct Methanol Fuel Cell landscape, forcing non-certified suppliers into costly retesting cycles. Toshiba Energy Systems & Solutions Corporation anchors Japanese utility-scale deployments through integrated system architectures. Panasonic Corporation leverages its consumer electronics heritage to dominate portable DMFC segments. Horizon Fuel Cell Technologies competes on manufacturing scale across China's Pearl River Delta.
A direct methanol fuel cell electrochemically oxidizes methanol at the anode to generate electricity with proton exchange membrane conductivity typically exceeding 0.1 S/cm at 60°C, serving off-grid and mobile power applications where hydrogen logistics prove impractical. The stationary power supply segment leads value capture due to data center uptime requirements, while portable devices sustain faster volume expansion through military and consumer electronics procurement. DMFC stack manufacturing concentrates margin pools with membrane electrode assembly specialists, whereas fuel cartridge production commoditizes faster across Chinese contract manufacturers.
Japan's METI enforces JIS C 8824 performance benchmarks that gate subsidy eligibility, while China's MIIT ties NEV credit transfers to domestic stack certification under GB/T standards. South Korea's MFDS coordinates with KGS on methanol purity protocols for indoor fuel cell operation. Stakeholders must track regulatory divergence on methanol storage limits as each major economy hardens its technical barriers to import penetration.
Market Dynamics
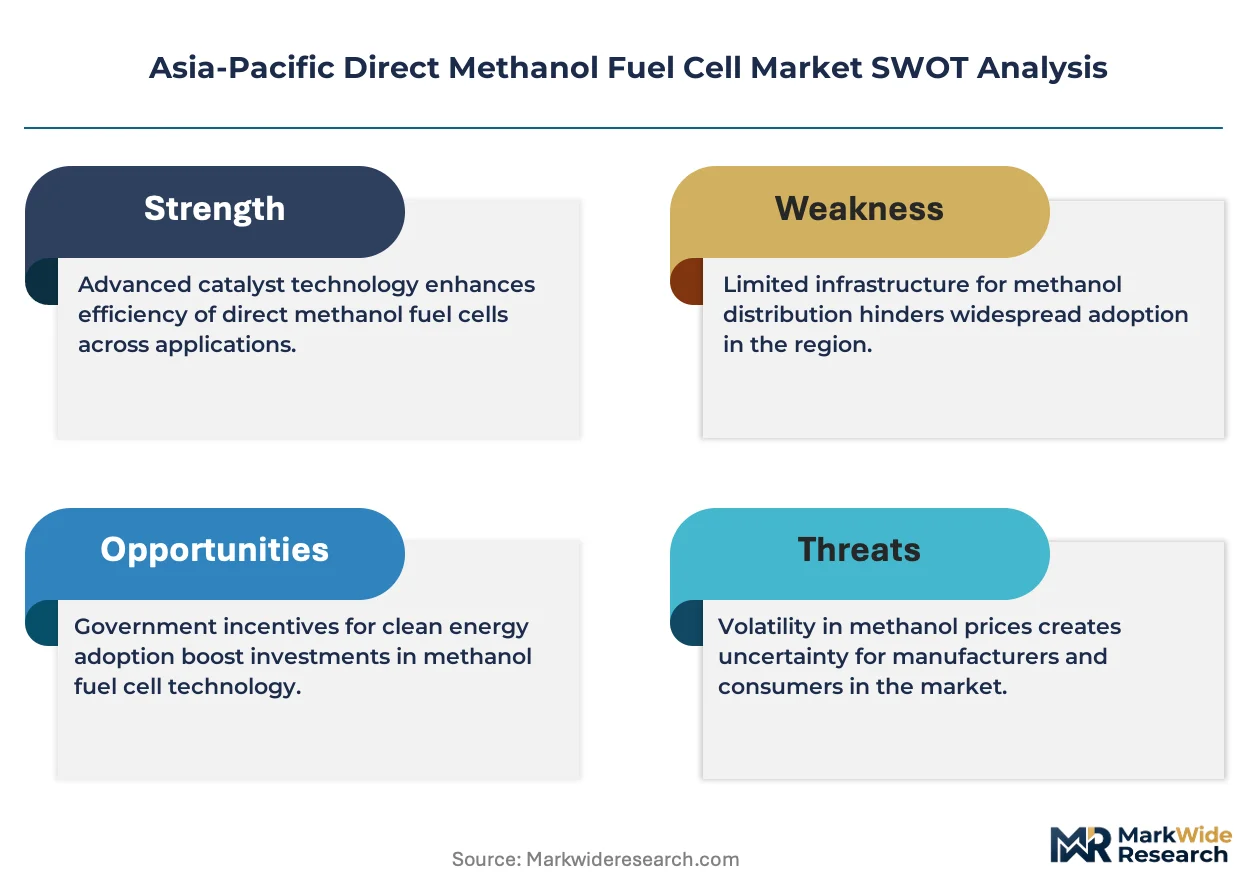
Japan's METI hydrogen roadmap and China's MIIT subsidy tiers are redirecting procurement toward domestic-certified systems, forcing non-certified suppliers into costly retesting cycles across the Asia-Pacific Direct Methanol Fuel Cell landscape.
Growth Catalysts
- Data center uptime requirements:Stationary power supply adoption accelerates across Japanese and South Korean data center operators seeking reliable off-grid electricity generation.
- GB/T 31035 compliance mandates:China's certification standards create procurement preference for domestic stack manufacturers, consolidating local supply chains.
- Methanol logistics advantage:DMFC systems serve mobile power applications where hydrogen distribution infrastructure remains underdeveloped, penetrating military and consumer electronics procurement.
Market Restraints
- Platinum catalyst cost volatility:Membrane electrode assembly production depends on platinum group metal prices, compressing margin pools for stack specialists.
- Chinese fuel cartridge commoditization:Contract manufacturers in the Pearl River Delta drive rapid price erosion in cartridge production, squeezing component suppliers.
- JIS C 8824 performance barriers:Japan's technical benchmarks gate subsidy eligibility, creating regulatory friction for import penetration.
Strategic Opportunities
- Kanto industrial corridor expansion:Japan's dense manufacturing belt offers concentrated demand for utility-scale DMFC deployments with established service networks.
- Ulsan petrochemical complex integration:South Korea's chemical hub provides captive methanol supply for stationary fuel cell installations at process facilities.
- KGS-MFDS indoor operation protocols:South Korea's coordinated methanol purity standards enable new commercial building applications previously restricted by safety codes.
Industry Challenges
- Membrane electrode assembly talent scarcity:Specialized electrochemistry expertise concentrates with Japanese and Korean incumbents, constraining new entrant scale-up.
- Dual certification timeline compression:Suppliers must simultaneously pursue GB/T, JIS, and KGS approvals to serve segmented national markets, extending product launch cycles.
- Legacy hydrogen infrastructure preference:Government hydrogen roadmaps in Japan and South Korea divert R&D funding from direct methanol pathways toward proton exchange membrane alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Direct Methanol Fuel Cell Market |
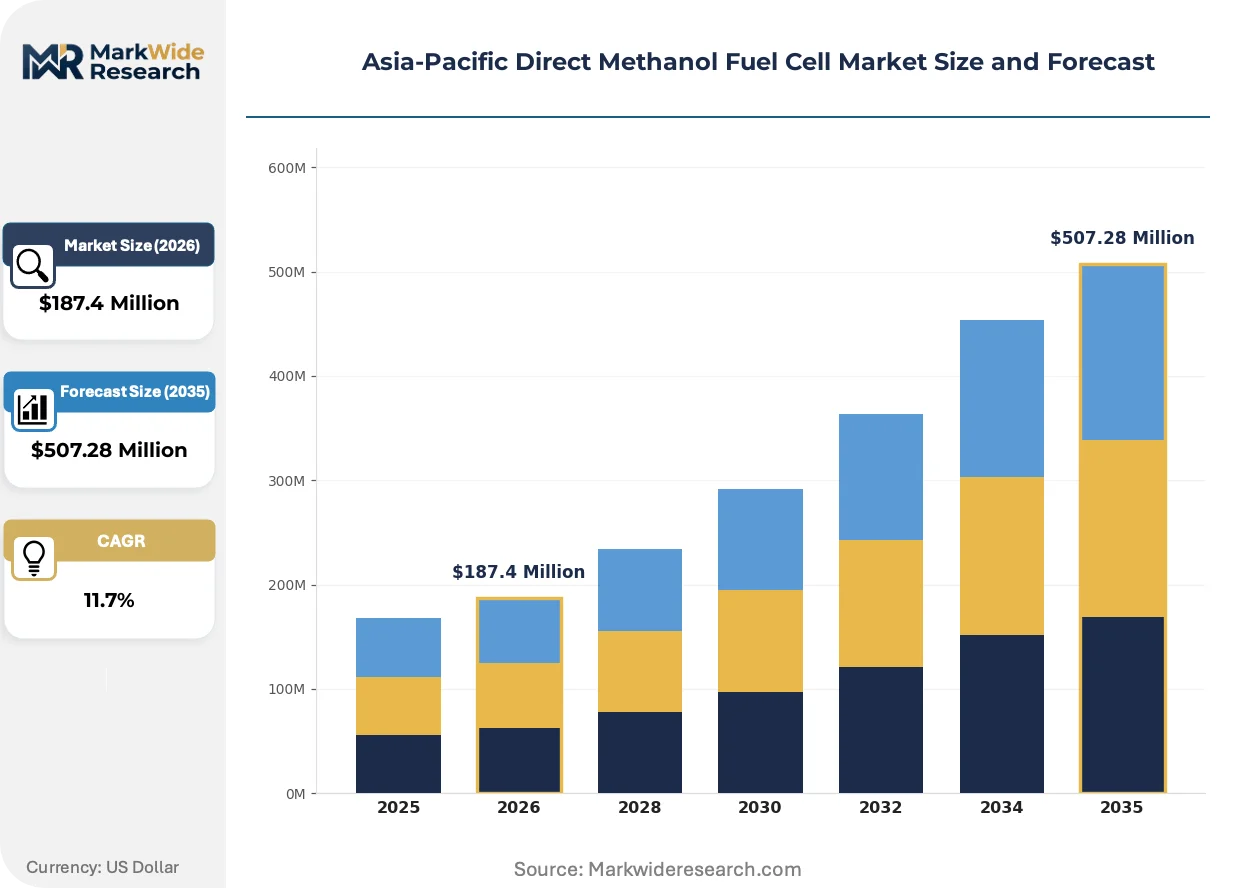
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Portable Devices, Stationary Power Supply, Automotive, Backup Power Product Type: DMFC Stack, Fuel Cartridge, Power Generator, Integrated System End User: Industrial, Military, Consumer Electronics, Renewable Energy Technology: Proton Exchange Membrane, Bipolar Plate, Cathode Catalysis, Anode Catalyst |
| Companies Covered | Antig Technology Co., Ltd, Blue World Technologies, Fujikura Ltd., Toshiba Energy Systems & Solutions Corporation, Panasonic Corporation, Horizon Fuel Cell Technologies, Viaspace Inc., Oorja Protonics, SFC Energy AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Direct Methanol Fuel Cell Market Trends and Innovations
Stack architecture evolution and regulatory divergence are compressing competitive timelines across the Asia-Pacific Direct Methanol Fuel Cell market, with certification requirements now determining market access faster than technical performance differentiation.
Membrane electrode assembly technology is miniaturizing. Proton exchange membrane conductivity exceeding 0.1 S/cm at 60°C enables thinner active layers without sacrificing power density. Japanese portable electronics manufacturers are integrating these compact stacks into handheld device designs previously served by lithium-ion batteries. The technology is miniaturizing form factors while maintaining electrochemical efficiency, opening consumer electronics segments where space constraints previously excluded fuel cell solutions.
METI enforces JIS C 8824 performance benchmarks that gate subsidy eligibility for utility-scale installations. Industrial consequence: Toshiba Energy Systems and Panasonic Corporation anchor domestic procurement through pre-certified integrated architectures. Data center operators in Japan's Kanto corridor now specify JIS-compliant systems exclusively, locking out non-certified competitors regardless of price positioning.
Buyer preference is hardening around certification-driven procurement. Military and enterprise customers in South Korea's Ulsan complex now require KGS methanol purity documentation before contract award, displacing informal supplier relationships. Channel partners in China's Pearl River Delta report compressed sales cycles for GB/T-certified systems versus uncertified alternatives. This preference shift concentrates volume with vertically integrated manufacturers holding captive testing capabilities.
Asia-Pacific Direct Methanol Fuel Cell Market Segmentation
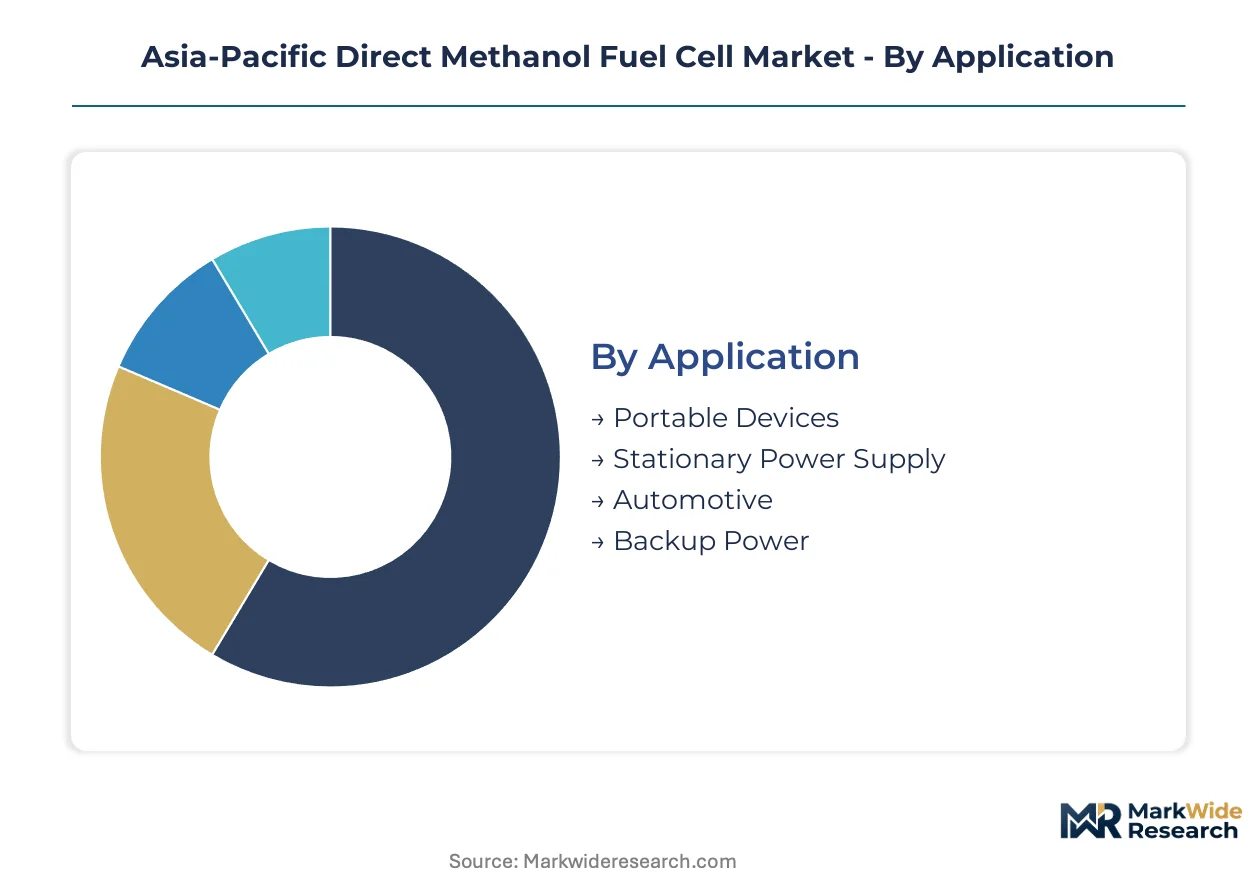
Direct methanol fuel cell procurement patterns diverge sharply across application contexts, with certification requirements and methanol logistics shaping customer preferences. Understanding where margin pools concentrate within each dimension reveals why Japanese incumbents dominate certain segments while Chinese manufacturers capture others.
Application:
Margin pools concentrate in stationary installations where uptime premiums outweigh capital costs, while portable volumes scale faster through military and consumer electronics channels.
- Stationary Power Supply:Utility-scale systems serving data centers in Japan's Kanto corridor and South Korea's Ulsan petrochemical complex command premium pricing tied to JIS C 8824 and KGS certification. METI subsidy eligibility gates procurement toward pre-certified integrated architectures from domestic suppliers.
- Portable Devices:Compact stacks penetrating military field operations and consumer electronics benefit from methanol logistics advantages over hydrogen distribution. Panasonic Corporation leverages consumer electronics heritage to dominate handheld segments where lithium-ion alternatives face energy density constraints.
- Automotive:Range-extender applications for commercial fleets remain nascent, constrained by platinum catalyst costs and methanol storage safety protocols.
- Backup Power:Telecom and critical infrastructure installations favor DMFC over diesel generators in indoor environments where emissions regulations restrict combustion alternatives.
The dominant share belongs to Stationary Power Supply, while Portable Devices is closing the gap fastest.
Product Type:
Component economics favor stack manufacturers controlling membrane electrode assembly production, while fuel cartridge production commoditizes rapidly across contract manufacturers.
- DMFC Stack:Membrane electrode assembly specialists capture concentrated margins through proprietary proton exchange membrane conductivity exceeding 0.1 S/cm at 60°C. Toshiba Energy Systems anchors Japanese utility-scale deployments through integrated system architectures incorporating captive stack production.
- Fuel Cartridge:Methanol fuel containers face rapid price erosion from Pearl River Delta contract manufacturers. GB/T 31035 compliance mandates redirect procurement toward domestic-certified suppliers, consolidating volume with vertically integrated Chinese producers.
- Power Generator:Self-contained units for off-grid applications concentrate demand in South Korea's renewable energy sector and Japan's disaster preparedness programs.
- Integrated System:Turnkey installations combining stack, cartridge, and power management command premiums from data center operators seeking single-source accountability.
DMFC Stack holds the revenue concentration, yet Fuel Cartridge volumes are climbing the fastest as portable applications proliferate.
End User:
Customer procurement sophistication varies sharply, with military and industrial buyers demanding certification documentation while consumer electronics channels prioritize form factor miniaturization.
- Industrial:Process facilities in South Korea's Ulsan petrochemical complex and Japan's Kanto manufacturing belt specify KGS and JIS-compliant systems for captive methanol utilization. MFDS-coordinated purity protocols enable indoor operation previously restricted by safety codes.
- Military:Field power requirements in ruggedized environments drive demand for methanol logistics advantages over hydrogen distribution infrastructure. Procurement mandates documentation of methanol purity standards before contract award.
- Consumer Electronics:Handheld device manufacturers integrate compact stacks where lithium-ion energy density proves insufficient for extended operation.
- Renewable Energy:Off-grid installations pair DMFC with solar or wind generation to address intermittency, particularly in Japan's disaster-resilient microgrid programs.
Industrial accounts dominate current procurement value, though Military applications are gaining share fastest through expanded defense modernization budgets.
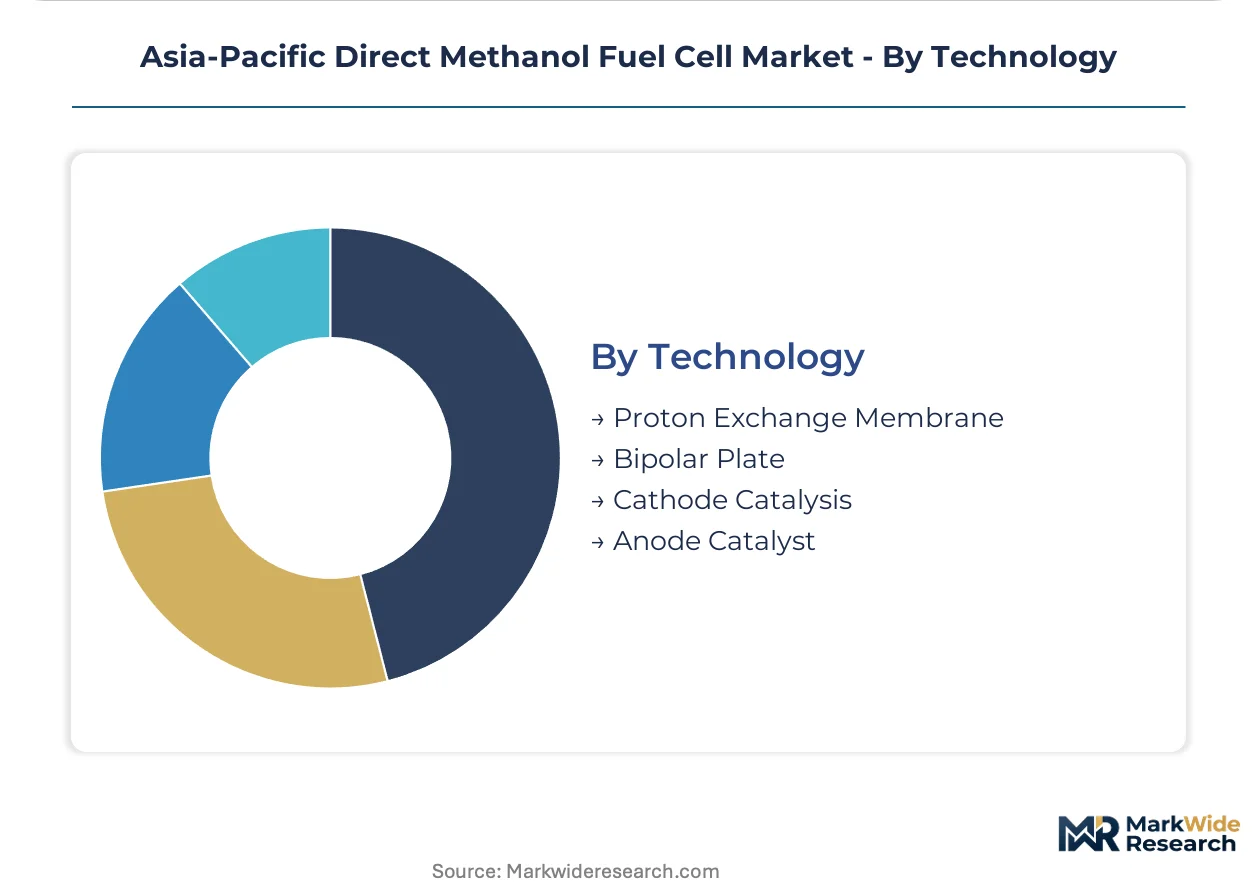
Technology:
Intellectual property concentration in membrane and catalyst layers determines competitive moats, with Japanese and Korean incumbents holding specialized electrochemistry expertise.
- Proton Exchange Membrane:Conductivity performance at 60°C operation gates system efficiency, with membrane electrode assembly miniaturization enabling consumer electronics penetration. Japanese portable electronics manufacturers integrate these compact active layers into handheld designs.
- Anode Catalyst:Platinum-ruthenium alloy formulations for methanol oxidation concentrate production expertise with established stack specialists, constraining new entrant scale-up.
- Bipolar Plate:Graphite and metallic plate designs balance conductivity against corrosion resistance in methanol vapor environments.
- Cathode Catalysis:Platinum loading reduction strategies target cost compression without sacrificing oxygen reduction reaction efficiency.
Proton Exchange Membrane commands the technology investment focus, while Anode Catalyst development is advancing most rapidly through materials science innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT subsidy tiers and METI hydrogen roadmaps are redirecting procurement toward domestic-certified systems across the Asia-Pacific Direct Methanol Fuel Cell landscape, fragmenting competitive access along national regulatory boundaries.
Japan
Data center operators in the Kanto industrial corridor drive stationary power demand for reliable off-grid electricity generation. METI enforces JIS C 8824 performance benchmarks that gate subsidy eligibility for utility-scale installations. Toshiba Energy Systems anchors domestic procurement through pre-certified integrated architectures serving Tokyo-area facilities.
China
GB/T 31035 compliance mandates create procurement preference for domestic stack manufacturers across the Pearl River Delta manufacturing belt. MIIT ties NEV credit transfers to domestic stack certification under national standards. Horizon Fuel Cell Technologies competes on manufacturing scale within Shenzhen and Dongguan industrial clusters.
South Korea
Process facilities at the Ulsan petrochemical complex specify KGS-certified systems for captive methanol utilization in stationary applications. MFDS coordinates with KGS on methanol purity protocols enabling indoor fuel cell operation. Busan-Ulsan corridor installations concentrate demand for backup power at chemical processing plants.
Australia
Remote mining operations and off-grid communities seek methanol logistics advantages where hydrogen distribution infrastructure remains underdeveloped. National renewable energy programs pair DMFC with solar generation to address intermittency in Western Australian resource extraction sites. Perth-based project developers target isolated industrial facilities with containerized power generator deployments.
India
Telecom tower operators evaluate DMFC backup systems against diesel generator restrictions in urban emissions zones. The country's national fuel cell standards body develops testing protocols for methanol purity and stack performance. Maharashtra and Gujarat industrial corridors host pilot installations at manufacturing facilities seeking captive power alternatives.
Asia-Pacific Direct Methanol Fuel Cell Market Competitive Landscape
Player mix skews toward integrated system architects and membrane electrode assembly specialists, creating a tiered structure where certification-holding incumbents control premium procurement channels. Japanese and Korean conglomerates with captive electrochemistry expertise dominate utility-scale deployments, while Chinese contract manufacturers capture commoditized fuel cartridge production. Two strategic archetypes define competitive positioning: vertically integrated energy conglomerates leveraging pre-certified architectures, and component specialists controlling membrane conductivity intellectual property. Dominant competitive moves include backward integration into membrane electrode assembly production and geographic expansion through dual-certification pursuit across GB/T, JIS, and KGS standards.
Among Asia-Pacific-based integrated system providers, Toshiba Energy Systems & Solutions Corporation and Panasonic Corporation exemplify the conglomerate archetype with pre-certified utility-scale and portable segment positioning respectively. Horizon Fuel Cell Technologies represents the scale-driven manufacturing specialist competing across China's Pearl River Delta. Blue World Technologies occupies a position within the European-originated technology licensor tier seeking regional market penetration through certification partnerships.
| Leading Market Players |
|---|
| Antig Technology Co., Ltd |
| Blue World Technologies |
| Fujikura Ltd. |
| Toshiba Energy Systems & Solutions Corporation |
| Panasonic Corporation |
| Horizon Fuel Cell Technologies |
| Viaspace Inc. |
| Oorja Protonics |
| SFC Energy AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with methanol suppliers lock in both feedstock access and cost visibility for Japanese and Korean DMFC stack manufacturers, insulating integrated producers from spot market volatility while compressing margins for cartridge assemblers exposed to Pearl River Delta contract pricing.
Pricing Analysis
Cost-plus contracts indexed to platinum group metal spot prices dominate membrane electrode assembly procurement, with JIS C 8824 and GB/T 31035 certification tiers driving price differentiation between premium certified and uncertified alternatives. Pricing pressure stems from Chinese fuel cartridge commoditization across Shenzhen and Dongguan manufacturing clusters. Industrial buyers in Japan's Kanto corridor show lowest price sensitivity due to uptime premiums, while consumer electronics channels face acute cost compression.
Supply Chain Analysis
Just-in-time inventory strategies prevail for membrane electrode assembly production in Japan and South Korea, whereas Chinese stack manufacturers maintain strategic stockpiles of methanol feedstock to buffer against purity standard enforcement. Supply concentrates in Japan, South Korea, and China for proton exchange membranes, platinum-ruthenium catalysts, and bipolar plate fabrication. Single-source vulnerability runs through Japanese membrane specialists. Distribution runs through vertically integrated system architects serving data center operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across METI, MIIT, and KGS certification regimes fragments competitive access, creating niche opportunities for specialists mastering dual or triple compliance pathways.
For Market Incumbents: Compound certification moats by accelerating JIS-GB-T-KGS triple approval timelines before subsidy eligibility windows narrow. Toshiba Energy Systems and Panasonic Corporation should deepen backward integration into membrane electrode assembly production to defend against Chinese scale competitors. Threat: Horizon Fuel Cell Technologies manufacturing expansion across Pearl River Delta. Lever: captive testing capabilities. For New Entrants and Emerging Players: After-sales service networks in South Korea's Ulsan-Busan corridor represent an under-served layer where incumbents rely on third-party maintenance contracts. Target Australia's Western Australian mining sector for off-grid power generator deployments where hydrogen infrastructure remains absent. Go-to-market: containerized turnkey systems with methanol logistics partnerships. For Investors and Strategic Acquirers: Membrane conductivity IP holders with established Korean or Japanese manufacturing footprints offer acquisition exposure to certification-gated procurement channels. Long-term viability hinges on DMFC maintaining cost-position against solid oxide and proton exchange membrane alternatives in stationary applications. Watch signal: METI hydrogen roadmap funding reallocation toward direct methanol pathways versus diversion to hydrogen infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Pursuit | Simultaneous JIS and GB/T approval unlocks procurement access across Japan's Kanto corridor and China's Pearl River Delta manufacturing belt. |
| Backward Integration into MEA Production | In-house membrane electrode assembly manufacturing captures margin pools concentrated with Japanese and Korean electrochemistry specialists. |
| Methanol Purity Protocol Compliance | KGS-MFDS coordinated standards enable indoor commercial building applications previously restricted by South Korean safety codes. |
| Portable Stack Miniaturization | Proton exchange membrane conductivity advances open consumer electronics segments where lithium-ion energy density proves insufficient. |
| Captive Methanol Supply Integration | Ulsan petrochemical complex proximity offers South Korean process facilities feedstock cost advantages for stationary installations. |
Research Methodology
The analysis maps DMFC stack manufacturing, fuel cartridge assembly, and integrated system deployment, each validated through plant managers at Japanese and Korean industrial facilities, procurement leads at data center operators, MIIT certification consultants, and membrane electrode assembly technical directors. Primary interview findings triangulate against secondary sources including METI hydrogen roadmap publications, MIIT NEV credit policy filings, KGS methanol safety standards, customs trade data for methanol fuel cell components, and SEC disclosures from listed fuel cell specialists. Bottom-up demand modeling from application-specific deployment data reconciles with top-down market sizing from national subsidy program allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include application context, product type, end-user procurement sophistication, and technology layer. CAGRs derive from installed base growth trajectories and replacement cycle analysis. Industry-specific forecast inputs incorporate platinum group metal price assumptions and certification timeline probability distributions.
Material uncertainties — regulatory redirection of hydrogen roadmap funding, methanol purity standard revisions, and platinum catalyst substitution breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about subsidy continuity and certification barrier maintenance. Revision becomes warranted when METI or MIIT policy reallocation crosses thresholds diverting procurement toward alternative fuel cell chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market