
 Phosphoric Acid Fuel Cell Market | 2026-2036
Phosphoric Acid Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphoric Acid Fuel Cell Market Intelligence
A fragmentation of the customer base, moving from large utility projects to a diverse set of commercial enterprises and data centers, is repositioning the competitive landscape. Doosan Fuel Cell Co., Ltd. specializes in large-scale stationary systems for utility and industrial clients. Fuji Electric Co., Ltd. leverages its electronics expertise to develop efficient power modules. FuelCell Energy, Inc. competes with a focus on combined heat and power (CHP) applications for commercial buildings.
A phosphoric acid fuel cell (PAFC) is an electrochemical generator using liquid phosphoric acid as the electrolyte. Operating at medium temperatures between 150°C and 210°C, PAFCs are primarily used for stationary power and combined heat and power (CHP). While utility power plants are a mature application, demand from data centers and telecommunication towers for backup power is growing. Stationary systems dominate the product landscape, with CHP variants gaining traction in commercial buildings due to higher efficiency.
Incentive structures like the US Inflation Reduction Act (IRA) and policies under the EU Green Deal directly support clean stationary power investments. Concurrently, standards from bodies like the International Electrotechnical Commission (IEC) govern the safety and performance requirements for fuel cell technologies, ensuring market access. Stakeholder success will depend on navigating these evolving policy landscapes and demonstrating long-term operational reliability to end-users.
Market Dynamics
The central dynamic shaping the market is the fragmentation of the customer base. A structural shift away from monolithic utility-scale projects toward a distributed network of commercial and industrial adopters, including data centers, is fundamentally altering product requirements and competitive strategies.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act (IRA) provides tax credits for clean stationary power generation, directly lowering the capital expenditure barrier for commercial and industrial firms adopting phosphoric acid fuel cell systems for on-site power.
- Data Center Demand:The requirement for uninterruptible, high-quality power in data centers is a significant catalyst. PAFCs offer a cleaner, quieter, and often more reliable backup and primary power alternative to traditional diesel generators in this application.
- Geographic Concentration:Adoption in Japan remains a primary driver, where government support and a mature market ecosystem encourage utilities and large commercial enterprises to deploy PAFC systems for both grid support and combined heat and power.
Market Restraints
- High Capital Cost:The significant upfront investment required for PAFC systems, driven by the cost of platinum catalysts and complex system components, remains a major barrier to adoption compared to conventional power generation technologies.
- Material Durability:Operating at medium temperatures places stress on materials within the fuel cell stack, particularly the carbon support structures for the catalyst. This can limit the operational lifetime and create long-term maintenance liabilities.
- Alternative Technologies:Competition from other fuel cell types, such as solid oxide fuel cells (SOFCs) for high-temperature industrial applications and proton-exchange membrane (PEM) fuel cells for a wider range of power outputs, constrains market expansion.
Strategic Opportunities
- Hybrid Energy Systems:Integrating PAFCs with renewable energy sources like solar photovoltaics and battery storage creates highly resilient and efficient microgrid solutions. This presents an opportunity to serve customers seeking comprehensive energy independence and decarbonization.
- Telecommunication Infrastructure:The expansion of 5G networks requires a dense network of towers that need reliable backup power. PAFCs offer a low-emission, low-maintenance solution for this underpenetrated application, particularly in areas with stringent environmental regulations.
- Geographic Expansion:Markets like South Korea, with strong government backing for a hydrogen economy and a need for clean, distributed power in dense urban areas, represent a significant opportunity for market entry and growth beyond established regions.
Industry Challenges
- Demonstrating Long-Term Reliability:A key operational hurdle is proving consistent performance and durability over 20-year-plus lifecycles to risk-averse customers like utilities and data center operators. This requires extensive field data and robust maintenance service networks.
- System Integration Complexity:Integrating PAFC units, especially combined heat and power variants, into existing building management and industrial process control systems is a significant technical challenge requiring specialized engineering expertise.
- Navigating Evolving Standards:Adherence to evolving safety and performance standards from bodies like the International Electrotechnical Commission (IEC) requires continuous investment in testing and certification, potentially delaying market access for new product iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphoric Acid Fuel Cell Market |
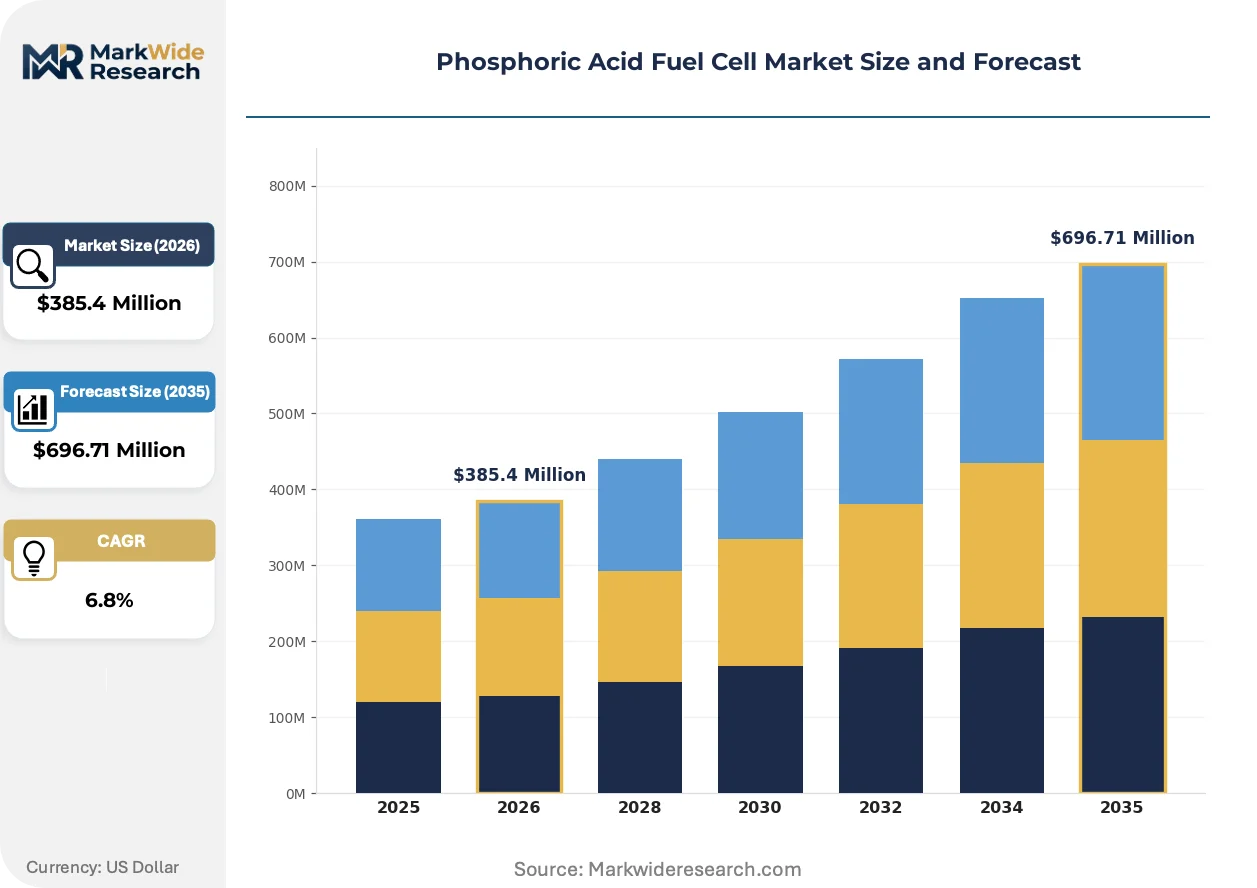
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Systems, Portable Devices, Combined Heat & Power, Auxiliary Power Units, Backup Power Technology: Low Temperature, Medium Temperature, High Temperature, Hybrid Systems, Direct Phosphoric Acid Cells Application: Telecommunication Towers, Data Centers, Military, Commercial Buildings, Utility Power Plants End User: Energy Providers, Research Institutes, Defense Contractors, Industrial Manufacturers, Commercial Enterprises |
| Companies Covered | Bloom Energy, SFC Energy AG, Doosan Fuel Cell Co., Ltd., Advent Technologies, FuelCell Energy, Inc., Fuji Electric Co., Ltd., HyAxiom Inc., Toshiba Corporation, Doosan Fuel Cell America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphoric Acid Fuel Cell Market Strategic Shifts & Innovations
The market is pivoting towards higher-efficiency, on-site power solutions tailored for commercial and industrial applications. This shift emphasizes total cost of ownership and energy resilience over the simple transactional sale of power generation equipment, favoring integrated and service-oriented models.
Advanced electrode designs featuring improved catalyst dispersion and more durable carbon support materials are gaining prominence. System integrators and component suppliers are steadily adopting these innovations to enhance stack longevity. This evolution in material science is absorbing the high-cost pressure associated with platinum group metals and extending the required maintenance intervals for core components.
Regulatory frameworks under the EU Green Deal are creating strong tailwinds for combined heat and power applications. The policy's focus on energy efficiency in buildings and industry directly incentivizes the adoption of systems that capture and utilize waste heat. The commercial buildings segment in Europe is most affected, with operators investing in CHP-configured PAFCs to meet stringent new energy performance mandates.
A notable behavioral change involves customers seeking comprehensive energy resilience rather than just purchasing standalone backup generators. This disrupts the traditional equipment sales model, giving rise to long-term energy-as-a-service (EaaS) contracts where the provider guarantees uptime and performance. This trend is most pronounced within the North American data center sector, where power availability is directly tied to revenue.
Phosphoric Acid Fuel Cell Market Segmentation
The Phosphoric Acid Fuel Cell market's segmentation reflects the diverse requirements of various industries and applications. Understanding these distinct segments helps stakeholders tailor product development and market strategies. This granular view reveals where demand concentrates and which specific features drive adoption within each category.
Product Type:
Buyers in this category prioritize their specific power delivery needs, ranging from continuous operation to emergency backup.
- Stationary Systems:These large-scale units provide continuous, on-site power generation, often integrated into existing grid infrastructure. Demand concentrates in Japan, where utilities and large commercial enterprises deploy them for grid stability and primary power.
- Combined Heat & Power:CHP systems simultaneously generate electricity and useful heat, significantly increasing overall energy efficiency by utilizing waste heat. Demand is notably strong in commercial buildings across Europe, driven by stringent energy performance mandates under the EU Green Deal.
- Portable Devices:These are smaller, mobile fuel cell units designed for low-power applications or remote charging, offering flexibility.
- Auxiliary Power Units:APUs provide power to vehicles or equipment when the main engine is off, reducing idling emissions and fuel consumption.
- Backup Power:These systems offer reliable, uninterruptible power supply during grid outages, crucial for critical infrastructure.
Stationary Systems lead volumes today; Combined Heat & Power is gaining share fastest.
Technology:
Application-specific requirements drive the selection of different phosphoric acid fuel cell technologies.
- Medium Temperature:These PAFCs operate between 150°C and 210°C, using liquid phosphoric acid as the electrolyte, suitable for stationary power and CHP. This technology sees significant deployment in commercial buildings and data centers due to its operational stability and efficient heat recovery.
- Hybrid Systems:These configurations integrate PAFCs with other energy sources like solar photovoltaics or battery storage to create resilient and efficient microgrid solutions. Demand for these systems is growing in North America, serving customers seeking comprehensive energy independence.
- Low Temperature:These technologies offer faster start-up times but typically have lower overall electrical efficiency compared to their medium-temperature counterparts.
- High Temperature:Operating at elevated temperatures, these systems often allow for greater fuel flexibility, though they are less common in the PAFC market.
- Direct Phosphoric Acid Cells:This variant allows for direct use of a fuel source without extensive reforming, simplifying the system design.
Medium Temperature technologies represent the core offering; Hybrid Systems show the steepest expansion trajectory.
Application:
The diverse operational environments of end-users dictate the specific application requirements for phosphoric acid fuel cells.
- Data Centers:These facilities require highly reliable, uninterruptible power to ensure continuous operation and protect critical data. PAFCs serve as a cleaner, quieter, and often more reliable backup and primary power source in this sector, particularly in North America.
- Utility Power Plants:Large-scale PAFC deployments contribute to grid support and distributed generation, offering stable power output to complement centralized power generation. Japan remains a primary driver for these applications, with utilities adopting PAFC systems for both grid support and CHP.
- Telecommunication Towers:The expansion of 5G networks necessitates reliable backup power for dense tower networks, where PAFCs offer a low-emission solution.
- Military:Fuel cells provide quiet, efficient, and reliable power for remote outposts, portable equipment, and specialized vehicles, reducing logistical burdens.
- Commercial Buildings:PAFCs are increasingly adopted for on-site power and combined heat and power (CHP) in commercial structures, driven by energy efficiency goals.
Utility Power Plants account for significant existing deployments; Data Centers are climbing the fastest in new installations.
End User:
The operational priorities and regulatory mandates of various end-user segments shape their adoption of phosphoric acid fuel cell solutions.
- Commercial Enterprises:This segment includes a diverse range of businesses adopting PAFCs for on-site power, backup, and CHP to meet sustainability goals and reduce energy costs. Demand is concentrating in Europe and North America, where enterprises seek energy resilience and decarbonization.
- Energy Providers:These entities, including utility companies, integrate PAFCs into their energy portfolios for distributed generation, grid stabilization, and peak shaving. Energy providers in Japan are key adopters, supported by government initiatives for clean energy.
- Research Institutes:Academic and private research organizations conduct studies and develop new materials and designs for fuel cell performance and longevity.
- Defense Contractors:These firms supply robust and reliable fuel cell systems for military applications, emphasizing operational security and reduced detection.
- Industrial Manufacturers:Manufacturing facilities use PAFCs for reliable process power and to co-generate heat for industrial operations, improving overall energy efficiency.
Energy Providers represent a mature customer base; Commercial Enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan demonstrates a mature market for phosphoric acid fuel cells, driven by utility adoption, while the United States shows rapid expansion in data center applications. European nations, under the EU Green Deal, are accelerating CHP system deployments. South Korea and Germany are also making significant strides in clean energy integration.
Japan
Utility power plants and large commercial enterprises in Japan deploy PAFC systems for grid stability and combined heat and power. The Ministry of Economy, Trade and Industry (METI) supports hydrogen and fuel cell technologies. Tokyo and Osaka metropolitan areas show high concentration of these systems, serving diverse energy needs.
United States
Data centers require reliable backup and primary power, driving significant PAFC adoption in the United States. The US Inflation Reduction Act (IRA) provides substantial tax credits for clean stationary power generation. California and Texas see increased installations around major tech hubs and industrial zones seeking energy independence.
Germany
Commercial buildings and industrial facilities in Germany increasingly adopt PAFC CHP systems for energy efficiency. Policies under the EU Green Deal incentivize waste heat utilization for decarbonization. The Rhine-Ruhr region and Bavaria exhibit growing commercial enterprises integrating these advanced energy solutions.
South Korea
Government backing for a hydrogen economy and clean distributed power drive PAFC deployment in South Korea. The Ministry of Trade, Industry and Energy (MOTIE) supports fuel cell research and commercialization. Seoul and Gyeonggi Province are focal points for new installations, addressing urban energy demands and air quality.
France
France prioritizes energy efficiency in buildings and industry, fostering demand for combined heat and power phosphoric acid fuel cells. The national hydrogen strategy aligns with EU objectives to decarbonize energy consumption. The Île-de-France region sees commercial and public sector buildings adopting these systems to meet environmental mandates.
Phosphoric Acid Fuel Cell Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure across the phosphoric acid fuel cell industry. This landscape encompasses established industrial players offering comprehensive solutions and agile technology firms innovating specific components. Strategic archetypes range from large-scale stationary system integrators to specialized combined heat and power providers. Dominant competitive moves include technology licensing agreements and strategic partnerships to expand geographic reach and application diversity.
Within the large-scale stationary systems tier, Doosan Fuel Cell Co., Ltd., a South Korean conglomerate, occupies a position specializing in utility and industrial clients. FuelCell Energy, Inc., a US-based corporation, exemplifies a focus on combined heat and power applications for commercial buildings, demonstrating adaptability across different energy needs. Fuji Electric Co., Ltd., a Japanese company, represents a player leveraging its extensive electronics expertise to develop efficient power modules, positioning itself across various power generation sectors.
| Leading Market Players |
|---|
| Bloom Energy |
| SFC Energy AG |
| Doosan Fuel Cell Co., Ltd. |
| Advent Technologies |
| FuelCell Energy, Inc. |
| Fuji Electric Co., Ltd. |
| HyAxiom Inc. |
| Toshiba Corporation |
| Doosan Fuel Cell America, Inc. |
Cost & Logistics Intelligence
Captive supply of platinum group metals anchors both the production capabilities and pricing power for phosphoric acid fuel cell manufacturers. This strategic control mitigates volatility in critical raw material costs.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for phosphoric acid fuel cell systems. Project-based pricing dominates the market, reflecting the custom engineering required for large stationary and CHP installations. Price differentiation stems from efficiency ratings, long-term service agreements, and customization levels for specific applications. Pricing softness reflects the increasing competition from alternative clean power technologies, making commercial enterprises highly price-sensitive compared to utilities focused on grid stability.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by risk-averse data center and utility operators. The supply chain for PAFCs concentrates heavily in Japan and South Korea, drawing from global sources for platinum catalysts and specialized carbon support materials. Single-source vulnerability for key catalyst precursors represents a structural risk. Distribution runs through specialized system integrators and direct sales channels to large commercial and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Phosphoric Acid Fuel Cell market functions as a stable compounder, with policy tailwinds like the US Inflation Reduction Act driving consistent, long-term investments in clean stationary power. Demand from critical infrastructure reinforces this trajectory.
For Market Incumbents:Deepen vertical integration into advanced electrode material manufacturing to mitigate the threat of rising platinum group metal costs. Invest in R&D for more durable carbon support structures, extending operational lifetimes beyond 20 years to satisfy risk-averse utilities. Expand service networks in North America and Europe, countering competitive pressure from alternative fuel cell technologies through demonstrated long-term reliability.
For New Entrants and Emerging Players:Energy-as-a-service providers offer a direct channel to penetrate the North American data center sector, which demands comprehensive energy resilience solutions. Focus on modular, easily integrated CHP systems for commercial buildings in Germany, leveraging EU Green Deal incentives. Develop robust system integration expertise to simplify deployment, targeting underpenetrated telecommunication infrastructure applications with low-emission solutions.
For Investors and Strategic Acquirers:Roll-up economics work for specialized system integrators because complex installation and long-term maintenance create localized expertise moats. Target mid-sized technology firms with strong intellectual property in advanced materials or system controls for long-term viability over a five-to-ten-year window. A signal to watch is the sustained increase in government-backed clean energy project funding in South Korea and the US.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production facilities in South Korea meets growing demand for distributed power. |
| Technology Licensing | Licensing advanced electrode designs enhances catalyst durability and system efficiency. |
| Long-term Service Agreements | Securing multi-year maintenance contracts builds customer loyalty and predictable revenue streams. |
| Vertical Integration into Materials | Controlling key material supply chains reduces cost volatility for core components. |
| Strategic Partnerships | Collaborating with energy-as-a-service providers expands market access in commercial sectors. |
Research Approach
Multiple input streams — primary interviews, secondary industry reports, and regulatory filings — were reconciled to construct the market analysis. Discussions with utility planning officers, data center procurement managers, and fuel cell R&D directors provided qualitative insights. Secondary data from EIA reports, corporate 10-K filings, and IEC standards ensured quantitative validation. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
Historical market performance was cross-referenced with expert panel input to project future growth across the modeling period. The analytical framework segmented the market by product type, technology, application, end-user, and regional policy environment. Compound annual growth rates were derived from a multi-variant regression analysis considering factors like renewable energy integration and hydrogen infrastructure development.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to policy shifts and material cost volatility. The projections reflect current market conditions and anticipated technological advancements. Deviation in major government incentive programs or platinum supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Bipolar Plate Coatings Market