
 Distributed Solar Energy Market | 2026-2036
Distributed Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Solar Energy Market Insights
A shift from single-source EPC contracts toward multi-source procurement is recalibrating how developers assemble project teams. Sunrun leverages its direct-to-consumer installation network to control customer acquisition costs across residential markets. Tesla anchors its position through in-house production of Powerwall storage paired with Solar Roof tiles. First Solar competes on thin-film cadmium telluride efficiency at utility-scale deployments.
Distributed solar energy refers to decentralized photovoltaic generation systems typically sited at or near the point of consumption, with capacities ranging from kilowatt-scale residential arrays to multi-megawatt commercial installations using monocrystalline or polycrystalline silicon cells with conversion efficiencies of 19-22%. These systems reduce transmission losses and enable behind-the-meter energy management for commercial and industrial facilities. Photovoltaic technology dominates installed capacity due to modularity and declining module costs, while building integrated photovoltaics represents the fastest-growing segment as architects embed solar generation into facades and roofing materials. Rooftop installations occupy the largest share of deployment volume, though floating solar is gaining traction where land constraints limit ground-mounted development.
The US Inflation Reduction Act directs the Treasury and IRS to administer production and investment tax credits that determine project finance structures. EPA renewable energy standards and state-level net metering policies shape interconnection rules and compensation frameworks for excess generation. California's Title 24 building code mandates solar readiness in new construction, tightening product compliance requirements. Stakeholders must monitor evolving interconnection queue reforms and storage pairing incentives as grid operators revise distributed resource integration standards.
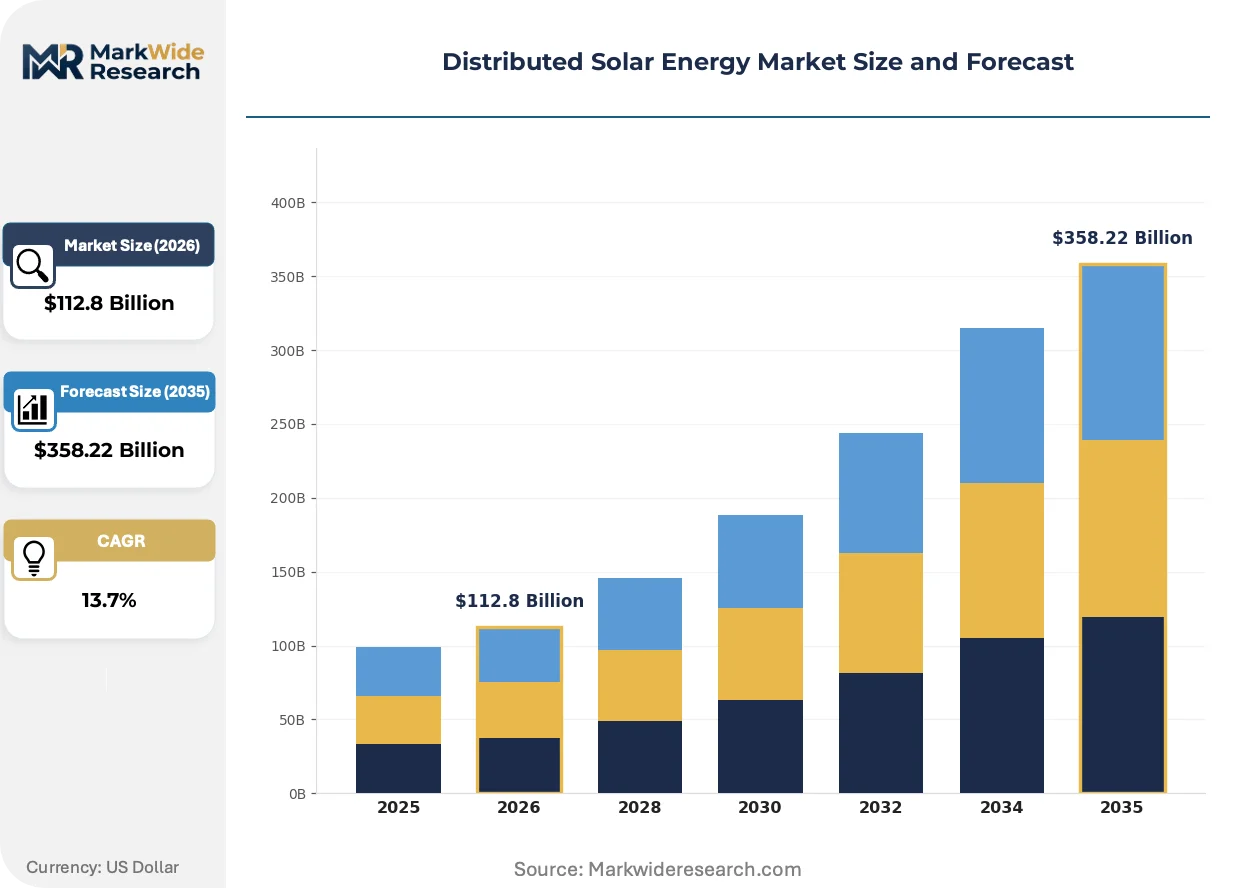
Market Dynamics
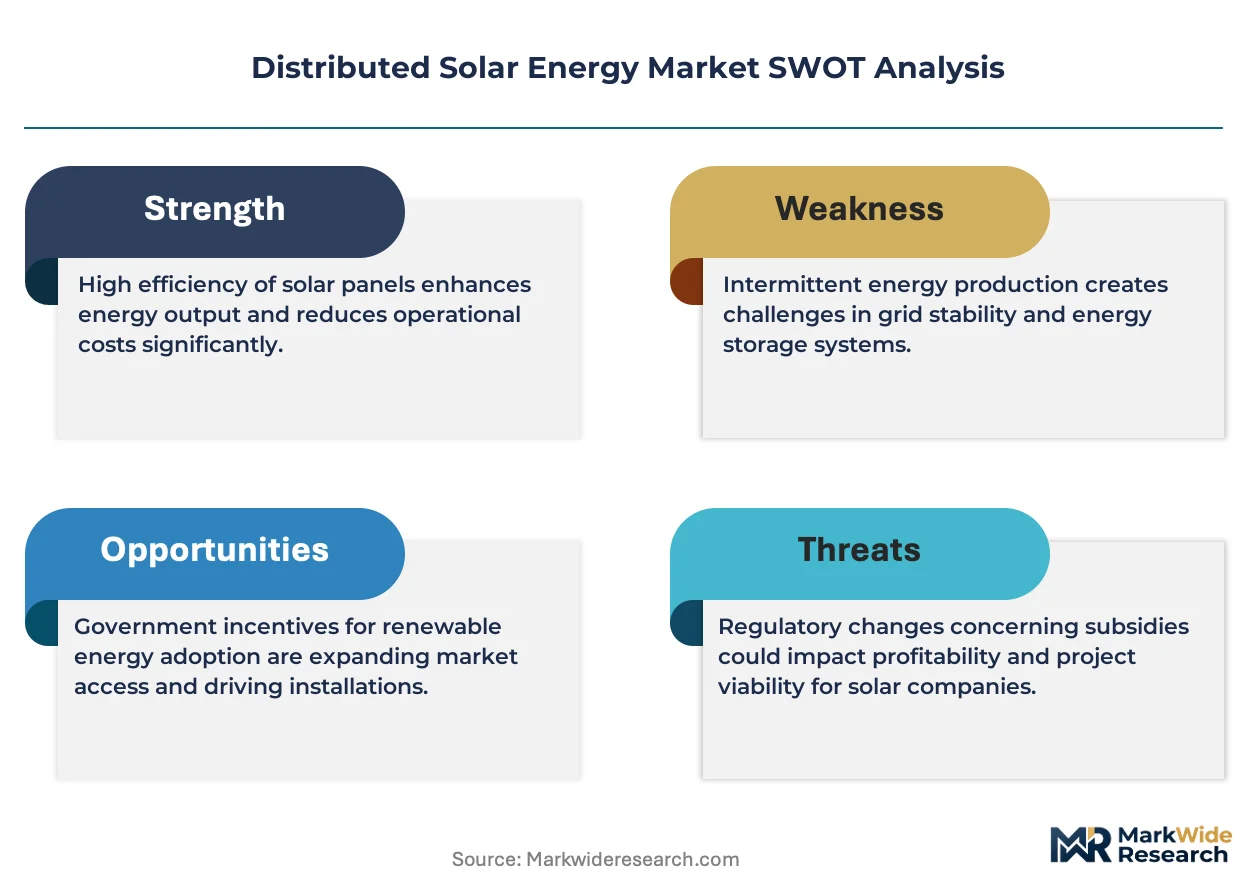
The US Inflation Reduction Act's investment tax credit extension has fundamentally restructured project finance economics, compressing payback periods and redirecting developer capital toward behind-the-meter commercial installations.
Growth Catalysts
- California Title 24 Mandate:New construction solar readiness requirements create guaranteed demand pull for building-integrated photovoltaic systems across the state's commercial corridor.
- Thin-Film Efficiency Gains:Cadmium telluride module performance improvements are expanding viable deployment surfaces beyond traditional rooftop geometries.
- Net Metering Frameworks:State-level compensation structures for excess generation sustain distributed solar economics in jurisdictions with favorable interconnection rules.
Market Restraints
- Polysilicon Supply Concentration:Upstream refining capacity clustering in specific manufacturing geographies creates input cost volatility exposure for crystalline silicon module assemblers.
- Interconnection Queue Friction:Grid operator backlog delays for distributed resource integration extend project commissioning timelines and erode developer returns.
- Storage Pairing Cost Burden:Lithium-ion battery system requirements for time-shifting generation add capital intensity that compresses project IRRs in rate-sensitive segments.
Strategic Opportunities
- Floating Solar Deployment:Water-surface photovoltaic arrays unlock generation capacity in land-constrained markets where reservoir and canal infrastructure permits dual-use development.
- Powerwall-Style Residential Storage:In-house battery production paired with rooftop systems creates bundled offering differentiation in the direct-to-consumer channel.
- Commercial Building Integrated Photovoltaics:Architectural facade embedding generates premium pricing capture in new construction and deep retrofit verticals.
Industry Challenges
- Electrical Grid Integration Expertise:Scarce talent pools for distributed energy resource management system configuration constrain project execution velocity.
- Module Certification Timelines:UL and IEC testing protocols for building-integrated products extend product launch cycles beyond standard rooftop equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Solar Energy Market |
| Market Size in 2026 | $112.8 Billion |
| Market Size in 2035 | $358.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Modules, Building Integrated Photovoltaics Application: Residential, Commercial, Industrial, Off-Grid End User: Homeowners, Businesses, Government Facilities, Utilities Installation Type: Rooftop, Ground-Mounted, Carports, Floating |
| Companies Covered | Sunrun, Tesla, Nexamp, First Solar, Canadian Solar, Trina Solar, JinkoSolar, SunPower, Enphase Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Solar Energy Market Trends and Innovations
Module-level power electronics and software-defined energy management are compressing the traditional boundaries between generation hardware and grid services, enabling new revenue stacking models for asset owners.
Module-level power electronics—microinverters and DC optimizers—are decentralizing inverter function to individual panel outputs, eliminating string-level mismatch losses. Commercial developers with complex roof geometries or partial shading conditions are specifying these architectures despite per-watt premiums. This granularity is decentralizing operations and maintenance accountability from central inverter vendors to module-level suppliers.
The US Inflation Reduction Act's domestic content bonus credits are restructuring supply chain geography requirements for tax equity eligibility. Treasury guidance on manufacturing location thresholds is forcing developers to requalify module and inverter sourcing. Utility-scale and commercial segments are responding with accelerated supplier qualification processes for thin-film and crystalline silicon producers with North American assembly.
Commercial energy managers are unbundling engineering-procurement-construction contracts into discrete component and service procurements. Direct module purchasing, separate installation contracting, and independent commissioning are displacing single-source EPC arrangements in the 500kW–5MW commercial segment. California and Texas building operators are most visible in this pattern, driven by internal sustainability teams with technical evaluation capacity.
Distributed Solar Energy Market Segmentation
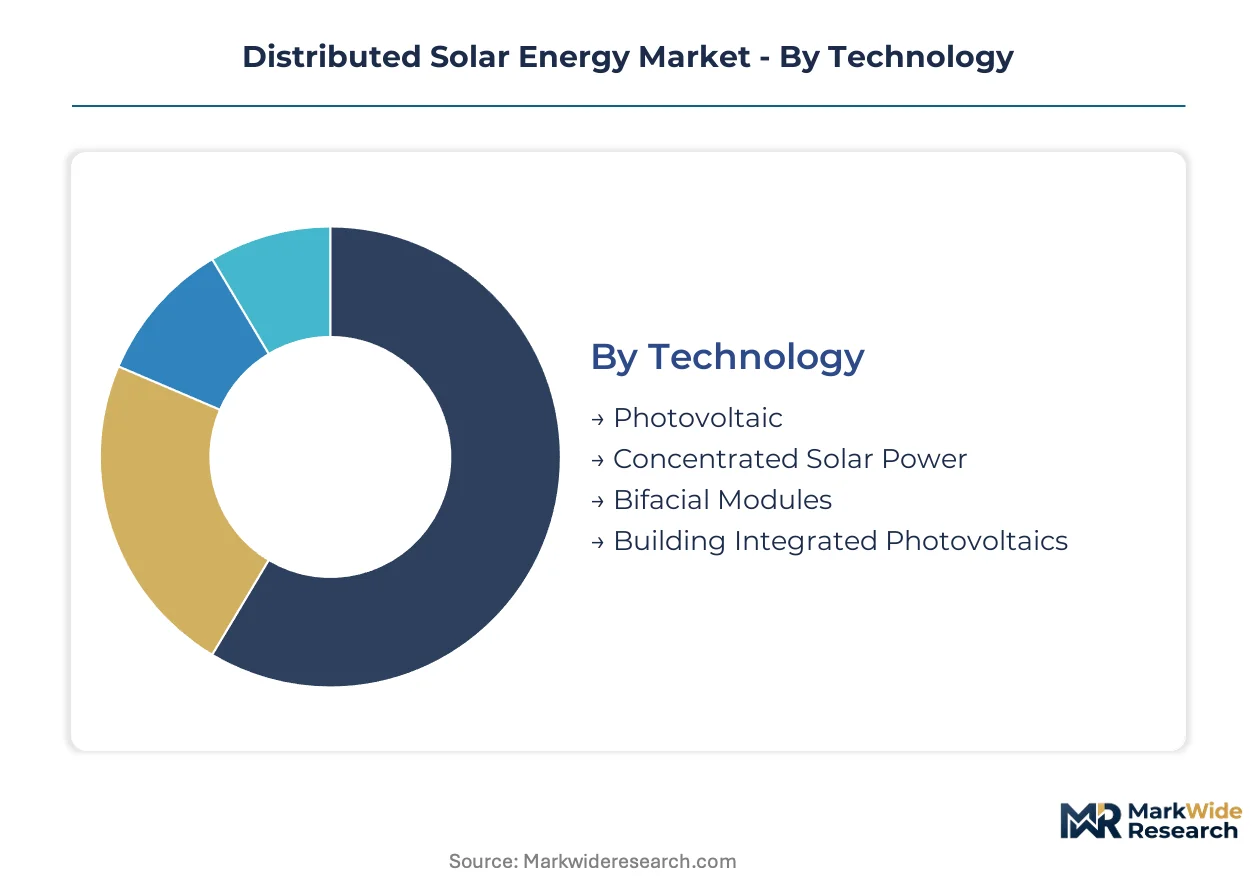
Segmentation in distributed solar reveals how certification burdens, installation constraints, and end-use economics fragment procurement strategies across technology and application types. Developers must match module specifications to interconnection standards and building codes that vary by deployment context.
Technology:
UL 61730 and IEC 61215 certifications govern crystalline silicon modules, while building-integrated photovoltaics face additional ASTM E119 fire-resistance testing and local jurisdictional approval cycles.
- Photovoltaic:Crystalline silicon cells with conversion efficiencies of 19-22% dominate installed capacity due to modularity and declining module costs. Demand concentrates in California's commercial and industrial corridor, where the Title 24 building code mandates solar readiness in new construction.
- Building Integrated Photovoltaics:Architectural embedding of solar generation into facades and roofing materials requires dual certification for structural and electrical performance. Commercial developers in land-constrained urban markets specify these systems despite 15-25% per-watt premiums over standard modules.
- Bifacial Modules:Dual-sided energy capture from reflected light boosts yield in high-albedo environments.
- Concentrated Solar Power:Thermal generation using mirrors and tracking systems finds niche deployment in utility-scale desert installations.
Photovoltaic sits at the top of the volume ranking, with Building Integrated Photovoltaics climbing the fastest.
Application:
Customer acquisition economics and interconnection queue complexity create distinct margin profiles across deployment scales.
- Commercial:Behind-the-meter installations for office buildings, warehouses, and retail facilities leverage net metering frameworks and investment tax credits. Project finance structures in this segment compress payback periods through accelerated depreciation schedules.
- Residential:Kilowatt-scale rooftop arrays serve single-family homes with direct-to-consumer sales models. Sunrun and Tesla compete on customer acquisition cost control through bundled storage offerings in California and Texas markets.
- Industrial:Multi-megawatt on-site generation for manufacturing facilities requires complex load-matching engineering.
- Off-Grid:Standalone systems for remote locations operate without utility interconnection.
Commercial commands the largest revenue pool, while Residential shows the steepest expansion trajectory as financing accessibility improves.
End User:
Procurement authority and sustainability mandate intensity shape contract structures and technology specifications.
- Businesses:Corporate renewable energy targets and ESG reporting requirements drive commercial and industrial procurement. Internal sustainability teams in California and Texas building operators increasingly unbundle EPC contracts into discrete component purchases.
- Homeowners:Individual purchase decisions respond to net metering compensation rates and local installer availability. Direct-to-consumer channels reduce soft costs compared to third-party ownership models.
- Government Facilities:Federal and state buildings access specialized procurement vehicles and resilience mandates.
- Utilities:Distribution network operators deploy community solar and grid-edge resources for peak shaving.
Businesses anchor current deployment volume, with Government Facilities expanding most quickly through federal building decarbonization targets.
Installation Type:
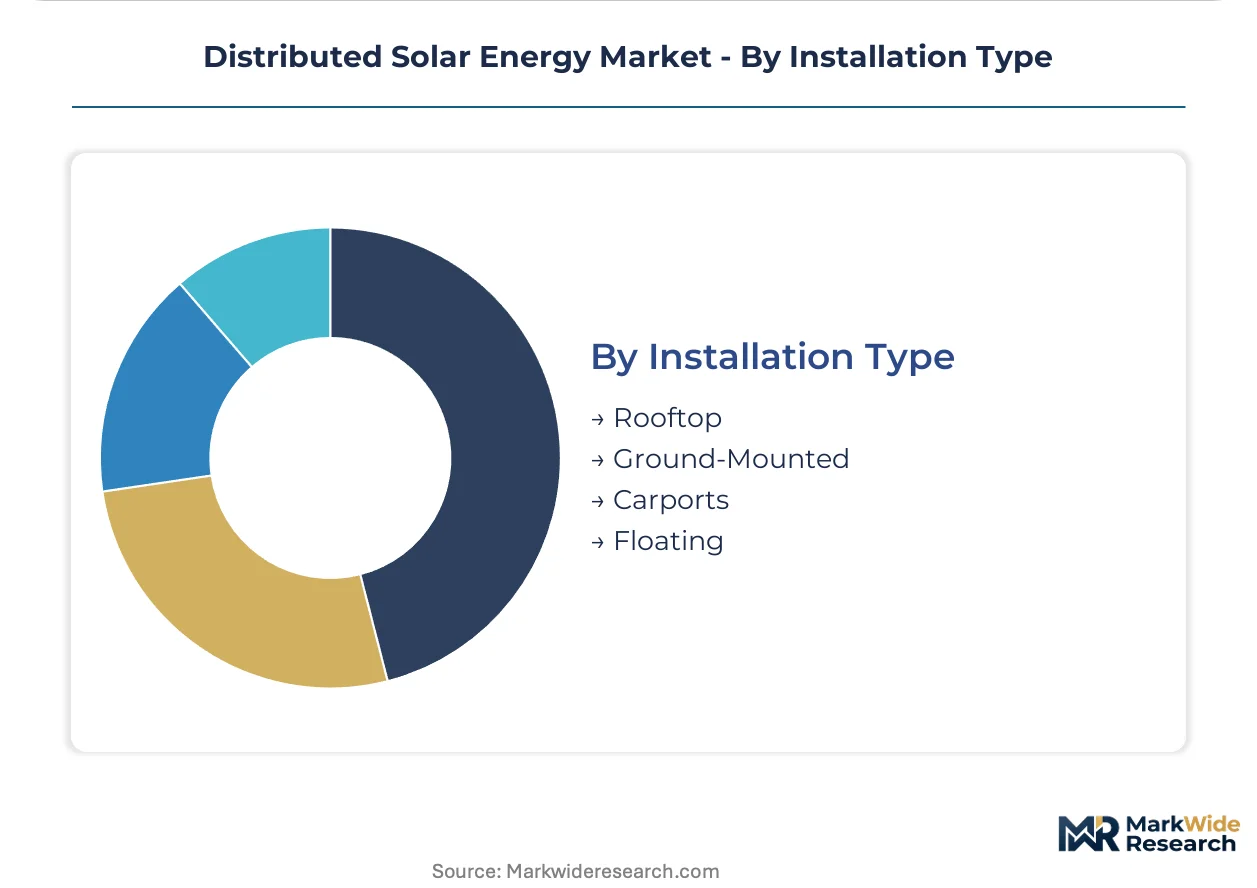
Site constraints and dual-use revenue potential determine structural engineering requirements and permitting pathways.
- Rooftop:Building-attached arrays on commercial and residential structures constitute the largest deployment volume. Module-level power electronics address complex geometries and partial shading conditions despite per-watt premiums.
- Floating:Water-surface photovoltaic arrays on reservoirs and canals unlock generation capacity where land constraints limit ground-mounted development. Japan and South Korea lead deployment through agricultural reservoir dual-use policies.
- Ground-Mounted:Terrestrial fixed-tilt and tracking systems dominate utility-scale and large commercial installations.
- Carports:Parking canopy structures combine shade provision with energy generation for commercial properties.
Rooftop maintains volume leadership, with Floating gaining share fastest as land-scarce markets adopt dual-use frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting module assembly toward jurisdictions with favorable domestic content bonus structures under the US Inflation Reduction Act, compressing payback periods for developers who requalify supply chains.
United States
California's Title 24 building code mandates solar readiness in new commercial construction, while Texas building operators unbundle EPC contracts into discrete component purchases. The Treasury and IRS administer investment tax credit extensions that determine project finance structures. Demand concentrates in California's commercial and industrial corridor where sustainability teams drive procurement decisions.
China
Polysilicon refining capacity clustering creates input cost volatility exposure for crystalline silicon module assemblers serving export markets. The country's national energy regulator oversees dual carbon goals that shape manufacturing location decisions. Yangtze River Delta production bases supply thin-film and crystalline silicon modules to North American developers seeking domestic content bonus eligibility.
Germany
Commercial energy managers specify building-integrated photovoltaic systems despite per-watt premiums over standard modules. The EU Green Deal and national building codes tighten product compliance requirements for facade-embedded generation. Industrial clusters in Bavaria and North Rhine-Westphalia anchor engineering-procurement-construction unbundling trends among large commercial building operators.
Japan
Agricultural reservoir dual-use policies accelerate floating solar deployment where land constraints limit ground-mounted development. METI administers feed-in tariff transitions that reshape compensation frameworks for excess generation. Kyushu and Kansai regions lead water-surface photovoltaic array installations through favorable interconnection rules.
Australia
Behind-the-meter commercial installations leverage accelerated depreciation schedules and state-level net metering frameworks. The national renewable energy regulator revises distributed resource integration standards that affect storage pairing incentives. New South Wales and Victoria building operators drive residential rooftop demand through direct-to-consumer channels.
Distributed Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue building-integrated and floating solar specializations. The market structures around three player tiers: integrated manufacturers with captive cell production, pure-play installers controlling customer acquisition costs, and technology specialists in module-level power electronics. Consolidation pressures favor scale-driven module producers while fragmentation persists in installation and software layers. Dominant competitive moves include backward integration into polysilicon refining and geographic expansion through direct-to-consumer channel buildouts.
Among US-based installers, Sunrun and Tesla exemplify divergent archetypes within the residential segment. Sunrun leverages its direct-to-consumer installation network to control customer acquisition costs across state markets. Tesla anchors its position through in-house production of storage systems paired with rooftop generation products. First Solar represents the thin-film manufacturing archetype, competing on cadmium telluride efficiency at utility-scale and commercial deployments. These three occupy positions that illustrate how vertical scope and technology specialization segment competitive space.
| Leading Market Players |
|---|
| Sunrun |
| Tesla |
| Nexamp |
| First Solar |
| Canadian Solar |
| Trina Solar |
| JinkoSolar |
| SunPower |
| Enphase Energy |
| Others |
Pricing and Supply Chain Analysis
California's Title 24 building code gates qualified supply and premium-tier pricing access by mandating solar readiness in new commercial construction, forcing developers toward certified building-integrated photovoltaic suppliers who command 15-25% per-watt premiums over standard module vendors.
Pricing Analysis
Input-cost pass-through from polysilicon refining volatility shapes crystalline silicon module pricing, with contract-based long-term offtake structures dominating utility-scale procurement while spot-indexed transactions prevail in distributed commercial segments. Price differentiation rests on UL 61730 certification tier and domestic content bonus eligibility under IRA Treasury guidance, with California and Texas building operators showing highest price sensitivity in rate-sensitive segments while premium facade-embedded systems find least elastic demand among architect-specified new construction.
Supply Chain Analysis
Certification and qualification gating through UL, IEC, and ASTM E119 protocols constrains supplier pools for building-integrated products, extending product launch cycles beyond standard rooftop equipment. Module assembly concentrates in China, Vietnam, and Malaysia as developers requalify sourcing for domestic content bonus eligibility, with polysilicon refining, silver metallization paste, and aluminum framing anchoring raw material dependencies. Single-source vulnerability in lithium-ion battery cell supply creates storage pairing cost volatility, while distribution runs through direct-to-consumer installer networks and unbundled EPC component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed solar functions as a geographic-arbitrage play where developers capture spreads between IRA domestic content bonus jurisdictions and lower-cost Asian module assembly, exploiting regulatory cost differentials between Treasury-qualified supply chains and standard import channels.
For Market Incumbents: Deploy backward integration into polysilicon refining to defend margins against input cost volatility from concentrated upstream capacity. Incumbents should consolidate module-level power electronics partnerships to counter emerging microinverter specialists, while accelerating North American assembly qualification to preserve tax equity access under evolving Treasury guidance on manufacturing location thresholds. For New Entrants and Emerging Players: The US Inflation Reduction Act's domestic content bonus credits in the United States open a window for thin-film cadmium telluride specialists to capture utility-scale share from crystalline silicon incumbents. New entrants should target floating solar deployment in Japan and South Korea's agricultural reservoir markets, entering through dual-use policy frameworks and water-surface engineering partnerships. For Investors and Strategic Acquirers: Roll-up economics work for regional installer networks because customer acquisition cost scale and direct-to-consumer channel density create local market moats. Investors should target commercial EPC unbundling specialists in California and Texas, monitoring interconnection queue reform timelines as the inflection signal for distributed resource integration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Supply Requalification | Treasury guidance on manufacturing thresholds redirects module sourcing toward North American assembly. |
| Building-Integrated Photovoltaic Certification | ASTM E119 fire-resistance testing creates product differentiation in California Title 24-mandated new construction. |
| Module-Level Power Electronics Integration | Microinverter and DC optimizer architectures capture complex roof geometry segments despite per-watt premiums. |
| Floating Solar Development Partnerships | Reservoir dual-use policies in Japan and South Korea unlock land-constrained generation capacity. |
| Direct-to-Consumer Channel Expansion | Installer network density in California and Texas compresses customer acquisition costs versus third-party ownership models. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative findings, cross-referenced against EIA generation data, IEA renewable energy reports, FERC interconnection filings, and project development databases. Secondary validation drew from SEC 10-K disclosures of listed module manufacturers and state-level net metering policy trackers. Bottom-up capacity and deployment estimates triangulated with top-down regulatory incentive valuation across the analysis window.
Bottom-up modeling of installed capacity by technology, application, and installation type converged with top-down investment tax credit flow analysis over the projection horizon. Segmentation dimensions included photovoltaic versus building-integrated technology, commercial versus residential application scale, and rooftop versus floating installation geometry. CAGRs derived from regression of historical deployment against incentive phase-down schedules and interconnection queue throughput rates, with IRA domestic content bonus eligibility curves and storage pairing incentive structures as key forecast inputs.
Revisions become necessary when Treasury guidance on manufacturing location thresholds shifts, interconnection queue reforms accelerate or stall, or polysilicon supply concentration triggers input cost spikes beyond historical volatility bands. Forecasts reflect documented assumptions on tax credit extension continuity and state-level net metering policy stability. A model refresh is warranted upon material change in FERC distributed resource integration standards or California Title 24 building code amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
United Kingdom Solar Power Market